
Blogs
Reinsurance Market 2026: 8.2% CAGR Trajectory and the Real Shifts Reshaping Industry Growth
By pmarketresearch, 2026-09-21
Reinsurance Market: Strategic Shifts and Commercial Opportunities in a Transforming Landscape
The global reinsurance market has entered a phase of structural expansion, driven by a combination of hardening premiums, evolving risk profiles, and accelerating digital transformation. Following a consistent upward trajectory over the past half-decade, the market surpassed the 200-billion mark in 2024 and reached 215 billion in 2025 at the base year level. Forward projections indicate sustained momentum, with the sector expected to grow at a compound annual rate of 8.2 percent through 2032, culminating in a market size approaching 345 billion. This growth is not merely a reflection of cyclical pricing but signals deeper shifts in how risk is transferred, managed, and financed across jurisdictions and asset classes. For executives and capital allocators, the numbers suggest a market that is both scaling and fragmenting in capability, creating pockets of premium returns alongside operational complexity.
Beneath the headline figures lies a market structure that remains moderately concentrated, with the top three players accounting for roughly 29 percent of total revenue and the top five holding just over 30 percent. This distribution indicates that while scale advantages persist, the market is not dominated by a handful of incumbents to the point of stifling innovation or new capacity entry. The relatively flat concentration curve between the third and fifth positions suggests competitive intensity among mid-tier and specialized carriers, particularly in non-life and life lines where pricing, underwriting discipline, and technological stack maturity diverge. The room between the leader cluster and the long tail of participants creates strategic space for platforms, service providers, and niche reinsurers that can differentiate on speed, data integration, or regulatory navigation.
Market Dynamics and Structural Challenges
Pricing Normalization Meets Risk Complexity
The post-2020 expansion reflects a market that has moved through several pricing cycles while absorbing growing exposure to climate-related losses, cyber accumulation, and demographic-driven longevity shifts. Rather than a single shock driving growth, the current phase is characterized by broad-based premium firming, improved loss recognition, and a recalibration of capital allocation toward lines with clearer risk-return profiles. This environment rewards reinsurers and brokers that can price risk with granularity and document assumptions transparently. At the same time, it raises the bar for underwriting rigor and actuarial validation, particularly where reinsured portfolios interact with complex asset structures or long-dated liabilities.
Regulatory Tightening as a Competitive Filter
A second defining challenge is the shifting regulatory architecture, which is reshaping how cedants and reinsurers prove solvency, adequacy, and collateral efficiency. In the United States, Actuarial Guideline 55, approved by the NAIC and effective from the end of 2025, requires cedants to incorporate reinsured business alongside net retained business in asset adequacy testing for statutory reserves. In Europe and comparable markets, solvency frameworks continue to mandate stringent capital equivalence, including 100 percent solvency capital requirement coverage and own-funds thresholds that support collateral-free transactions. These rules elevate the cost of compliance but also create differentiation opportunities for carriers and platforms that can operationalize asset adequacy documentation, investment accelerators, and principles-based bond definitions with minimal friction. The net effect is a market where regulatory fluency is becoming a commercial capability rather than a back-office necessity.
Talent, Automation, and the Cost of Expertise
A third pressure point is the intensifying demand for specialized actuarial and claims expertise. Updated guidelines such as AG 55, combined with tighter supervisory expectations for third-party cloud and AI deployments, increase the operational labor required to complete filings and maintain audit-ready documentation. Teams must interpret evolving asset adequacy standards, align investment matching adjustments, and demonstrate governance over automated reinsurance workflows. Where platforms and processes remain manual or fragmented, labor costs and cycle times expand, eroding margin and slowing decision velocity. Conversely, organizations that embed automation, standardized reporting, and embedded compliance into their reinsurance operations can convert this pressure into a durability advantage.
Key Growth Drivers
Digital Platforms and Automation of the Reinsurance Lifecycle
Technology is moving from experimentation to core infrastructure. Cloud-native reinsurance administration platforms are increasingly automating cessions, recoverables, commission calculations, and claims recovery across both traditional and non-proportional structures. Modular architectures allow insurers and brokers to integrate reinsurance operations with existing policy and finance systems without rip-and-replace disruptions. The emphasis is shifting from point solutions to end-to-end lifecycle coverage that spans contract initiation, ongoing administration, and retrocession management. As these platforms mature, they reduce reconciliation errors, accelerate settlements, and provide data lineage that supports regulatory exams and actuarial review. The recent wave of platform updates and launches underscores this direction, with new releases targeting automated cessions and recoverable tracking for property and casualty insurers and brokers, and sovereign-backed initiatives launching global reinsurance platforms anchored in financial free zones with institutional partners to facilitate cross-border operations.
Regulatory Modernization Enabling More Flexible Asset Deployment
Complementary regulatory changes are expanding the toolkit for matching long-tail liabilities with suitable assets. Principles-based bond definitions and investment accelerator mechanisms introduced in late 2025 are designed to facilitate more flexible asset deployment for matching adjustments within reinsurance portfolios. Alongside solvency frameworks that support collateral-free transactions when capital and own-funds thresholds are met, these developments allow market participants to optimize asset-liability alignment while preserving liquidity and governance standards. The practical implication is that reinsurers and cedants can structure transactions with greater latitude in asset selection and duration matching, provided they can evidence adequacy and maintain robust oversight. This flexibility is particularly valuable for life and annuity lines, where asset duration and crediting strategies interact directly with reinsured liabilities.
Demand-Side Shifts Toward Resilience and Capital Efficiency
On the demand side, primary insurers and corporate buyers are increasingly treating reinsurance as a strategic lever for balance-sheet resilience rather than a pure cost of risk transfer. Harder markets and elevated catastrophe volatility have reinforced the value of capacity certainty, tailored coverage, and transparent terms. At the same time, capital market participants and institutional allocators are exploring avenues to support reinsurance operations, especially in jurisdictions that offer regulatory clarity and operational efficiency. This convergence expands the ecosystem around reinsurance, creating demand for platforms and services that can coordinate ceded and assumed contracts, streamline reporting, and support multi-jurisdiction compliance. Brokers and intermediaries benefit as well, since structured automation reduces processing overhead and improves turnaround for complex placements.
Operational Cost Structures and the Value of Integrated Workflows
Cost structures are being reshaped by the interplay of technology adoption, labor scarcity, and supervisory expectations. As AI-assisted models gain traction in underwriting support, reserving, and claims triage, regulators are increasing governance, risk management, and third-party audit requirements for cloud providers and model operators. Organizations that standardize data, document model usage, and maintain audit trails can harness automation without compromising supervisory confidence. Where workflows remain siloed, the cumulative cost of manual reconciliation, rework, and compliance documentation compresses operating leverage. The emerging competitive logic is clear: integration of policy, finance, actuarial, and reinsurance administration into coherent workflows is becoming a determinant of margin and speed, especially as filing deadlines tighten and documentation expectations rise.
Competitive Landscape and Leading Strategies
The competitive field blends global reinsurers with technology and service providers, each pursuing distinct positions along the value chain. Incumbent carriers continue to anchor the market with broad risk appetite, diversified portfolios, and established distribution relationships. Their strategic emphasis typically centers on disciplined underwriting, integrated digital client tools, and robust risk-transfer and administration capabilities across life, non-life, and specialty lines. Many have built or acquired proprietary platforms and client portals to reduce friction in the placement and servicing of reinsurance contracts, reinforcing the perception of reliability and continuity that matters in long-tail and capital-intensive transactions.
Technology and software providers are carving a parallel track focused on the operational backbone of reinsurance. SaaS reinsurance administration platforms deliver modular automation for contract initiation, claims recovery, retrocession, and full lifecycle management for both traditional and non-proportional treaties. Other providers offer cloud or on-premise insurance suites that cover premiums, loss reserves, commission calculation, claims processing, and regulatory reporting for ceded and assumed contracts. These platforms increasingly target the pain points identified earlier—manual reconciliation, fragmented reporting, and audit readiness—while enabling interoperability with core policy and financial systems. The value proposition is not solely cost reduction; it is the creation of data continuity that supports solvency and asset adequacy documentation, accelerates settlements, and gives executives a clearer view of ceded exposures and recoverables.
The market is evolving through a combination of consolidation, specialization, and new entry. Scale incumbents compete on breadth and capital strength, while specialists compete on depth in particular lines or geographies. Newer entrants and platform operators compete on speed, configurability, and the ability to plug into existing ecosystems with limited disruption. Strategic differentiation is increasingly defined by three factors: the completeness of the reinsurance administration lifecycle covered, the strength of regulatory and actuarial documentation support, and the ability to operate across jurisdictions with consistent governance. As a result, partnerships between carriers, platforms, and institutional players are becoming more common, especially where an anchor in a well-regulated financial hub can streamline cross-border capacity and operations.
PW Consulting
For decision-makers evaluating partners and vendors, the practical question is not whether a provider offers a feature list, but whether its architecture reduces the cost of compliance, improves data lineage, and supports the lines and structures that matter to the organization. Providers that combine lifecycle automation with actuarial and claims support, or that can evidence alignment with asset adequacy and solvency expectations, are better positioned to capture share in a market where documentation and control are increasingly part of the commercial conversation.
Forward Outlook: Trends and Opportunities
Automation Becomes the Baseline, Not the Differentiator
Over the next three to five years, cloud-native reinsurance administration and integrated automation will move from competitive advantage to operational baseline. Organizations that standardize cessions, recoverables, commission flows, and claims recovery within connected workflows will reduce cycle times and improve the reliability of reporting used in both internal decision-making and external reviews. The commercial opportunity lies in extending these workflows to cover specialty and non-proportional structures, retrocession, and multi-currency settlements, where manual processing has historically introduced the most friction and error. Companies that achieve this baseline earlier will free managerial attention for pricing strategy, asset-liability optimization, and client service rather than administrative remediation.
Regulatory Fluency as a Commercial Capability
Regulatory and actuarial guideline evolution will continue to influence transaction structuring and platform design. Asset adequacy documentation, investment matching adjustments, and principles-based classification will require systems that can trace assumptions, evidence testing, and maintain auditability across ceded and retained portfolios. Firms that build or adopt tooling to operationalize these requirements will gain speed and credibility in filings, while those that rely on manual processes will face rising labor costs and execution risk around deadlines. The upside is not only compliance efficiency but also the ability to structure transactions with greater flexibility in asset deployment and collateral arrangements where supervisory frameworks permit, particularly in life and asset-intensive portfolios.
Market Structure Continues to Fragment in Capability, Consolidate in Ecosystems
While revenue concentration remains moderate, capability concentration will likely increase among providers that can span administration, analytics, and regulatory support within a coherent stack. Expect continued partnership activity between incumbents, platform operators, and institutional participants, especially where a regulated hub and aligned governance can reduce cross-border friction. At the same time, specialization will persist in lines with distinct underwriting, reserving, or asset dynamics, creating room for focused carriers and boutique platforms. The strategic implication is that the most resilient participants will be those that can combine clear risk appetite with interoperable technology, disciplined documentation, and the ability to scale operations without proportional increases in manual effort.
Risks and Uncertainties to Monitor
The outlook is constructive, but not without caveats. Catastrophe volatility and the accumulation of secondary perils can re-rate pricing and capacity quickly, pressuring returns and testing reserving discipline. Regulatory interpretation can shift as supervisors deepen scrutiny of AI-assisted models and third-party cloud dependencies, potentially increasing governance costs or constraining certain automation paths until standards settle. Talent constraints in actuarial and specialized claims roles may continue to elevate operational expenses where workflows are not sufficiently automated or standardized. Finally, macro and capital market dynamics can affect asset deployment strategies and the attractiveness of collateral-free structures, influencing transaction economics in life and non-life lines alike. Participants should therefore pair growth ambitions with scenario planning, data quality, and flexible operating models.
Strategic Implications for Decision-Makers
For Executives and Strategy Teams
Prioritize integration over point fixes. Decision velocity and margin protection increasingly depend on connected workflows that span policy, finance, actuarial, and reinsurance administration. Establish clear ownership of data lineage and documentation so that asset adequacy testing, solvency reporting, and recoverable tracking can be produced consistently and on time. Evaluate partners and platforms against their ability to cover the full lifecycle, support the lines and structures most relevant to the portfolio, and demonstrate governance aligned with supervisory expectations. Where feasible, sequence adoption to first reduce the highest-friction manual processes, then extend automation to specialty and non-proportional structures and multi-currency operations.
Worldwide Real Estate Insurance Market
For Investors and Capital Allocators
Assess exposure and resilience across the value chain rather than relying on headline market size alone. Differentiate between carriers with diversified, disciplined underwriting and those more exposed to concentrated catastrophe or cyber accumulation. In technology and service providers, focus on evidence of workflow completeness, customer retention, and the ability to reduce compliance and reconciliation costs, since these qualities translate into durable operating leverage as regulatory and documentation demands rise. Consider jurisdictional and partnership dynamics that can lower cross-border friction, while monitoring the regulatory trajectory for AI and cloud governance, which may affect cost structures and deployment options in the medium term.
For Procurement and Vendor Selection Teams
FrameRFP criteria around outcomes rather than feature counts. Define requirements for automated cessions, recoverable tracking, commission handling, claims support, and audit-ready reporting, and verify how each candidate maps to existing policy and financial systems. Require demonstrations of data lineage, documentation support for asset adequacy and solvency contexts, and clear migration or interoperability plans to avoid rip-and-replace risk. Weight vendor stability, roadmap coherence, and support for multi-jurisdiction operations where relevant, and build pilot metrics around cycle-time reduction, error reduction, and documentation completeness so that adoption decisions are anchored in measurable operational improvement.
The reinsurance market is scaling within a framework of rising expectations for speed, transparency, and regulatory discipline. Those that treat technology, data, and compliance fluency as core commercial capabilities will be better positioned to absorb complexity, protect margin, and access capacity where it is most valuable. For readers seeking a deeper segmentation of regional and line-level dynamics, detailed revenue paths across the forecast horizon, and tailored recommendations calibrated to specific portfolio structures, the full research report provides the granular data and scenario analysis needed to convert these strategic signals into concrete plans.
Insurance Market
For detailed analysis of this topic, please visit the official page: Reinsurance Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Urea Formaldehyde Resin Market: Why the 2% CAGR Trajectory Signals Real Growth Drivers
By pmarketresearch, 2026-09-21
Urea Formaldehyde Resin Market: Navigating the Crossroads of Compliance, Cost, and Innovation
The global urea formaldehyde resin market stands at a strategic inflection point, where established demand patterns intersect with tightening regulatory frameworks and evolving supply chain dynamics. Valued at approximately $11.71 billion in 2020, the market expanded steadily through 2023, reaching $12.47 billion, before experiencing a modest contraction to $12.93 billion in 2025. Looking ahead, the trajectory projects growth to $14.85 billion by 2032, reflecting a compound annual growth rate of roughly 2.0% over the forecast horizon. This measured expansion masks significant underlying volatility, as the market navigates structural shifts in end-use demand, raw material pricing pressures, and regulatory mandates that are fundamentally reshaping product specifications and competitive positioning. For executives and investors operating in downstream manufacturing, chemical distribution, or advanced materials, understanding these dynamics is no longer optional; it is a prerequisite for capital allocation, product roadmap planning, and supplier diversification strategies.
Market Landscape and Structural Headwinds
A Moderating Growth Curve with Regional Asymmetry
The market’s historical progression from $11.79 billion in 2021 to $13.08 billion in 2024 illustrates a period of steady adoption, primarily fueled by construction activity, furniture manufacturing, and panelboard production across key industrial corridors. However, the slight pullback in 2025 to $12.93 billion signals a transitional phase rather than a cyclical downturn. Demand composition remains heavily anchored in traditional adhesive applications, with powder and liquid formulations splitting the revenue base in ways that reflect both application engineering preferences and logistical constraints. Liquid grades continue to dominate environments requiring on-site mixing flexibility or continuous processing lines, while powder variants maintain relevance in settings where shelf stability, transportation efficiency, and controlled inventory management outweigh handling complexity.
PW Consulting Chemical & Energy Research Center
Three Critical Challenges Shaping the Next Cycle
First, regulatory tightening around volatile organic compound emissions has moved from a compliance checkbox to a product architecture constraint. Standards such as CARB Phase-III and EPA TSCA Title VI now require composite wood products to limit formaldehyde emissions to 0.05 ppm, effectively mandating reformulation across legacy adhesive portfolios. The operational implication extends beyond chemistry; it touches manufacturing line validation, certification timelines, and customer acceptance cycles, creating a compliance burden that disproportionately affects mid-tier producers without dedicated R&D or regulatory affairs capacity.
Second, raw material cost volatility has introduced margin compression risks that are difficult to hedge through conventional procurement strategies. Formaldehyde pricing in Europe reached 370 euros per ton in early 2025, marking a historical high, while urea formaldehyde resin prices in the United States climbed to 908 USD per metric ton in September 2025, closely tracking feedstock urea movements. These cost pressures are not isolated to a single region or feedstock; they reflect broader energy, logistics, and agricultural input dynamics that ripple through the value chain and challenge the economics of both conventional and low-emission formulations.
Third, the cost differential between conventional and low-emission resin variants introduces a strategic dilemma for downstream buyers. Industry analysis indicates that meeting EU and global low-emission requirements can add 10–15% to production costs for standard UF resins compared with compliant low-emission grades. This premium is not uniformly absorbed across end markets; cost-sensitive applications face pricing resistance, while premium wood bonding and construction panel segments increasingly treat low-emission compliance as a baseline entry requirement rather than a differentiated feature.
Paraformaldehyde Market
Key Drivers Reshaping the Market Trajectory
Regulatory Architecture as a Catalyst for Product Innovation
Regulatory pressure is no longer a static compliance backdrop; it is actively steering formulation pathways and competitive differentiation. The requirement for a 40% reduction in VOC emissions by 2026 under CARB Phase-III has accelerated reformulation programs across the adhesive and panelboard ecosystem. This regulatory trajectory is pushing producers to invest in low-emission UF grades that meet E0, CARB, and LEF/ULEF standards without sacrificing bond strength, cure speed, or process compatibility. The practical outcome is a market where regulatory conformity becomes a gatekeeper for market access, particularly in North American and European composite wood segments, while simultaneously creating a technical moat for suppliers that can deliver compliant formulations at scale.
Green Chemistry and Low-Emission Formulation as Competitive Levers
The push toward reduced formaldehyde emissions has coincided with broader sustainability mandates across the chemical and manufacturing sectors, creating a convergence of compliance and corporate ESG objectives. Leading producers are responding by developing resin lines that lower formaldehyde output while maintaining performance benchmarks for plywood, particleboard, fibreboard, and impregnation applications. Some offerings now emphasize emission reductions of up to 90% relative to conventional benchmarks, positioning low-emission grades as enablers for downstream manufacturers seeking to satisfy both regulatory standards and customer-facing sustainability claims. This trend is not merely a technical adjustment; it is reshaping procurement criteria, as panel producers and wood product manufacturers increasingly evaluate resin suppliers on emission profiles, certification support, and formulation flexibility alongside price and delivery reliability.
Demand-Side Shifts in Construction, Furniture, and Panel Manufacturing
Downstream demand patterns are evolving in response to housing market dynamics, interior fit-out cycles, and the expansion of engineered wood solutions in both developed and emerging economies. Wood adhesives remain the dominant application driver, reflecting the continued reliance on UF resins in panelboard production and furniture assembly. At the same time, demand for molding compounds, surface coatings, and textile finishing applications introduces segments with distinct performance requirements and growth profiles. The practical implication for resin producers is that volume growth is increasingly tied to application-specific engineering rather than broad commodity displacement. Customers are looking for formulations that balance cure compatibility, moisture resistance, emission compliance, and total cost of ownership, which elevates the importance of technical service, application testing, and co-development arrangements.
Supply Chain Reconfiguration and Cost Structure Dynamics
Feedstock pricing, energy costs, and logistics constraints are collectively reshaping the cost structure of UF resin production. The convergence of elevated formaldehyde prices in Europe and urea-linked resin pricing movements in the United States underscores the vulnerability of input cost pass-through strategies, particularly in markets where downstream price sensitivity limits aggressive adjustments. In response, some producers are exploring formulation optimization, regional sourcing adjustments, and inventory positioning strategies to mitigate exposure. For downstream manufacturers, this environment heightens the importance of supplier diversification, contractual flexibility, and scenario planning around input cost trajectories. It also reinforces the strategic value of long-term supply agreements that incorporate transparency on feedstock indices and formulation change timelines.
Urea Formaldehyde Concentrate (UFC) Market
Competitive Landscape and Strategic Positioning
Fragmented Leadership with Clear Differentiation Paths
The market exhibits a moderate concentration profile, with a handful of large players commanding a significant share of revenue while a broader base of specialty and regional suppliers competes on formulation, service, and application expertise. This structure supports both scale-driven efficiency and differentiation-driven premium positioning, depending on the segment and geography. Leading companies are pursuing distinct strategic paths that reflect their product portfolios, geographic footprints, and sustainability commitments.
Ercros has focused on low-emission UF resin offerings designed to meet stringent formaldehyde standards across plywood, particleboard, fibreboard, and impregnation applications. Its resin range emphasizes compatibility with LEF, ULEF, CARB, and E0 requirements, positioning the company as a solution provider for downstream manufacturers navigating emission compliance without sacrificing processing performance. Prefere Resins has pursued a sustainability-forward strategy, integrating green chemistry principles into its amino resin portfolio for wood adhesives, insulation, and construction panels. The company’s emphasis on CO2-neutral and bio-based resin innovations, reinforced by recent sustainability certifications and reporting, signals a strategic alignment between regulatory compliance and corporate ESG positioning.
Hexion Inc. continues to leverage established methylated UF grades and resin platforms tailored for wood panel adhesives and particleboard production, emphasizing performance consistency and application familiarity in mature markets. BASF SE maintains a broad specialty chemicals footprint, with urea formaldehyde resin grades positioned for wood bonding and adjacent applications, benefiting from integrated supply chain capabilities and cross-market formulation expertise. Dynea Oy and Advachem contribute through specialized resin technology and niche chemical portfolios, respectively, serving panel adhesives and wood product manufacturing with focused application support. Kronospan Limited’s in-house UF resin production for particleboard, MDF, and plywood illustrates a vertical integration model that prioritizes supply control and formulation alignment with internal panel specifications. Metadynea International GmbH complements this landscape with targeted UF resin offerings for wood panel and adhesive applications, reinforcing the diversity of strategic approaches across the competitive field.
Strategic Takeaways from Recent Industry Moves
Recent developments underscore how sustainability credentials and transparency are becoming embedded in competitive positioning. Prefere Resins’ achievement of an EcoVadis Gold rating for ESG performance, alongside the publication of its first Group Sustainability Report covering 2023–2024, reflects a broader trend in which ESG performance is increasingly treated as a procurement consideration rather than a peripheral corporate initiative. The company’s earlier emphasis on Mission Zero 2050 CO2-neutral bio-based resin innovations further illustrates how long-term decarbonization targets are being translated into product strategy. For buyers and investors, these moves signal that supplier selection is increasingly influenced by verifiable sustainability performance, formulation roadmaps, and the ability to support downstream compliance narratives.
Market Evolution: Integration, Specialization, and New Entrant Dynamics
The competitive landscape is evolving along two complementary paths. On one hand, scale-oriented players continue to pursue integration and portfolio breadth to capture efficiency advantages, support multi-application supply, and reinforce regional distribution reach. On the other hand, specialization is intensifying around low-emission formulations, application-specific engineering, and sustainability-linked product attributes. This dual dynamic creates opportunities for incumbents to defend share through performance and compliance leadership, while also opening space for new entrants or expanding specialists that can address underserved application niches or regional compliance requirements. The likely outcome over the next several years is a market where broad-scale suppliers coexist with highly differentiated formulation specialists, and where downstream buyers increasingly manage a dual-sourcing strategy that balances cost, compliance, and technical support.
Forward Outlook: Three Trends Shaping the 2026–2032 Window
Low-Emission Compliance as a Baseline, Not a Premium
As regulatory mandates mature and enforcement intensifies, low-emission UF grades are likely to transition from differentiated offerings to market-entry requirements in key regions. This shift will compress the commercial advantage of early compliance while simultaneously raising the cost of late adaptation. Manufacturers that have already validated low-emission formulations, secured certification pathways, and aligned production lines with compliant grades will be better positioned to manage transition risk. Conversely, suppliers and downstream buyers that delay reformulation or certification readiness may face margin erosion, supply disruption, or exclusion from regulated procurement channels.
Formulation Engineering and Application-Specific Value Creation
Volume growth is expected to increasingly depend on application-specific value creation rather than broad-based resin displacement. Wood adhesives will remain the core demand anchor, but opportunities in molding compounds, surface coatings, and textile finishing will require tailored performance profiles, processing compatibility, and technical service. This trend favors suppliers that can combine formulation flexibility with application engineering, testing support, and regional responsiveness. For downstream manufacturers, it creates an incentive to deepen technical collaboration with resin partners, particularly where product performance, emission profile, and total cost of ownership must be optimized simultaneously.
Cost Volatility and Supply Chain Resilience as Strategic Priorities
Input cost volatility, particularly around formaldehyde and urea-linked feedstocks, is likely to remain a defining feature of the market environment. While long-term contracts, index-linked pricing, and regional sourcing adjustments can mitigate some exposure, the broader reality is that cost resilience will become a strategic priority for both producers and buyers. This includes evaluating supplier diversity, inventory positioning, formulation flexibility, and scenario planning around feedstock price trajectories. For investors, this environment rewards companies that demonstrate disciplined cost management, transparent input exposure, and the ability to adapt formulations without compromising compliance or performance.
Strategic Actions for Decision-Makers
For Manufacturers and Panel Producers
- Validate low-emission resin compatibility across existing and planned production lines before regulatory deadlines tighten further, prioritizing formulations that meet CARB, EPA TSCA, and E0/EU expectations without disrupting cure profiles or bond performance.
- Diversify resin sourcing to balance cost, compliance, and technical support, while establishing clear criteria for supplier evaluation that include emission data, certification support, formulation adaptability, and supply continuity.
- Invest in application testing and co-development with resin suppliers where performance or emission targets require custom formulation, reducing the risk of line stoppages, rework, or certification delays.
For Investors and Strategic Capital Allocators
- Prioritize companies that demonstrate verifiable progress on low-emission formulation roadmaps, ESG transparency, and cost discipline, as these attributes are increasingly correlated with market access and procurement preference in regulated segments.
- Monitor feedstock exposure and pricing pass-through capabilities, recognizing that margin resilience will depend on formulation optimization, regional sourcing flexibility, and contract structures that align input costs with downstream pricing reality.
- Evaluate consolidation and specialization dynamics as indicators of where value is being created, particularly in segments where low-emission compliance, application engineering, and sustainability credentials are reshaping buyer selection criteria.
For Procurement and Supply Chain Leaders
- Integrate emission compliance, certification support, and sustainability reporting into supplier scorecards alongside price, lead time, and quality metrics, ensuring that procurement decisions reflect both regulatory readiness and corporate ESG objectives.
- Establish scenario planning for raw material cost movements, including index-linked contracting, alternative supplier qualification, and inventory strategies that reduce exposure to sudden feedstock price spikes.
- Engage early with resin suppliers on formulation change timelines and certification requirements, aligning procurement calendars with technical validation cycles to avoid disruption during regulatory transitions.
Closing Perspective
The urea formaldehyde resin market is not defined by a single growth driver or a uniform competitive narrative. It is a market in which regulatory compliance, feedstock economics, application-specific performance, and sustainability positioning intersect to shape buyer behavior and supplier strategy. The modest headline growth projection conceals a more nuanced reality: value creation is shifting toward compliance readiness, formulation flexibility, and supply chain resilience, while cost volatility and certification complexity reward companies that act early and coordinate across technical, commercial, and procurement functions. For executives, investors, and supply chain leaders, the practical imperative is to treat resin selection and supplier relationships as strategic variables rather than transactional inputs, and to align product roadmaps, sourcing decisions, and investment priorities with the regulatory and cost realities that will define the next cycle.
For detailed segmentation data, regional demand profiles, application-level revenue splits, and tailored scenario analysis, the full research report provides the granular data and customized recommendations needed to translate these market dynamics into concrete planning parameters.
For detailed analysis of this topic, please visit the official page: Urea Formaldehyde Resin Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Electroretinography Market: Why 8% CAGR and Clinical Diagnostics Shift Strategy
By pmarketresearch, 2026-09-21
Strategic Trends and Commercial Opportunities in the Electroretinography Market
The electroretinography (ERG) market has entered a phase of structural expansion, driven by the convergence of regulatory alignment, technological miniaturization, and the clinical need for objective functional assessment of retinal health. Spanning a base year of 2025 with historical tracking from 2020 through 2025 and a forecast period extending to 2032, the market demonstrates a consistent upward trajectory. Revenue grew from 300.0 million in 2020 to an estimated 414.0 million in 2025, and is projected to reach 711.32 million by 2032, reflecting a compound annual growth rate of 8.0 percent. This growth is not merely incremental; it signals a market transitioning from a niche diagnostic tool toward a more integrated component of routine ophthalmic and neurological evaluation.
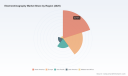
The revenue distribution across testing modalities reveals a clear hierarchy. Full-field flash ERG remains the dominant segment, accounting for the largest share of market value, while multifocal ERG holds a substantial secondary position, reflecting its growing utility in localized retinal function mapping. Pattern ERG and other specialized variants occupy smaller but strategically important niches, often tied to specific clinical indications or research applications. On the application side, clinical diagnostics represent the overwhelming majority of demand, with research activities comprising a meaningful but smaller portion. Geographically, North America leads in market size, followed by Europe, with the Asia Pacific region representing a smaller but rapidly evolving base. Latin America and the Middle East and Africa collectively account for a modest share, though emerging healthcare infrastructure investment suggests latent demand that may unlock as reimbursement pathways mature.
Market concentration remains relatively fragmented. The top three participants collectively hold approximately 24.6 percent of revenue, while the top five reach 26.2 percent. This dispersion indicates that no single entity controls the market, leaving room for strategic consolidation, differentiated technology plays, and regional expansion by mid-tier manufacturers. The absence of dominant concentration also suggests that competitive advantage will increasingly derive from clinical validation, reimbursement alignment, and workflow integration rather than sheer scale alone.
1. Market Status and Core Challenges
The electroretinography market operates at the intersection of diagnostic precision and practical clinical adoption. Despite clear growth signals, several structural challenges shape how manufacturers, providers, and investors approach the space.
PW Consulting
1.1 Reimbursement Ambiguity and Coding Fragmentation
One of the most persistent friction points is the uneven reimbursement landscape for ERG testing. While certain Current Procedural Terminology codes, such as CPT 92273 for full-field ERG with interpretation and report, are recognized under Medicare with defined reimbursement levels and supported by major Medicare Administrative Contractors for medically necessary indications, coverage is not universal across payers. Pattern ERG codes, for example, are frequently classified as investigational by commercial insurers, creating a reimbursement gap that limits routine adoption in some clinical settings. This fragmentation forces manufacturers and provider networks to navigate a patchwork of coverage policies, which can slow procurement cycles and complicate revenue forecasting for diagnostic service providers.
1.2 Standardization Gaps and Protocol Variability
Although the International Society for Clinical Electrophysiology of Vision has published updated standards for full-field clinical electroretinography to promote reproducible recordings using dark-adapted and light-adapted stimuli, real-world implementation varies. Differences in stimulus calibration, electrode placement, patient preparation, and interpretation workflows can affect result consistency across sites. For clinicians, this variability can undermine confidence in ERG as a longitudinal monitoring tool, particularly when integrating findings with structural imaging modalities. For manufacturers, it creates both a challenge and an opportunity: devices that embed standardized protocols, built-in quality checks, and guided workflows can reduce inter-site variability and improve adoption.
1.3 Workflow Integration and Clinical Practicality
Traditional ERG testing has often been perceived as technically demanding, time-consuming, and dependent on dilated pupils or specialized setups. In high-volume clinical environments, any test that disrupts patient flow or requires extensive technician training faces adoption friction. The market is therefore at a turning point where portability, non-mydriatic operation, and streamlined interpretation are becoming decisive factors. Devices that reduce preparation time, allow testing in broader patient populations including newborns and non-cooperative patients, and integrate with existing electronic health record workflows are better positioned to convert clinical interest into sustained purchasing decisions.
2. Key Demand Drivers
The growth trajectory of the electroretinography market is not accidental; it reflects a set of reinforcing drivers that are reshaping how retinal function is assessed, reimbursed, and commercialized.
2.1 Technological Innovation and Portable Non-Mydriatic Systems
The most consequential technological shift is the emergence of handheld, portable ERG platforms that enable functional retinal assessment without dilation and with reduced setup complexity. These systems expand the feasible testing environment beyond specialized electrophysiology labs to outpatient clinics, primary care-linked ophthalmology settings, and even screening programs. By lowering the practical barriers to testing, portable devices increase the addressable patient population and create new use cases for routine diabetic retinopathy monitoring, glaucoma suspect evaluation, and inherited retinal disease screening. The clinical value proposition is reinforced when portable systems demonstrate performance comparable or superior to conventional imaging in predicting disease progression, particularly in moderate to severe non-proliferative diabetic retinopathy, where functional assessment can complement structural imaging and help identify patients at risk of vision-threatening complications.
2.2 Regulatory Clarity and Guideline Alignment
Regulatory and guideline developments are steadily reducing uncertainty around ERG’s clinical role. The inclusion of full-field and multifocal ERG in updated ophthalmologic preferred practice pattern guidelines for diabetic retinopathy management represents a meaningful endorsement, signaling that functional testing has a place in routine disease management rather than being confined to specialized referrals. At the same time, FDA clearance pathways and international certification frameworks, including ISO 13485 and MDSAP compliance, provide a structured route for manufacturers to demonstrate safety and performance. The alignment between standards bodies, regulatory agencies, and clinical guidelines creates a more predictable environment for product development and market entry, particularly for devices that are designed to meet ISCEV-aligned protocols from the outset.
Automated Ophthalmic Perimeters Market
2.3 Demand-Side Shifts Toward Objective Functional Biomarkers
Clinicians and health systems are increasingly seeking objective, quantifiable functional biomarkers that can track disease progression, guide treatment decisions, and support payer discussions. Structural imaging alone does not always capture functional decline, especially in early or moderate disease stages where anatomical changes may be subtle. ERG provides a direct measure of retinal electrical response, offering a complementary data point that can strengthen diagnostic confidence and support longitudinal monitoring. This demand-side shift is particularly relevant in diabetic retinopathy management, where the ability to identify patients at higher risk of progression can influence follow-up intervals, referral patterns, and intervention timing. As value-based care models emphasize outcomes and risk stratification, functional testing that contributes to more precise patient management becomes more attractive to providers and payers alike.
2.4 Supply Chain Consolidation and Portfolio Integration
Recent corporate activity illustrates a broader supply-side trend: established medtech and electronic instruments companies are expanding their ophthalmic diagnostic portfolios through acquisition and integration. By absorbing specialized ERG manufacturers, larger platforms can combine regulatory expertise, distribution networks, and cross-selling capabilities with proven clinical technologies. This consolidation can accelerate market reach, improve service and support infrastructure, and create bundled solutions that pair ERG with other diagnostic modalities. For smaller manufacturers, the environment presents both pressure and opportunity: pressure from potential acquisition or competition with better-resourced rivals, but also opportunity to differentiate through proprietary stimulation methods, advanced protocol libraries, or region-specific reimbursement strategies.
3. Competitive Landscape and Leading Strategies
The competitive field in electroretinography is characterized by a mix of established electrophysiology specialists, vision monitoring companies, and broader diagnostic portfolios that have expanded into retinal functional testing. Rather than competing solely on hardware specifications, leading players are increasingly differentiating through clinical evidence, workflow design, regulatory positioning, and ecosystem integration.
3.1 Strategic Positioning of Leading Participants
Several companies illustrate the range of viable strategic postures within the market. One U.S.-based manufacturer has concentrated on portable, handheld full-field ERG and visual evoked potential systems, emphasizing FDA-cleared, non-mydriatic operation suitable for clinical functional assessment. This positioning targets the practical adoption barrier directly, making the technology accessible in settings where conventional ERG infrastructure is impractical. Clinical evidence linking the device’s scoring approach to prediction of progression in moderate to severe non-proliferative diabetic retinopathy further strengthens the commercial narrative by tying the product to a high-impact clinical use case.
Another U.S. specialist focuses on full-field and multifocal ERG systems with advanced protocols for both clinical and research electrophysiology. This company’s strategy leans toward technical depth, protocol flexibility, and support for rigorous electrophysiological evaluation, appealing to centers that require detailed functional mapping and research-grade capability. In Europe, a French manufacturer has built its identity around a vision monitoring platform that supports multiple ERG modalities and visual evoked potential testing, incorporating proprietary constant-luminance stimulation methods. This approach highlights the importance of stimulation precision and modality breadth as differentiators for customers who need a single platform capable of spanning multiple testing requirements.
A German producer emphasizes electrophysiological diagnostic systems for clinical use across full-field, multifocal, and pattern ERG as well as visual evoked potential testing, positioning around clinical reliability and standards alignment. A U.S. vendor offering multifocal and flash ERG systems for clinical settings continues to serve a segment that values established platforms and specialized electroretinography equipment. An Italian manufacturer provides clinical ERG and electrophysiological diagnostic equipment with an emphasis on compliance with international standards, which can be an important factor in markets where regulatory and procurement processes are closely tied to certification and conformity. A Russian manufacturer has extended its reach into full-field and extended ERG testing across age groups, including newborns, illustrating how demographic coverage and pediatric capability can open niche but valuable application spaces.
Worldwide 12 Channel Electrocardiograph Market
The acquisition of the portable ERG platform by a larger electronic instruments company in early 2026 exemplifies the portfolio integration strategy. By embedding the handheld device within a broader ophthalmic diagnostics portfolio, the acquiring company gains a differentiated functional testing offering, an established regulatory and quality framework, and a channel to expand distribution. This move also signals to the market that portable non-mydriatic ERG is viewed as a strategic asset rather than a peripheral niche product.
3.2 Market Evolution Trends
The competitive landscape is evolving along several interrelated dimensions. Consolidation is likely to continue as larger platforms seek to strengthen their diagnostic portfolios and smaller specialists evaluate whether independence or partnership better serves their growth ambitions. At the same time, differentiation is shifting toward clinical validation, reimbursement readiness, and workflow integration. Devices that can demonstrate alignment with recognized standards, support Medicare and commercial coverage pathways, and fit smoothly into clinic operations are gaining an advantage over products that rely primarily on technical specifications.
Regional dynamics also shape competition. In North America, reimbursement alignment and guideline inclusion are powerful adoption catalysts, favoring products with strong regulatory documentation and clinical evidence. In Europe, standards conformity, multi-modality platforms, and regional service networks influence purchasing decisions. In Asia Pacific and other emerging markets, adoption may be more sensitive to price, training support, and the ability to operate in varied clinical settings, suggesting that a one-size-fits-all go-to-market approach will underperform. New entrants that can address specific gaps, such as pediatric testing, portable screening, or integrated interpretation tools, may find opportunities even in a market with established incumbents.
4. Future Trend Predictions
Looking ahead across the next three to five years, several trends are likely to define the market’s direction and shape the commercial opportunities available to manufacturers, providers, and investors.
4.1 From Specialized Testing to Routine Functional Assessment
As portable, non-mydriatic systems mature and clinical guidelines continue to recognize the role of full-field and multifocal ERG in conditions such as diabetic retinopathy, functional retinal testing is likely to move from specialized referral settings toward more routine use. This shift creates opportunities for manufacturers to design products that prioritize speed, ease of use, and interpretation support, and for providers to build service lines around objective functional monitoring. The commercial implication is clear: devices that can be deployed in broader clinical environments and supported by clear reimbursement logic will capture more consistent demand than those tied to niche specialist workflows.
4.2 Evidence-Led Adoption and Predictive Clinical Value
The next phase of adoption will be increasingly driven by clinical evidence that ties ERG findings to meaningful outcomes, particularly risk stratification and progression prediction. Studies demonstrating that functional scoring can outperform or complement structural imaging in forecasting vision-threatening complications provide a template for how evidence can accelerate uptake. As more data accumulate, sales cycles may shorten in settings where ERG is framed not merely as an alternative test but as a decision-support tool that influences management. Manufacturers and service providers that invest in robust clinical validation and real-world evidence generation will be better positioned to justify formulary inclusion, procurement priority, and payer coverage.
4.3 Ecosystem Integration and Multi-Modal Workflows
ERG is unlikely to replace structural imaging; instead, it will increasingly be integrated into multi-modal diagnostic workflows. Platforms that combine functional and structural data, support standardized reporting, and connect with electronic health records will offer greater value to busy clinical teams. This trend also encourages portfolio-level competition, where companies aim to provide a coherent diagnostic suite rather than isolated instruments. For investors, this suggests that value may accrue not only to best-in-class standalone devices but also to platforms that can embed ERG within broader ophthalmic or neurological diagnostic ecosystems.
4.4 Risks and Uncertainties
Several uncertainties could alter the pace or shape of growth. Reimbursement policy remains fluid, and adverse changes to coverage for pattern ERG or shifts in medical necessity documentation requirements could slow adoption in certain segments. Standardization, while improving, is not yet universally implemented; sites that lack trained personnel or consistent protocols may underutilize available technology. Competition from alternative functional or structural assessments, including advanced imaging and artificial intelligence-assisted diagnostics, could compress ERG’s role if those modalities prove more convenient or better reimbursed. Finally, macroeconomic pressure on healthcare capital spending may extend procurement cycles, particularly in smaller practices and emerging markets, making clear return-on-investment arguments more important than ever.
5. Strategic Recommendations for Decision-Makers
Companies operating in or entering the electroretinography market face a landscape where clinical utility, regulatory alignment, and workflow practicality determine commercial success more than specification comparisons alone. The following recommendations translate the current dynamics into actionable priorities for different stakeholder groups.
5.1 For Manufacturers
Develop products with reimbursement and guideline alignment built into the design and commercialization plan, not treated as an afterthought. Where possible, support ISCEV-aligned protocols, document performance against recognized standards, and generate clinical evidence that connects functional testing to decision-making in high-prevalence conditions such as diabetic retinopathy. Prioritize portability, non-mydriatic operation, and streamlined interpretation to broaden the addressable setting beyond specialized labs. Consider whether independent positioning or portfolio integration best fits your capabilities, and invest in service, training, and workflow compatibility to reduce adoption friction.
5.2 For Investors
Evaluate opportunities not only on technology novelty but on the strength of clinical evidence, reimbursement readiness, and the ability to integrate into routine care pathways. Companies that can demonstrate a clear link between functional assessment and risk stratification, supported by credible validation and standards alignment, are better positioned for durable adoption. Monitor consolidation trends, as acquired platforms may gain distribution and service advantages, while independent specialists may offer niche leadership in areas such as pediatric testing, advanced protocols, or region-specific reimbursement strategies. Scrutinize portfolio fit and cross-selling potential when assessing larger platforms that are expanding into ophthalmic diagnostics.
5.3 For Procurement and Clinical Leaders
Assess ERG solutions based on how well they fit into existing workflows, the availability of standardized protocols, and the practical training burden for staff. Favor systems that support consistent, reproducible recordings and provide clear interpretation support, particularly if the goal is to use ERG for longitudinal monitoring or risk stratification. Evaluate total cost of ownership in the context of reimbursement realities, including whether the intended use cases align with covered indications and documentation requirements. Where possible, seek evidence that the selected solution contributes to measurable improvements in patient management, rather than treating ERG as an isolated diagnostic add-on.
The electroretinography market is advancing along a path shaped by portable technology, guideline recognition, and a growing appetite for objective functional biomarkers. The companies and clinical programs that succeed will be those that treat ERG as part of a broader diagnostic strategy, supported by evidence, standards, and practical workflow design. For decision-makers who need granular segmentation data, competitive benchmarking, reimbursement mapping, and customized scenario analysis, a comprehensive market research report can provide the level of detail required to translate these trends into concrete investment, product, and procurement decisions.
For detailed analysis of this topic, please visit the official page: Electroretinography Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Strategic Shifts and Commercial Opportunities in the Global Glass Microfiber Market
The global glass microfiber market has entered a phase of measured expansion, evolving from a niche material segment into a strategically important component across filtration, energy storage, and thermal management applications. Over the 2020–2025 period, the market demonstrated steady growth, reaching a valuation of approximately $33.0 million in 2025. The trajectory into the 2026–2032 forecast window points to a compound annual growth rate of 5.48 percent, with the market expected to approach $47.9 million by 2032. This baseline reflects both residual growth from mature industrial applications and incremental demand from emerging use cases. The expansion is not uniform, however, and beneath the aggregate figures lies a landscape shaped by feedstock dynamics, technological differentiation, and shifting regulatory expectations. For executives and investors evaluating exposure to advanced nonwoven materials, the glass microfiber segment presents a case study in how commodity-linked inputs can coexist with high-value specialty positioning.
Navigating Constraints in a Mature yet Evolving Segment
The market’s current phase is defined by three intersecting challenges that require strategic attention. First, the cost structure remains highly sensitive to raw material inputs. High-purity quartz, the foundational feedstock for borosilicate glass microfiber production, has exhibited notable price volatility, with premium grades beginning at $5,000 per ton. This volatility directly constrains margin predictability and influences capacity planning decisions across the value chain. Second, regulatory and compliance expectations are tightening around product consistency, particularly for borosilicate formulations used in analytical, laboratory, and filtration contexts. Manufacturers must navigate not only cost pressures but also the operational burden of maintaining traceable, high-purity production streams. Third, the industry exhibits meaningful concentration, with the top three players accounting for roughly 45.2 percent of market share and the top five reaching 62.1 percent. This concentration signals entrenched competitive positions, but it also leaves room for targeted differentiation by regional specialists, application-focused producers, and new entrants that can align product specifications with emerging demand pockets.
Core Drivers Reshaping the Market Trajectory
Understanding where the market is headed requires examining the forces that are actively reshaping demand, supply, and competitive behavior. These drivers are not isolated; they interact in ways that create both headroom and friction.
Technological innovation remains a primary catalyst. The transition from commodity-grade microfiber to engineered, application-specific formulations has unlocked performance gains in filtration efficiency, thermal stability, and dimensional consistency. Developments in binderless architectures and specialty borosilicate blends have reduced dependency on additive systems, enabling manufacturers to offer products that better meet the purity and durability requirements of analytical and cleanroom environments. At the same time, advancements in nonwoven processing have expanded the utility of glass microfiber beyond traditional paper and filter formats, allowing it to perform in battery separator-adjacent functions and heat preservation materials where weight, insulation, and chemical resistance matter.
Policy and regulatory dynamics are compounding these technical shifts. Environmental and safety expectations are increasingly shaping procurement criteria in industrial filtration, HVAC, and laboratory settings. As end-users place higher value on traceability, low-leaching performance, and consistent particle retention, the bar for qualification rises. Regulatory pressure does not uniformly suppress demand; rather, it accelerates the separation between standard-grade offerings and premium, compliance-ready products. Companies that can demonstrate robust quality systems and transparent sourcing gain a structural advantage in markets where substitution risk is low and qualification cycles are long.
Demand-side behavior is also evolving. Industrial operators and research institutions are prioritizing filtration media that deliver higher efficiency with lower lifecycle cost, even if upfront pricing is higher. This preference is visible in cleanroom, environmental monitoring, and high-purity laboratory applications, where failure costs outweigh material cost considerations. Simultaneously, growth pockets in energy-related and thermal management applications are pulling glass microfiber into adjacent value chains. While the filter paper segment continues to anchor a substantial portion of revenue, battery-adjacent and heat preservation use cases are expanding the addressable base. The practical implication is that demand is becoming more application-specific, and generic commodity positioning is increasingly vulnerable to displacement by tailored solutions.
Supply chain and cost structure changes complete the picture. Feedstock volatility, as noted, affects planning horizons and pricing strategies. Producers that secure long-term quartz supply arrangements, invest in process efficiency, or localize certain production steps can convert cost pressure into a barrier for less-prepared competitors. At the same time, geographic divergence in demand intensity means that supply decisions increasingly weigh regional proximity, logistics stability, and local compliance requirements alongside pure production economics.
Recent operational moves underscore these dynamics in practice. In January 2026, Johns Manville launched a state-of-the-art micro fiberglass production line at its Wertheim, Germany facility to produce Evalith micro fiberglass nonwovens. This capacity expansion reflects a deliberate push into higher-value nonwoven formats, aligning product architecture with filtration, specialty paper, and battery separator-adjacent applications. The move illustrates how leading producers are translating technical differentiation into tangible capacity and geographic positioning, rather than relying solely on incremental grade improvements.
Competitive Positioning and the Evolution of Market Structure
The competitive landscape is anchored by companies that have built strong reputations around product specialization, application alignment, and quality assurance. These players do not compete on identical terms; instead, each has carved a distinct strategic position that leverages specific technological or market strengths.
Johns Manville, headquartered in Denver, Colorado, operates as a broad-based producer with recognized franchises in JM Micro-Strand and Evalith glass microfibers. Its portfolio spans filtration, battery separators, and specialty papers, giving it a multi-application footprint that supports cross-selling and scale advantages in nonwoven production. The recent German capacity expansion reinforces its emphasis on advanced nonwoven formats and positions the company to serve European and export markets with a more localized, higher-specification supply base.
Hollingsworth & Vose, based in East Walpole, Massachusetts, maintains a clear identity as a specialist in high-efficiency glass microfiber filter media. Its focus on cleanroom, HVAC, and industrial filtration aligns it with sectors where performance consistency, particulate retention, and compliance readiness are decisive. This application-centric positioning allows the company to compete on technical merit and qualification reliability rather than price alone.
I.W. Tremont, located in Riverton, New Jersey, has built its profile around binderless and specialty 100 percent borosilicate glass microfiber for laboratory, analytical, and volatile suspended solids filtration. The emphasis on borosilicate purity and binderless construction addresses stringent analytical requirements and creates a defensible niche where substitution is difficult once methods and protocols are established. This specialization also makes the company particularly exposed to high-purity quartz cost dynamics, but it simultaneously raises switching costs for demanding end-users.
Porvair Filtration Group, headquartered in Fareham, United Kingdom, supplies precision glass microfiber filter media and cartridges for laboratory, environmental, and industrial applications. Its cartridge and media combination strategy connects material performance with downstream system integration, giving customers a more complete solution path. This approach is well suited to environments where filter format, housing compatibility, and replacement cycles influence total cost of ownership.
The market structure is evolving along several vectors. Concentration at the top indicates that scale, brand familiarity, and established qualification networks matter, but the presence of highly specialized players shows that segmentation remains viable. Differentiation is increasingly tied to product architecture, application fit, and supply reliability rather than volume alone. Integration trends are likely to continue where larger players seek to secure higher-margin nonwoven and specialty segments, while smaller specialists may pursue regional expansion, formulation depth, or partnership-based distribution. New entry remains challenging due to qualification cycles and feedstock complexity, but targeted entry in underserved applications or geography-specific supply gaps is not implausible, especially where local compliance and proximity advantages can be leveraged.
Looking Ahead: Three Trends That Will Shape the Next Three to Five Years
The next phase of market development will be shaped by the interaction of feedstock economics, application expansion, and the premiumization of compliant, high-performance materials. The first trend is the continued bifurcation between standard-grade and engineered offerings. As end-users in filtration, laboratory, and thermal applications place greater weight on consistency, purity, and lifecycle performance, the share of revenue associated with premium, application-tailored products is expected to rise even if overall growth remains moderate. This trend rewards manufacturers that can sustain tight specification control, provide clear qualification support, and reduce total cost of ownership for customers through better performance rather than lower sticker price.
The second trend is the gradual broadening of application adjacency. While filter paper remains a central demand anchor, battery-related and heat preservation use cases are expanding the contexts in which glass microfiber is evaluated. This does not imply a sudden surge in any single application, but it does suggest that product development and commercial teams should treat adjacent markets as incremental growth vectors, particularly where insulation, chemical resistance, and dimensional stability align with material strengths. Companies that can translate filtration and analytical credibility into credibility for thermal and energy-adjacent applications will have more options to diversify revenue.
Microfiber Market
The third trend is supply-side recalibration around feedstock risk and regionalization. High-purity quartz volatility will continue to influence cost planning, and producers will increasingly manage this risk through long-term sourcing, process efficiency gains, and strategic capacity placement. Regional demand intensity will also matter more as customers prioritize supply resilience and compliance alignment. Over the next three to five years, the market is likely to reward players who can combine formulation expertise with reliable, geographically appropriate supply, while those dependent on undifferentiated commodity positioning may face margin compression and substitution pressure.
These trends carry both opportunity and uncertainty. Demand for premium solutions is real, but qualification cycles can be slow and customer switching behavior cautious. Feedstock volatility can compress margins even for differentiated products if not managed proactively. And while application adjacency opens new paths, it also requires credible performance data and application-specific validation before commercial traction materializes. Executives should therefore treat growth as achievable but conditional on disciplined product strategy, supply risk management, and targeted commercial execution.
Strategic Actions for Different Decision-Maker Profiles
For manufacturers, the priority is to reinforce differentiation where qualification and performance consistency create durable advantages. This means investing in formulation precision, binderless or low-additive architectures where appropriate, and application-focused product documentation that speeds customer validation. Capacity and sourcing decisions should be evaluated not only on unit cost but also on proximity to key demand pools, resilience to quartz price swings, and the ability to support regional compliance expectations. Companies that align product roadmaps with higher-value nonwoven, analytical, and thermal use cases are better positioned to capture premium share than those competing primarily on volume.
For investors, the relevant question is where value is created and protected within the segment. Market concentration indicates that scale and brand matter, but the more durable opportunities often sit in specialized formulations, application-aligned portfolios, and supply chains that mitigate feedstock volatility. Due diligence should examine how well a company manages high-purity quartz exposure, whether its product mix leans toward standard or engineered grades, and how effectively it converts technical capability into qualified, repeatable customer relationships. Investment theses that assume uniform growth across all applications will likely overlook the segmentation dynamics that actually drive margin and retention.
PW Consulting
For procurement and sourcing leaders, the focus should shift from unit price to total cost of ownership and qualification risk. In filtration, laboratory, and thermal applications, inconsistency or non-compliance can create far greater costs than material price differences. Evaluating suppliers on traceability, lot-to-lot consistency, technical support, and long-term feedstock stability is a practical way to reduce operational risk. Where possible, securing multi-source options for critical grades while deepening relationships with suppliers that demonstrate strong quality systems can balance resilience with performance assurance.
Across all of these perspectives, the value of detailed, application-level and regional intelligence is clear. Aggregate market size and growth rates provide a useful frame, but they do not reveal where specification upgrades are accelerating, which applications are expanding fastest, how feedstock cost exposure differs by product type, or where capacity additions will alter competitive dynamics. Decision-makers who pair strategic intent with granular market data are better equipped to time capacity moves, prioritize product development, and structure supplier relationships with greater confidence.
Glass Fibers Market
A closer examination of the market’s segmentation splits, application-level demand shifts, regional intensity patterns, and company-specific strategic moves can sharpen planning considerably. For teams seeking to align investment, sourcing, or product strategy with the structural dynamics of glass microfiber, a fuller dataset and tailored analysis provide the detail needed to move from directional insight to executable decision-making. The complete research report offers that level of segmentation depth, including detailed regional and application breakdowns, competitive positioning context, and forward-looking scenario analysis designed to support specific business decisions.
For detailed analysis of this topic, please visit the official page: Glass Microfiber Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Rugged Handheld Device Market: Why 7.2% CAGR and Manufacturing Demand Redefine Growth
By pmarketresearch, 2026-09-21
Strategic Trends and Commercial Opportunities in the Rugged Handheld Device Market
1. Market Landscape and Core Challenges
The rugged handheld device market has evolved from a niche equipment segment into a critical infrastructure layer for enterprise mobility and field operations. Valued at approximately $1.4 billion in 2020, the market has demonstrated consistent expansion, crossing the $1.9 billion threshold by 2025 and reaching a projected valuation beyond $3.1 billion by the end of the 2032 forecast period. This growth trajectory reflects a compound annual growth rate of roughly 7.2 percent, signaling sustained demand across both mature and emerging application domains. The expansion is not merely a function of unit volume increases but is increasingly driven by value escalation as devices incorporate advanced connectivity, processing power, and specialized certifications that justify higher average selling prices.
The market structure reveals a moderately concentrated environment where leading vendors collectively command a significant share of global revenue. This concentration underscores the barriers to entry posed by certification requirements, engineering expertise in materials and thermal management, and long-term enterprise procurement cycles. While the top tier of manufacturers maintains strong positioning, the tail of the market remains fragmented, with regional specialists and vertical-focused players competing on cost, localized support, or application-specific features. This duality creates a dynamic landscape where scale advantages coexist with opportunities for targeted differentiation.
Key Challenges and Inflection Points
Despite favorable growth indicators, the industry faces several structural tensions that will shape competitive outcomes over the next several years.
The first challenge lies in balancing ruggedization with the demand for consumer-grade user experiences. Field workers increasingly expect intuitive interfaces, fast boot times, seamless wireless connectivity, and long battery life, while operations teams require devices that withstand drops, dust, moisture, extreme temperatures, and hazardous atmospheres. Engineering teams must reconcile these competing priorities without inflating device weight, cost, or thermal complexity. Manufacturers that fail to deliver an ergonomic, reliable user experience risk adoption friction, even when hardware durability is technically superior.
A second inflection point involves certification and compliance intensity. Environmental durability standards, ingress protection thresholds, and hazardous-location certifications have become table stakes in many verticals. These requirements extend development cycles, increase validation costs, and create procurement hurdles when end users must verify compliance across multiple jurisdictions or site-specific safety regimes. As regulatory scrutiny intensifies in sectors such as utilities, oil and gas, and public safety, compliance capability is transitioning from a technical checkpoint to a strategic differentiator that influences vendor selection and deployment speed.
The third challenge is supply chain resilience and component availability. Rugged devices depend on specialized enclosures, shock-absorbing materials, industrial-grade displays, and connectivity modules that are not always interchangeable with mainstream consumer components. Volatility in semiconductor allocations, logistics disruptions, and the need for long product lifecycles complicate inventory planning and cost management. Vendors must design for serviceability, component substitution, and predictable refresh cycles while maintaining performance and durability commitments across multi-year deployment horizons.
2. Core Demand Drivers
Technology Innovation and Breakthroughs
Technology advancement is reshaping what rugged handheld devices can deliver in the field. The integration of high-performance processing platforms, accelerated by artificial intelligence capabilities, is enabling on-device analytics, smarter barcode and text recognition, and more responsive workflow assistance. Recent product announcements illustrate this shift: Getac unveiled a rugged Copilot+ PC lineup alongside next-generation B360 and B360 Pro models designed with AI-ready hardware and full rugged reliability, signaling a move toward intelligent mobile productivity in demanding environments. Similarly, the company introduced 8-inch fully rugged Windows 11 IoT Enterprise LTSC tablets built on Arm-based platforms with fanless designs and high-memory configurations, highlighting the trend toward efficient, thermally managed performance that supports advanced workloads without sacrificing durability.
Connectivity evolution is another critical driver. Devices are increasingly equipped with Wi-Fi 6, integrated scanning engines, and modular pathways for 5G, enabling real-time data exchange in warehouses, retail floors, and remote sites. Panasonic has emphasized modular 5G and AI designs within its rugged handheld portfolio, reinforcing the expectation that future devices must maintain continuous, low-latency connectivity while operating in environments where infrastructure may be inconsistent. On the component side, durable displays, glove-friendly touch surfaces, and high-capacity batteries are becoming standard expectations rather than premium add-ons. Winmate's recent launches of compact rugged Android handhelds and updated tablet lineups demonstrate how vendors are prioritizing fast scanning, reliable wireless links, and extended battery endurance in compact form factors tailored for field service and warehouse workflows.
Policy and Regulatory Environment
Regulatory and certification frameworks continue to exert a strong influence on device design and market access. Environmental durability testing protocols, such as military-standard evaluation procedures, are widely referenced as benchmarks for shock, vibration, temperature extremes, humidity, and dust resistance. These protocols provide a common language for procurement teams assessing device robustness, and many product lines pair such compliance with high ingress protection ratings to assure operation in harsh field conditions. For utilities, public safety, and defense applications, the combination of durability certification and sealed enclosures is often a prerequisite rather than an optional feature.
In addition to durability standards, hazardous-location certifications are increasingly relevant for sectors exposed to explosive atmospheres, including oil and gas and chemical processing. Devices intended for these environments must meet specific certification thresholds, which shape component selection, enclosure design, and thermal management strategies. The cumulative effect is that regulatory adherence is not merely a compliance exercise but a design constraint that defines the feasible product space. Vendors that internalize these requirements early in the development process can shorten deployment timelines and reduce the risk of post-purchase modifications or site-specific delays.
Rugged Notebooks Market
Demand-Side Shifts in Enterprise Behavior
Enterprise buyers are rethinking mobile device strategy in response to operational pressures. The push toward real-time visibility, digital work instructions, and automated data capture is expanding the role of handheld devices beyond simple scanning or communication tools. In manufacturing, facilities are deploying rugged mobile computers to support quality inspections, asset tracking, and maintenance workflows that require reliable performance in dusty, high-traffic environments. Retail and logistics organizations continue to prioritize devices that integrate scanning, rugged mobility, and enterprise software compatibility to streamline inventory, fulfillment, and field service operations.
At the same time, procurement preferences are shifting toward devices that support longer service lives, predictable upgrade paths, and software environments aligned with enterprise IT policies. Buyers are increasingly attentive to operating system longevity, manageability, and the ability to integrate with existing mobility platforms. This demand-side behavior favors vendors that can offer stable software roadmaps, certified enterprise features, and support structures capable of sustaining deployments over multiple years. The result is a market where durability remains essential, but total cost of ownership, IT integration, and workflow efficiency are becoming equally decisive in purchasing decisions.
Supply Chain and Cost Structure Dynamics
Cost structures in the rugged handheld market are influenced by material selection, component sourcing, and the economics of certification and validation. Magnesium-alloy chassis, reinforced corners, sealed interfaces, and robust display protection contribute to durability but also affect weight, manufacturability, and unit cost. Vendors must navigate trade-offs between over-engineering and optimal protection, particularly as end users become more sensitive to device ergonomics and handheld fatigue during extended shifts.
Supply chain dynamics add another layer of complexity. Long lifecycle support requires forward planning for component availability, firmware maintenance, and spare parts logistics. Devices that rely on specialized scanning modules, industrial-grade memory, or specific connectivity stacks may face longer lead times or substitution challenges when supply conditions tighten. Companies that design with modularity, standardize on broadly available platforms where feasible, and maintain transparent roadmaps are better positioned to manage cost volatility while preserving performance and durability commitments. This is especially relevant for sectors with multi-year fleet refresh cycles, where predictability in pricing and availability can be as important as hardware specifications.
3. Competitive Landscape and Leading Strategies
Strategic Positioning of Key Players
The competitive arena is shaped by vendors that combine durability engineering with application-tailored features and strong enterprise support ecosystems. Zebra Technologies has built a strong presence through ultra-rugged Android and Windows handheld computers and tablets optimized for warehouse, retail, logistics, and field service workflows. Its product families emphasize MIL-STD-810H and high ingress protection ratings, aligning durability with practical operational needs. This positioning reflects a strategy centered on workflow reliability and integration with enterprise mobility software, appealing to organizations that seek consistent performance across high-volume environments.
Honeywell competes with rugged handheld mobile computers and tablets featuring Wi-Fi 6, integrated scanning, and military-standard compliance, targeting retail, warehouse, and field operations. Its approach underscores the importance of connectivity and data capture precision in settings where speed and accuracy directly affect throughput. By embedding scanning and wireless performance into rugged form factors, the company addresses the convergence of durability and operational efficiency that many enterprises now expect.
Getac Technology has carved a distinctive position with fully rugged Windows and Android tablets and handhelds built around magnesium-alloy chassis, high-level shock protection, and hazardous-location ratings. Its focus on defense, utilities, and extreme environments is reinforced by recent moves into AI-ready hardware and Arm-based platforms with fanless designs, as well as certifications for explosive atmospheres. This combination of rugged engineering and advanced compute readiness positions Getac for sectors where environmental resilience and future-proof performance are both critical.
Panasonic contributes to the landscape with rugged handheld computers and tablets featuring modular 5G and AI designs alongside military-standard certification. Its emphasis on construction, logistics, and public safety reflects a strategy that prioritizes adaptability across demanding use cases while maintaining durable, dependable hardware. Datalogic focuses on rugged handheld PDAs and scanners with strong ingress protection and durable glass, supporting enterprise data capture in retail, manufacturing, and logistics. Its strength lies in precision data capture and practical durability, which appeal to organizations where scanning reliability is central to daily operations.
Winmate rounds out the competitive field with compact rugged Android handhelds and tablets designed for warehouse and field service use. Recent launches highlight fast barcode scanning, long battery life, reliable wireless connectivity, and high ingress protection in compact form factors. This approach demonstrates how smaller-footprint devices can deliver field-ready durability while meeting the ergonomic and battery expectations of mobile workforces.
Market Evolution Trends
The competitive landscape is evolving along several axes. First, there is a clear trend toward higher performance and smarter capabilities within rugged form factors. Devices are no longer limited to basic durability; they increasingly incorporate AI-ready hardware, advanced wireless standards, and modular platforms that support future upgrades. This shift is raising the bar for what qualifies as a competitive device and is pushing vendors to invest in both hardware engineering and software manageability.
Second, the market is seeing a blend of consolidation and specialization. Larger players with broad portfolios and global support networks continue to strengthen their position in high-volume sectors, while specialists deepen their relevance in verticals that demand unique certifications, form factors, or regional service capabilities. New entrants face a challenging path because credibility in rugged markets depends on demonstrated durability, certification success, and the ability to support deployments over time. As a result, credible differentiation often comes from targeted vertical expertise, innovative materials or thermal designs, or distinctive software and integration capabilities rather than from price competition alone.
Third, procurement behavior is encouraging vendors to think beyond hardware specifications. Fleet manageability, software longevity, serviceability, and support responsiveness are becoming integral to competitive positioning. Vendors that can reduce IT overhead, simplify deployments, and maintain predictable product availability are likely to gain advantage in environments where operational continuity matters as much as device toughness.
PW Consulting Health Care Research Center
4. Future Outlook: Trends and Opportunities
Trend One: AI-Ready Rugged Devices Become Mainstream
Over the next three to five years, rugged handheld devices are likely to become increasingly AI-enabled, not only through cloud-connected services but also via on-device processing that supports faster recognition, contextual assistance, and adaptive workflows. The shift toward AI-ready hardware in rugged product lines suggests that enterprises will begin to expect intelligent features as part of the baseline for field mobility. This creates opportunities for vendors that can deliver efficient, thermally sound designs capable of running advanced workloads without compromising durability or battery life. For end users, the opportunity lies in reducing manual effort, improving data quality, and enabling more responsive decision-making in environments where connectivity may be intermittent.
The associated risk is that AI capability claims may outpace practical deployment value if hardware optimization, software ecosystem support, and workflow integration are not aligned. Buyers will need to evaluate not just the presence of AI-ready silicon but the tangible operational benefits, manageability, and long-term support commitments that accompany it.
Trend Two: Certification and Compliance as Differentiators
As deployment environments grow more varied and safety expectations rise, certification and compliance capability will become an increasingly visible competitive dimension. Durability testing protocols, ingress protection standards, and hazardous-location certifications are already shaping procurement decisions in defense, utilities, public safety, oil and gas, and chemical processing. In the coming years, vendors that can clearly demonstrate compliance, streamline verification for buyers, and design for multiple certification regimes are likely to secure an advantage in complex tenders and multi-site rollouts.
This trend presents commercial opportunities for players that invest early in certification roadmaps and document their testing rigor in ways that reduce buyer uncertainty. It also introduces risk for those that treat compliance as an afterthought, since remediation or revalidation can delay deployments and erode trust. In highly regulated sectors, the ability to meet site-specific requirements quickly and confidently may matter as much as core hardware performance.
Trend Three: Compact, Modular, and Lifecycle-Focused Designs
A third trend is the growing emphasis on compact, modular designs that balance portability with durability and support long lifecycle management. Field workers often prefer lighter, more ergonomic devices, while operations teams require flexibility to adapt hardware to changing needs. Recent product activity in compact rugged Android handhelds and updated tablet lineups points to demand for devices that combine strong protection with practical form factors, reliable battery performance, and connectivity suitable for warehouse and field service use.
Modularity and lifecycle planning create opportunities for vendors to offer predictable refresh paths, component serviceability, and software continuity that reduce total cost of ownership. For enterprises, this means fewer disruptions during fleet updates and more control over upgrade timing. The uncertainty here lies in balancing modularity with rugged integrity; too many interchangeable elements can complicate sealing, structural protection, and validation, while overly integrated designs may limit flexibility. Successful products will be those that reconcile these priorities without weakening durability or maintainability.
Commercial Opportunity Implications
These trends point to several commercial opportunities. There is room for vendors that can deliver intelligent, durable devices with clear software roadmaps and strong manageability, especially in sectors where real-time data capture and workflow efficiency are priorities. There is also opportunity in vertical-specific solutions that combine the right certification profile, form factor, and support model for defense, utilities, manufacturing, retail, and logistics. For enterprises, the opportunity lies in selecting devices that match both immediate operational needs and longer-term IT strategy, rather than optimizing for a single specification in isolation.
Risks include component availability volatility, the temptation to over-index on feature lists without sufficient attention to ergonomics or serviceability, and the possibility that certification complexity slows adoption in new regions or verticals. Navigating these risks will require disciplined product planning, transparent communication with buyers, and a clear understanding of how device choice affects operational continuity over time.
5. Strategic Recommendations for Decision Makers
For Manufacturers and Product Leaders
Prioritize the balance between rugged integrity and user experience. Durability is necessary but no longer sufficient; devices must also deliver intuitive interaction, dependable battery performance, and connectivity that supports real workflows. Invest in AI-ready hardware and efficient thermal design where it provides measurable field benefits, and ensure that advanced features are supported by manageable software environments and clear upgrade paths. Build certification and compliance into the design process early, particularly for sectors with hazardous-location or extreme-environment requirements, so that validation accelerates rather than delays market entry.
Also consider lifecycle economics. Design for serviceability, component availability, and predictable refresh cycles. A device that performs well in the first year but creates support burden or replacement complexity later will weaken portfolio competitiveness over time. Where possible, standardize on broadly supportable platforms and provide transparent roadmaps that help enterprise customers plan deployments with confidence.
Rugged Tablet Market
For Investors and Strategic Planners
Focus on vendors that combine durable hardware engineering with software manageability, vertical relevance, and credible support ecosystems. The market's growth is supported by structural demand for field mobility, but outperformance will likely come from companies that can translate durability into operational value through integration, certification readiness, and lifecycle support. Monitor how AI-ready rugged devices move from announcement to widespread deployment, as this will reveal which intelligent features deliver genuine workflow improvements and which remain aspirational.
Pay attention to differentiation signals in certification strategy, modular design, and regional service capability. These factors often determine win rates in complex procurement scenarios and influence the durability of competitive advantages. Investment theses should account for the reality that rugged markets reward execution consistency and long-term customer support as much as product innovation.
For Procurement and Operations Leaders
Evaluate rugged handheld devices against total operational impact rather than isolated specifications. Consider device ergonomics for extended shifts, battery endurance under real workload patterns, wireless reliability in the intended environment, and the ease of integrating the device with existing enterprise software and management tools. Verify certification relevance to the actual deployment context, ensuring that durability and safety claims match site conditions instead of relying on generic marketing language.
Plan for lifecycle needs from the outset. Ask about software longevity, firmware support, spare parts availability, and the process for fleet-wide updates or replacements. Where multi-year deployments are expected, prioritize vendors that can provide predictable availability and support continuity. The strongest purchasing decisions will align device ruggedness with workflow efficiency, IT manageability, and long-term operational resilience.
Looking Ahead
The rugged handheld device market is entering a phase where durability, intelligence, and lifecycle practicality must advance together. Growth is supported by expanding use of real-time data capture, field mobility, and connected operations across manufacturing, retail, logistics, defense, and utilities. At the same time, competitive success will depend on how well vendors reconcile rugged engineering with user experience, certification rigor, and supply chain predictability. The organizations that make device choices with these trade-offs in mind will be better positioned to turn rugged handheld technology into reliable operational capability rather than a isolated hardware purchase.
For those seeking a deeper breakdown of segment-level dynamics, regional nuances, company-level benchmarking, and tailored recommendations aligned to specific deployment contexts, the full PW Consulting report provides a more granular view of the market and its strategic pathways.
For detailed analysis of this topic, please visit the official page: Rugged Handheld Device Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Trail Running Shoes Market: Why 6.85% CAGR and 55% CR3 Signal Industry Shifts
By pmarketresearch, 2026-09-21
Trail Running Shoes Market: Strategic Trends and Commercial Opportunities Through 2032
The global trail running shoes market has evolved from a niche segment within the broader athletic footwear industry into a distinct growth engine, driven by shifting recreational habits, technological refinement, and category-specific performance demands. Tracking the full market trajectory from 2020 through the forecast window extending to 2032, the sector demonstrates consistent expansion with a compound annual growth rate of 6.85%. Revenue progressed from 5.92 billion U.S. dollars in 2020 to 8.45 billion in 2025, with projections indicating a climb to 13.52 billion by 2032. This trajectory underscores a market that has moved beyond pandemic-era spikes and established a structural growth foundation. The category’s resilience reflects deeper changes in how consumers engage with outdoor recreation, how brands engineer footwear for technical terrain, and how distribution channels adapt to specialized product lines.
PW Consulting
Despite the positive trajectory, the industry faces structural tensions that will shape competitive positioning over the next several years. First, tariff exposure and trade policy volatility have introduced meaningful cost uncertainty into the footwear supply chain. Certain footwear imports, particularly those originating from China, could face effective duty rates approaching 145%, creating pricing pressure for brands that assemble substantial inventory in Vietnam and other Southeast Asian hubs. This dynamic threatens to push retail prices for trail models from approximately 155 U.S. dollars toward 220 U.S. dollars, compressing margin flexibility and altering price elasticity assumptions. Second, the category carries inherent manufacturing complexity. Reinforced uppers and outsoles raise production complexity by 18–25% compared with road running counterparts, and retail audits consistently show trail models priced 30–45% higher on average. Brands must justify this premium through demonstrable performance gains rather than relying on category halo effects. Third, the market is fragmenting around divergent performance expectations, with consumers balancing lightweight agility, protection, and durability in ways that vary by terrain, race format, and training intensity. Managing these competing demands without diluting brand identity or overextending product architectures remains a persistent strategic challenge.
Key Drivers Reshaping the Trail Running Shoes Market
Technological Innovation and Performance Engineering
Performance engineering has become the central battlefield in the trail segment, with brands investing in materials, midsole architectures, and traction systems that translate directly into competitive differentiation. The shift toward enhanced cushioning and traction was prominently visible at The Running Event in December 2025 in San Antonio, where more than thirty brands, including Nike, Hoka, On, La Sportiva, Salomon, Adidas-Terrex, Brooks, Arc'teryx, and Merrell, showcased 2026 trail running shoe models. Emerging labels such as Norda, Mount to Coast, Satisfy, Kiprun, and Speedland also demonstrated new approaches, indicating that innovation is no longer confined to incumbent players. Key themes included refined road-to-trail hybrids, gravel-specific options, and modular traction designs tuned for variable footing. The category’s technical trajectory aligns with consumer behavior: registered trail running event participation exceeded 2.8 million runners globally in 2023, up from 1.9 million in 2017, and more than 61% of trail runners prefer shoes weighing less than 320 grams per pair. At the same time, 4–6 mm lug depths have become standard for grip on uneven terrain, signaling a convergence around practical performance benchmarks rather than extreme specialization.
The innovation cycle is also being shaped by sustainability and material science. Recycled midsoles have reached durability levels exceeding 500 kilometers of trail use, matching conventional EVA performance standards. This development matters because it reduces the historical trade-off between environmental credentials and functional reliability. Brands that can integrate recycled content without compromising shock absorption, stability, or outsole longevity gain both margin protection and regulatory readiness. The engineering emphasis has moved from visible design cues to measurable performance attributes, and the winners are those who can prove that lighter weight, better traction, and durable cushioning can coexist in a single package.
Policy, Regulation, and Compliance Pressures
Regulatory and event-level compliance requirements are quietly reshaping demand patterns. Race organizers reported that 72% of trail running events now mandate specialized trail footwear for safety compliance, increasing category-specific adoption and reducing substitution from road or hybrid shoes in competitive settings. This requirement reinforces the category’s identity and supports pricing power for purpose-built models, but it also raises the stakes for product validation. Brands must ensure that traction, toe protection, and stability meet the expectations of event organizers and participants alike. At the same time, trade policy remains a significant exogenous risk. Tariff pressures on footwear imports from China have intensified, with brands such as Nike and Adidas, which assemble much of their inventory in Vietnam, exposed to steep new U.S. duties. The resulting cost escalation could compress promotional flexibility and force a reexamination of sourcing strategies, regional assembly footprints, and price architecture. For market participants, policy exposure is no longer a peripheral concern; it is a core planning variable that affects cost of goods, launch timing, and channel pricing.
Demand-Side Shifts and Consumer Behavior
Demand patterns are being reshaped by a broader migration toward outdoor and hybrid running formats. Trail running is no longer limited to ultramarathon specialists; it increasingly attracts everyday runners seeking varied terrain, reduced impact, and a break from paved surfaces. This expansion broadens the buyer base but also complicates product segmentation. Consumers want versatility without sacrificing technical capability, which has accelerated interest in road-to-trail hybrids and gravel-oriented designs. The preference for sub-320-gram shoes indicates that weight sensitivity remains high, yet the same consumers also expect adequate protection and grip. This tension has encouraged brands to develop tiered product architectures, with lightweight racing lines positioned alongside daily training and adventure-oriented models. The result is a market in which performance messaging must be precise, because generic outdoor positioning no longer captures the nuances of trail-specific needs.
Distribution behavior is also evolving, though the category remains heavily anchored in physical retail channels. Offline channels continue to dominate revenue share, reflecting the importance of fit, tactile assessment, and specialist retail relationships in a category where sizing, drop, and traction feel are difficult to evaluate remotely. Online channels are expanding, particularly for repeat buyers and performance-focused enthusiasts, but the category’s technical nature means that digital growth depends on better product guidance, fit tools, and return management. For brands, the strategic question is not whether to invest in digital, but how to design omnichannel experiences that preserve the tried-on confidence that drives trail purchases.
Supply Chain Complexity and Cost Structure
The cost structure of trail footwear is inherently more demanding than that of road running products. Reinforced uppers, protective rock plates, and aggressive outsole compounds increase manufacturing complexity by 18–25% relative to road shoes, and the resulting retail premiums reflect those inputs. This complexity has implications for scale economics, quality control, and inventory planning. Brands must balance the desire for specialized construction with the need to maintain efficient production runs and consistent material availability. The introduction of KEEN Footwear’s full-scale trail running development illustrates how established players are expanding into more technically demanding categories, following the July 2025 release of SEEK with additional models such as ROAM for technical mountain terrain. Such moves signal that even brands with heritage in hiking and outdoor footwear are treating trail running as a distinct growth avenue, not a side project. As more companies commit to dedicated trail programs, competition for skilled manufacturing capacity and specialized component supply will intensify.
Competitive Landscape and Leading Strategies
The market remains moderately concentrated, with the top three players holding approximately 55% of revenue and the top five reaching around 62%. This concentration suggests that scale, brand equity, and product pipeline maturity still confer meaningful advantages, but the presence of numerous differentiated competitors indicates that niche leadership and category-specific credibility can also drive share. The competitive field includes a mix of European engineering-led brands, American performance specialists, Japanese technical manufacturers, and Swiss cushioning innovators, each with distinct positioning.
Basketball Shoes Market
Salomon, headquartered in Annecy, France, continues to emphasize advanced rock plate technology, S/Lab racing lines, and a Vision recyclable sole collection for rugged trail performance. Its strategy blends race-proven credibility with sustainability-oriented material initiatives, allowing it to address both competitive runners and environmentally conscious buyers. HOKA, based in Vevey, Switzerland, has built recognition around maximalist cushioning through its Speedgoat, Challenger, and Tecton X series, with lightweight designs tuned for trail runners who prioritize impact management and stability on variable surfaces. Nike, from Beaverton, Oregon, leverages the ACG Pegasus Trail and Ultrafly series to offer versatile road-to-trail hybrids and high-performance cushioning, using its broader platform to connect trail offerings with mainstream running visibility. ASICS, in Kobe, Japan, focuses on Metafuji Trail and Trabuco models that emphasize lightweight construction and durability on technical trails, appealing to runners who value engineered precision. Adidas, in Herzogenaurach, Germany, supplies Terrex Agravic and Adizero Evo SL ATR for all-terrain adventure and mountain performance, extending its outdoor lineage into trail-specific applications. Brooks, in Seattle, Washington, develops Ghost Trail and Cascadia models with responsive cushioning and stability features for everyday trail use, anchoring its lineup in accessible performance. Saucony, in Lawrence, Massachusetts, concentrates on Peregrine and Xodus Ultra series for agility, shock absorption, and all-around trail versatility, balancing speed with protection. Topo Athletic, in Boulder, Colorado, offers Ultraventure and similar shoes with natural drop and versatile cushioning for everyday trail running, targeting runners who prefer a more natural foot position. Altra, in Logan, Utah, emphasizes Experience Wild 3 with zero-drop FootShape fit for natural foot positioning on trails, differentiating through fit philosophy. La Sportiva, in Ziano di Fiemme, Italy, provides Prodigio and Bushido models optimized for technical climbing and rocky trail conditions, leaning into mountaineering-adjacent credibility. Merrell, in Wolverhampton, United Kingdom, manufactures Eco-Trail and Moab series using recycled materials for sustainable outdoor performance, aligning durability with environmental messaging. On, in Zurich, Switzerland, creates Cloudsurfer and similar road-to-trail hybrid shoes with patented CloudTec cushioning for versatile trail use, extending its road heritage into hybrid applications. KEEN, in Venice, California, develops Wander and SEEK trail running shoes with durable, sustainable materials for all-day adventure hiking and trails, signaling a broader commitment to technical mountain terrain. Arc'teryx, in Vancouver, British Columbia, produces Sylan and Altamesa models with high-end materials and performance-focused designs for serious trail runners, positioning at the premium end of the market.
Leading strategies diverge along several axes. Some brands compete on race-proven performance and lightweight engineering, others on maximal cushioning and impact protection, and still others on hybrid versatility or fit philosophy. The common thread is precision: successful players articulate a clear performance promise and build product architectures that deliver it consistently. Differentiation also increasingly depends on material credibility, with recyclable soles, recycled midsoles, and durable sustainable constructions becoming part of the competitive conversation rather than optional add-ons.
The landscape is evolving through both consolidation and fragmentation. Scale players benefit from distribution reach, marketing leverage, and supply chain flexibility, while emerging brands gain traction by solving specific performance problems or serving underserved runner profiles. New entrants showcased at recent industry gatherings indicate that the barrier to credibility is shifting from brand heritage to demonstrable product performance. This dynamic suggests a market in which incumbents must continue to refresh their technical portfolios, while smaller players can capture attention by focusing on a well-defined use case, such as ultra-distance racing, technical mountain terrain, or natural-foot fit. The presence of multiple strong regional and specialty players also means that category leadership will be contested rather than dominated, and channel strategy will matter as much as product strategy.
Forward Outlook: Trends and Commercial Implications for 2026–2032
Over the next three to five years, three trends are likely to shape the market’s direction. First, hybrid and gravel-oriented designs will continue to gain relevance as runners seek footwear that performs across paved, unpaved, and technical surfaces without requiring multiple specialized pairs. This trend expands the addressable use case for trail-adjacent footwear and encourages brands to design for versatility without sacrificing grip or protection. The commercial opportunity lies in product lines that bridge road and trail expectations, supported by clear performance messaging and fit guidance. The risk is brand dilution if hybrid offerings blur category identity or underperform in technical conditions.
Second, sustainability and material performance will become increasingly intertwined. Recycled midsoles that meet durability benchmarks and recyclable sole initiatives will move from differentiation to expectation, especially as event compliance and consumer scrutiny intensify. Brands that can validate recycled content with measurable durability, such as the 500+ kilometer trail-use threshold, will be better positioned to maintain pricing power while meeting regulatory and reputational standards. The opportunity is to integrate sustainable materials into core performance lines rather than treating them as a separate eco tier. The risk is greenwashing exposure if sustainability claims are not backed by functional equivalence.
Third, trade policy and sourcing economics will remain a central strategic variable. Tariff exposure could elevate effective import costs and push retail pricing higher, forcing brands to reassess assembly locations, material sourcing, and price architecture. This creates both risk and opportunity. Companies that diversify sourcing, optimize regional assembly, and improve cost transparency will be better equipped to manage price increases without eroding demand. The commercial opportunity lies in supply chain resilience and disciplined price segmentation, while the risk is margin compression and consumer resistance if price increases outpace perceived value.
These trends connect directly to commercial opportunities. Brands that invest in hybrid architectures, validate sustainable materials with performance data, and build flexible sourcing strategies will be better positioned to defend margins and capture share as the market expands toward 13.52 billion U.S. dollars by 2032. At the same time, the category’s technical complexity means that product claims must be substantiated, because runners increasingly compare traction depth, weight, cushioning durability, and fit precision across brands. The companies that win will be those that align engineering, messaging, and channel experience around a coherent performance promise.
Sports Footwear Market
Actionable Recommendations for Decision-Makers
For manufacturers and brand leaders, the priority is to sharpen product architecture around clearly defined use cases while maintaining engineering credibility across the lineup. Develop tiered offerings that separate lightweight racing, daily training, and adventure or technical mountain applications, and ensure that each tier has a distinct performance story supported by traction, weight, and durability benchmarks. Invest in sustainable materials that meet functional thresholds, because recycled midsoles and recyclable sole initiatives now influence both compliance readiness and consumer perception. At the same time, reassess sourcing and assembly exposure in light of tariff dynamics, and model pricing scenarios that account for potential cost escalation without sacrificing competitiveness.
For investors and strategic planners, the market’s growth trajectory and moderate concentration suggest that category leadership will be earned through product differentiation and channel execution rather than scale alone. Evaluate companies based on their ability to deliver hybrid versatility, validate sustainable performance, and manage trade-policy exposure. Pay attention to brands that are expanding dedicated trail programs, because full-scale commitment signals confidence in category demand and can reshape competitive dynamics. Monitor event-level footwear mandates and participation trends, since compliance requirements and runner growth directly influence category-specific adoption and pricing resilience.
For retailers, procurement teams, and channel partners, the strategic focus should be on assortment clarity and fit guidance. Trail running shoes are not easily evaluated online without strong product information, so assortments should be organized by terrain type, weight class, and intended use rather than by brand alone. Inventory planning should reflect the category’s higher manufacturing complexity and premium pricing, balancing depth in proven models with selectivity in new launches. Partnerships with brands that provide clear performance differentiation and reliable material standards will reduce return risk and improve conversion.
The strategic value of detailed, up-to-date market intelligence is especially high in a category where performance claims, sourcing economics, and consumer preferences are evolving simultaneously. Granular segmentation, competitive benchmarking, and scenario analysis can help decision-makers move from broad trends to specific product, pricing, and channel choices. For those seeking deeper segmentation data, regional breakdowns, and customized strategic recommendations, the full PW Consulting research report provides the detailed framework needed to translate market dynamics into executable plans.
For detailed analysis of this topic, please visit the official page: Trail Running Shoes Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Car Batteries Market Analysis: Why 5.75% CAGR and Regional Shifts Redefine Growth
By pmarketresearch, 2026-09-21
The Car Batteries Market: Navigating Transition, Value Chains, and Strategic Opportunities
The automotive energy storage landscape is entering a decisive inflection point. Measured in billions of U.S. dollars, the total market expanded from roughly $27.85 billion in 2020 to $35.4 billion in 2025, reflecting a compound annual growth rate of 5.75 percent through 2032. The trajectory is not a straight line. After a dip in 2022, volumes recovered through 2023 and 2024, and the forecast path shows steady expansion with a modest plateau near 2029 before renewed acceleration. This pattern matters because it reveals a market that is maturing in conventional segments while reallocating capital toward new chemistries, regional supply strategies, and application-specific designs. For executives and investors, the central question is no longer whether the market will grow, but where margin, scale, and resilience will concentrate over the next cycle.
Three structural challenges define the current turning point. First, the industry is balancing a dominant incumbent chemistry with a faster-growing alternative that carries different economics, sourcing risks, and performance expectations. Second, regional trade and resource policies are reshaping cost structures and forcing companies to rethink where they source, assemble, and sell. Third, the application mix is shifting as original equipment demand evolves alongside a large and still-growing replacement segment, creating diverging requirements for durability, service life, and total cost of ownership. These forces interact rather than operate in isolation, which is why portfolio strategy and geographic positioning now matter as much as unit economics.
PW Consulting
Key Drivers Reshaping the Market
Technology Innovation and Product Differentiation
Innovation is no longer confined to a single chemistry roadmap. Advanced lead-acid designs continue to improve performance in start-stop, micro-hybrid, and certain backup roles, while lithium-ion platforms extend their footprint in applications that reward higher energy density and longer cycle life. The practical impact is a widening performance envelope across the product spectrum. Manufacturers are differentiating through tighter tolerances, improved thermal behavior, and application-tuned durability rather than competing solely on price. This matters for buyers because the selection criterion is shifting from price per unit to risk-adjusted service life, integration complexity, and warranty exposure. For producers, the strategic prize is to align product architecture with the duty cycle of each application, capturing premium segments where reliability and consistency justify higher value.
Policy and Regulatory Environment
Regulation is becoming a first-order driver of sourcing, pricing, and competitive positioning. Trade actions and export controls are altering the cost baseline for key materials and components, while regional content expectations are pushing development of more localized supply chains. Recent movements in trade policy illustrate the point: tariffs on selected graphite imports into the United States and adjustments to export controls on battery-related components and materials in other major economies have added new layers of cost and compliance. These measures do more than move prices in the short term. They influence where capacity is built, which suppliers are viable across regions, and how quickly product specifications must adapt to meet local content or traceability expectations. The durable takeaway is that regulatory trajectory now belongs in the core of product planning, not in a separate compliance function.
Demand-Side Shifts in Consumer and Fleet Behavior
Demand patterns are bifurcating. A substantial portion of activity continues to come from replacement and aftermarket needs, where fleet managers, service networks, and individual consumers prioritize availability, interchangeability, and predictable cost. At the same time, original equipment demand is being reshaped by vehicle electrical architectures that place different burdens on energy storage, especially in hybrids and vehicles with higher accessory loads. The practical result is that volume growth is being accompanied by more demanding specifications in a subset of applications, while the replacement market keeps the baseline stable. For commercial buyers, the implication is to manage two different procurement logics at once: one optimized for uptime and service simplicity, the other optimized for integration and performance over a longer design life.
Supply Chain and Cost Structure Dynamics
Material prices and sourcing options are reintroducing volatility into cost planning. Spot prices for lithium carbonate, for example, moved sharply lower through mid-2025 before rebounding to a materially higher range by early 2026, a swing that affects input planning for lithium-based products and influences the relative economics of different chemistries. At the same time, cobalt availability has come under tighter constraints, with export measures converting into quota systems that contributed to price increases over the course of the year. These dynamics are not abstract. They change the relative attractiveness of design choices, the timing of capacity commitments, and the value of supplier relationships that offer flexibility or alternative material pathways. Companies that treat procurement as a strategic lever rather than a transactional function are better positioned to absorb swings without eroding margins.
Competitive Landscape and Leading Strategies
Incumbents With Scale and Application Focus
The market is led by a group of established manufacturers with deep application knowledge and broad distribution. East Penn Manufacturing operates one of the largest single-site lead-acid production platforms, with product lines spanning flooded, AGM, and gel technologies for automotive use, including start-stop systems. Its recent expansion of EHP and Extreme Power AGM automotive lines, along with a dedicated EV and hybrid battery navigation section on its website, signals an effort to make advanced lead-acid options easier to identify and specify as vehicle electrification needs broaden. GS Yuasa International remains a major producer of high-performance lead-acid batteries for original equipment and aftermarket channels, with a long-standing emphasis on reliability and application fit. Exide Industries continues to scale its position across passenger cars and commercial vehicles, leveraging a broad manufacturing footprint and strong regional reach. Together, these companies illustrate how incumbents defend their position by combining scale, service networks, and product breadth rather than relying on a single technology narrative.
Specialists and Integrated Suppliers Extending Their Reach
A second layer of competitors competes through specialization and integration. Kung Long Batteries focuses on lead-acid products for automotive, motorcycle, and marine use, with manufacturing operations structured to support export-oriented volume. Furukawa Battery Co. has built recognition around advanced lead-acid technologies, including UltraBattery and AGM variants for starting and hybrid applications, positioning itself where performance under partial state-of-charge and cycling matters. Clarios operates as a global automotive battery producer with well-known consumer and retail brands, giving it strong visibility in replacement channels. Robert Bosch and Denso Corporation bring complementary strength through components and thermal management integration, linking battery supply to broader vehicle electrical and thermal systems. EnerSys rounds out the field with automotive and industrial battery offerings, including AGM and flooded types, where stationary and commercial demands intersect with automotive requirements. The differentiating theme among these players is the ability to serve specific application needs or to integrate battery hardware into wider system solutions, rather than competing purely on commodity volume.
Battery Market
Market Structure and Evolution Pathways
Concentration in the market is moderate. The three largest firms account for roughly 37.4 percent of revenue, while the top five approach 51.2 percent, leaving meaningful room for regional leaders, specialists, and brand-driven retail channels. This structure shapes strategy in two ways. First, it allows differentiated players to win in niches by solving specific performance, service, or integration problems. Second, it creates pressure for scale players to defend share through cost discipline, distribution strength, and portfolio breadth. The likely evolution is a combination of consolidation at the top, continued regional strength below the leaders, and selective entry by new participants where a clear application advantage or supply advantage can be established quickly. For buyers and investors, the important signal is that leadership will increasingly be measured by the ability to manage technology transitions, regional sourcing, and application-specific value rather than by volume alone.
Future Trends and Commercial Implications
Chemstry Coexistence and Application-Specific Design
Over the next three to five years, the market is likely to see continued coexistence of advanced lead-acid and lithium-ion solutions, with the split shaped by application requirements, total cost of ownership, and regional economics rather than by a single replacement curve. This creates clear commercial opportunities for suppliers that can engineer for specific duty cycles, demonstrate reliability in service, and simplify specification for buyers. The opportunity is not simply to offer both chemistries, but to reduce the decision burden for customers by matching product architecture to real-world use, backing claims with consistent quality, and aligning warranty and support structures accordingly. The principal risk is misjudging the pace of adoption in applications where expectations are rising faster than cost structures can justify, which can leave inventory or positioning misaligned with demand.
Regionalization of Supply and Sourcing Flexibility
Trade policy and resource constraints are accelerating a shift toward more regionally aware sourcing and, in some cases, more localized assembly or component supply. The commercial implication is twofold. Companies can gain from nearer-term supply resilience and improved alignment with regional content expectations, but they must also absorb higher coordination costs and potentially higher input prices in the short run. The strategic opportunity lies in building a flexible supplier base, qualifying alternative materials or sub-suppliers where feasible, and designing products that can tolerate modest specification changes without compromising performance. The risk is overcommitting to a single geography or a single sourcing route in a period when trade measures and export controls can change quickly, as seen with graphite tariffs and adjustments to battery-related export controls.
Value Migration Toward Integration and After-Sales Reliability
As vehicle electrical systems become more complex and replacement demand remains large, value is migrating toward providers that can reduce downtime, simplify servicing, and deliver consistent performance across a wide installed base. For manufacturers, this means investing in quality consistency, traceability, and support models that matter to fleet operators and service networks. For channel and retail partners, it means winning on availability, brand trust, and clear differentiation in product tiers. For OEMs and Tier-1 integrators, it means treating energy storage as part of a broader system where thermal behavior, charging profiles, and service life interact with vehicle design. The risk in this trend is underinvestment in the service and reliability dimension, which can erode margin even when unit sales grow, particularly in markets where replacement activity remains the backbone of demand.
Actionable Guidance for Decision Makers
For manufacturers, the priority is to align product roadmaps with application realities and to build sourcing flexibility into the cost model. That means mapping each product line to the duty cycle it is designed for, stress-testing specifications against material price volatility, and maintaining qualified alternatives for critical inputs where possible. It also means treating advanced lead-acid and lithium-ion portfolios as complementary tools rather than competing narratives, using each where its economics and performance profile are strongest. Companies that can reduce specification friction for buyers and demonstrate dependable service life will capture more value than those competing on unit price alone.
Primary Battery Market
For investors, the central task is to assess which players are positioned to earn durable margins through the current transition. Look for evidence of application-specific differentiation, distribution strength in replacement channels, and supply strategies that reduce exposure to concentrated sourcing or abrupt trade changes. Favor organizations that combine scale with clear technical focus, because that combination tends to preserve pricing power while allowing selective growth in higher-value segments. Be cautious about assumptions that any single chemistry shift will simplify the competitive field; the more likely outcome is a wider, more application-diverse market in which execution quality determines who captures premium positioning.
For procurement and supply-chain leaders, the actionable step is to manage the baseline and the innovation path at the same time. Maintain a resilient core supply arrangement for high-volume replacement needs, where availability and interchangeability are paramount, while establishing a separate evaluation track for new specifications tied to OEM or hybrid applications. Build visibility into input price cycles and policy developments so that purchasing decisions do not lag behind market changes. Where possible, structure contracts and supplier relationships to preserve optionality, because the next few years are likely to bring further swings in material costs and regional trade conditions rather than a return to a stable baseline.
The strategic picture is clear enough to act on, but the granular choices depend on segment-specific data, regional cost structures, and the timing of policy and material movements. Detailed segmentation, regional revenue splits, application-level volumes, and company-level benchmarking provide the precision needed to convert these trends into concrete plans. For teams that require that level of detail, the full PW Consulting report on the car batteries market offers deeper figures, scenario breakdowns, and customized recommendations aligned to specific business models and geographies.
For detailed analysis of this topic, please visit the official page: Car Batteries Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Navigating the Laboratory Furniture Market: Strategic Trends and Commercial Opportunities Through 2032
The global laboratory furniture market has transitioned from a cyclical, project-driven sector to a structurally expanding industry shaped by scientific modernization, regulatory tightening, and supply chain recalibration. Valued at approximately 1.8 billion USD in 2025, the market has expanded from roughly 1.34 billion USD in 2020, reflecting a compound annual growth rate of 4.3 percent through 2032. While short-term fluctuations are inevitable in capital-intensive laboratory build-outs, the underlying trajectory points toward sustained demand as research institutions, clinical facilities, and educational laboratories retrofit aging infrastructure and accommodate new experimental workflows. For executives and investors, the opportunity lies not in chasing headline growth figures, but in understanding where segmentation, compliance, and manufacturing capabilities intersect to create defensible positioning.
Market Snapshot and Structural Headwinds
The market’s growth over the past half-decade has been underpinned by steady capital deployment in life sciences, materials research, and diagnostic capacity. Europe and North America continue to anchor the largest revenue pools, reflecting mature research ecosystems and ongoing public and private investment in laboratory modernization. Asia Pacific has emerged as a high-growth corridor, driven by expanding university infrastructure, pharmaceutical development hubs, and localized manufacturing of laboratory equipment. Latin America and the Middle East and Africa represent smaller but increasingly meaningful demand pockets, often tied to bilateral research initiatives, hospital network expansions, and emerging biotech clusters.
Despite the positive top-line trajectory, several structural challenges are reshaping how manufacturers, integrators, and buyers approach laboratory furniture projects.
Supply Chain Complexity and Labor Cost Pressures
The sector has moved beyond the acute disruptions of earlier years, but supply chain volatility remains embedded in procurement planning. Lead times for steel, engineered plastics, coatings, and specialized hardware continue to fluctuate with regional manufacturing capacity, logistics constraints, and input cost swings. Alongside this, labor costs for fabrication, assembly, and on-site installation have risen, compressing margins for vendors that rely on labor-intensive customization without corresponding productivity gains. Kewaunee Scientific Corporation highlighted these dynamics in its recent reporting, noting that supply chain complexity and labor cost pressures are ongoing challenges across the laboratory furniture segment. For operators, the implication is clear: scale alone is no longer sufficient. Margins increasingly depend on modular standardization, predictable sourcing, and efficient project execution.
School Furniture Market
Regulatory and Standards Acceleration
A second major shift is the rapid evolution of design and installation standards. Standards bodies and industry groups are moving from advisory guidance to more formalized expectations around laboratory furniture safety, chemical resistance, and ergonomic integration. The publication of EN 14056-1:2025 for installation and design of laboratory benches, associated storage units, and service provision marked a notable step in codifying expectations across Europe. In parallel, SIST EN 14056-1:2026 extended similar design and installation considerations to biology, chemistry, and physics laboratories. More recently, SEFA has been developing standards for lab-grade flooring and lab-grade washers, with committee work planned to advance into walls and ceilings. This expanding standards ecosystem raises the bar for compliance, documentation, and integration, particularly for international projects where multiple regional codes intersect.
Demand Fragmentation Across Laboratory Types
Laboratory furniture is no longer a homogeneous category. Research and development laboratories continue to drive a significant share of demand, but the market is increasingly shaped by divergent requirements across clinical diagnostics, academic environments, and specialized institutional use. R&D environments prioritize modularity, chemical resistance, and integration with equipment-centric workflows. Clinical and medical laboratories place heavier emphasis on cleanability, contamination control, and regulatory-aligned finishes. Educational laboratories demand durability, flexibility, and cost predictability across high-use cycles. This fragmentation rewards manufacturers that can align product architecture to distinct use cases rather than offering one-size-fits-all casework and bench solutions.
Key Demand Drivers Reshaping the Market
Technical Innovation in Modular and Material Systems
Material and modularity innovation remains one of the most direct levers for competitive differentiation. Manufacturers are expanding beyond traditional steel and wood casework toward hybrid configurations that combine durability, chemical resistance, and cleaner finishes for modern laboratory protocols. The September 2025 launch of a new modular laboratory furniture range featuring powder-coated options alongside stainless-steel models illustrated how suppliers are broadening their material toolkits to serve varied hygiene, corrosion, and aesthetics requirements. At the same time, modular bench systems, mobile lab configurations, and integrated storage are gaining traction because they reduce installation complexity and support reconfiguration as research priorities shift. For buyers, modularity is not merely a convenience; it is a lifecycle strategy that lowers total cost of ownership in environments where experimental layouts and equipment footprints change frequently.
Regulatory Alignment as a Market Access Driver
Regulatory and standards activity is functioning as both a constraint and a catalyst. On one hand, tighter expectations around installation design, storage safety, and surface compatibility increase verification burdens and can slow project timelines if documentation is incomplete. On the other hand, standardized expectations create clearer pathways for vendors that invest early in compliance-ready product lines and installation documentation. The EN 14056-1 framework, together with emerging SEFA work on lab-grade building components, signals a future where laboratory environments are evaluated more holistically, with furniture, casework, flooring, and related systems treated as part of an integrated compliance picture. Companies that anticipate these expectations can convert regulatory maturity into a procurement advantage, particularly in public tenders, institutional projects, and cross-border initiatives where standardization reduces approval friction.
Office Furniture Market
Shifting End-User Expectations and Infrastructure Modernization
Demand-side behavior is changing as laboratory operators prioritize flexibility, longevity, and integration over lowest initial price. Research organizations are increasingly weighing furniture selections against long-term reconfiguration needs, equipment integration, and maintenance burdens. Clinical laboratories and hospital networks are upgrading from legacy casework to systems designed for stricter cleaning protocols and more durable finishes. Educational institutions are balancing budget constraints with the need for adaptable spaces that can support evolving curricula and safety requirements. This behavior shift is pushing the market toward higher-specification systems in selected applications, even as price sensitivity persists in broader institutional spending. The strategic implication is that value is increasingly defined by how well furniture supports operational continuity, not simply by upfront unit economics.
Cost Structure Realignment and Regional Manufacturing Dynamics
Cost structures across the laboratory furniture market are being reshaped by a combination of input pricing, fabrication methods, and regional sourcing strategies. In mature markets, the pressure on labor-intensive assembly is encouraging greater use of pre-engineered components, standardized sub-assemblies, and improved logistics planning. In faster-growing regions, localized production and regional distribution hubs are becoming more relevant to reduce lead times and improve responsiveness to project-based demand. This realignment favors companies that can balance global product consistency with regional execution capability. It also creates opportunities for partners that can support installation, training, and post-deployment service without relying entirely on centralized manufacturing models.
Competitive Landscape and Strategic Positioning
The competitive environment is characterized by a moderate level of concentration, with the top three firms representing roughly 21 percent of the market and the top five approximately 26 percent. This leaves meaningful room for mid-tier specialists, regional players, and application-focused manufacturers to compete on differentiation rather than scale alone. The field includes established North American and European producers with broad laboratory furniture portfolios, alongside specialized companies targeting specific product categories such as casework, storage cabinets, chemical-resistant units, ergonomic seating, and integrated lab infrastructure.
Established Incumbents and Capability Clustering
Several incumbent manufacturers have built their market positions by clustering capabilities around complementary product families. Kewaunee Scientific Corporation has centered its offering on steel and wood casework, modular benches, and fume hoods, giving it a recognizable footprint in core laboratory infrastructure. Labconco Corporation has emphasized custom laboratory furniture, including casework, storage systems, and integrated modular components, positioning itself around tailored lab configuration. Esco Technologies, Inc. provides laboratory casework, benches, and full furniture systems for research facilities, aligning product breadth with project-scale demand. NuAire, Inc. manufactures laboratory furniture components and integrated lab infrastructure solutions, while Diversified Casework, Institutional Casework, and Mott Manufacturing Corp. each contribute specialized casework and modular system expertise across institutional and research contexts.
In Europe, Waldner Laboreinrichtungen SE & Co. KG has developed a comprehensive laboratory furniture system portfolio encompassing fume hoods and mobile labs, supporting clients that need coordinated lab environments rather than isolated furniture purchases. Asecos GmbH focuses on laboratory furniture including storage cabinets and chemical-resistant units, a specialization that maps well to safety-intensive applications. BIMOS GmbH differentiates through ergonomic laboratory furniture, seating, and complete work systems, targeting human-centered lab design. Together, these profiles show a market where competitive advantage is often built from product depth, application fit, and integration capability rather than from price alone.
PW Consulting Health Care Research Center
Strategic Differentiation and Event-Driven Visibility
Trade participation and product launches are increasingly used to signal capability expansion and reinforce market presence. Kewaunee Scientific Corporation and Waldner both used analytica 2026 in Munich to exhibit laboratory infrastructure and furniture solutions, including fume hoods and mobile labs, reinforcing their positioning in integrated lab environments. In a different but related move, Teknomek Ltd expanded its modular laboratory furniture range with powder-coated options alongside stainless-steel models, signaling a broader material strategy. These activities matter because laboratory furniture purchasing is highly project- and specification-driven; visibility at industry events and the introduction of new material or modularity options can shape short-list decisions well before procurement cycles close.
Consolidation, Fragmentation, and New Entrant Dynamics
The market is likely to continue evolving along two parallel tracks. In one direction, larger players may pursue selective consolidation, channel partnerships, or capability acquisitions to broaden geographic reach, strengthen installation and service networks, or add complementary product lines such as integrated storage, ergonomic seating, or specialized containment-related furniture. In the other direction, application-specific fragmentation will persist, with niche players competing around chemical resistance, cleanability, modularity, or ergonomics in ways that matter to particular end users. New entrants can still gain traction by targeting underserved regional markets or specialized laboratory types, but sustained success will depend on demonstrating measurable advantages in compliance readiness, lead-time reliability, and installation efficiency. Pure commodity positioning is increasingly vulnerable, especially as standards and end-user expectations raise the baseline for acceptable performance.
Forecast Pathways and Commercial Implications
Looking ahead through the next three to five years, several trends are likely to shape both market growth and competitive dynamics.
Standards-Integrated Product Architecture
As standards for laboratory benches, storage, and related building components become more entrenched, product architecture will increasingly need to reflect compliance, documentation, and integration requirements from the outset. Manufacturers that design for these expectations can shorten approval cycles, reduce retrofit risk, and position themselves favorably in regulated or publicly funded environments. For procurement teams, this trend raises the importance of evaluating not just furniture performance, but also the quality of installation guidance, certification documentation, and compatibility with adjacent lab-grade systems.
Modularity as a Baseline Expectation
Modular design is poised to move from a premium feature to a baseline expectation in many laboratory segments. Research teams, in particular, value the ability to reconfigure benches, casework, and service access as experimental requirements evolve. Mobile labs and reconfigurable systems also appeal to organizations managing multiple sites or temporary project spaces. The commercial opportunity lies in offering modular systems that still meet durability, safety, and serviceability requirements without becoming overly customized or cost-prohibitive. Success will depend on standard engineering, repeatable installation patterns, and clear upgrade paths.
Regional Growth and Localized Execution
Growth is expected to remain strongest in regions where laboratory infrastructure expansion and modernization are converging, including parts of Asia Pacific, while mature markets will likely see steadier replacement and upgrade demand. In both cases, localized execution capability will matter more than in the past. Buyers increasingly care about predictable lead times, on-site support, spare parts availability, and regional accountability. Companies that pair consistent product standards with strong local service and installation capacity are better positioned to win repeat business and institutional relationships. A key uncertainty is the pace of input cost normalization and labor availability; if cost pressures persist, price-sensitive segments may delay projects or shift toward simpler specifications, while higher-value applications may continue upgrading regardless.
Strategic Guidance for Decision Makers
The most actionable implications vary by role, but several themes apply across the board.
For Manufacturers and Integrators
- Prioritize modular standardization and material diversity that align with real installation and cleaning requirements, rather than expanding product breadth for its own sake.
- Invest in documentation, installation clarity, and compatibility with emerging lab-grade standards so that projects move through approval and compliance steps more efficiently.
- Strengthen regional execution capability, including installation support and post-deployment service, to reduce the operational risks that erode margin in project-based businesses.
For Investors and Strategic Planners
- Evaluate exposure to standards-driven and compliance-heavy segments, where early investment in certified or certification-ready systems can create durable procurement advantages.
- Look for business models that combine product repeatability with reliable service and installation capacity, since these characteristics support margin stability in a fragmented market.
- Monitor regional demand shifts and localized production strategies, as sourcing and execution geography will increasingly influence lead-time reliability and customer retention.
For Procurement and Facility Decision Makers
- Move beyond unit price comparisons and assess total lifecycle value, including reconfigurability, cleaning and maintenance burdens, and compatibility with adjacent lab infrastructure.
- Treat standards readiness and documentation quality as selection criteria, especially for regulated, multi-site, or publicly funded projects where approval friction can delay delivery.
- Define specification requirements around actual operating conditions rather than generic categories, since laboratory furniture performance varies significantly across R&D, clinical, educational, and institutional use cases.
Conclusion
The laboratory furniture market is moving toward a more standards-aware, modular, and operationally demanding environment. Growth at a 4.3 percent CAGR through 2032 reflects durable demand across research, clinical, educational, and institutional settings, but the profitable opportunity is concentrated in manufacturers and integrators that can align product architecture, compliance readiness, and regional execution with distinct laboratory workflows. As standards expand beyond furniture into broader lab-grade systems and end users increasingly prioritize lifecycle flexibility, the winners will be those that treat laboratory furniture as part of an integrated operational strategy rather than a stand-alone purchase. Detailed segmentation data, application-level demand patterns, and company-specific positioning can sharpen decision making further, and organizations seeking deeper commercial intelligence may find value in consulting the full research report for more granular market detail and tailored guidance.
For detailed analysis of this topic, please visit the official page: Laboratory Furniture Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Auto Dealer Software Market: How 7.8% CAGR and Web Platforms Reshape Growth
By pmarketresearch, 2026-09-21
The Auto Dealer Software Market: Strategic Trends and Commercial Opportunities Through 2032
The auto dealer software market has entered a phase of structural transformation, driven by technological maturation, regulatory pressure, and shifting dealership economics. Measured in USD millions, the market expanded from 143.5 in 2020 to approximately 190.8 in 2025, reflecting a compound annual growth rate of 7.8 percent across the 2020–2025 historical window. Forward projections indicate continued expansion, with revenue reaching 200.7 in 2026 and progressing toward 309.2 by 2032. This trajectory signals more than incremental growth; it reflects a market where software is no longer a back-office utility but a core operational and competitive layer for dealership networks.
Market concentration remains high, with the top three providers capturing roughly 68.5 percent of overall revenue and the top five accounting for approximately 75.0 percent. Such concentration suggests that scale, integration depth, and compliance infrastructure create durable moats, while also leaving meaningful room for specialized entrants targeting specific dealership segments or workflow niches. The revenue split across software types shows dealer management systems commanding the largest share, followed by CRM and marketing platforms, with additional categories rounding out the portfolio. Deployment models reveal a clear tilt toward web-based solutions, which now represent the majority of market value, while installed software maintains a substantial but gradually declining footprint. Regional allocations point to North America as the largest revenue base, with Europe and Asia Pacific forming the next tier of meaningful demand centers, and Latin America along with the Middle East and Africa representing faster-growing but smaller absolute markets.
These headline trajectories mask underlying friction. Dealerships and software providers are navigating a landscape where legacy operational assumptions are colliding with cloud economics, regulatory scrutiny, and changing consumer expectations. The following sections break down the core challenges, demand drivers, competitive positioning, and forward-looking signals that matter for executives planning technology roadmaps, capital allocation, or market entry strategies.
Market Conditions and Critical Inflection Points
The current market environment is shaped by a combination of steady top-line growth and intensifying operational pressure. Three issues stand out as particularly consequential for how the market will evolve over the next several years.
First, cybersecurity and operational resilience have moved from a compliance checkbox to a strategic imperative. A major disruption in mid-2024 involving a leading DMS provider accelerated industry-wide reassessment of backup systems, access controls, and incident response planning. Providers have since increased investment in SOC 2-aligned platforms and AI-assisted fraud detection, while dealership groups have grown more cautious about single-vendor dependency and data exposure. This shift is not merely defensive; it is reshaping procurement standards, contract terms, and the value proposition of platforms that can demonstrate stronger security and continuity guarantees.
Second, data privacy expectations and compliance requirements are increasing the cost and complexity of software deployment. Cloud-native systems require ongoing alignment with evolving consumer information handling rules, particularly as platforms integrate more deeply with financing, marketing, and OEM data flows. For dealership operators, this creates a tension between the desire for streamlined digital experiences and the need to maintain rigorous consent management, retention controls, and audit readiness. For software vendors, it raises the bar for product design, documentation, and continuous updates, especially in markets where regulatory expectations differ by region or customer segment.
Third, labor economics are altering the calculus of dealership operations. DMS platforms that incorporate AI automation can reduce manual data entry and F&I processing time by up to 50 percent, easing reliance on specialized staffing for routine workflows. This is attractive in an environment where dealerships face persistent pressure on per-unit profitability and operational consistency. At the same time, automation creates new expectations: staff must be retrained, workflows must be redesigned, and the value of software shifts from record-keeping toward decision support and exception handling. The dealerships that benefit most are those that treat automation as a process redesign opportunity rather than a simple cost-reduction tool.
Taken together, these inflection points suggest a market that is expanding not just in size but in strategic importance. Software choices increasingly affect compliance posture, operational resilience, staffing models, and customer experience quality. That makes technology decisions harder to reverse and more consequential for long-term performance.
Core Drivers Reshaping the Market
Several interconnected forces are accelerating adoption and redefining what software must deliver to remain competitive.
Insurance Agency Software Market
Technological innovation continues to be the most visible driver. AI-enabled analytics, workflow automation, and modular integration architectures are becoming baseline expectations rather than differentiators. The industry context indicates that open integrations and API partnerships with lenders and OEMs have expanded the ecosystem around dealer platforms, but they have also increased licensing costs for third-party connectors in integrated DMS deployments. This dynamic is pushing providers to balance flexibility with cost control, and it is encouraging dealership groups to evaluate total cost of ownership rather than focusing narrowly on upfront subscription pricing. Recent platform launches have emphasized unified customer data and real-time insights, reflecting a broader shift from siloed records to connected intelligence. For example, a major provider launched a customer data platform in early 2026 designed to unify fragmented customer information, followed shortly by a foundations suite offered with free implementation for existing DMS renewals. These moves illustrate how vendors are using data unification and onboarding incentives to deepen adoption and reduce switching friction.
Policy and regulatory conditions are reinforcing this technological push. Cybersecurity expectations have tightened across the sector, and industry-wide investment in enhanced defenses following major disruptions has raised annual compliance expenditures for providers. In parallel, data privacy compliance demands continuous alignment for cloud-native systems handling consumer information. The result is a market where security and privacy are competitive factors: platforms that can demonstrate robust controls, transparent data practices, and predictable update cycles gain credibility with larger dealership groups and institutional partners. Regulatory pressure also indirectly benefits more mature providers, since compliance overhead can be harder for smaller players to absorb at scale.
Demand-side behavior is changing as well. Consumers and corporate buyers increasingly expect seamless digital interactions across the sales, service, and financing journey, even when the final transaction still involves in-person or hybrid steps. Dealerships are responding by investing in CRM and marketing software that complements the core DMS, using digital tools to improve lead handling, follow-up consistency, and retention marketing. Industry context shows AI-enabled tools expanding into areas such as driver’s license validation and fraud detection within F&I processes, signaling a broader expectation that software should reduce risk and improve speed without adding administrative burden. For dealerships, the strategic question is how to connect front-end digital engagement with back-end operational systems without creating new data silos or compliance gaps.
Cost structures and operating models are also in flux. Automation is reducing certain manual workloads, but API licensing, compliance, and integration complexity can offset some of those gains. At the same time, leadership changes and expansion initiatives among key vendors indicate that firms are betting on growth beyond their existing customer bases, often by broadening product scope, improving usability, or strengthening partner ecosystems. These developments suggest that the market is moving toward a more layered value proposition: core DMS functionality remains essential, but differentiation increasingly comes from analytics, automation, security, and ecosystem connectivity.
Competitive Landscape and Leading Strategies
The competitive environment is defined by a small set of scaled incumbents and a broader field of specialized and emerging providers. The leading companies share a common anchor in dealer management systems, but they differ in architecture, ecosystem strategy, and target customer segments.
CDK Global has reinforced its position through a combination of platform expansion, data unification, and adoption incentives. Its integrated dealership experience platform spans core sales, service, parts, finance, and accounting modules, with AI-driven analytics and open integrations. Recent activity includes the launch of a customer data platform for real-time insights, the introduction of a foundations suite with free implementation for existing DMS renewals, and a major industry event showcasing AI enhancements and expanded payment-related capabilities. These moves point to a strategy centered on deepening existing relationships, reducing churn risk, and making the platform more central to dealership data and workflow decisions.
Reynolds and Reynolds continues to compete through a comprehensive retail management system that covers inventory, customer management, and compliance tools. Its positioning emphasizes operational breadth and dealership-wide process support, which appeals to groups seeking a unified operational backbone. Dealertrack has carved out a strong niche around cloud-based DMS with a focus on F&I, digital contracting, and AI automation for deal closing and fraud reduction. Its recent introduction of AI-enabled driver’s license validation and expanded fraud detection for F&I processes underscores a strategy that ties technology directly to risk management and transaction efficiency. Cox Automotive, through its connected offerings, emphasizes AI-powered workflows and digital retailing tools, aligning DMS components with broader marketplace and retail technology ecosystems.
A second layer of competitors targets usability, small-to-medium dealer segments, and customer-service-centric relationships. Auto/Mate supplies a DMS focused on streamlined sales, service, finance, and accounting, with an emphasis on free upgrades and service responsiveness. Autosoft provides dedicated DMS platforms that stress ease of use, 360-degree dealership visibility, and automation for smaller dealers, and it recently appointed a new CEO to drive expansion beyond its current customer base. DealerSocket partners with Auto/Mate to offer connected DMS solutions, pairing integration with award-winning support and ongoing enhancements. Dominion Dealer Solutions supplies a VUE DMS aimed at comprehensive dealership management, including inventory and operational tracking. This segment of the market is more fragmented, and its growth often depends on delivering clear operational simplicity, responsive support, and cost-effective deployment models.
The market is evolving along three overlapping directions. Consolidation remains attractive at the top, where scale in data, compliance, and integrations strengthens competitive positioning. Differentiation is intensifying around AI, automation, security, and ecosystem breadth, with vendors competing to prove that their platforms can reduce friction in both routine operations and high-stakes processes like F&I. At the same time, new entrants and partner-led models continue to emerge in niches such as usability-focused DMS, specialized CRM and marketing layers, and region-specific compliance or deployment requirements. The practical implication is that buyers face a trade-off between the stability and depth of large platforms and the agility or specialization of smaller offerings, while vendors must decide whether to compete on breadth, depth, ecosystem access, or service quality.
PW Consulting Information & Electronics Research Center
Forward Outlook: Trends and Commercial Implications
Looking ahead to the 2026–2032 period, several trends are likely to shape both market growth and opportunity allocation.
A first trend is the shift from modular software to integrated intelligence. As customer data platforms, AI analytics, and automated workflows become more embedded in dealer systems, the value of software will increasingly depend on how well it connects data across sales, service, parts, finance, and marketing. This creates opportunities for providers that can reduce fragmentation while preserving flexibility through open integrations. It also raises the stakes for dealerships that rely on patchwork systems, since disconnected data limits the benefits of automation and makes compliance and reporting more burdensome.
A second trend is the continued rise of cloud-native, web-based deployment as the dominant operating model. Web-based solutions already represent the larger share of market value, and their advantages in updates, remote access, integration, and scalability reinforce that position. The commercial implication is that procurement will increasingly favor platforms with strong security credentials, predictable data-handling practices, and clear upgrade paths. It also means that providers must manage ongoing compliance and integration costs, including the rising expense of third-party connectors and licensing arrangements with lenders and OEMs.
A third trend is the growing strategic role of automation in dealership economics. Reducing manual processing in F&I, inventory handling, and customer follow-up can meaningfully lower specialized staffing needs and improve consistency, but the payoff depends on workflow redesign and change management. The opportunity lies not just in adopting automation tools, but in reorganizing processes so that staff can focus on exception handling, relationship management, and higher-value decisions. The risk is that automation is treated as a plug-in cost saver without rethinking the surrounding operating model, which can blunt benefits and create new bottlenecks.
These trends carry uncertainty. Cybersecurity and data privacy requirements will continue to evolve, and compliance costs may rise further, particularly for providers operating across multiple jurisdictions. API licensing and integration expenses could pressure margins or slow ecosystem expansion if connector costs become a barrier. In addition, market concentration gives leading vendors significant influence over standards and pricing, which may limit the room for smaller players unless they serve clearly defined segments or offer distinctive workflow advantages. For investors and corporate strategists, the key is to distinguish between durable structural demand for connected, secure, automated dealer software and short-lived features that may be quickly commoditized.
Action Guidance for Decision-Makers
The strategic implications vary by role, but several priorities apply across the market.
Real Estate Software Market
For manufacturers and OEM-affiliated teams, the priority is to align technology partnerships with the broader retail experience strategy. As dealership software becomes more central to data flow, digital retailing, and compliance, OEM relationships with DMS and adjacent platforms can influence everything from inventory visibility to customer journey consistency. It is worth evaluating how open integrations, data-sharing models, and security expectations affect the long-term scalability of retail partnerships, rather than treating software selection as a purely dealership-level decision.
For investors, the most important signal is that growth is being driven by integration, automation, and compliance rather than by simple subscription expansion. That favors businesses with strong security posture, credible data unification capabilities, and sustainable ecosystem economics. At the same time, rising licensing costs, compliance expenses, and concentration risk argue for careful scrutiny of unit economics, customer retention dynamics, and the durability of differentiation. In a market where top providers hold a large share, incremental advantages in analytics, fraud controls, and workflow automation may matter more than headline feature counts.
For dealership groups and procurement teams, the practical question is total value rather than initial price. A platform that reduces manual processing, strengthens compliance readiness, and connects customer and operational data can create more value than one that appears cheaper but leaves workflows fragmented. Procurement decisions should weigh security certifications, integration costs with lenders and OEMs, support quality, and the feasibility of workflow redesign during implementation. It is also prudent to assess continuity and backup capabilities, given the sector’s heightened focus on operational resilience following recent disruptions.
Across these audiences, the value of detailed market intelligence lies in translating broad trends into segment-specific decisions. Revenue trajectories, deployment shifts, competitive moves, and compliance dynamics all interact differently across dealership size, region, and operational model. A fuller picture of these interactions, including granular segmentation and tailored strategic scenarios, can be found in the complete research report, which expands on the market structure, competitive dynamics, and decision frameworks discussed here.
For detailed analysis of this topic, please visit the official page: Auto Dealer Software Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Fuel Cell Membranes Market: Why 17.4% CAGR and APAC Shift Redefine Growth
By pmarketresearch, 2026-09-21
Fuel Cell Membranes Market: Strategic Trends and Commercial Opportunities
Market Overview and Core Challenges
The fuel cell membranes market has evolved from a niche component sector into a critical enabler of the broader hydrogen economy. Measured by global revenue, the industry generated approximately 671.23 USD Million in 2025, up from 423.74 USD Million in 2020. This trajectory reflects a compound annual growth rate of 17.4 percent through 2032, with revenue projected to surpass 1.2 billion USD Million by the end of the forecast period. The growth is not uniform. Demand is spreading across stationary power, transportation, and portable applications, while regional momentum is shifting toward Asia Pacific, followed by Europe and North America.
Behind these headline figures, the industry is navigating a series of structural tensions. First, membrane performance must keep pace with increasingly stringent operational requirements. Fuel cell stacks are being pushed toward higher power densities, lower operating temperatures in some configurations, and longer lifetimes in harsh environments. Meeting these demands requires membranes that balance proton conductivity, mechanical durability, and chemical stability, a combination that remains technically demanding even as material science advances.
Second, cost and supply chain resilience are becoming decisive competitive factors. The membranes segment relies on specialized polymers, ionomers, and precise manufacturing processes that have historically been concentrated among a small number of suppliers. As scale increases, manufacturers are under pressure to reduce bill-of-materials costs while maintaining quality consistency. Any disruption in raw material availability or production capacity can ripple through downstream stack assembly and system deployment timelines.
Third, the market is experiencing a policy-driven inflection point. Public support for hydrogen technologies is expanding, but the pace and shape of that support vary widely across jurisdictions. Incentive structures, emissions criteria, and technical targets are reshaping what qualifies as commercially viable. Companies that cannot align their product roadmaps with evolving regulatory expectations risk being sidelined, even if their technology is technically sound.
Key Drivers of Market Change
Technology Innovation and Material Breakthroughs
Material innovation is the most direct lever for expanding the addressable market for fuel cell membranes. Researchers and manufacturers are pursuing thinner membranes with higher proton conductivity, improved thermal and mechanical robustness, and reduced reliance on scarce or costly inputs. These improvements matter because they influence stack efficiency, system size, and lifetime performance. A membrane that conducts more effectively at lower thickness can enable more compact stacks, which in turn opens new design possibilities for vehicles, stationary units, and portable devices.
Recent technical targets from the U.S. Department of Energy illustrate the direction of travel. The department has articulated performance expectations for PEM fuel cell components that include membranes with less than 10 micrometer thickness and proton conductivity around 0.2 S/cm at 80 degrees Celsius. These benchmarks are not merely laboratory aspirations; they signal the performance threshold that commercialization efforts increasingly need to meet. Companies that can deliver membranes consistently at or near these specifications are better positioned to win contracts in mobility and stationary applications where efficiency and packaging constraints are tight.
Policy and Regulatory Environment
Policy support is reshaping both demand and economics. In the United States, the Inflation Reduction Act provides a Clean Hydrogen Production Tax Credit of up to 3 USD per kilogram for hydrogen with well-to-gate emissions below 0.45 kg CO2e per kg H2. This incentive changes the economics of hydrogen supply, which in turn affects the attractiveness of fuel cell deployments that depend on affordable, low-carbon hydrogen. When hydrogen production becomes more cost-competitive, downstream applications become more viable, and membrane demand follows.
Alongside production incentives, technical targets and cost-roadmap goals are influencing procurement and product development. U.S. Department of Energy multi-year plans outline hydrogen production cost targets of 2 USD per kilogram by 2026 and 1 USD per kilogram by 2031. These targets frame the cost structure that fuel cell systems, including membrane-based components, need to support. The implication is clear: membrane suppliers and system integrators must anticipate not just performance requirements, but the cost trajectory that policy and public investment are pushing the industry toward.
PW Consulting
Demand-Side Behavior and Application Expansion
Demand is broadening beyond early adopters and demonstration projects. Stationary applications continue to represent a substantial share of membrane demand, driven by power generation, backup power, and distributed energy needs. Transportation remains a strong growth vector, particularly where electrification alternatives face range, payload, or refueling time constraints. Portable applications add another layer of diversification, though at a smaller scale.
A telling example of how demand can pivot comes from the stationary power segment. In November 2025, Ceres Power signed a manufacturing licence agreement with Weichai Power for production of Ceres-designed fuel cells and stacks targeting stationary power markets, including AI data centres. This agreement highlights how fuel cell technology is being positioned for high-value, continuous-power applications where reliability and footprint matter. For membrane suppliers, such partnerships expand the pool of potential manufacturing and deployment partners, while also signaling that data centre and critical infrastructure power needs are becoming a strategic demand source.
Supply Chain and Cost Structure Shifts
Cost reduction is increasingly tied to vertical integration, manufacturing scale, and material strategy. Several companies are expanding in-house capacity for membrane-related components, including membrane electrode assemblies, to gain control over quality, lead times, and unit economics. Roll-to-roll manufacturing and other continuous production methods are being explored to improve throughput and consistency. At the same time, supply chain resilience has become a priority, with U.S. Department of Energy project work identifying membrane and ionomer materials as critical components for both supply chain resilience and cost reduction in fuel cell manufacturing.
For commercial strategy, this means that membranes are no longer just a performance component; they are a strategic supply chain asset. Companies that can secure reliable material inputs, optimize manufacturing processes, and reduce dependency on a narrow supplier base are gaining an advantage. Conversely, organizations that rely on fragmented sourcing or lack visibility into material availability may face cost volatility and deployment delays.
Competitive Landscape and Leading Strategies
The competitive field is defined by a mix of system integrators, component specialists, and manufacturers pursuing in-house production of membrane-related assemblies. Market concentration remains notable, with the top three companies accounting for roughly 61 percent of market revenue and the top five reaching about 67 percent. This concentration suggests that scale, brand recognition, and established customer relationships still matter greatly, even as innovation and niche differentiation create openings for new entrants.
Ballard Power Systems, based in Burnaby, British Columbia, Canada, is one of the most recognized names in PEM fuel cell systems. Its profile centers on designing, developing, manufacturing, and selling fuel cell systems for mobility, stationary, and marine applications. Proprietary membrane electrode assemblies, including membranes, form a core part of its fuel cell stacks. Ballard’s strategic positioning is built on broad application coverage and long-standing system-level expertise, which gives it visibility across multiple end markets and a platform for iterative membrane and MEA improvements tied to real-world stack performance.
Plug Power Inc., headquartered in Latham, New York, USA, operates as a manufacturer and supplier of PEM fuel cell systems and MEAs, with in-house production of membranes for its GenDrive mobility and GenSure stationary products. This in-house capability is strategically significant. By controlling more of the membrane and MEA supply chain, Plug Power can better align component production with its system roadmap, reduce dependency on external suppliers, and respond more quickly to volume changes. Its commercial focus on both mobility and stationary applications also diversifies revenue exposure.
Hyzon Motors Inc., based in Bolingbrook, Illinois, USA, develops and manufactures high-performance hydrogen fuel cell systems and operates an in-house roll-to-roll membrane electrode assembly manufacturing line for proprietary components. This manufacturing approach points to a strategy centered on performance customization and production control. For Hyzon, the ability to produce proprietary membrane-related components in-house supports differentiation in the commercial vehicle and heavy-duty segments, where performance, durability, and system integration are central buying criteria.
Freudenberg e-Power Systems, located in Weinheim, Germany, supplies fuel cell components including membranes and seals for PEM and other fuel cell technologies. Its role illustrates a different competitive posture: component supply and engineering partnership rather than full system branding. Freudenberg’s strengths lie in material expertise, precision component supply, and the ability to serve multiple customers and applications through a focused components business. This model can be attractive in a market where some system builders prefer to source advanced membranes and related parts from specialized suppliers rather than internalize all production.
The recent Ceres Power and Weichai Power agreement also illustrates a broader competitive trend: licensing and partnership models are becoming more prominent alongside direct manufacturing. In this case, the agreement targets stationary power markets including AI data centres, signaling that intellectual property and licensed manufacturing can be a viable route to scale, especially when paired with a strong local manufacturing partner. This pattern suggests the competitive landscape is not only about who makes membranes, but also about who controls the design, licensing, and deployment pathways that turn membrane technology into deployed systems.
Strategic Evolution: Consolidation, Fragmentation, and New Entry
The market is showing signs of both consolidation and fragmentation, depending on the segment. In established system-level applications, scale advantages and customer qualification cycles favor larger players with proven track records. At the same time, new entry remains possible in component supply, specialized membrane formulations, and licensed manufacturing. The presence of in-house MEA production among several leading companies indicates that vertical integration is becoming a more common response to cost, quality, and supply chain concerns.
At the same time, end-use diversification is fragmenting demand patterns. Stationary, transportation, and portable applications each impose different technical and commercial requirements, which means a single membrane strategy is rarely sufficient. Companies that can tailor products to application-specific needs, or that can supply a broad range of customers through component Sales, are better positioned to capture growth across multiple demand pockets. The strategic question is whether to compete as a system-level brand, a high-value component supplier, or a licensed technology partner. Each path carries a different risk-return profile.
Future Trends and Commercial Implications
Trend 1: Performance-Barrier Reduction and Wider Adoption
As membrane technology advances toward thinner, more conductive, and more durable formulations, the performance barriers that have limited adoption in certain applications are likely to ease. This trend should support broader use in transportation and stationary deployments where efficiency, packaging, and operating lifetime are decisive. Commercially, this creates opportunities for suppliers that can reliably meet higher performance expectations while maintaining cost discipline. It also raises the stakes for producers that fail to keep pace with evolving specifications.
Ceramic Membrane Market
Trend 2: Policy-Aligned Economics Becoming a Purchasing Criterion
Hydrogen production incentives, emissions thresholds, and cost targets are increasingly shaping procurement decisions. Buyers are not just evaluating membrane performance; they are evaluating how component choices fit into a broader system that must meet policy-driven cost and emissions expectations. This trend favors suppliers and integrators that can articulate the link between membrane selection, stack efficiency, hydrogen utilization, and total cost of ownership. It also means that regulatory developments in major markets can quickly alter demand patterns, making policy monitoring a core business function rather than a peripheral activity.
Worldwide Breathable Membranes Market
Trend 3: Manufacturing Control and Supply Chain Resilience as Competitive Moats
As volumes grow, manufacturing capability and material security will become more important differentiators. Companies with in-house MEA production, continuous manufacturing processes, and diversified material sourcing are likely to be better positioned to manage cost, quality, and lead-time risk. This trend could accelerate partnership, licensing, and selective vertical integration across the value chain. It also introduces a cautionary note: over-investment in fixed manufacturing capacity without aligned demand can create financial strain, especially if deployment timelines shift or policy support changes.
Risks and Uncertainties
Several uncertainties could alter the trajectory. Policy support may change in pace or design, affecting hydrogen economics and demand timing. Technical targets may prove difficult to meet consistently at scale, especially under real-world operating conditions. Raw material availability and pricing can affect margin stability, particularly for specialized polymers and ionomers. Finally, competition from alternative power technologies, including advances in batteries and hybrid systems, continues to shape the commercial context in which fuel cell membranes are evaluated. These risks do not negate the growth outlook, but they do suggest that strategy should be built around flexibility, scenario planning, and close monitoring of both technology and policy developments.
Actionable Recommendations for Decision-Makers
For Manufacturers and Component Suppliers
- Align membrane development with application-specific performance targets rather than pursuing a single universal specification. Stationary, transportation, and portable uses impose different durability, conductivity, and packaging needs, and product portfolios should reflect that reality.
- Evaluate selective vertical integration or partnership models for membrane electrode assemblies and related components. In-house capability can improve quality control and responsiveness, but it should be weighed against capital intensity and demand uncertainty.
- Treat material security and manufacturing resilience as strategic priorities. Diversify sourcing where possible, monitor critical material dependencies, and build production processes that can support consistent quality at higher volumes.
For Investors
- Focus on companies with clear pathways to scale, whether through in-house manufacturing, licensing, or strong system-level customer relationships. Revenue concentration in the market means that competitive positioning and customer access are especially important.
- Assess exposure to policy-driven economics, particularly hydrogen production incentives and technical targets that influence downstream demand. Companies that can connect their component or system offerings to these macroeconomic drivers may have stronger commercial momentum.
- Watch for partnerships and licensing agreements that expand reach into high-value stationary applications, such as data centre power and critical infrastructure, where reliability and continuous operation can support premium positioning.
For Procurement and Strategic Buyers
- Evaluate membrane and MEA suppliers not only on performance specifications, but also on manufacturing reliability, supply chain transparency, and the ability to support long-term volume needs. Qualification cycles are often long, so supplier stability matters.
- Consider total system economics, including how membrane choices affect stack efficiency, lifetime, and hydrogen utilization. In policy-supported markets, these factors can be as important as upfront component cost.
- Plan for evolving technical targets and regulatory expectations. Procurement strategies should remain flexible enough to accommodate performance improvements and cost changes as the market matures.
Conclusion
The fuel cell membranes market is entering a phase where performance, cost, policy, and supply chain strategy are tightly intertwined. Growth is supported by expanding demand across stationary, transportation, and portable applications, while technical targets and hydrogen economics are sharpening the requirements that suppliers must meet. Market concentration indicates that scale and established relationships remain powerful advantages, but the rise of in-house manufacturing, licensing models, and application-specific differentiation shows that the competitive field is still evolving.
For organizations operating in or adjacent to this market, the most valuable next step is to convert broad trends into specific decisions about product positioning, manufacturing strategy, supplier selection, and investment timing. Detailed segmentation data, regional breakdowns, and company-level assessments can make those decisions more precise and less dependent on generalization. The full research report provides that deeper view, with granular market splits, competitive profiling, and structured scenarios designed to support planning across manufacturing, investment, and procurement teams.
For detailed analysis of this topic, please visit the official page: Fuel Cell Membranes Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com