

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Laboratory Furniture Market 2026: Beyond the 4.3% CAGR Story

Navigating the Laboratory Furniture Market: Strategic Trends and Commercial Opportunities Through 2032
The global laboratory furniture market has transitioned from a cyclical, project-driven sector to a structurally expanding industry shaped by scientific modernization, regulatory tightening, and supply chain recalibration. Valued at approximately 1.8 billion USD in 2025, the market has expanded from roughly 1.34 billion USD in 2020, reflecting a compound annual growth rate of 4.3 percent through 2032. While short-term fluctuations are inevitable in capital-intensive laboratory build-outs, the underlying trajectory points toward sustained demand as research institutions, clinical facilities, and educational laboratories retrofit aging infrastructure and accommodate new experimental workflows. For executives and investors, the opportunity lies not in chasing headline growth figures, but in understanding where segmentation, compliance, and manufacturing capabilities intersect to create defensible positioning.
Market Snapshot and Structural Headwinds
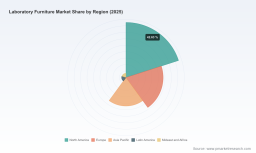
The market’s growth over the past half-decade has been underpinned by steady capital deployment in life sciences, materials research, and diagnostic capacity. Europe and North America continue to anchor the largest revenue pools, reflecting mature research ecosystems and ongoing public and private investment in laboratory modernization. Asia Pacific has emerged as a high-growth corridor, driven by expanding university infrastructure, pharmaceutical development hubs, and localized manufacturing of laboratory equipment. Latin America and the Middle East and Africa represent smaller but increasingly meaningful demand pockets, often tied to bilateral research initiatives, hospital network expansions, and emerging biotech clusters.
Despite the positive top-line trajectory, several structural challenges are reshaping how manufacturers, integrators, and buyers approach laboratory furniture projects.
Supply Chain Complexity and Labor Cost Pressures
The sector has moved beyond the acute disruptions of earlier years, but supply chain volatility remains embedded in procurement planning. Lead times for steel, engineered plastics, coatings, and specialized hardware continue to fluctuate with regional manufacturing capacity, logistics constraints, and input cost swings. Alongside this, labor costs for fabrication, assembly, and on-site installation have risen, compressing margins for vendors that rely on labor-intensive customization without corresponding productivity gains. Kewaunee Scientific Corporation highlighted these dynamics in its recent reporting, noting that supply chain complexity and labor cost pressures are ongoing challenges across the laboratory furniture segment. For operators, the implication is clear: scale alone is no longer sufficient. Margins increasingly depend on modular standardization, predictable sourcing, and efficient project execution.
School Furniture Market
Regulatory and Standards Acceleration
A second major shift is the rapid evolution of design and installation standards. Standards bodies and industry groups are moving from advisory guidance to more formalized expectations around laboratory furniture safety, chemical resistance, and ergonomic integration. The publication of EN 14056-1:2025 for installation and design of laboratory benches, associated storage units, and service provision marked a notable step in codifying expectations across Europe. In parallel, SIST EN 14056-1:2026 extended similar design and installation considerations to biology, chemistry, and physics laboratories. More recently, SEFA has been developing standards for lab-grade flooring and lab-grade washers, with committee work planned to advance into walls and ceilings. This expanding standards ecosystem raises the bar for compliance, documentation, and integration, particularly for international projects where multiple regional codes intersect.
Demand Fragmentation Across Laboratory Types
Laboratory furniture is no longer a homogeneous category. Research and development laboratories continue to drive a significant share of demand, but the market is increasingly shaped by divergent requirements across clinical diagnostics, academic environments, and specialized institutional use. R&D environments prioritize modularity, chemical resistance, and integration with equipment-centric workflows. Clinical and medical laboratories place heavier emphasis on cleanability, contamination control, and regulatory-aligned finishes. Educational laboratories demand durability, flexibility, and cost predictability across high-use cycles. This fragmentation rewards manufacturers that can align product architecture to distinct use cases rather than offering one-size-fits-all casework and bench solutions.
Key Demand Drivers Reshaping the Market
Technical Innovation in Modular and Material Systems
Material and modularity innovation remains one of the most direct levers for competitive differentiation. Manufacturers are expanding beyond traditional steel and wood casework toward hybrid configurations that combine durability, chemical resistance, and cleaner finishes for modern laboratory protocols. The September 2025 launch of a new modular laboratory furniture range featuring powder-coated options alongside stainless-steel models illustrated how suppliers are broadening their material toolkits to serve varied hygiene, corrosion, and aesthetics requirements. At the same time, modular bench systems, mobile lab configurations, and integrated storage are gaining traction because they reduce installation complexity and support reconfiguration as research priorities shift. For buyers, modularity is not merely a convenience; it is a lifecycle strategy that lowers total cost of ownership in environments where experimental layouts and equipment footprints change frequently.
Regulatory Alignment as a Market Access Driver
Regulatory and standards activity is functioning as both a constraint and a catalyst. On one hand, tighter expectations around installation design, storage safety, and surface compatibility increase verification burdens and can slow project timelines if documentation is incomplete. On the other hand, standardized expectations create clearer pathways for vendors that invest early in compliance-ready product lines and installation documentation. The EN 14056-1 framework, together with emerging SEFA work on lab-grade building components, signals a future where laboratory environments are evaluated more holistically, with furniture, casework, flooring, and related systems treated as part of an integrated compliance picture. Companies that anticipate these expectations can convert regulatory maturity into a procurement advantage, particularly in public tenders, institutional projects, and cross-border initiatives where standardization reduces approval friction.
Office Furniture Market
Shifting End-User Expectations and Infrastructure Modernization
Demand-side behavior is changing as laboratory operators prioritize flexibility, longevity, and integration over lowest initial price. Research organizations are increasingly weighing furniture selections against long-term reconfiguration needs, equipment integration, and maintenance burdens. Clinical laboratories and hospital networks are upgrading from legacy casework to systems designed for stricter cleaning protocols and more durable finishes. Educational institutions are balancing budget constraints with the need for adaptable spaces that can support evolving curricula and safety requirements. This behavior shift is pushing the market toward higher-specification systems in selected applications, even as price sensitivity persists in broader institutional spending. The strategic implication is that value is increasingly defined by how well furniture supports operational continuity, not simply by upfront unit economics.
Cost Structure Realignment and Regional Manufacturing Dynamics
Cost structures across the laboratory furniture market are being reshaped by a combination of input pricing, fabrication methods, and regional sourcing strategies. In mature markets, the pressure on labor-intensive assembly is encouraging greater use of pre-engineered components, standardized sub-assemblies, and improved logistics planning. In faster-growing regions, localized production and regional distribution hubs are becoming more relevant to reduce lead times and improve responsiveness to project-based demand. This realignment favors companies that can balance global product consistency with regional execution capability. It also creates opportunities for partners that can support installation, training, and post-deployment service without relying entirely on centralized manufacturing models.
Competitive Landscape and Strategic Positioning
The competitive environment is characterized by a moderate level of concentration, with the top three firms representing roughly 21 percent of the market and the top five approximately 26 percent. This leaves meaningful room for mid-tier specialists, regional players, and application-focused manufacturers to compete on differentiation rather than scale alone. The field includes established North American and European producers with broad laboratory furniture portfolios, alongside specialized companies targeting specific product categories such as casework, storage cabinets, chemical-resistant units, ergonomic seating, and integrated lab infrastructure.
Established Incumbents and Capability Clustering
Several incumbent manufacturers have built their market positions by clustering capabilities around complementary product families. Kewaunee Scientific Corporation has centered its offering on steel and wood casework, modular benches, and fume hoods, giving it a recognizable footprint in core laboratory infrastructure. Labconco Corporation has emphasized custom laboratory furniture, including casework, storage systems, and integrated modular components, positioning itself around tailored lab configuration. Esco Technologies, Inc. provides laboratory casework, benches, and full furniture systems for research facilities, aligning product breadth with project-scale demand. NuAire, Inc. manufactures laboratory furniture components and integrated lab infrastructure solutions, while Diversified Casework, Institutional Casework, and Mott Manufacturing Corp. each contribute specialized casework and modular system expertise across institutional and research contexts.
In Europe, Waldner Laboreinrichtungen SE & Co. KG has developed a comprehensive laboratory furniture system portfolio encompassing fume hoods and mobile labs, supporting clients that need coordinated lab environments rather than isolated furniture purchases. Asecos GmbH focuses on laboratory furniture including storage cabinets and chemical-resistant units, a specialization that maps well to safety-intensive applications. BIMOS GmbH differentiates through ergonomic laboratory furniture, seating, and complete work systems, targeting human-centered lab design. Together, these profiles show a market where competitive advantage is often built from product depth, application fit, and integration capability rather than from price alone.
PW Consulting Health Care Research Center
Strategic Differentiation and Event-Driven Visibility
Trade participation and product launches are increasingly used to signal capability expansion and reinforce market presence. Kewaunee Scientific Corporation and Waldner both used analytica 2026 in Munich to exhibit laboratory infrastructure and furniture solutions, including fume hoods and mobile labs, reinforcing their positioning in integrated lab environments. In a different but related move, Teknomek Ltd expanded its modular laboratory furniture range with powder-coated options alongside stainless-steel models, signaling a broader material strategy. These activities matter because laboratory furniture purchasing is highly project- and specification-driven; visibility at industry events and the introduction of new material or modularity options can shape short-list decisions well before procurement cycles close.
Consolidation, Fragmentation, and New Entrant Dynamics
The market is likely to continue evolving along two parallel tracks. In one direction, larger players may pursue selective consolidation, channel partnerships, or capability acquisitions to broaden geographic reach, strengthen installation and service networks, or add complementary product lines such as integrated storage, ergonomic seating, or specialized containment-related furniture. In the other direction, application-specific fragmentation will persist, with niche players competing around chemical resistance, cleanability, modularity, or ergonomics in ways that matter to particular end users. New entrants can still gain traction by targeting underserved regional markets or specialized laboratory types, but sustained success will depend on demonstrating measurable advantages in compliance readiness, lead-time reliability, and installation efficiency. Pure commodity positioning is increasingly vulnerable, especially as standards and end-user expectations raise the baseline for acceptable performance.
Forecast Pathways and Commercial Implications
Looking ahead through the next three to five years, several trends are likely to shape both market growth and competitive dynamics.
Standards-Integrated Product Architecture
As standards for laboratory benches, storage, and related building components become more entrenched, product architecture will increasingly need to reflect compliance, documentation, and integration requirements from the outset. Manufacturers that design for these expectations can shorten approval cycles, reduce retrofit risk, and position themselves favorably in regulated or publicly funded environments. For procurement teams, this trend raises the importance of evaluating not just furniture performance, but also the quality of installation guidance, certification documentation, and compatibility with adjacent lab-grade systems.
Modularity as a Baseline Expectation
Modular design is poised to move from a premium feature to a baseline expectation in many laboratory segments. Research teams, in particular, value the ability to reconfigure benches, casework, and service access as experimental requirements evolve. Mobile labs and reconfigurable systems also appeal to organizations managing multiple sites or temporary project spaces. The commercial opportunity lies in offering modular systems that still meet durability, safety, and serviceability requirements without becoming overly customized or cost-prohibitive. Success will depend on standard engineering, repeatable installation patterns, and clear upgrade paths.
Regional Growth and Localized Execution
Growth is expected to remain strongest in regions where laboratory infrastructure expansion and modernization are converging, including parts of Asia Pacific, while mature markets will likely see steadier replacement and upgrade demand. In both cases, localized execution capability will matter more than in the past. Buyers increasingly care about predictable lead times, on-site support, spare parts availability, and regional accountability. Companies that pair consistent product standards with strong local service and installation capacity are better positioned to win repeat business and institutional relationships. A key uncertainty is the pace of input cost normalization and labor availability; if cost pressures persist, price-sensitive segments may delay projects or shift toward simpler specifications, while higher-value applications may continue upgrading regardless.
Strategic Guidance for Decision Makers
The most actionable implications vary by role, but several themes apply across the board.
For Manufacturers and Integrators
- Prioritize modular standardization and material diversity that align with real installation and cleaning requirements, rather than expanding product breadth for its own sake.
- Invest in documentation, installation clarity, and compatibility with emerging lab-grade standards so that projects move through approval and compliance steps more efficiently.
- Strengthen regional execution capability, including installation support and post-deployment service, to reduce the operational risks that erode margin in project-based businesses.
For Investors and Strategic Planners
- Evaluate exposure to standards-driven and compliance-heavy segments, where early investment in certified or certification-ready systems can create durable procurement advantages.
- Look for business models that combine product repeatability with reliable service and installation capacity, since these characteristics support margin stability in a fragmented market.
- Monitor regional demand shifts and localized production strategies, as sourcing and execution geography will increasingly influence lead-time reliability and customer retention.
For Procurement and Facility Decision Makers
- Move beyond unit price comparisons and assess total lifecycle value, including reconfigurability, cleaning and maintenance burdens, and compatibility with adjacent lab infrastructure.
- Treat standards readiness and documentation quality as selection criteria, especially for regulated, multi-site, or publicly funded projects where approval friction can delay delivery.
- Define specification requirements around actual operating conditions rather than generic categories, since laboratory furniture performance varies significantly across R&D, clinical, educational, and institutional use cases.
Conclusion
The laboratory furniture market is moving toward a more standards-aware, modular, and operationally demanding environment. Growth at a 4.3 percent CAGR through 2032 reflects durable demand across research, clinical, educational, and institutional settings, but the profitable opportunity is concentrated in manufacturers and integrators that can align product architecture, compliance readiness, and regional execution with distinct laboratory workflows. As standards expand beyond furniture into broader lab-grade systems and end users increasingly prioritize lifecycle flexibility, the winners will be those that treat laboratory furniture as part of an integrated operational strategy rather than a stand-alone purchase. Detailed segmentation data, application-level demand patterns, and company-specific positioning can sharpen decision making further, and organizations seeking deeper commercial intelligence may find value in consulting the full research report for more granular market detail and tailored guidance.
For detailed analysis of this topic, please visit the official page: Laboratory Furniture Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com