

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Glass Microfiber Market 2026: Beyond the 5.48% CAGR Growth Story

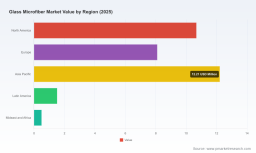
Strategic Shifts and Commercial Opportunities in the Global Glass Microfiber Market
The global glass microfiber market has entered a phase of measured expansion, evolving from a niche material segment into a strategically important component across filtration, energy storage, and thermal management applications. Over the 2020–2025 period, the market demonstrated steady growth, reaching a valuation of approximately $33.0 million in 2025. The trajectory into the 2026–2032 forecast window points to a compound annual growth rate of 5.48 percent, with the market expected to approach $47.9 million by 2032. This baseline reflects both residual growth from mature industrial applications and incremental demand from emerging use cases. The expansion is not uniform, however, and beneath the aggregate figures lies a landscape shaped by feedstock dynamics, technological differentiation, and shifting regulatory expectations. For executives and investors evaluating exposure to advanced nonwoven materials, the glass microfiber segment presents a case study in how commodity-linked inputs can coexist with high-value specialty positioning.
Navigating Constraints in a Mature yet Evolving Segment
The market’s current phase is defined by three intersecting challenges that require strategic attention. First, the cost structure remains highly sensitive to raw material inputs. High-purity quartz, the foundational feedstock for borosilicate glass microfiber production, has exhibited notable price volatility, with premium grades beginning at $5,000 per ton. This volatility directly constrains margin predictability and influences capacity planning decisions across the value chain. Second, regulatory and compliance expectations are tightening around product consistency, particularly for borosilicate formulations used in analytical, laboratory, and filtration contexts. Manufacturers must navigate not only cost pressures but also the operational burden of maintaining traceable, high-purity production streams. Third, the industry exhibits meaningful concentration, with the top three players accounting for roughly 45.2 percent of market share and the top five reaching 62.1 percent. This concentration signals entrenched competitive positions, but it also leaves room for targeted differentiation by regional specialists, application-focused producers, and new entrants that can align product specifications with emerging demand pockets.
Core Drivers Reshaping the Market Trajectory
Understanding where the market is headed requires examining the forces that are actively reshaping demand, supply, and competitive behavior. These drivers are not isolated; they interact in ways that create both headroom and friction.
Technological innovation remains a primary catalyst. The transition from commodity-grade microfiber to engineered, application-specific formulations has unlocked performance gains in filtration efficiency, thermal stability, and dimensional consistency. Developments in binderless architectures and specialty borosilicate blends have reduced dependency on additive systems, enabling manufacturers to offer products that better meet the purity and durability requirements of analytical and cleanroom environments. At the same time, advancements in nonwoven processing have expanded the utility of glass microfiber beyond traditional paper and filter formats, allowing it to perform in battery separator-adjacent functions and heat preservation materials where weight, insulation, and chemical resistance matter.
Policy and regulatory dynamics are compounding these technical shifts. Environmental and safety expectations are increasingly shaping procurement criteria in industrial filtration, HVAC, and laboratory settings. As end-users place higher value on traceability, low-leaching performance, and consistent particle retention, the bar for qualification rises. Regulatory pressure does not uniformly suppress demand; rather, it accelerates the separation between standard-grade offerings and premium, compliance-ready products. Companies that can demonstrate robust quality systems and transparent sourcing gain a structural advantage in markets where substitution risk is low and qualification cycles are long.
Demand-side behavior is also evolving. Industrial operators and research institutions are prioritizing filtration media that deliver higher efficiency with lower lifecycle cost, even if upfront pricing is higher. This preference is visible in cleanroom, environmental monitoring, and high-purity laboratory applications, where failure costs outweigh material cost considerations. Simultaneously, growth pockets in energy-related and thermal management applications are pulling glass microfiber into adjacent value chains. While the filter paper segment continues to anchor a substantial portion of revenue, battery-adjacent and heat preservation use cases are expanding the addressable base. The practical implication is that demand is becoming more application-specific, and generic commodity positioning is increasingly vulnerable to displacement by tailored solutions.
Supply chain and cost structure changes complete the picture. Feedstock volatility, as noted, affects planning horizons and pricing strategies. Producers that secure long-term quartz supply arrangements, invest in process efficiency, or localize certain production steps can convert cost pressure into a barrier for less-prepared competitors. At the same time, geographic divergence in demand intensity means that supply decisions increasingly weigh regional proximity, logistics stability, and local compliance requirements alongside pure production economics.
Recent operational moves underscore these dynamics in practice. In January 2026, Johns Manville launched a state-of-the-art micro fiberglass production line at its Wertheim, Germany facility to produce Evalith micro fiberglass nonwovens. This capacity expansion reflects a deliberate push into higher-value nonwoven formats, aligning product architecture with filtration, specialty paper, and battery separator-adjacent applications. The move illustrates how leading producers are translating technical differentiation into tangible capacity and geographic positioning, rather than relying solely on incremental grade improvements.
Competitive Positioning and the Evolution of Market Structure
The competitive landscape is anchored by companies that have built strong reputations around product specialization, application alignment, and quality assurance. These players do not compete on identical terms; instead, each has carved a distinct strategic position that leverages specific technological or market strengths.
Johns Manville, headquartered in Denver, Colorado, operates as a broad-based producer with recognized franchises in JM Micro-Strand and Evalith glass microfibers. Its portfolio spans filtration, battery separators, and specialty papers, giving it a multi-application footprint that supports cross-selling and scale advantages in nonwoven production. The recent German capacity expansion reinforces its emphasis on advanced nonwoven formats and positions the company to serve European and export markets with a more localized, higher-specification supply base.
Hollingsworth & Vose, based in East Walpole, Massachusetts, maintains a clear identity as a specialist in high-efficiency glass microfiber filter media. Its focus on cleanroom, HVAC, and industrial filtration aligns it with sectors where performance consistency, particulate retention, and compliance readiness are decisive. This application-centric positioning allows the company to compete on technical merit and qualification reliability rather than price alone.
I.W. Tremont, located in Riverton, New Jersey, has built its profile around binderless and specialty 100 percent borosilicate glass microfiber for laboratory, analytical, and volatile suspended solids filtration. The emphasis on borosilicate purity and binderless construction addresses stringent analytical requirements and creates a defensible niche where substitution is difficult once methods and protocols are established. This specialization also makes the company particularly exposed to high-purity quartz cost dynamics, but it simultaneously raises switching costs for demanding end-users.
Porvair Filtration Group, headquartered in Fareham, United Kingdom, supplies precision glass microfiber filter media and cartridges for laboratory, environmental, and industrial applications. Its cartridge and media combination strategy connects material performance with downstream system integration, giving customers a more complete solution path. This approach is well suited to environments where filter format, housing compatibility, and replacement cycles influence total cost of ownership.
The market structure is evolving along several vectors. Concentration at the top indicates that scale, brand familiarity, and established qualification networks matter, but the presence of highly specialized players shows that segmentation remains viable. Differentiation is increasingly tied to product architecture, application fit, and supply reliability rather than volume alone. Integration trends are likely to continue where larger players seek to secure higher-margin nonwoven and specialty segments, while smaller specialists may pursue regional expansion, formulation depth, or partnership-based distribution. New entry remains challenging due to qualification cycles and feedstock complexity, but targeted entry in underserved applications or geography-specific supply gaps is not implausible, especially where local compliance and proximity advantages can be leveraged.
Looking Ahead: Three Trends That Will Shape the Next Three to Five Years
The next phase of market development will be shaped by the interaction of feedstock economics, application expansion, and the premiumization of compliant, high-performance materials. The first trend is the continued bifurcation between standard-grade and engineered offerings. As end-users in filtration, laboratory, and thermal applications place greater weight on consistency, purity, and lifecycle performance, the share of revenue associated with premium, application-tailored products is expected to rise even if overall growth remains moderate. This trend rewards manufacturers that can sustain tight specification control, provide clear qualification support, and reduce total cost of ownership for customers through better performance rather than lower sticker price.
The second trend is the gradual broadening of application adjacency. While filter paper remains a central demand anchor, battery-related and heat preservation use cases are expanding the contexts in which glass microfiber is evaluated. This does not imply a sudden surge in any single application, but it does suggest that product development and commercial teams should treat adjacent markets as incremental growth vectors, particularly where insulation, chemical resistance, and dimensional stability align with material strengths. Companies that can translate filtration and analytical credibility into credibility for thermal and energy-adjacent applications will have more options to diversify revenue.
Microfiber Market
The third trend is supply-side recalibration around feedstock risk and regionalization. High-purity quartz volatility will continue to influence cost planning, and producers will increasingly manage this risk through long-term sourcing, process efficiency gains, and strategic capacity placement. Regional demand intensity will also matter more as customers prioritize supply resilience and compliance alignment. Over the next three to five years, the market is likely to reward players who can combine formulation expertise with reliable, geographically appropriate supply, while those dependent on undifferentiated commodity positioning may face margin compression and substitution pressure.
These trends carry both opportunity and uncertainty. Demand for premium solutions is real, but qualification cycles can be slow and customer switching behavior cautious. Feedstock volatility can compress margins even for differentiated products if not managed proactively. And while application adjacency opens new paths, it also requires credible performance data and application-specific validation before commercial traction materializes. Executives should therefore treat growth as achievable but conditional on disciplined product strategy, supply risk management, and targeted commercial execution.
Strategic Actions for Different Decision-Maker Profiles
For manufacturers, the priority is to reinforce differentiation where qualification and performance consistency create durable advantages. This means investing in formulation precision, binderless or low-additive architectures where appropriate, and application-focused product documentation that speeds customer validation. Capacity and sourcing decisions should be evaluated not only on unit cost but also on proximity to key demand pools, resilience to quartz price swings, and the ability to support regional compliance expectations. Companies that align product roadmaps with higher-value nonwoven, analytical, and thermal use cases are better positioned to capture premium share than those competing primarily on volume.
For investors, the relevant question is where value is created and protected within the segment. Market concentration indicates that scale and brand matter, but the more durable opportunities often sit in specialized formulations, application-aligned portfolios, and supply chains that mitigate feedstock volatility. Due diligence should examine how well a company manages high-purity quartz exposure, whether its product mix leans toward standard or engineered grades, and how effectively it converts technical capability into qualified, repeatable customer relationships. Investment theses that assume uniform growth across all applications will likely overlook the segmentation dynamics that actually drive margin and retention.
PW Consulting
For procurement and sourcing leaders, the focus should shift from unit price to total cost of ownership and qualification risk. In filtration, laboratory, and thermal applications, inconsistency or non-compliance can create far greater costs than material price differences. Evaluating suppliers on traceability, lot-to-lot consistency, technical support, and long-term feedstock stability is a practical way to reduce operational risk. Where possible, securing multi-source options for critical grades while deepening relationships with suppliers that demonstrate strong quality systems can balance resilience with performance assurance.
Across all of these perspectives, the value of detailed, application-level and regional intelligence is clear. Aggregate market size and growth rates provide a useful frame, but they do not reveal where specification upgrades are accelerating, which applications are expanding fastest, how feedstock cost exposure differs by product type, or where capacity additions will alter competitive dynamics. Decision-makers who pair strategic intent with granular market data are better equipped to time capacity moves, prioritize product development, and structure supplier relationships with greater confidence.
Glass Fibers Market
A closer examination of the market’s segmentation splits, application-level demand shifts, regional intensity patterns, and company-specific strategic moves can sharpen planning considerably. For teams seeking to align investment, sourcing, or product strategy with the structural dynamics of glass microfiber, a fuller dataset and tailored analysis provide the detail needed to move from directional insight to executable decision-making. The complete research report offers that level of segmentation depth, including detailed regional and application breakdowns, competitive positioning context, and forward-looking scenario analysis designed to support specific business decisions.
For detailed analysis of this topic, please visit the official page: Glass Microfiber Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com