
Blogs
High Temperature Superconductor Market: Why 11.5% CAGR and 2G HTS Shifts Define 2032 Growth
By pmarketresearch, 2026-09-21
Unlocking the High Temperature Superconductor Market: Strategic Trends and Commercial Horizons
The high temperature superconductor (HTS) market has transitioned from a niche technology space to a strategic battleground for energy infrastructure, advanced manufacturing, and next-generation computing. Over the past five years, global revenue has expanded from a modest base to a meaningful commercial tier, and the trajectory toward the end of the decade suggests an inflection point rather than a linear continuation. With a compound annual growth rate of 11.5 percent across the 2026 to 2032 horizon, the market is not merely expanding in size; it is evolving in structure, application mix, and competitive intensity. For executives and investors, the central question is no longer whether superconductors will reach broader commercial relevance, but where value will concentrate and which capabilities will separate winners from laggards.
Market Snapshot: Size, Structure, and the Emerging Inflection
The HTS market crossed from incremental expansion into a more pronounced upward phase beginning in 2023, with momentum carrying through 2025 and setting the stage for a faster growth cadence in the forecast period. Revenue progression over the historical window reflects steady adoption punctuated by acceleration as certain applications moved from demonstration to early commercial deployment. Looking ahead, the forecast figures indicate a market that does not simply add increments each year but gains pace as the addressable base broadens and more projects convert into procurement commitments. By 2032, the market is projected to reach a materially higher revenue level than today, implying that the cumulative value created over this window will be substantial relative to the starting point.
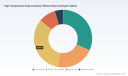
This trajectory is not uniform across the landscape. The market remains decentralized, with a relatively modest concentration among the largest players. Such fragmentation is typical of an industry where niche applications, regional demand patterns, and differentiated wire and system technologies coexist. It also signals that leadership positions are still being defined, and that the structure of the market may shift as consolidation, partnerships, and scale-up strategies mature. For decision-makers, the implication is clear: the field is open enough that strategic choices made now can influence positioning, yet concentrated enough in key technologies and regions that late movers may face steeper integration costs or higher barriers to performance credibility.
Defining Challenges at the Current Inflection Point
Despite the growth outlook, three challenges are shaping how value accrues and which business models prove durable. The first is the tension between performance gains and manufacturing scalability. As application requirements push toward higher current densities, stronger magnetic fields, and more demanding operating conditions, the industry is being asked to deliver consistency at volume. Producing advanced conductor materials with tight defect tolerances and repeatable performance remains a central bottleneck, especially as demand in priority segments begins to outpace available capacity. This is not merely a production issue; it is a commercial qualification issue, because reliability testing and standards development continue to be prerequisites for broader adoption in grid infrastructure, transport, aerospace, and high-field environments.
The second challenge is the cryogenic ecosystem. Even as HTS materials lower the temperature requirements relative to low-temperature alternatives, commercial-scale deployment still depends on reliable cooling systems that are long-lived, low-maintenance, and cost-effective. The performance of the conductor and the practicality of the cooling architecture cannot be optimized in isolation. Projects that succeed tend to integrate wire selection, thermal management, and installation constraints as a single system problem rather than as separate procurement item. This interdependency raises the barrier to entry for component-only suppliers and rewards players who can deliver integrated, field-ready solutions.
The third challenge is the evolving but still maturing regulatory and standardization context. HTS technologies generally operate within existing frameworks, but the pathway to faster deployment increasingly depends on industry-led standardization efforts that reduce compliance ambiguity and create confidence in performance verification. Efforts around reference measurement methods and interoperability expectations are helping, but broad industrial acceptance still requires continued qualification work and consistency in how performance claims are validated. For companies and buyers alike, the practical consequence is that leadership in standards engagement and credible testing can become a competitive asset, not just a compliance exercise.
Core Drivers Reshaping the Market
Performance breakthroughs expanding the application frontier
A decisive driver is the ongoing improvement in wire and tape performance that broadens the feasible application envelope. Recent product and exhibition activity signals that rare-earth-based HTS tapes are reaching higher engineering current density levels and enabling more demanding magnet and power applications. At the same time, independent development programs are targeting faster tape production lines to support high-field magnets, power transmission, fusion, and even electric aircraft concepts. These advances matter because performance improvements do more than refine existing products; they open new commercial contexts where superconductors offer advantages in footprint, efficiency, or field intensity that conventional alternatives cannot match.
The strategic significance of these breakthroughs is not limited to scientific credibility. In industrial settings, a step change in performance can reduce system size, lower cooling burden, improve power density, or enable designs that were previously impractical. For manufacturers and system integrators, that translates into differentiation potential and the ability to enter higher-value segments. For investors, it reframes risk: the opportunity is less about a single breakthrough product and more about whether a company can sustain a performance roadmap while scaling production and qualification at commercial speed.
Policy momentum and the demand signal from strategic priorities
Public-sector interest continues to shape demand by funding research, demonstration, and manufacturing initiatives that de-risk commercialization pathways. Programs associated with national energy and advanced technology priorities are supporting projects that target both end-use applications and production capability. Such support does not guarantee commercial success, but it does help bridge the gap between laboratory performance and field-ready systems, especially where capital intensity, qualification requirements, or scale-up complexity would otherwise slow private investment.
The policy environment is also reinforcing the importance of standards and interoperability. As more consortia and public agencies work to align expectations around performance verification and deployment, the regulatory direction leans toward reducing ambiguity rather than creating new barriers. That matters commercially because predictable qualification and measurement practices can shorten procurement cycles and give early movers a stronger case for adoption in infrastructure and industrial projects.
Demand-side shifts favoring power density and advanced computing
On the demand side, the most visible new driver is the pressure on power delivery in high-density environments, particularly in AI data centers and other facilities where energy throughput, space constraints, and reliability requirements are intensifying. HTS power delivery concepts are being piloted in contexts that simulate these operating conditions, and the successful demonstration of compact power delivery solutions points to a practical use case where superconducting cables can address real operational constraints. At the same time, demand from fusion energy and high-field magnet applications continues to provide a high-performance anchor for the technology roadmap, even if those applications follow longer development cycles.
This demand shift changes the commercial conversation. Traditional HTS applications have long relied on niche but stable use cases; the emerging mix adds demand sources that are larger in scale potential and more sensitive to power density and reliability. For procurement leaders and infrastructure planners, the implication is that superconductors should be evaluated not only on cost per unit but on system-level value, including reduced footprint, energy efficiency, and operational resilience in demanding environments.
PW Consulting Chemical & Energy Research Center
Supply-chain evolution and the scaling premium
A further driver is the evolving supply chain around conductor manufacturing. Demand growth is creating a premium for scale, consistency, and availability, and the companies that can expand production while maintaining performance quality will gain leverage. This dynamic is reshaping strategic behavior: some players are positioning around proprietary wire platforms, others are extending into integrated systems, and several are aligning with customer programs that require long development horizons. Scaling is not simply an operational target; it is becoming a strategic differentiator because the ability to supply qualified material reliably directly affects which applications can move forward on schedule.
The same dynamic applies to the broader ecosystem. As applications broaden, the market increasingly rewards partners who can coordinate conductor supply, cooling architecture, installation requirements, and qualification support. That integrated capability is difficult to replicate quickly, which gives incumbents with credible production and application experience a meaningful advantage. At the same time, new entrants with novel manufacturing approaches or targeted platform strategies can still find room to compete if they solve a specific bottleneck or serve a specialized application with clear performance economics.
Competitive Landscape: Leaders, Positioning, and Evolution
The competitive field includes mature manufacturers of superconducting wires and magnets, companies specializing in second-generation HTS tapes and cables, and newer entrants pursuing high-performance wire platforms and system-level power delivery. The group spans North America, Europe, Japan, China, and Russia, reflecting both long-standing technology bases and regional demand patterns. Rather than a single dominant leader, the market is characterized by differentiated capabilities, where advantage often comes from the combination of wire technology, application knowledge, and the ability to support qualification and deployment.
Several patterns stand out in how leaders are positioning themselves. One is the focus on advanced tape platforms and high-field magnet suitability, where performance density is becoming a defining attribute. Companies exhibiting rare-earth HTS tape developments and targeting fusion and high-field applications are building credibility in segments where performance thresholds are especially demanding. Another pattern is the move toward application-specific integration and commercial pilots, particularly in power delivery and grid-related use cases. Pilots that demonstrate practical power delivery in relevant environments help convert technical promise into commercial confidence and can serve as reference points for broader adoption.
Strategic differentiation and the shift toward integration
Differentiation is increasingly tied to more than material supply. In a market where cooling systems, reliability testing, and standards are central to adoption, manufacturers that provide usable solutions rather than standalone components are gaining strategic ground. This includes aligning wire performance with system constraints, supporting qualification for industrial use, and participating in standardization efforts that shape how performance is verified and compared. The companies that do this well are better placed to win projects that require multi-stakeholder confidence, where technical performance is necessary but not sufficient.
Another differentiator is the speed and credibility of scaling. In an environment where demand is beginning to outpace some supply capacities, the ability to expand production without sacrificing quality becomes a competitive lever. Board appointments, funding-supported production projects, and product catalog releases all signal how firms are trying to align capability with market timing. These moves are not isolated events; they are indicators of how companies plan to compete on scale, application breadth, and readiness for commercial deployment.
Market evolution: consolidation, specialization, and new entry points
The market structure appears likely to evolve through a mix of specialization and selective consolidation. On one hand, distinct technology niches—high-field magnets, power cables, fault current limiters, imaging systems, and advanced transport applications—create room for firms with deep application expertise. On the other hand, as projects grow in scale and as customers seek fewer, more capable partners, there is pressure for integration and strategic alignment around key platforms and regions. New entrants are likely to continue appearing where they can address a specific bottleneck, such as manufacturing speed, wire performance in a particular temperature and field regime, or compact power delivery for dense load centers.
For incumbents, the strategic challenge will be to preserve differentiation while building scale and credibility in the applications that matter most. For challengers, the opportunity lies in solving a concrete constraint that larger players have not yet fully addressed, then expanding from that foothold into adjacent applications. For buyers, the practical takeaway is that supplier selection should weigh not only current product specifications but also roadmap commitment, qualification support, and the ability to deliver in the specific operating context of the project.
Future Outlook: Three Trends Shaping the Next Few Years
Trend one: performance-led expansion into higher-value applications
Over the next three to five years, continued performance improvements are likely to pull HTS applications further into higher-value, higher-constraint use cases. Higher engineering current density and better high-field behavior will make superconductors more attractive in contexts where space, efficiency, and field intensity matter most. This expands the addressable market beyond traditional niches and increases the commercial stakes for companies with credible performance roadmaps. The opportunity for businesses is to align product development with the applications that can capture premium value, rather than competing solely on broad volume in commoditizing segments. The uncertainty is that performance claims must be matched by consistent manufacturing and credible qualification, or the market will reward only those claims that survive real-world scrutiny.
Trend two: scaling production and integration as decisive competitive factors
Scaling is likely to become a more explicit competitive battlefield. As demand broadens, the companies that can deliver qualified conductor material at volume, with dependable performance and acceptable lead times, will be positioned to capture the most important projects. At the same time, integration capability—linking conductor choice, cooling architecture, installation logistics, and standards-aligned testing—will increasingly influence procurement decisions. Businesses that build this integrated competence will have an advantage in winning multi-year infrastructure and industrial projects. The risk is that scaling without quality control or application support can damage reputation and slow future adoption, especially in sectors where reliability is paramount.
Trend three: stronger emphasis on standards, verification, and ecosystem alignment
A third trend is the likely deepening of standards and verification activity as commercial deployment expands. As more projects move into operation, buyers and regulators will demand clearer performance verification, interoperability expectations, and consistent qualification approaches. Industry consortia and reference measurement efforts are already shaping part of this environment, and their influence is likely to grow. This trend creates an opportunity for companies that actively participate in standards alignment and credible testing, because it can reduce ambiguity for customers and strengthen the commercial case for adoption. The uncertainty is that standards development is iterative and not always fast; companies that depend on rapid regulatory clarity may find progress uneven, requiring parallel investment in technical and commercial readiness.
Worldwide Low Temperature Superconductors Market
Strategic Actions for Decision-Makers
For manufacturers and technology developers
Focus investment on the intersection of performance, scale, and qualification. Advancing a wire or tape platform is necessary, but the differentiator will increasingly be the ability to produce consistently at scale and to support customers through qualification for industrial and infrastructure use. Prioritize the applications where performance improvements translate into the clearest system-level value, and build reference cases that reduce perceived risk for buyers. Engage early with standardization and measurement efforts, because credible participation can shorten adoption cycles and strengthen market positioning. Where possible, align production expansion with confirmed demand signals to avoid overbuilding capacity before it is needed, while still maintaining enough momentum to capture first-mover advantage in priority segments.
For investors and strategic capital allocators
Evaluate the market through the lens of application economics and execution risk rather than headline growth alone. The most attractive opportunities are likely to be those where performance gains directly improve system value, where scaling can be achieved with disciplined quality control, and where the company has a credible path to integration or strong partnership leverage. Assess whether a business is positioned around a durable platform, a specific high-value application, or a system-level solution, because each carries different risk and return profiles. Pay attention to signals that indicate readiness for commercialization, such as pilot completion, qualified production expansion, and engagement with industrial customers or standards bodies. Avoid assuming that technical promise alone will convert into market share; execution, consistency, and ecosystem relationships will determine which players capture lasting value.
For procurement, infrastructure planners, and demand-side buyers
Treat superconductor-based options as system-level investments rather than component purchases. Evaluate total cost, reliability, cooling requirements, installation constraints, and qualification status together, because the value case often depends on how well these elements fit the operating environment. Use pilot and demonstration results as evidence, but verify that performance claims are supported by credible measurement and testing practices relevant to your sector. For projects in power-dense or high-reliability contexts, consider how superconducting solutions may reduce footprint or improve efficiency where conventional alternatives are constrained. Build supplier evaluation criteria that include roadmap credibility, production readiness, and support for standards-aligned qualification, since these factors will influence long-term performance and operational risk more than initial specifications alone.
Superconductor Market
The strategic picture for the HTS market is one of expanding opportunity shaped by performance progress, scaling pressure, and a maturing standards environment. The window for positioning is open, but it is narrowing in the most valuable segments where execution and credibility increasingly separate leaders from the rest of the field. For organizations that need detailed segmentation data, regional and application-level projections, and tailored scenario planning, a fuller research set can provide the finer granularity required to translate these trends into specific investment, production, and procurement decisions.
For detailed analysis of this topic, please visit the official page: High Temperature Superconductor Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Rugged Tablet Market 2026: Beyond the 5.8% CAGR Story—Examining Growth Dynamics
By pmarketresearch, 2026-09-21
The Rugged Tablet Market: Navigating Volatility, AI Integration, and Supply Chain Shifts
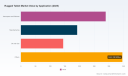
The rugged tablet sector stands at a strategic inflection point. What was once a niche hardware category defined primarily by durability and compliance certifications has transformed into a technology platform where artificial intelligence, edge computing, and supply chain resilience converge. With the market closing 2025 at approximately 972 million USD and projected to reach over 1.4 billion USD by 2032, the sector is expanding at a steady compound annual growth rate of 5.8 percent. This trajectory is neither explosive nor stagnant; it is the hallmark of a mature market undergoing structural re-invention rather than cyclical expansion. For executives and investors, the question is no longer whether rugged tablets will grow, but where value will concentrate as hardware differentiation shifts toward software integration, semiconductor access, and regulatory positioning.
PW Consulting
The market expansion from roughly 748 million USD in 2020 to the current baseline reflects a compounding alignment of defense modernization, industrial digitization, and field-service transformation. Growth has not been linear. Post-pandemic procurement cycles, semiconductor availability constraints, and shifting public-sector budgets introduced volatility that rewarded companies with flexible supply chains and diversified end-market exposure. Looking ahead, the forecast period through 2032 suggests that revenue gains will increasingly depend on higher-margin configurations, AI-enabled form factors, and regional supply chain restructuring rather than volume-driven commoditization. The market's trajectory is clear, but the competitive map beneath that trajectory is being redrawn.
Market Landscape and Core Tensions
The sector's fundamental dynamic is a tension between performance ambition and supply chain reality. Rugged tablets are engineered to function in extremes: temperature swings, dust immersion, impact shock, and electromagnetic interference. Historically, meeting those requirements meant premium pricing, slower innovation cycles, and dependence on specialized component suppliers. Today, the same durability thresholds are being paired with compute architectures that demand higher power delivery, advanced thermal management, and memory bandwidth. That pairing is exposing manufacturers to a new layer of complexity: ruggedness is no longer the hardest engineering problem, but it remains the most expensive one to maintain while integrating AI workloads and next-generation connectivity.
The first core challenge is the shifting hierarchy of what buyers value. In many deployments, ruggedness has become a baseline expectation rather than a differentiating advantage. Procurement teams in aerospace, defense, manufacturing, and field operations now evaluate devices through the lens of software ecosystem compatibility, device management scalability, and total cost of ownership across refresh cycles. Hardware that survives a six-foot drop is table stakes; hardware that integrates cleanly into AI-assisted workflows and field data architectures is where procurement attention concentrates. This shift is forcing manufacturers to decide whether they compete as device builders or as operational technology platforms.
A second challenge is the uneven cadence between product innovation and component availability. The industry has entered a phase in which long-horizon semiconductor lead times interact with short-cycle product roadmaps. When memory and microcontroller lead times extend beyond typical procurement windows, production schedules, configuration options, and launch timing all become harder to synchronize. This does not stop demand, but it reshapes fulfillment patterns, inventory strategies, and margin predictability. Manufacturers with diversified component sourcing and flexible bill-of-materials engineering are better positioned to absorb disruptions, while those dependent on concentrated semiconductor nodes face more volatile planning horizons.
A third challenge is regulatory and geopolitical pressure on the underlying materials and components that make rugged devices possible. The sector relies on displays, batteries, memory, and specialized substrates that are tied to critical mineral supply chains and electronics manufacturing geographies. Trade investigations, tariff frameworks, and export-control dynamics introduce uncertainty not only for cost but also for product compliance and sourcing continuity. This environment favors organizations that treat supply chain resilience as a strategic capability rather than a procurement function.
Key Drivers Shaping the Market
The market's direction is being shaped by a combination of technological, regulatory, demand-side, and supply-side forces. The most consequential of these are not operating in isolation; they are reinforcing one another and reshaping where competitive advantage can be built.
Technology Innovation and AI Migration to the Edge
One of the most significant shifts is the migration of AI capabilities from backend systems to field-deployed hardware. Rugged tablets are increasingly positioned as edge nodes rather than passive terminals. Recent product announcements show vendors building devices around processors designed for AI inference, extending battery architectures to support higher-performance compute, and layering MIL-STD and ingress protection certifications onto AI-capable platforms. This trend matters because it changes the purchase logic. A rugged tablet with local AI processing can support offline workflow assistance, image-based inspection, speech-to-text field documentation, and rapid device-side decision support. Those capabilities reduce dependency on uninterrupted connectivity and enable more autonomous field operations.
The technology trajectory is also visible in the broader computing architecture transition. Devices are being designed around processors that emphasize efficiency and integrated acceleration for AI tasks, which matters in environments where thermal envelopes and battery capacity are constrained. The result is a new product tier in which ruggedness and on-device intelligence are being offered as a combined value proposition rather than separate features. This creates an opening for manufacturers that can deliver robust hardware without sacrificing computational relevance, but it also raises the engineering bar for thermal design, power management, and software optimization.
Policy, Regulation, and Compliance as Market Architecture
Policy dynamics are increasingly shaping product roadmaps and sourcing strategies. Rugged tablets are heavily represented in defense, public safety, aerospace, and regulated industrial environments, where certification requirements act as both a barrier to entry and a competitive anchor. Military-grade standards, ingress protection ratings, and sector-specific compliance frameworks remain central to purchase decisions, especially in government and critical infrastructure procurement. At the same time, supply-side regulation around critical minerals and processed components is becoming more consequential. Investigations into processed critical minerals, broader ministerial frameworks for securing non-domestic supply, and periodic export-control suspensions all influence which component pathways are viable and at what cost.
For the rugged tablet market, this means regulation is not only a compliance burden; it is a structural force in supply chain design. Vendors that can demonstrate certification credibility while maintaining transparent sourcing and alternative component pathways are gaining an advantage in procurement conversations where risk tolerance is falling. The policy environment also rewards modularity and configuration flexibility, since regulatory shifts can alter which components are accessible, affordable, or compliant in specific regions.
Demand-Side Transformation in Field Operations
End-user demand is changing in ways that extend beyond sector-level growth. In manufacturing and heavy industry, the push toward predictive maintenance, digital work instructions, and real-time equipment data has increased the need for devices that can operate in harsh conditions while integrating with enterprise systems. In oil and gas and similar environments, the operational imperative is to reduce downtime and improve remote inspection workflows, which favors durable, connected devices with strong battery endurance. In aerospace and defense, the trend is toward devices that can support secure field workflows, rugged mobility, and integration with broader digital infrastructure.
Fully Rugged Tablets Market
A notable demand-side shift is the blending of commercial and operational requirements. Field personnel now expect interfaces and software experiences that resemble consumer-grade usability, while operations leaders still demand durability and manageability. That tension has accelerated the appeal of semi-rugged and fully rugged form factors that offer balanced trade-offs between protection, weight, and user experience. It also encourages device makers to invest in software ecosystems, enterprise integration, and device management tooling, because a rugged tablet that is difficult to deploy at scale loses real-world value regardless of its hardware specifications.
Supply Chain and Cost Structure Pressures
Cost structure dynamics are being reshaped by demand for advanced components and concentration risk in critical inputs. Rising prices and extended lead times for materials used in battery housings, displays, and conductive components have introduced upward pressure on bill-of-materials costs. These pressures are not uniform across all configurations, but they are especially visible in higher-specification devices where materials intensity and performance requirements intersect. At the same time, semiconductor prioritization patterns have made it more difficult to guarantee component access on predictable timelines, which affects production planning and inventory strategy.
Rugged Notebooks Market
This environment is pushing manufacturers toward several strategic responses. Some are designing for component substitution and broader supplier qualification. Others are shifting toward platform strategies that allow families of devices to share core components while varying levels of ruggedization, display quality, or compute capability. The most effective approaches combine engineering flexibility with procurement discipline, allowing companies to preserve margins while maintaining delivery reliability. In a market where durability remains non-negotiable, the ability to manage input volatility without compromising product integrity is becoming a differentiating capability.
Competitive Landscape and Leading Strategies
The competitive field includes established rugged-device specialists, diversified enterprise hardware players, and regional manufacturers with strong presence in defense and industrial channels. The market is moderately concentrated at the top, with a significant share held by a small group of leaders, but the broader roster remains diverse. That combination matters because the category spans multiple form factors, certification requirements, and vertical applications, making it difficult for any single product architecture to dominate across all use cases.
Zebra Technologies has built its position around rugged mobile computing with a strong orientation toward logistics, warehousing, and industrial workflow integration. Its strategy emphasizes scanning, enterprise connectivity, and deployment scalability rather than ruggedness alone. That positioning reflects a broader truth in the category: for many commercial users, value lies in how well a device fits into operational workflows and data systems, not just in its ability to withstand harsh conditions.
Getac and Panasonic Toughbook continue to serve as anchors in fully rugged and defense-facing segments. Getac's emphasis on fully rugged industrial tablets, customization, and MIL-STD compliance suits environments where device failure carries high operational risk. Panasonic's reputation for durable devices certified to military standards supports its strong presence in public safety, defense, and industrial deployments. Both companies benefit from long-standing credibility in high-stakes sectors, which helps in procurement cycles where trust, certification history, and service support weigh heavily.
Winmate, RuggON, and Durabook illustrate how manufacturers are evolving product portfolios to combine ruggedness with newer compute and AI capabilities. Durabook's recent Copilot+ PC tablet launch, with Intel Core Ultra processors and strong protection ratings, exemplifies the movement toward higher-performance rugged computing. RuggON's AI-driven tablet with MIL-STD-810H and IP65 certification shows similar intent, targeting construction, defense, and IoT-oriented deployments. These moves suggest that a growing segment of the market is being shaped by devices that aim to bridge field durability with modern AI-ready architectures.
Dell Rugged and Samsung Electronics bring the advantage of large enterprise ecosystems and broad brand familiarity. Dell's rugged Latitude devices and Samsung's Galaxy Tab Active Pro line both fit into larger mobility strategies for organizations that want rugged capability without decoupling from mainstream device management, procurement, or support relationships. Their presence adds competitive pressure on specialists to demonstrate not just durability but also integration simplicity and total cost of ownership.
Honeywell, DT Research, MobileDemand, and Emdoor Information round out a competitive map that remains segmented by vertical strength. Honeywell's rugged computing portfolio aligns with industrial, transportation, and public safety use cases. DT Research emphasizes healthcare, military, and logistics applications with specialized certifications. MobileDemand focuses on industrial tablets and mobile POS contexts, particularly in construction and warehouse settings. Emdoor Information has been active in presenting high-performance rugged tablets and AI laptops at major trade events, indicating a strategy oriented toward enterprise and industrial visibility and performance positioning.
Strategic Positioning and Differentiation
The clearest differentiation strategy in the current market is the combination of durability with AI-readiness and enterprise integration. Companies that can offer MIL-STD and ingress protection certifications alongside modern processor architectures, AI software partnerships, and manageable device fleets are building the strongest value narratives. Another differentiating axis is vertical specialization. Vendors that understand the procurement language, certification priorities, and workflow requirements of a particular sector are often able to command stronger positioning than generalists, especially in defense, public safety, and regulated industrial environments.
Partnerships are also becoming a strategic lever rather than a supporting tactic. Recent collaboration activity shows manufacturers linking hardware with software providers and platform ecosystems to accelerate AI capability integration and field-service functionality. This matters because rugged hardware alone is increasingly insufficient as a final value proposition; the ability to pair durable devices with intelligent software workflows is becoming a decisive factor in competitive evaluations.
Market Evolution and Structural Shifts
The competitive landscape is evolving along several directions at once. One is consolidation pressure at the high end, where established players with strong certification records, service networks, and vertical relationships are well positioned to defend share. Another is differentiation at the platform level, where new product cycles are creating opportunities for entrants or expanding players that can combine ruggedness with newer compute architectures and AI capabilities. A third is regional and supply-chain repositioning, as companies adjust sourcing and manufacturing pathways in response to minerals-related policy and component availability dynamics.
The net effect is a market that is not heading toward a single dominant architecture, but toward a layered competitive structure. Fully rugged devices will remain essential in the most demanding deployments. Semi-rugged devices will continue to capture users who need a balance of protection and usability. AI-capable rugged tablets will likely gain share as field operations increasingly depend on local intelligence, offline support, and tighter integration with enterprise data systems. The winners will be those who align product design, sourcing, and vertical go-to-market strategy with the specific risk and workflow profile of their target customers.
Future Outlook: Three Trends for the Next Three to Five Years
The next several years are likely to be defined by three interrelated trends. The first is the normalization of AI-enabled rugged devices as a distinct product tier. As more devices incorporate processors and software stacks designed for on-device intelligence, the category will increasingly be evaluated not only by survivability but by operational augmentation. This shift creates opportunities for vendors that can package rugged hardware with practical AI use cases, such as field inspection support, voice-assisted documentation, and offline workflow assistance. The opportunity is not simply to add a processor; it is to make AI usable in environments where connectivity, power, and environmental stress are all constraints.
The second trend is supply chain re-architecture. Critical mineral investigations, minerals ministerial frameworks, and periodic export-control dynamics are likely to keep sourcing strategy in sharp focus. Over the next few years, more manufacturers are expected to qualify alternative component pathways, regionalize certain supply relationships, and design for substitution flexibility. This trend favors organizations that invest early in supply resilience and transparent sourcing narratives, particularly in government and defense procurement where continuity risk is scrutinized closely.
The third trend is vertical specialization becoming more explicit in product strategy. Rather than positioning rugged tablets as generic durable devices, vendors are increasingly aligning form factors, certification sets, and software partnerships with the requirements of aerospace and defense, manufacturing, oil and gas, healthcare logistics, and field service. This trend creates stronger competitive moats in sectors where procurement processes are relationship-heavy and certification-driven, but it also requires deeper domain expertise and more tailored service models.
These trends carry both opportunity and uncertainty. AI integration can unlock higher-value deployments, but only if software, device management, and user training are treated as part of the product. Supply chain diversification can reduce risk, but it can also raise short-term costs and complicate engineering coordination. Vertical specialization can deepen customer relationships, but it can limit scale advantages if pursued too narrowly. Executives should therefore treat these trends as a portfolio of choices rather than a single direction.
Strategic Implications for Decision-Makers
Manufacturers should decide early whether the strategic goal is category breadth or vertical depth. A breadth strategy depends on modular platforms, broad certification coverage, and flexible sourcing to serve multiple sectors. A depth strategy depends on concentrated domain expertise, tailored software partnerships, and strong procurement relationships in selected verticals. Both can work, but they require different engineering, sales, and supply chain investments. In the current environment, AI-readiness and component resilience should be treated as enabling capabilities for whichever strategy is chosen, not as optional upgrades.
Investors should evaluate the market with attention to platform transitions and sourcing exposure rather than headline growth alone. Revenue expansion is expected, but margin quality will increasingly depend on device mix, software-enabled value, and the ability to manage component and materials volatility. Companies that are building AI-capable rugged platforms, securing supply pathways for critical inputs, and aligning with high-trust verticals are better positioned for durable advantage than those competing primarily on ruggedness as a standalone attribute.
Procurement leaders and operational technology decision-makers should approach rugged tablet selection as a platform decision with downstream implications for workflow, manageability, and supply continuity. Device evaluation should extend beyond drop ratings and ingress protection to include AI compatibility, enterprise integration, support models, and component sourcing resilience where applicable. In sectors sensitive to regulatory and supply-chain uncertainty, procurement teams may benefit from understanding not only which device is selected, but how the vendor manages certification continuity and component substitution risk over the asset life cycle.
For stakeholders seeking deeper segmentation, configuration-level demand patterns, regional procurement dynamics, and company-specific benchmarking, a more detailed research package can provide the granularity needed to turn these strategic themes into operational decisions. The full report expands on the segmentation structure, heat points in supply chain exposure, competitive positioning across major manufacturers, and scenario-based outlooks that support planning under variable regulatory and component-availability conditions.
For detailed analysis of this topic, please visit the official page: Rugged Tablet Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Zeolite Market 2026: What the 5.11% CAGR and Asia Pacific Surge Really Mean for Growth
By pmarketresearch, 2026-09-21
Navigating the Zeolite Market: Strategic Trends and Commercial Opportunities Through 2032
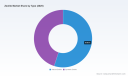
The global zeolite market is entering a phase of steady expansion, defined by a compound annual growth rate of 5.11 percent across the projection window ending in 2032. Revenue has moved from 140.0 million USD in 2020 to a projected 332.0 million USD by 2032, reflecting both established industrial reliance and emerging demand vectors. The trajectory is not a straight line. The 2020 to 2025 period shows a market that recovered from pandemic-era supply distortions, with annual figures climbing from 147.13 million USD in 2021 through 182.53 million USD in 2023 and reaching 205.0 million USD in 2025. The forecast interval from 2026 to 2032 projects continued growth, with valuations moving through 221.65 million USD in 2026, 260.95 million USD in 2028, and 283.7 million USD in 2030 before approaching the 308.99 million USD and 332.0 million USD marks in 2031 and 2032 respectively. This corridor signals a market that has shifted from recovery mode to structural expansion, where volume growth, application diversification, and performance specifications increasingly determine competitive positioning.
Behind these figures lies a landscape shaped by concentration and complexity. The top three participants account for roughly 45.0 percent of revenue, while the top five firms command approximately 62.0 percent. Such concentration does not imply stagnation. It points to a market where scale, formulation expertise, and application-specific engineering create meaningful barriers, yet also leaves room for specialized entrants, regional suppliers, and technology-driven disruptors to capture niche value. For executives and investors, the core question is not whether the zeolite market will grow, but how value will be allocated across types, applications, and geographies as performance requirements tighten and end-use industries recalibrate their sourcing strategies.
Structural Pressures and Inflection Points
Three interlocking challenges define the current market environment and will shape strategic choices over the next several years. The first is the tension between natural and synthetic supply pathways. Natural zeolite offers cost advantages and adequate performance for bulk applications, but its variable purity and inconsistent cation exchange characteristics limit its use in high-stakes catalysis and emission control. Synthetic zeolite delivers reproducible porosity, tailored crystal morphology, and reliable performance under demanding operating conditions, but its production requires precise hydrothermal synthesis, controlled calcination, and consistent raw material inputs. The market must balance these trade-offs as downstream customers demand higher efficiency, lower regeneration energy, and longer service life. Companies that can reliably bridge the cost-performance gap through improved synthesis yield, better seed crystal control, or hybrid processing routes will capture incremental share.
The second challenge centers on feedstock volatility and energy intensity. Zeolite manufacturing is sensitive to silica and alumina sources, alkali flux availability, and thermal processing costs. Regional supply chain disruptions, shifting energy pricing, and tightening logistics networks can compress margins or delay capacity expansion. The implication is that cost leadership will increasingly depend on location strategy, integrated feedstock sourcing, and process efficiency rather than on sheer volume. Firms that treat supply chain resilience as a design parameter, rather than a contingency plan, will be better positioned to protect margins when input costs fluctuate.
The third challenge is regulatory and performance pressure from end-use sectors. Environmental compliance, emissions reduction targets, and industrial efficiency mandates are raising the bar for catalyst and adsorbent performance. In refining, petrochemical processing, and emission control, operators need materials that maintain activity over extended cycles, withstand poisons and fouling, and allow lower-temperature regeneration. In separation and purification applications, selectivity and moisture management are becoming critical as processes seek to reduce energy consumption and waste. These requirements do not merely increase demand; they change the basis of competition. Suppliers that can demonstrate application-specific performance, provide technical support, and co-develop formulations with customers will differentiate more effectively than those competing primarily on commodity pricing.
Key Drivers Reshaping the Market
Technology Innovation and Process Breakthroughs
Advances in zeolite synthesis, modification, and characterization are altering the market's performance ceiling. Controlled hydrothermal pathways, structured template use, and improved post-synthesis treatments are enabling more precise pore architecture, narrower crystal size distribution, and enhanced thermal stability. These improvements matter because zeolite value is increasingly tied to application-specific behavior rather than generic material properties. In catalytic contexts, shaping, binder selection, and active site dispersion determine conversion efficiency and lifecycle cost. In adsorption and separation, surface chemistry, moisture handling, and regeneration dynamics dictate operating economics. The market is therefore shifting from a volume-driven model to a performance-driven model, where incremental material improvements translate directly into downstream savings and compliance advantages.
Innovation is also visible in the integration of zeolites into broader process systems. Hybrid adsorbent-catalyst configurations, structured packing, and tailored pellet or extrudate geometries are reducing pressure drop, improving mass transfer, and extending service intervals. Digital process monitoring and performance modeling further increase the value of consistent material quality, because operators can optimize regeneration cycles and throughput when material behavior is predictable. As these capabilities mature, the commercial advantage moves toward suppliers that combine material science with application engineering, rather than those offering undifferentiated bulk product.
Zeolite Molecular Sieves Market
Policy and Regulatory Dynamics
Policy frameworks continue to shape demand patterns by setting performance thresholds and encouraging cleaner industrial processes. Emissions control requirements, fuel and feedstock specifications, and industrial efficiency standards are expanding the use of zeolites in catalytic formulations and separation systems. Regulatory momentum does not operate in isolation. It interacts with operational economics: when compliance requires lower emissions or higher yield, materials that deliver performance with lower energy input become more attractive. This creates a dual incentive for zeolite adoption, combining compliance necessity with total cost of ownership benefits.
The regulatory environment also influences sourcing and qualification behavior. In industries where material consistency and traceability matter, qualification cycles can be long, and switching costs can be high. That dynamic rewards established suppliers with documented performance records and technical support capabilities. At the same time, it creates an opening for new entrants that can offer demonstrable performance gains, faster qualification support, or more flexible commercial terms. Policy-driven demand is therefore a growth engine, but it also raises the bar for evidentiary support and customer collaboration.
Demand-Side Shifts in End-Use Industries
Downstream industries are re-evaluating material choices through the lens of efficiency, durability, and process integration. In refining and petrochemical operations, the emphasis is on catalyst systems that improve conversion, reduce coke formation, and allow more flexible operating windows. In emission control, the priority is long-life performance under variable load conditions and resistance to poisoning. In adsorption and separation, operators seek materials that reduce regeneration energy and maintain selectivity under fluctuating feed compositions. These demand-side priorities are pushing zeolite specifications toward higher consistency, better mechanical strength, and more tailored surface properties.
Consumer and corporate behavior also feed into this evolution indirectly. Sustainability commitments, waste reduction goals, and resource efficiency programs encourage industrial buyers to evaluate lifecycle impact rather than upfront price alone. When a zeolite-based system can extend cycle life, reduce waste streams, or lower regeneration energy, the business case strengthens even if the material premium is nonzero. This shift toward lifecycle thinking expands the addressable value of higher-performance zeolites and encourages suppliers to frame value in operational terms rather than unit price alone.
Supply Chain and Cost Structure Evolution
Cost structures are being reshaped by feedstock access, energy economics, and regional manufacturing strategies. Where silica and alumina sources are readily available and processing energy is stable, producers can compete on consistency and margin protection. Where feedstock logistics are constrained or energy costs are volatile, the edge shifts to integrated sourcing, localized production, or formulation efficiency that reduces dependency on variable inputs. The market is therefore becoming more sensitive to where and how zeolites are made, not just how much is produced.
Another cost-related dynamic is the growing importance of yield and throughput optimization. Small improvements in synthesis efficiency, crystallization control, and drying/calcination energy use can compound into meaningful margin differences at scale. Suppliers that invest in process control, quality consistency, and waste reduction can convert operational discipline into commercial advantage. For buyers, this means that supplier selection increasingly hinges on reliability, technical support, and total delivered performance, not just headline pricing.
Competitive Landscape and Strategic Positioning
Leading Players and Differentiation Paths
Clariant has built a strong position in specialty zeolite powders for chemical and environmental applications, supported by broad development and manufacturing capabilities across multiple zeolite types. Its differentiation comes from application breadth, formulation flexibility, and the ability to serve customers that require tailored material properties rather than commodity consistency alone. In a market where performance specifications are tightening, that breadth allows Clariant to align material design with end-use requirements and to capture value in segments where customization matters.
BASF competes through a comprehensive zeolite powder portfolio and a strong orientation toward commercial catalysts designed for specific applications. Its advantage lies in integrating zeolite materials into catalyst systems that address target operating conditions, which positions the company to serve customers who value application-engineered solutions over stand-alone material supply. In segments where catalyst performance drives conversion economics and process stability, this system-level approach strengthens commercial relevance.
Zeolyst International operates as a global leader in specialty zeolite powders and catalysts for catalysis, adsorbents, hydrocracking, refineries, and clean air applications. Its positioning reflects deep focus on high-value industrial uses where material consistency, mechanical robustness, and application support are critical. By concentrating on specialty rather than bulk markets, Zeolyst can emphasize performance reliability and technical partnership, which are especially valuable in qualifying environments and long-cycle industrial operations.
PQ Group Holdings and Ecovyst are linked through a joint venture structure that combines zeolite catalyst product strength with emission control, hydrocracking, and petrochemical applications. The shared exposure to Zeolyst assets creates a blend of manufacturing capability and application focus, allowing the combined entity to serve segments where emission control and refining performance intersect. In markets where regulatory pressure and operating efficiency both matter, this dual orientation supports a value proposition rooted in proven industrial use and specialized catalyst supply.
Grace emphasizes zeolite molecular sieves and crystalline products for catalysis and adsorbent applications, with a focus on precise separation and performance characteristics. Its differentiation comes from product specificity and the ability to address processes where selectivity, purity, and controlled adsorption behavior are decisive. As separation efficiency becomes more closely tied to energy and waste outcomes, Grace's positioning aligns with buyers who prioritize functional precision over general-purpose supply.
Market Structure Evolution: Consolidation, Differentiation, and Entry
The current concentration level suggests a market where scale and technical capability reinforce each other, but it does not eliminate room for evolution. Consolidation is likely to continue where larger players can invest in application development, qualify new customers more efficiently, and absorb process improvements that smaller competitors cannot fund as easily. At the same time, differentiation will remain a potent strategy, particularly in specialty segments where customers require tailored pore structures, binder systems, shapes, or performance guarantees.
PW Consulting
New entry is less likely to succeed through commodity competition and more likely to emerge through focused technology, regional supply advantages, or application-specific service models. A newcomer that can demonstrate superior consistency, lower regeneration demands, faster qualification support, or cost-effective hybrid production could carve out meaningful share in targeted segments. The broader trend is therefore one of parallel movement: scale players strengthening system-level integration and application support, specialty players deepening technical focus, and selective new entrants pursuing differentiated niches. For strategic planners, this means that competitive response should be based on segment definition, customer qualification dynamics, and the relative importance of performance versus price in each application.
Worldwide Zeolite Adsorbents Market
Forward-Looking Trends and Commercial Implications
Trend One: Performance Specification Will Drive Segmentation More Than Volume Alone
Over the next three to five years, the market will increasingly reward materials that meet tighter performance criteria in specific applications. This does not mean bulk demand will disappear; it means that premium value will concentrate where consistency, longevity, and application fit are provable. The commercial implication is that suppliers should invest in application data, qualification support, and lifecycle economics, while buyers should assess not only unit cost but also regeneration energy, replacement frequency, and process stability. The risk is that suppliers focused only on volume may face margin erosion as customers migrate toward higher-specification offerings where the value case is clearer.
Trend Two: Regional Sourcing and Supply Resilience Will Become Procurement Priorities
As feedstock access, energy costs, and logistics complexity continue to influence production economics, procurement strategies will place greater weight on regional availability, supply continuity, and qualified alternate sources. This trend favors suppliers with localized manufacturing, stable input relationships, and transparent quality systems. For buyers, it argues for dual sourcing where feasible and for evaluating suppliers on delivery reliability and technical support as well as price. The uncertainty lies in the pace and direction of energy and logistics cost changes, which can shift regional competitiveness faster than long-term planning cycles anticipate.
Trend Three: Cross-Application Integration Will Expand Value Capture
Zeolites are increasingly evaluated as part of integrated process solutions rather than standalone materials. In catalysis, adsorption, and separation, the ability to link material properties with equipment design, regeneration strategy, and operating parameters increases total value. Suppliers that can support system-level optimization will be better positioned to capture value beyond the material itself, while customers that adopt integrated thinking can unlock efficiency gains that are not visible in siloed purchasing decisions. The main risk is that integration demands closer collaboration and longer qualification cycles, which can slow short-term adoption even as long-term value improves.
Strategic Actions for Decision Makers
For Manufacturers and Material Suppliers
- Prioritize application-engineering capability alongside material production. Customers in refining, emission control, and separation increasingly value suppliers who can help optimize performance in context, not just deliver consistent powder.
- Invest in process control and yield optimization to protect margins against feedstock and energy variability. Small improvements in crystallization, drying, and calcination efficiency can compound into durable cost advantages.
- Segment the portfolio deliberately between cost-effective bulk supply and higher-specification specialty offerings. Clear differentiation helps defend pricing where performance matters and prevents commoditization in segments where customers are willing to pay for reliability and technical support.
For Investors and Strategic Buyers
- Evaluate exposure by application and specification level rather than by broad market size alone. Growth is real, but value capture will concentrate where performance, qualification, and lifecycle economics are strongest.
- Assess supplier resilience through feedstock access, regional manufacturing footprint, and quality consistency. In a market shaped by energy and logistics variability, these factors can matter as much as product specifications.
- Look for value in partnerships and selective consolidation where application breadth or technical support creates durable advantages, while remaining cautious about commodity-driven price competition in undifferentiated segments.
For Procurement and Operations Leaders
- Expand evaluation criteria beyond unit price to include regeneration energy, service life, replacement frequency, and process stability. Total cost of ownership often favors higher-consistency materials in demanding applications.
- Build qualification pathways early for new or improved zeolite grades. Downtime, conversion loss, and compliance risk can outweigh apparent material savings if switching occurs late or without adequate testing.
- Use regional sourcing and qualified alternate suppliers to reduce exposure to feedstock and logistics disruptions, especially where production continuity and specification consistency are critical to operations.
The zeolite market is moving from a phase of recovery to a phase of specification-led growth. The revenue corridor through 2032 reflects continued expansion, but the more important story is how value will be allocated across natural and synthetic supply, across application segments with different performance demands, and across suppliers with different capabilities in application engineering and supply resilience. For decision makers, the practical imperative is to align strategy with where performance, qualification, and total operating economics create durable advantage, and to secure detailed market intelligence that supports segment-level choices rather than broad generalizations. A comprehensive research report can provide the deeper segmentation detail, regional nuance, and customized scenario analysis needed to translate these strategic themes into concrete sourcing, investment, and product decisions.
For detailed analysis of this topic, please visit the official page: Zeolite Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Makeup Brushes Market: 5.4% CAGR and the Natural Bristle Shift Reshaping Growth
By pmarketresearch, 2026-09-21
The Makeup Brushes Market at an Inflection Point: Strategic Trends and Commercial Opportunities
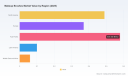
The global makeup brushes market has entered a phase of structural transformation. Valued at approximately 1.6 billion USD in 2025, the market has grown steadily from 1.05 billion USD in 2020, reflecting a compound annual growth rate of 5.4 percent through the forecast horizon extending to 2032. By the close of the projection period, revenue is expected to approach 2.6 billion USD. This trajectory signals more than incremental expansion; it points to a market where consumer expectations, material innovation, regulatory pressure, and supply chain reconfiguration are converging to reshape competitive dynamics. For manufacturers, brand owners, and investors, the question is no longer whether the market will grow, but how value will be allocated across segments, geographies, and business models over the next several years.
Hairbrush Market
Market Snapshot and Structural Context
The makeup brushes market has demonstrated resilient demand across economic cycles, supported by the broader expansion of professional and consumer beauty routines. Growth has been underpinned by higher utilization frequency, a widening palette of application techniques, and the normalization of brush-based makeup application as a standard beyond niche or professional use. The market’s expansion from 2020 to 2025 reflects both post-pandemic recovery in personal care spending and the continued penetration of brush-based application in everyday routines. Looking ahead, the forecast period points to a measured but consistent climb, with acceleration expected as product innovation and channel expansion reinforce one another.
Despite the positive trajectory, the market faces a small number of decisive challenges that will separate scalable operators from those constrained by cost, compliance, or positioning. First, input cost volatility and trade policy friction are reshaping the economics of production and sourcing. Second, material and sustainability expectations are changing procurement criteria, pushing manufacturers to justify brush construction beyond performance alone. Third, differentiation is becoming harder as category familiarity increases, forcing players to compete on craftsmanship, customization, and brand narrative rather than basic functionality. These pressures are not isolated; they interact to influence pricing power, margin structure, and the pace at which new capacity can be commercialized.
Key Drivers Reshaping the Market
Material Innovation and Performance Engineering
Material choice remains one of the most consequential decisions in brush design, influencing application feel, durability, washability, and cost. The market continues to see a balance between natural and synthetic options, with each serving distinct performance profiles and consumer preferences. Natural fibers are still associated with elegance, softness, and blending quality, while synthetic alternatives have broadened their appeal through consistency, 내구성, and evolving feel characteristics. The commercial significance lies in the fact that performance tradeoffs are narrowing. Manufacturers are investing in fiber engineering, filament grading, and ferrule construction to improve snap, shed resistance, and rinse behavior. That matters commercially because it allows product lines to target multiple use cases without compromising on perceived quality. As application techniques become more refined, consumers and professionals alike are evaluating brushes not just by whether they apply product, but by how precisely they control placement, blend, and finish.
Recent product launches illustrate how material and design improvements are becoming a visible competitive lever. In early 2026, Jenny Patinkin introduced a sustainable luxury powder and bronzer brush built entirely from post-consumer recycled materials, including nylon bristles and an aluminum ferrule. This launch signals that premium positioning can coexist with recycled inputs, expanding the commercial vocabulary for sustainability beyond basic compliance. Around the same time, Alpine launched face brushes with matching eye brushes featuring updated handle designs, emphasizing coordinated sets and tactile differentiation. These moves show that innovation is not limited to fiber chemistry; it also extends to set architecture, user experience, and visual identity. For commercial stakeholders, the implication is clear: material and design innovation are increasingly intertwined, and the strongest offerings are those that connect performance claims with recognizable product language.
Regulatory Pressure and Trade Cost Realignment
Trade policy has become a central variable in the makeup brushes market’s cost structure. US tariff dynamics have raised the effective cost of imported brushes and related components, with baseline rates and higher surcharges pushing average rates higher by early 2026. Higher duties on Chinese-origin imports have increased landed costs for many finished brushes and components, altering the economics of offshore production and cross-border distribution. At the same time, the broader beauty sector has faced elevated average tariff rates on imports, with combined rates on certain Chinese goods reaching levels that directly affect cosmetic brush supply chains. In some cases, tariff exposure on packaging and component inputs has reached levels that drive price increases, particularly for smaller brands with limited ability to absorb cost shocks.
This regulatory environment is prompting reactive and strategic responses. Some large players have chosen to reinvest tariff refunds into price reductions on makeup products, including brushes, in order to protect volume and consumer perception after cost increases. That approach highlights a broader strategic tension: whether to pass costs through, compress margins, or offset pressure through operational efficiency and sourcing changes. For the market overall, the consequence is a reconfiguration of cost-sensitive volume flows and a greater premium on supply chain flexibility. Companies that can diversify sourcing, manage duty exposure, and maintain consistent lead times are gaining an advantage in an environment where cost predictability is increasingly scarce.
Demand-Side Shifts in Consumer and Professional Use
Demand is being shaped by two reinforcing dynamics: higher standards for application quality and broader adoption of brush-based routines across consumer segments. Consumers are increasingly attentive to finish quality, hygiene, and tool longevity, while professional users continue to prioritize precision, control, and repeatability. This dual demand structure is expanding the commercial relevance of both premium and value-oriented offerings, but with different winning criteria in each tier. In premium segments, buyers are evaluating craftsmanship, material provenance, and design coherence. In more price-sensitive segments, the battleground is reliability, set composition, and the perceived value of multi-piece kits.
PW Consulting
The market is also benefiting from the continued normalization of at-home application as a routine rather than a specialized activity. Brush use is no longer confined to advanced enthusiasts; it is becoming part of standard grooming and makeup workflows. That broadening user base increases the importance of intuitive design, clear use cases, and accessible product architectures. It also encourages brands to think in terms of system selling, where brushes are positioned alongside application habits, tutorials, and routine-building narratives. The commercial opportunity lies in converting casual users into repeat purchasers by reducing friction in product choice and improving perceived outcomes.
Supply Chain Reconfiguration and Production Geography
Production geography is being reconsidered as companies weigh cost, lead time, duty exposure, and operational resilience. Recent operational updates from factories involved in professional makeup brush production indicate ongoing attention to capacity, process standardization, and geographic diversification. Updates from facilities in Cambodia and other production locations reflect a wider interest in expanding or consolidating manufacturing footprints beyond traditional hubs. This matters because brush manufacturing is labor-intensive in finishing, assembly, and quality inspection, making location decisions sensitive to labor availability, process maturity, and export logistics.
At the same time, supply chain pressure is encouraging a more deliberate approach to supplier relationships and production control. Some manufacturers are deepening OEM and ODM capabilities to serve brand clients with customized specifications, while others are strengthening in-house control over ferrule fitting, fiber insertion, and trimming to protect consistency. The strategic direction is toward more transparent production pathways and more flexible order structures, especially for brands that need to balance speed, customization, and cost. In practice, this means that competitive advantage is increasingly defined by the ability to deliver consistent quality across varying order sizes, maintain compliance with material and labeling expectations, and adapt quickly when sourcing conditions shift.
Competitive Landscape and Leading Strategies
Established Manufacturers and Positioning Logic
The competitive field includes manufacturers with distinct positioning across price tiers, materials, and customer models. Guangzhou Yafei Makeup Brush Co., Ltd. operates as a professional cosmetic brush manufacturer offering a broad range of makeup brushes with custom options, positioning itself around breadth of catalog and flexibility for brand clients. Ningbo Chungfat Brushes Factory, Ltd. extends beyond makeup brushes into related categories such as hair brushes, combs, nail brushes, and bath tools, suggesting a strategy built on cross-category manufacturing scale and export orientation. Fay Cosmetic Brushes Co., Ltd., active since 2010, emphasizes OEM and ODM customization with multiple production facilities, indicating a focus on repeatable custom production and capacity to serve varied brand requirements.
On the premium side, Hakuhodo Co., Ltd. represents a long-standing Japanese manufacturer of handmade premium makeup brushes using fine natural and synthetic materials, with a heritage that supports a craftsmanship-based positioning. Cangzhou Hexin Brush Making Co., Ltd., operating as part of HWASHIN CORPORATION, reflects a larger corporate manufacturing footprint in cosmetic and makeup brushes, where scale, process control, and integrated operations can support consistent output and broader commercial reach. These profiles illustrate a spectrum from customization-focused manufacturers to heritage-led premium makers and scale-oriented producers. The strategic lesson is that different buyers value different combinations of speed, customization, materials, and brand story, and the most resilient manufacturers are those that can clearly own a position rather than compete generically across all attributes.
Strategic Differentiation and Recent Moves
Recent product and operational activity points to several differentiation paths. In material and sustainability terms, recycled-content brushes and updated handle designs indicate that brands are seeking visible points of difference that resonate with conscious consumption and aesthetic preferences. In commercial terms, customization capabilities and multi-facility production are becoming important for serving brand partners who need variations in ferrule design, handle aesthetics, filament blends, and packaging-ready finishes. The direction of travel is toward more modular product architecture, where core construction can be adapted without sacrificing quality or lead time.
There is also a growing distinction between manufacturers that compete primarily on volume and cost and those that compete on perceived quality and brand alignment. The latter group often relies on material narrative, finishing quality, and design consistency to support pricing. The former must lean on process efficiency, sourcing discipline, and order flexibility. Both models can be viable, but they require different operational capabilities and different customer engagement strategies. Market evolution is likely to reward clarity of positioning, because buyers are increasingly able to compare offerings across performance, aesthetics, and procurement criteria.
Market Structure: Consolidation, Fragmentation, and New Entry
The market structure remains relatively fragmented, with a meaningful share concentrated among leading players but ample room for specialized manufacturers and regional suppliers. Concentration levels indicate that the largest companies hold a notable share, yet the market is broad enough to accommodate niche craftsmanship, regional production, and custom-service models. This combination creates opportunities for both consolidation and differentiation. Larger producers may gain from scale in sourcing, standardized quality control, and broader distribution relationships. Smaller or specialized producers may gain from customization, faster iteration, and stronger brand partnerships in premium or boutique segments.
New entry and re-entry are likely in areas where trade cost shifts, material innovation, or regional production incentives alter the economics. factories updating operations in new locations suggest that production geography is still being optimized, and that some brands are looking for alternative sourcing pathways. At the same time, the bar for successful entry is rising because buyers have more access to product information, material claims, and comparative reviews. Entrants will need a clear value proposition, whether that comes from material innovation, design distinctiveness, customization speed, or a compelling brand narrative.
Future Trends and Commercial Implications
Premiumization with Verifiable Material Claims
One of the most visible trends is the continued push toward premiumization, supported by material storytelling and design refinement. The commercial opportunity lies in aligning premium pricing with verifiable attributes such as fiber quality, ferrule durability, wash performance, and sustainable sourcing choices. Buyers are increasingly skeptical of vague claims, so the winning offerings will likely be those that can connect premium feel with traceable construction and repeatable quality. For manufacturers, this means investing in consistent finishing, tested material combinations, and product language that accurately reflects what the brush delivers. For brand owners, it means selecting tools that can be credibly positioned within a broader routine or ritual, rather than relying on aesthetics alone.
Sustainability as Procurement Criteria, Not Peripheral Messaging
Sustainability is increasingly embedded in purchasing decisions rather than treated as add-on messaging. Recycled materials, durable construction, and longer service life are becoming relevant to both consumer perception and brand compliance requirements. The trend suggests that sustainability will matter most when it is linked to product performance and lifecycle value. A brush that is marketed as sustainable but fails on shedding, shape retention, or ease of cleaning will undermine the claim. Conversely, an offering that combines recycled inputs with reliable application and durable construction can support both commercial and reputational goals. The risk is greenwashing fatigue; the opportunity is to make sustainability operational by designing it into materials, processes, and product longevity.
Supply Chain Agility as a Margin Defense
As tariff exposure and sourcing costs remain unpredictable, supply chain agility will likely become a defining competitive capability. Companies that can shift order volumes, qualify alternative production sites, and maintain stable lead times will be better positioned to protect margins without sacrificing service levels. This trend favors organizations that invest in supplier diversity, documentation discipline, and flexible manufacturing arrangements. It also favors brands that can plan assortments with cost variation in mind, balancing higher-duty items with lower-exposure alternatives where feasible. The uncertainty lies in the durability of current trade conditions and the speed with which new sourcing patterns become stable. Until then, flexibility is a strategic asset.
Strategic Actions for Decision Makers
For Manufacturers
Own a clear positioning rather than competing on every attribute. Decide whether the business will win through customization speed, craftsmanship narrative, material performance, or cost-efficient scale, and build processes around that choice. Strengthen consistency in ferrule fitting, filament placement, and finishing because quality variation erodes trust quickly in tool categories. Where possible, expand modular production capabilities so that handle, ferrule, and bristle variations can be managed without sacrificing lead time. Monitor trade and duty exposure continuously, and evaluate whether certain SKUs or component inputs should be sourced differently to reduce volatility.
For Investors
Look for operators with defensible differentiation and resilient commercial models. In this market, durability of advantage often comes from material expertise, customization relationships, and the ability to maintain quality across order sizes. Assess whether a company’s growth depends on transient cost advantages or on genuine product and service differentiation. Pay attention to sustainability positioning only when it is supported by product performance and manufacturing discipline, because the market is increasingly sensitive to the gap between claim and experience. Also consider how exposed a business is to tariff-sensitive sourcing, and whether it has alternatives that can preserve margin under shifting trade conditions.
Cosmetics Brushes Market
For Brand Owners and Procurement Teams
Treat brush selection as a strategic part of product experience rather than a commodity accessory. Prioritize tools that match the intended application method, user skill level, and routine architecture. When sourcing, balance price with consistency, durability, and the ability to customize where it matters most. Build supplier relationships that allow for clear specifications, repeatable quality, and responsiveness when trade or material conditions change. Evaluate sustainability claims against actual construction and lifecycle performance to avoid disconnects between messaging and consumer experience.
Closing Perspective
The makeup brushes market is moving from broad-based growth toward a more competitive environment where execution quality, material credibility, and supply chain flexibility determine outcomes. The combination of steady demand expansion, evolving material expectations, and shifting trade costs creates both opportunity and pressure. Companies that define their positioning clearly, invest in consistent manufacturing quality, and adapt sourcing strategies to a less predictable cost environment are best placed to capture value. For decision makers seeking deeper segmentation, company-level benchmarks, and tailored assessment of sourcing or product strategy, the full PW Consulting market report provides more granular data and structured recommendations to support next-step planning.
For detailed analysis of this topic, please visit the official page: Makeup Brushes Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
BCTMP Market 2026: The Real Drivers Behind the 5.25% CAGR Growth Trajectory
By pmarketresearch, 2026-09-21
Beyond Volume: Strategic Realignment in the Bleached Chemi-ThermoMechanical Pulp Market
The Bleached Chemi-ThermoMechanical Pulp (BCTMP) market stands at a structural inflection point. Over the past five years, the segment has expanded steadily, with industry revenue climbing from approximately $185 million in 2020 to an estimated $240 million in 2025. Forward-looking projections indicate the market will surpass $345 million by 2032, translating to a compound annual growth rate of roughly 5.25% between 2026 and 2032. This trajectory is not merely a function of incremental demand growth; it reflects a broader reconfiguration of fiber economics, regulatory expectations, and downstream application requirements. BCTMP has carved out a strategic middle ground between mechanical pulps and fully chemical pulps, offering producers a high-yield, energy-efficient pathway to deliver brightness and bulk properties that align with modern paperboard, tissue, and specialty printing formats. Yet the reliability of this middle ground is being tested by tightening environmental mandates, shifting consumer-facing material preferences, and capital allocation pressures across a fragmented but increasingly active producer base.
For executives and strategic planners navigating fiber procurement, capacity planning, or portfolio allocation, the BCTMP segment warrants close attention precisely because it sits at the intersection of cost discipline and performance customization. The market’s growth is real, but its composition is changing. Volume expansion alone no longer guarantees margin resilience or customer retention. The following analysis maps the forces reshaping the BCTMP landscape, distinguishes durable drivers from transient cycles, and frames the strategic choices that will separate adaptive operators from those exposed to regulatory friction and competitive squeeze.
Market Context and Core Challenges
The current BCTMP market is defined by three overlapping realities. First, demand continues to track upward, but the growth is uneven across end-use categories and geographies, creating pockets of oversupply in mature paper segments and acute tightness in tissue and lightweight packaging grades. Second, the industry is confronting a regulatory and sustainability transition that is no longer a future concern but a present-day capital and operational constraint. Third, cost structures are being reshaped by input volatility, energy integration requirements, and the need to maintain consistent pulp specifications under more complex bleaching and effluent management protocols.
One of the most immediate challenges is the tension between capacity additions and demand absorption. Several major producers have brought new lines online or expanded existing facilities, particularly in Europe and Asia, while traditional newsprint and printing volumes continue to erode in multiple markets. The result is a market where aggregate capacity can grow while the highest-value grades become increasingly contested. Producers are being forced to differentiate on fiber blend, brightness, bulk, and drainage characteristics rather than compete purely on tonnage. This shift raises the operational bar: consistency at scale, flexibility in grade conversion, and the ability to validate sustainable sourcing claims have become baseline expectations rather than optional enhancements.
A second challenge lies in the regulatory environment. Effluent discharge standards, water stewardship requirements, and carbon reduction targets are tightening across major producing regions. These rules do not merely impose compliance costs; they reshape the economics of mill operation by increasing the returns to energy recovery, process integration, and cleaner production technologies while penalizing older configurations that rely on less efficient bleaching or higher discharge loads. At the same time, downstream customers and brand owners are increasingly tying procurement decisions to traceable and deforestation-free fiber, meaning compliance is becoming a commercial prerequisite, not just an environmental one.
A third challenge is cost and margin volatility. BCTMP production is sensitive to fiber quality, chemical consumption, utilities, and transport. Mills that can integrate biomass-derived energy, recover and reuse process streams, and optimize chemical usage gain a structural cost advantage. Those without such integration face more exposed cost curves and less flexibility when input prices spike. In a market where procurement contracts increasingly reference sustainability attributes and consistent specification performance, cost leadership is being redefined around efficiency, recovery, and traceability rather than sheer scale alone.
Key Drivers Reshaping the BCTMP Market
Technology Innovation and Process Differentiation
Process innovation remains a central driver of competitive positioning in BCTMP. Producers are moving beyond generic high-yield pulps toward recipes that balance bulk, brightness, and strength while reducing chemical and energy intensity. Bleaching configurations that emphasize environmentally compliant reagents, reduced effluent loads, and flexible grade adjustment are becoming differentiators. In practical terms, mills are designing for controllability: the ability to deliver distinct hardwood and softwood variants, adjust bulk and drainage profiles for specific board or tissue needs, and maintain brightness stability without relying on heavier chemical regimes. These capabilities support premiumization in tissue and hygiene grades, where bulk and softness are critical, and enable lighter-weight packaging designs that depend on high-bulk pulp to maintain stiffness at lower grammages.
Recent equipment and line commissioning activity illustrates this direction. In China, a major phase startup expanded BCTMP capacity and reflected the continued push to localize high-yield pulp supply for board and packaging applications. In Europe, a Nordic producer introduced a bleached hardwood BCTMP grade derived from Nordic birch fibers, engineered for high bulk and high brightness, with specifications that can be adjusted for different end-use requirements. These moves signal a broader industry shift: BCTMP is increasingly positioned as a customizable, grade-specific input rather than a commodity bulk fiber. The strategic implication is that production flexibility, specification engineering, and quality consistency are becoming as valuable as volume.
Policy and Regulatory Realignment
Policy frameworks are reshaping both the cost floor and the market access conditions for BCTMP. Stricter effluent norms and carbon reduction targets require ongoing investment in cleaner production and treatment infrastructure. At the same time, regulatory regimes focused on sustainable sourcing are pushing traceability and deforestation-free fiber into procurement criteria. These dynamics elevate the importance of mills that can document chain-of-custody, demonstrate responsible forestry, and operate processes compatible with lower-emission targets. Mills that integrate biomass energy and black liquor recovery are better positioned to navigate carbon pricing and renewable energy expectations, converting compliance from a burden into a competitive lever.
Regulatory pressure also interacts with downstream substitution dynamics. As brands and converters seek materials that support lighter-weight designs, recyclable packaging formats, and hygiene product performance, BCTMP’s high-yield and bulk properties make it relevant to these targets, provided the fiber can be sourced and produced in ways that align with corporate sustainability commitments. In effect, regulation is compressing the market into two directions at once: it raises the operational bar for producers, while simultaneously creating demand pull from end-users who need fiber that meets both performance and sustainability specifications.
Demand-Side Reconfiguration
Downstream demand is being reshaped by two long-running shifts: the contraction of legacy printing and newsprint channels and the expansion of tissue, hygiene, and lightweight packaging applications. Tissue and hygiene products continue to represent a substantial share of BCTMP consumption, driven by sustained consumer demand and product engineering that favors bulk, softness, and absorbency. Packaging applications, particularly lightweight coated board and cartonboard structures, also rely on high-bulk pulp to achieve stiffness goals without adding mass. This application mix favors producers with grade flexibility and the ability to serve multiple end-use clusters from a single asset base.
Worldwide Unbleached Kraft Pulp (UKP) Market
Consumer-facing expectations are reinforcing this shift. Hygiene brands are increasingly optimizing for comfort and performance while also seeking materials that align with broader environmental narratives. In packaging, converters and brand owners are pursuing weight reduction and material efficiency, which translates into demand for pulps that contribute bulk and surface properties at lower basis weights. These behaviors change the commercial calculus for BCTMP suppliers: customers are not just buying volume, they are buying engineered fiber attributes that help them hit downstream performance and sustainability targets.
Supply Chain and Cost Structure Evolution
The economics of BCTMP production are increasingly defined by integration, energy recovery, and logistics. Mills with co-located energy recovery, efficient water management, and robust chemical reuse systems enjoy more stable cost structures and greater resilience to utility and input fluctuations. Conversely, producers reliant on less integrated configurations face more exposed margins. Logistics and fiber sourcing patterns matter as well, particularly as mills seek fiber that meets provenance and sustainability expectations while remaining cost-competitive across regional transport routes.
This dynamic is encouraging both operational modernization and strategic realignment of sourcing footprints. Some producers are optimizing around local fiber availability and established logistics corridors, while others are upgrading process lines to improve yield, reduce chemical demand, and enhance grade flexibility. The practical effect is a market where cost advantage is less about raw tonnage and more about total system efficiency, including energy, water, chemicals, and traceability.
Competitive Landscape and Leading Strategies
The BCTMP space features a diverse set of participants spanning North American integrated producers, Nordic mills with strong sustainability positioning, and Asian operators expanding capacity to serve regional board and tissue demand. Several incumbents hold meaningful scale in specific grades, while newer or expanding players are pursuing targeted capacity additions and product specialization. The overall market structure reflects moderate concentration, with a handful of large producers accounting for a substantial share of output, but with enough fragmentation to sustain active competition on grade, region, and application focus.
Leading producers differentiate through a combination of grade breadth, process sustainability, and integration. North American operators continue to supply softwood and hardwood BCTMP variants for tissue, packaging, and printing-related uses, often leveraging regional fiber logistics and established customer relationships. Nordic producers emphasize high-yield and environmentally compatible bleaching configurations, aligning their product attributes with tissue and packaging needs while reinforcing sustainability credentials through traceable fiber and lower-impact processes. Asian producers are expanding to meet localized demand for lightweight board and tissue grades, reinforcing the geographic diversification of supply.
Strategic differentiation is increasingly tied to three themes. First, grade engineering: mills that can deliver specific bulk, brightness, and drainage profiles for tissue, board, or specialty applications command more favorable positioning than those offering undifferentiated volume. Second, sustainability integration: producers that can connect fiber sourcing, process chemistry, and energy recovery to verifiable environmental outcomes are better positioned for customers whose procurement decisions incorporate traceability and compliance requirements. Third, operational flexibility: the ability to adjust production across grades, manage specification consistency, and respond to regional demand shifts is becoming a valuable asset in a market where end-use mix continues to evolve.
The competitive dynamic is shifting along two axes. On the consolidation side, larger producers are strengthening their positions through operational scale, integration, and product specialization, which can raise barriers for smaller players without comparable process or sourcing advantages. On the fragmentation and new entry side, capacity additions in select regions and targeted grade launches are creating localized competition and expanding optionality for downstream buyers. This combination suggests a market that will remain active and multi-polar, with winners determined less by geography alone and more by the ability to deliver the right fiber attributes with defensible cost and compliance profiles.
Notable Industry Movements and What They Signal
Several recent developments illustrate how the competitive and strategic themes are playing out in practice. One European producer launched a high-bulk, high-brightness hardwood BCTMP grade from Nordic birch fibers, highlighting the push toward specification customization and sustainable forestry alignment. Another operator completed a modernization program that raised daily capacity and reflected the continued emphasis on scale and efficiency improvements in producing regions. A Nordic mill advanced the design phase for a new BCTMP line, signaling confidence in demand for high-yield pulp in tissue and packaging applications. Meanwhile, a phase startup in China added capacity for BCTMP, reinforcing the trend toward regional supply growth tied to board and hygiene demand.
PW Consulting
These moves collectively indicate that investment is flowing toward capacity where demand is strongest and toward grades where differentiation is most defensible. The pattern is not simply additive; it is selective. Producers are expanding where they can combine volume growth with usable grade flexibility, credible sustainability positioning, and integration advantages. That selectivity matters for buyers and investors because it shapes where competition intensifies, where supply tightens, and where pricing power is likely to be contested.
Strategic Outlook: Trends and Opportunities for 2026–2032
Looking ahead, three trends are likely to define the BCTMP market over the next several years. First, application-led grade specialization will deepen. As tissue, hygiene, and lightweight packaging continue to absorb growth while legacy printing volumes decline, producers will face stronger incentives to customize bulk, brightness, and drainage characteristics. Mills capable of producing distinct hardwood and softwood variants with consistent quality and flexible specifications will capture more value than those competing solely on volume. This trend favors assets and operating models that can shift output across applications without sacrificing specification integrity.
Second, sustainability and compliance will increasingly function as commercial gateways. Traceable fiber, deforestation-free sourcing, and cleaner production are becoming connected to procurement decisions and market access. Mills that can demonstrate process efficiency, energy recovery, and responsible sourcing will find more options in customer qualification processes, while those with weaker documentation or higher-impact configurations may face narrower pathways to premium segments. The opportunity here is not compliance alone but the ability to use credible sustainability attributes as part of a differentiated value proposition, particularly in applications where downstream brands are sensitive to material positioning.
Third, cost and margin discipline will be redefined by integration and recovery. Energy efficiency, water stewardship, chemical optimization, and black liquor or biomass-derived energy recovery will increasingly separate resilient producers from exposed ones. As carbon costs and regulatory expectations rise, the economic premium on integrated, lower-intensity operations will grow. The strategic upside lies in combining cost stability with grade flexibility, enabling producers to serve higher-value applications while maintaining margin durability through cycles.
These trends create clear commercial opportunities. Producers can pursue premiumization through specification control, target application clusters with stronger demand momentum, and invest in process configurations that reduce exposure to regulatory and energy cost pressure. Buyers can use grade selectivity and supplier qualification to secure fiber that supports both performance and compliance goals. Investors can focus on assets and operators with credible integration, traceability, and grade flexibility, recognizing that future returns will be tied to operational adaptability as much as to capacity scale. At the same time, uncertainty persists around the pace of legacy paper decline, the stringency and timing of regulatory implementation, and the extent to which regional capacity additions will outpace absorption in specific grades. Market participants should treat these as dynamic variables rather than fixed assumptions, monitoring capacity announcements, specification adoption, and compliance-driven qualification shifts as leading indicators.
Decision-Maker Playbook: Actions for Manufacturers, Investors, and Buyers
For pulp producers and paperboard or tissue manufacturers, the priority is to align grade strategy with end-use demand and compliance readiness. Operators should map their product portfolio against the applications where BCTMP attributes add the most value, ensure specification flexibility where customers are optimizing for bulk, brightness, or drainage, and verify that sourcing and process practices can withstand documentation and traceability requirements. Where feasible, investment in energy recovery, chemical efficiency, and effluent management will strengthen both cost resilience and market access. The practical question is whether current assets and operating practices can shift output toward higher-value grades without sacrificing consistency or compliance credibility.
For investors, the focus should be on structural advantages rather than headline capacity alone. Favorable opportunities are likely to emerge where operators demonstrate integration benefits, grade flexibility across tissue and packaging applications, and credible sustainability positioning that aligns with evolving buyer requirements. Capacity additions are meaningful, but their value depends on absorption quality, specification differentiation, and cost discipline. Monitoring modernization programs, grade launches, and regional supply shifts provides earlier signal than aggregate capacity figures, particularly in a market where competitive advantage is increasingly defined by how fiber is produced and qualified rather than how much is produced.
For procurement and sourcing teams, the actionable move is to treat BCTMP selection as an engineered input decision, not a generic commodity purchase. Buyers should define specification priorities for their end-use formats, qualify suppliers on both performance consistency and traceability or compliance documentation, and assess total delivered cost with energy, logistics, and regulatory exposure in mind. Diversifying across suppliers with complementary grade strengths and regional footprints can reduce exposure to localized tightness while preserving access to the fiber attributes needed for product performance and packaging efficiency. As qualification criteria evolve, early alignment with suppliers that can meet both technical and sustainability expectations will reduce friction in downstream product development and customer-facing claims.
The BCTMP market is expanding, but its value creation is shifting from volume growth toward grade engineering, compliance readiness, and operational integration. That shift rewards participants who can read application-specific demand, adapt specifications, and operate with credible sustainability and cost structures. For decision-makers who need granular segment data, regional nuance, and tailored scenario analysis to translate these themes into concrete investment, sourcing, or production choices, a deeper data set can sharpen the path from insight to execution.
Worldwide Unbleached Wood Pulp Market
For detailed analysis of this topic, please visit the official page: Bleached Chemi-ThermoMechanical Pulp (BCTMP) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Satellite Market Viewed Through 6.98% CAGR and 344.8 Million Regional Growth Dynamics
By pmarketresearch, 2026-09-21
Navigating the Satellite Market: Strategic Trends and Commercial Opportunities Through 2032
The satellite industry has entered a phase of accelerated transformation, where technological maturation, regulatory modernization, and shifting demand patterns are reshaping competitive boundaries. Market valuation has expanded from approximately $163.15 million in 2020 to a projected $215.0 million in 2025, with forward estimates placing the sector at $344.8 million by 2032. This trajectory reflects a compound annual growth rate of 6.98 percent over the 2026–2032 forecast window, signaling sustained expansion rather than cyclical volatility. Such growth is not merely a function of incremental capacity additions; it represents a structural reconfiguration of how space-based infrastructure is designed, deployed, and monetized. For executives and investors, the critical question is no longer whether the market will grow, but which subsegments, geographies, and business models will capture disproportionate value as the ecosystem matures.
Behind the headline figures lies a more complex reality. The industry is navigating several inflection points that will determine competitive outcomes over the next half decade. Manufacturing throughput and component scaling remain pressing constraints, particularly as constellation architectures grow in size and operational complexity. Regulatory frameworks are evolving from prescriptive limits to performance-based models, creating both compliance flexibility and new coordination challenges across operators. Additionally, the economics of space deployment are shifting as launch cadence increases and reusable platforms reduce per-kilogram costs, yet these gains are unevenly distributed across suppliers and mission types. These dynamics are not isolated headwinds; they are interconnected forces that will separate agile, vertically integrated players from those reliant on legacy supply chains or static service models.
Key Drivers Reshaping the Satellite Landscape
Technological Innovation and Mission Architecture Evolution
The shift toward proliferated low Earth orbit architectures is fundamentally altering satellite design philosophy. Rather than relying on a small number of high-value, long-lifecycle platforms, operators are increasingly deploying modular, software-defined constellations that prioritize rapid iteration, in-orbit reconfigurability, and scalable manufacturing. This architectural transition is supported by advances in optical inter-satellite links, autonomous orbital maneuvering, and standardized payload interfaces, which collectively reduce integration lead times and improve network resilience. Recent product introductions illustrate this trajectory: the deployment of direct-to-cell broadband satellites in early 2026 expanded emergency and consumer connectivity capabilities without requiring ground terminal upgrades, demonstrating how payload innovation can unlock adjacent service markets. For manufacturers and system integrators, the opportunity lies in designing platforms that accommodate frequent software updates, cross-constellation interoperability, and rapid payload swaps, rather than optimizing solely for unit cost reduction.
Regulatory Modernization and Spectrum Coordination
Policy frameworks are transitioning from rigid emission limits to performance-based spectrum sharing models, a shift that carries significant implications for network planning and capital allocation. In early 2026, regulators adopted a modernized framework for non-geostationary and geostationary spectrum sharing in key broadband bands, replacing legacy interference thresholds with criteria tied to actual network performance. This approach grants operators greater flexibility in orbital slot utilization and frequency coordination, but it also raises the analytical burden for compliance strategy and interference mitigation. Parallel adjustments, including differentiated licensing structures for small versus large constellations and clarified end-of-life deorbit obligations, are reshaping entry barriers and lifecycle cost assessments. Companies that invest early in spectrum strategy, orbital debris management, and regulatory engagement will secure faster deployment timelines and lower long-term operational risk, while those treating compliance as a afterthought may face costly redesigns or licensing delays.
Demand-Side Shifts Across Commercial and Government Sectors
Demand patterns are diversifying beyond traditional communications and Earth observation use cases. Enterprise connectivity requirements are expanding into maritime, aviation, remote industrial operations, and mobile platforms, driven by the need for resilient backhaul and real-time telemetry in environments where terrestrial infrastructure is impractical. Simultaneously, government and defense procurement is emphasizing rapid delivery, proliferated architectures, and multi-orbit mission flexibility, reflecting a strategic preference for distributed assets over concentrated, high-cost platforms. Contract activity in early 2026 highlighted this dual demand stream: significant delivery milestones for transport-layer satellites supporting government programs coincided with finalized commercial constellation agreements, indicating that public and private capital are converging on similar architectural principles. For service providers and platform suppliers, the strategic implication is clear: product roadmaps must accommodate both high-reliability mission requirements and cost-sensitive commercial scaling, often within the same architectural family.
Supply Chain Dynamics and Manufacturing Scale-Up
The economics of satellite production are being recalibrated as demand volume increases and component standardization gains traction. Industry reporting from mid-2025 noted a 17 percent rise in satellite manufacturing revenue alongside a dominant U.S. market share, underscoring how regional capability concentration and supply chain maturity can accelerate deployment. At the same time, exporters and suppliers are navigating evolving trade controls, with certain spacecraft and servicing items experiencing reduced licensing friction for select partner markets. These shifts create a window for suppliers that can deliver qualified subsystems at scale, maintain stringent quality assurance, and align production schedules with constellation deployment cadence. Cost structure advantages will increasingly accrue to organizations that secure long-term subsystem agreements, invest in automated assembly and test processes, and mitigate single-source dependencies for critical components such as propulsion modules, power systems, and phased-array payloads.
Competitive Landscape and Strategic Positioning
Established Systems Integrators and Platform Leaders
Large aerospace and defense primes continue to anchor the market through comprehensive system integration capabilities, deep mission engineering expertise, and established relationships with government and commercial buyers. Their strategic positioning typically emphasizes end-to-end delivery spanning bus platforms, payloads, ground interfaces, and mission operations, which reduces customer integration risk and supports complex, multi-year programs. Differentiators in this tier include advanced manufacturing scale, secure production environments, and the ability to manage stringent reliability and certification requirements. These companies are increasingly adapting to proliferated architectures by offering standardized platforms, modular payload integration, and faster delivery cycles, while preserving their advantage in high-complexity missions where performance margins and compliance rigor remain paramount.
Specialized Operators and Connectivity Enablers
A distinct tier of operators and subsystem specialists is expanding the commercial surface area of the market by focusing on constellation services, mobile tracking systems, broadband platforms, and end-to-end connectivity solutions. Their competitive edge often stems from vertical service integration, rapid product iteration, and close alignment with specific user segments such as mobile communications, remote enterprise networking, and IoT telemetry. Recent commercial activity illustrates this focus: mobile tracking antenna providers have secured advance orders for LEO and MEO tracking systems, signaling growing demand for vehicle-based and transportable connectivity that can follow dynamic orbital pathways. Similarly, broadband platform operators are extending service reach through direct-to-device capabilities and ecosystem partnerships that reduce reliance on specialized ground hardware. These players are reshaping buyer expectations around deployment speed, service flexibility, and total cost of ownership, forcing traditional suppliers to respond with more agile commercial terms and modular offerings.
TV Market
Market Evolution: Consolidation, Differentiation, and New Entrants
The competitive structure is moving toward a hybrid model in which large integrators, specialized operators, and nimble platform startups coexist, each competing on different axes of value. Consolidation is likely where scale economics, spectrum access, and multi-orbit capability become decisive, particularly for operators seeking to amortize network costs across large user bases. At the same time, differentiation is intensifying around software-defined payloads, rapid manufacturing pipelines, and niche mission solutions that address specific defense, scientific, or commercial requirements. New entrants are gaining traction by leveraging standardized bus architectures, commercial-off-the-shelf component strategies, and focused service propositions that bypass the cost structures of legacy programs. The net effect is a market where incumbents must accelerate product cycle times and expand commercial flexibility, while entrants must prove reliability, supply continuity, and mission-grade performance to secure sustained contracts. Strategic positioning will increasingly depend on how effectively companies balance scale with specialization, and how quickly they can translate technical capability into deployable, revenue-generating service models.
Forward Outlook: Three Defining Trends for the Next Three to Five Years
The first defining trend is the acceleration of multi-orbit, software-defined networks that blend LEO, MEO, and GEO assets into coordinated service layers. As spectrum sharing becomes performance-based and inter-satellite linking matures, operators will be able to route traffic dynamically across orbits, improving latency, coverage, and resilience without proportionally increasing satellite count. This creates commercial opportunities in network orchestration, payload virtualization, and cross-orbit service integration, while challenging suppliers to deliver interoperable interfaces and secure data-handling architectures. The primary risk is coordination complexity: as networks multiply, interference management, orbital slot allocation, and standards alignment will require sustained industry cooperation and proactive regulatory engagement.
LEO Satellite Market
The second trend is the continued pressure on manufacturing throughput and subsystem standardization as constellation programs scale. Buyers will increasingly favor suppliers that can demonstrate repeatable production cycles, qualified component inventories, and transparent lead-time commitments. Companies that invest in automation, modular test flows, and long-term subsystem partnerships will secure margin stability and preferential positioning in large-scale procurements. The uncertainty lies in supply chain concentration and export control variability; shifts in licensing scope or component availability can quickly alter cost assumptions and deployment schedules, making diversification and contingency planning essential.
The third trend is the expansion of service monetization beyond traditional bandwidth leasing into vertical-specific connectivity, mobile tracking, and integrated telemetry solutions. Direct-to-device capabilities, transportable antenna systems, and end-to-end platform offerings are lowering adoption barriers for enterprise, maritime, aviation, and government users who previously faced high terminal costs or limited coverage. This opens addressable market growth for operators and equipment suppliers that can package hardware, software, and service operations into unified solutions. The commercial risk is fragmentation: as more players introduce niche offerings, differentiation may erode unless companies can sustain clear performance advantages, reliable service-level commitments, and scalable support infrastructure.
Strategic Guidance for Decision-Makers
For satellite manufacturers and subsystem suppliers, the priority is to align product roadmaps with proliferated, multi-orbit demand while protecting margin through standardization and supply continuity. Investing in modular platform design, repeatable assembly processes, and qualified component pipelines will reduce integration risk and position suppliers for large-scale constellation awards. Concurrently, proactive engagement on spectrum coordination, end-of-life compliance, and export licensing will shorten deployment timelines and reduce operational uncertainty. Organizations that treat these capabilities as core competitive assets, rather than ancillary compliance tasks, will be better equipped to capture value as procurement cycles accelerate.
For investors and strategic capital allocators, the most resilient opportunities will likely emerge where technical capability, regulatory readiness, and scalable commercial models intersect. Due diligence should prioritize suppliers and operators with demonstrated manufacturing throughput, clear spectrum and licensing strategies, and service architectures that can adapt across orbit regimes and user segments. Allocation decisions should weigh not only unit economics and contract pipelines, but also exposure to supply concentration, compliance evolution, and standards fragmentation. Capital deployed into companies that can harmonize hardware scale with software-defined service delivery is more likely to benefit from the structural expansion projected through the end of the decade.
PW Consulting Automotive & Machinery Research Center
For procurement leaders and enterprise buyers, the immediate objective is to evaluate total cost of ownership across hardware, service, and lifecycle dimensions rather than focusing narrowly on upfront terminal or bandwidth pricing. Engaging suppliers with proven multi-orbit interoperability, mobile and transportable connectivity options, and transparent service-level frameworks will reduce integration risk and improve resilience in remote or mobile operations. Buyers should also monitor regulatory and licensing developments that affect spectrum availability, deorbit obligations, and export eligibility, as these factors can materially influence deployment timing and long-term operating costs.
Detailed segmentation data, competitive benchmarking, and customized scenario modeling can further sharpen these decisions by translating market-level trends into segment-specific priorities and investment thresholds. Access to comprehensive research supporting the trajectory from 2026 through 2032 can help decision-makers validate assumptions, compare supplier positioning, and align procurement or capital strategies with the most probable growth pathways.
For detailed analysis of this topic, please visit the official page: Satellite Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Mammography X-ray Unit Market: Why 8.75% CAGR & Shifting Digital Demand Redefine Growth
By pmarketresearch, 2026-09-21
Strategic Trends and Commercial Opportunities in the Mammography X-ray Unit Market
The global mammography equipment sector has entered a decisive phase of structural expansion. Valued at approximately $1.15 billion in 2020, the market has grown steadily through 2025, crossing the $1.65 billion threshold. Over the coming years, the trajectory projects sustained momentum, with revenue expected to approach the $3 billion mark by 2032, translating to a compound annual growth rate of 8.75 percent. This growth is not merely a function of broader healthcare spending; it reflects a fundamental shift in how imaging systems are engineered, deployed, and reimbursed. For manufacturers, investors, and healthcare procurement teams, the market is evolving from a volume-driven replacement cycle into a technology-and-outcomes-led upgrade environment.
The macro picture, however, masks underlying asymmetries. Regional deployment patterns, modality preferences, and clinical use cases are converging around digital capabilities and screening-first workflows. At the same time, the market remains highly concentrated, with a small group of players accounting for the majority of share. That concentration creates both resilience and friction: established incumbents benefit from installed-base loyalty and service ecosystems, while emerging entrants test the boundaries of clinical differentiation and capital efficiency. Understanding where value is being created—and where it is being eroded—requires looking beyond top-line numbers to the operational and regulatory forces reshaping purchasing decisions.
Market Snapshot and Core Challenges
The overall market size reflects a steady climb from 2020 through 2025, with a pronounced acceleration expected over the forecast horizon. This cadence aligns with capital equipment replacement cycles, expanded screening participation in mature markets, and the gradual modernization of imaging fleets in emerging regions. The growth rate is supported by a mix of fresh unit sales and the recurring economics tied to system upkeep, calibration, and software-enabled upgrades. Yet the headline figures do not tell the full story. Three structural challenges are reshaping how the market behaves and where commercial opportunities are forming.
Challenge 1: Concentrated Supply and the Cost of Differentiation
With a small number of companies commanding the majority of market share, competition has shifted from pure hardware parity to integrated clinical value. Leading vendors compete on workflow integration, dose management, image quality reproducibility, and service reliability. For newer or smaller players, this environment raises the bar for entry: differentiation must be clinically credible and economically defensible, not just technically novel. The challenge is not simply to launch a system, but to demonstrate that a new configuration can reduce total cost of ownership, improve throughput, or enhance diagnostic confidence in ways that matter to facilities and payers.
PW Consulting
Challenge 2: Regulatory Rigor and the Burden of Compliance
Mammography is one of the most tightly regulated imaging modalities. Equipment must meet specific performance and dose standards, and operating sites are expected to maintain rigorous quality control routines. Compliance is not a one-time approval event; it is a continuous operational commitment. Facilities must conduct regular testing, address deviations promptly, and document corrective actions. For manufacturers, this means that product design, training, documentation, and service support must be engineered for sustained compliance—not just initial installation. For buyers, the regulatory layer influences procurement choices, as the cost of non-compliance and downtime can outweigh the upfront price difference between systems.
Challenge 3: Capital Sensitivity Amid Evolving Reimbursement Dynamics
Mammography systems represent significant capital investments, with pricing spread across entry-level, intermediate, and premium configurations depending on features such as three-dimensional imaging capability. At the same time, service contracts add a recurring cost dimension that facilities must plan for over the life of the equipment. On the revenue side, imaging services are tied to specific coding frameworks, and reimbursement outcomes depend on Medicare and private payer policies. This combination creates a tension familiar to capital equipment markets: clinical ambition must be reconciled with budget realism. Buyers increasingly weigh not only acquisition cost, but also the likelihood of sustained reimbursement coverage, utilization patterns, and the operational efficiency gains that can justify premium configurations.
Key Drivers Shaping the Market
The growth trajectory is underpinned by forces that extend beyond simple demand expansion. These drivers interact with one another, creating a market in which technology, regulation, and purchasing behavior reinforce new standards of care.
Technological Innovation and Clinical Value Creation
Digital mammography has become the dominant modality, with digital systems representing the majority of revenue and analog systems playing a diminishing role. The shift reflects more than legacy replacement; it reflects the operational and diagnostic advantages of digital workflows, including improved image handling, integration with downstream reporting, and the ability to support advanced acquisition modes. Three-dimensional capabilities and newer imaging architectures have further raised expectations around lesion visibility, dose optimization, and reading efficiency. These innovations are not merely feature upgrades; they change the economics of screening and diagnostic workflows by influencing recall rates, throughput, and radiologist confidence.
Recent milestones illustrate the pace of clinical exploration in this space. In early 2026, a first-in-human clinical study of a 4D mammography system reached enrollment completion at a regional health facility, signaling continued interest in higher-dimensional acquisition approaches and their potential to improve lesion characterization or workflow efficiency. Whether such approaches ultimately scale depends on clinical evidence, reproducibility, and the ability to integrate into routine practice without disrupting throughput. What is clear is that the market is actively testing the boundaries of acquisition geometry, image reconstruction, and workflow design.
Medical X-Ray Generator Market
Policy and Regulatory Environment as a Market Architect
Regulatory frameworks do more than set minimum standards; they shape procurement behavior, service expectations, and product roadmaps. In the United States, mammography systems are subject to equipment standards that include average glandular dose limits under federal rulemaking, and facilities must maintain quarterly quality control testing per manufacturer specifications, with corrective actions required if tests fail. This regulatory environment elevates the importance of reliable hardware design, consistent calibration, and responsive service infrastructure.
Regulatory guidance also evolves in ways that affect testing practices and equipment validation. Recent updates have revised phantom testing references, aligning quality assurance practices with current standards and commercial phantom solutions. While such changes may appear procedural, they matter commercially because they influence validation protocols, service training, and the documentation that facilities rely on to maintain compliance. For manufacturers, the operational implication is clear: regulatory alignment must be embedded into product lifecycle management, not treated as a separate compliance exercise.
Demand-Side Shifts in Screening and Diagnostic Workflows
Clinical demand is increasingly organized around screening as the dominant application, with diagnostic imaging representing a smaller share of usage. This pattern reflects both public health priorities and the operational logic of early detection programs. Screening-driven demand tends to favor systems that can handle higher volumes, maintain consistent image quality across broad patient populations, and support efficient reading workflows. At the same time, diagnostic demand remains important for problem-solving, recall evaluation, and symptomatic assessment, which keeps advanced imaging capabilities relevant across the product spectrum.
Behaviorally, healthcare organizations are paying closer attention to total cost of ownership and clinical outcomes, not just unit price. The decision to adopt premium configurations is increasingly tied to expected improvements in workflow efficiency, dose management, and diagnostic confidence, balanced against reimbursement realities. This demand-side evolution is pushing vendors to present not just equipment, but integrated solutions that bundle acquisition, training, service, and workflow optimization.
Supply-Side and Cost Structure Dynamics
The market’s cost structure is defined by a wide price spectrum across system tiers, with premium configurations commanding materially higher investment. This gradient creates an environment in which service contracts, parts availability, and upgrade paths have outsized importance. Annual service agreements typically vary with system age and feature set, making lifecycle cost a central element of procurement planning. In addition, the concentration of market share among leading vendors reinforces the importance of service networks and installed-base support, since many facilities prioritize reliability and long-term support over speculative new entrants.
For manufacturers, supply-side strategy increasingly involves balancing premium innovation with accessible configurations that meet the needs of smaller facilities or cost-sensitive markets. For buyers, the key question is how to select systems that fit clinical requirements without creating avoidable operational or financial strain over the equipment’s life. The result is a market where commercial success depends as much on service economics and compliance readiness as on hardware specifications.
Competitive Landscape and Leading Strategies
The competitive field is broad, spanning established global medtech and imaging companies as well as regional manufacturers and specialized innovators. This mix creates a layered competitive environment in which incumbents compete on ecosystem depth, while challengers attempt to carve out niches through clinical novelty, cost efficiency, or regional focus.
Strategic Positioning of Core Players
Hologic, GE HealthCare, and Siemens Healthineers represent the scale end of the market, where breadth of portfolio, installed-base leverage, and service infrastructure matter. These companies typically compete by integrating mammography into wider imaging and women’s health ecosystems, emphasizing workflow connectivity, dose management, and reproducibility across sites. Their strategic advantage lies in the ability to support large deployments, offer consistent service coverage, and align equipment with broader enterprise imaging and IT strategies.
FUJIFILM, Philips, and Canon Medical Systems bring strong imaging heritage and differentiated technology narratives. Their positioning often emphasizes image quality, system design, and workflow integration, with an eye toward supporting both screening throughput and diagnostic precision. Meanwhile, companies such as Konica Minolta, Carestream Health, Planmed, and IMS Giotto illustrate the value of specialized positioning. These players often target specific clinical use cases, regional markets, or configuration preferences, using focused product strategies to compete against broader portfolios.
On the emerging and regional side, companies such as Metaltronica, Beijing Wandong Medical Technology, Perlong Medical Equipment, and Shenzhen Angell Technology reflect the continued presence of cost-conscious manufacturing ecosystems and regional demand. Their commercial challenge is to demonstrate reliability, regulatory alignment, and service viability in markets where procurement decisions are highly sensitive to upfront price and local support.
Newer entrants such as Calidar highlight a different strategic pathway: clinical differentiation through novel acquisition concepts. In this case, early clinical study activity points to an innovation-focused approach that seeks to establish a distinct value proposition. Whether such a strategy scales will depend on the strength of clinical evidence, regulatory navigation, and the ability to position the system within existing workflows without imposing excessive operational complexity.
Market Evolution: Consolidation, Differentiation, and New Entry
The market is unlikely to become uniformly fragmented. Concentration in the upper tier is supported by the economics of service, compliance, and enterprise integration, which favor companies with broad reach and mature support structures. At the same time, differentiation remains possible through technology advances, workflow innovation, and regional specialization. New entrants are most likely to succeed when they can demonstrate a credible clinical benefit, fit into existing compliance and service expectations, and offer a clear economic rationale for switching or augmenting existing fleets.
For incumbents, the strategic imperative is to protect installed-base value while continuing to upgrade systems and service offerings in ways that align with regulatory expectations and clinical demand. For challengers, the opportunity lies in identifying segments where premium incumbents may be over-indexed on capability, or where regional demand is better served by focused product and support models. The broader trend is not a single winner-takes-all dynamic, but a layered market in which different players compete on different axes of value.
Future Trends and Commercial Opportunities
Looking ahead over the next three to five years, several trends are likely to define where growth and margin potential concentrate.
Trend 1: Digital-First Deployment and Advanced Acquisition Maturity
Digital systems will continue to dominate new deployments, while analog installations decline further as replacement cycles and modernization programs progress. Beyond the broad digital shift, more advanced acquisition approaches will mature from early research and limited adoption toward more mainstream consideration, particularly where evidence supports workflow or diagnostic gains. Commercial opportunity lies not only in selling higher-end systems, but in designing upgrade paths, software enhancements, and service models that allow facilities to move along the capability curve without full fleet replacement.
Medical X-Ray Tube Market
Trend 2: Compliance and Quality Assurance as Commercial Leverage
Regulatory expectations and quality control requirements will remain central to purchasing behavior. Facilities will increasingly favor vendors that make compliance easier to maintain through intuitive testing workflows, clear documentation, and responsive service. Manufacturers that embed compliance support into the product experience—rather than treating it as a separate service line—can turn a regulatory burden into a competitive advantage. This creates opportunities for service contracts, training programs, and digital quality management tools that reduce administrative friction for sites.
Trend 3: Total Cost of Ownership and Outcome-Linked Procurement
Buyers will continue to weigh acquisition price against lifecycle cost, reimbursement risk, and operational outcomes. As a result, vendors that can articulate how a system affects throughput, recall dynamics, dose management, and service reliability will have an advantage in competitive evaluations. The commercial opportunity here is to shift conversations from unit price to value over time, including service predictability, consumables efficiency, and integration with existing imaging IT and reporting workflows.
Risks and Uncertainties
These trends are not without risk. Reimbursement changes can alter the economic logic of premium configurations, especially if coding or payer policies shift in ways that affect facility revenue. Regulatory updates can increase testing and documentation burdens or change validation requirements, influencing procurement timing and service expectations. In addition, clinical novelty does not automatically translate into adoption; new acquisition modes must prove themselves in routine practice, with acceptable workflow impact and reproducible results. Finally, competitive intensity may compress margins in certain segments, particularly where regional manufacturers compete aggressively on price or where incumbents face pressure to modernize fleets without triggering full replacement cycles.
Actionable Guidance for Decision Makers
Different stakeholders face different strategic questions, but all benefit from a clear view of where value is forming and how the market is likely to evolve.
For Manufacturers and Technology Providers
- Design for lifecycle value, not just launch features. Emphasize serviceability, compliance support, and upgrade pathways that extend relevance across multiple procurement cycles.
- Align product narratives with operational outcomes. Frame capabilities in terms of throughput, dose management, reading efficiency, and quality assurance, not only image quality claims.
- Prepare for layered competition. Defend installed-base value while identifying segments where a focused configuration, regional support model, or clinical innovation can open new opportunities.
For Investors
- Focus on ecosystems, not only units. Recurring service economics, installed-base durability, and regulatory alignment often matter as much as new hardware sales.
- Watch for differentiation that is clinically and economically credible. Novel acquisition concepts or software-enabled workflows should be evaluated against adoption friction, evidence trajectory, and integration demands.
- Monitor concentration dynamics and regional expansion. High share among leading players creates stability, but also raises the importance of service reach, local support, and the ability to participate in modernization cycles across diverse markets.
For Healthcare Procurement and Facility Leaders
- Evaluate total cost of ownership with service and compliance in mind. Acquisition price is only one part of the equation; service contracts, downtime risk, and quality control support can shape financial outcomes over the life of the system.
- Match configuration to clinical mission and utilization patterns. Premium capabilities may be justified in high-volume or complex diagnostic environments, while simpler configurations may better serve sites with narrower use cases and tighter capital constraints.
- Request evidence of workflow integration and support reliability. Confirm that vendors can demonstrate not only system performance, but also the operational support needed to maintain compliance and minimize disruption.
For decision makers navigating this market, the most valuable intelligence is granular and current: segmentation details, regional deployment patterns, pricing and service economics, regulatory timelines, and competitive moves that affect procurement timing. Access to a complete research report can provide the depth needed to translate these dynamics into procurement strategy, investment thesis, or commercial planning. The broader market trajectory points to continued growth, but the distribution of value will depend on how well organizations align product strategy, compliance readiness, and service economics with evolving clinical demand.
For detailed analysis of this topic, please visit the official page: Mammography X-ray Unit Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
5-Aminolevulinic Acid Market: Why 9.8% CAGR and Pharma’s Dominance Reshape 2032
By pmarketresearch, 2026-09-21
Strategic Trends and Commercial Opportunities in the 5-Aminolevulinic Acid Market: A 2032 Outlook
The global 5-Aminolevulinic Acid (5-ALA) market has transitioned from a specialized biochemical niche to a multi-sectoral growth engine, driven by converging advances in photodynamic therapies, agricultural biotechnology, and cosmetic formulations. With a compound annual growth rate of 9.8% through 2032, the sector reflects a disciplined expansion pattern rather than speculative hype. The trajectory from 2020 to 2032 demonstrates consistent value creation, with revenue rising steadily as clinical validation, manufacturing scale-up, and cross-industry adoption reinforce each other. Yet beneath the headline growth metrics lies a more nuanced reality: regulatory fragmentation, formulation bottlenecks, and an evolving competitive map are reshaping how value is captured. For executives, investors, and procurement leaders, the question is no longer whether the market is expanding, but where capital, R&D, and commercial execution will yield the highest risk-adjusted returns.
This analysis examines the structural drivers, competitive dynamics, and forward-looking inflection points that will define the 5-ALA landscape over the next three to five years. The goal is to translate macroeconomic momentum into actionable strategic positioning, highlighting where operational excellence, regulatory navigation, and application diversification intersect.
Market Snapshot and Core Challenges
The market has demonstrated resilient upward momentum, expanding from a baseline in 2020 to an estimated valuation in 2025, with projections pointing toward a multi-hundred-million-dollar scale by 2032. The growth profile is characterized by sustained, double-digit compounding that reflects both volume expansion and value migration toward higher-margin applications. Rather than a single breakthrough driving this trajectory, the expansion is the product of incremental clinical adoption, agricultural pilot scaling, and formulation optimization across multiple end-use sectors.
Despite this momentum, three structural challenges are redefining the commercial playbook.
Regulatory Uncertainty and Classification Gaps
The regulatory landscape for 5-ALA remains uneven across major markets. In pharmaceutical and medical device contexts, approvals have progressed through established clinical pathways, enabling commercialization in specific diagnostic and therapeutic applications. Outside these narrow indications, however, classification remains unresolved. In the United States, the absence of definitive guidance on whether 5-ALA qualifies as a New Dietary Ingredient has created ambiguity for supplement and functional nutrition ventures. Similarly, in the European Union, the compound continues to navigate Novel Food review processes, with no final determination enabling broad dietary supplement deployment. This regulatory lag is not merely a compliance issue; it dictates which business models can scale, which distribution channels remain accessible, and how quickly new formulations can reach consumers or enterprise buyers.
PW Consulting Chemical & Energy Research Center
Formulation and Delivery Optimization Constraints
While 5-ALA’s biochemical properties are well understood, translating laboratory efficacy into consistent clinical or agricultural outcomes remains a non-trivial engineering challenge. Photodynamic applications require precise timing, concentration control, and tissue-specific uptake, while agricultural and cosmetic use cases demand stability, dermal or foliar compatibility, and shelf-life reliability. Recent clinical data has demonstrated that extending the administration window for oral 5-ALA can improve procedural flexibility in diagnostic settings, underscoring that delivery protocols—not just molecule availability—are critical value drivers. Companies that treat formulation and dosing protocols as afterthoughts risk ceding margin and differentiation to competitors who integrate pharmacokinetics, user experience, and application-specific optimization into their core product architecture.
Supply Chain Concentration and Quality Standardization
The market exhibits moderate concentration among established suppliers, with a meaningful share of high-purity material flowing through a limited set of manufacturers and regional production hubs. This structure offers efficiency advantages but introduces vulnerability: batch consistency, regulatory documentation, and specialty-grade purification remain bottlenecks for downstream formulators. Moreover, as demand expands beyond research-grade supply into commercial-scale pharmaceutical, agricultural, and cosmetic volumes, the industry faces pressure to standardize quality frameworks while managing cost structures. Firms that rely on fragmented sourcing or lack robust analytical validation risk delays, compliance friction, and margin erosion as end-market specifications tighten.
Key Growth Drivers Reshaping the Landscape
The 5-ALA market’s expansion is not uniform; it is being pulled forward by a set of interlocking drivers that reward companies capable of aligning technical, regulatory, and commercial execution.
Clinical Validation and Fotodynamic Therapy Evolution
The most consequential driver is the maturation of photodynamic diagnosis and therapy applications. Clinical evidence continues to reinforce the utility of 5-ALA as a photosensitizing precursor in tumor visualization and targeted treatment protocols. Recent regulatory acknowledgments that extend oral administration windows for specific diagnostic procedures illustrate how clinical data can directly translate into procedural flexibility and broader adoption. As hospitals and specialty clinics integrate these protocols into routine workflows, demand shifts from experimental or pilot-scale use toward standardized, repeatable procurement. This transition elevates the importance of product reliability, regulatory documentation, and clinician training support, turning commercial success into a function of ecosystem enablement rather than molecule supply alone.
Policy and Regulatory Pathway Clarification
While regulatory uncertainty remains a challenge, incremental policy progress is also a growth catalyst. Where health authorities provide clearer indications for medical use, downstream investment becomes more predictable. In parallel, agricultural and cosmetic applications are shaping their own compliance trajectories, often leveraging existing biostimulant, cosmetic ingredient, or research-grade frameworks to accelerate go-to-market timelines while broader dietary classifications remain unresolved. The companies that navigate this environment effectively do not wait for a single global ruling; they design application-specific regulatory strategies that align with the fastest available pathways, using clinical or agronomic data packages to support targeted approvals and market access.
Demand-Side Shifts in Agriculture and Personal Care
Beyond the clinic, demand-side behavior is evolving rapidly. In agriculture, the push for yield optimization, stress tolerance, and reduced dependency on conventional inputs has elevated interest in biochemical biostimulants. 5-ALA’s role in chlorophyll synthesis and plant metabolic pathways positions it as a candidate for precision agricultural programs, particularly in markets where sustainability mandates and input cost pressures coincide. In cosmetics and personal care, consumer interest in biologically derived actives and skin-health benefits has spurred formulation exploration, with brands seeking ingredients that can anchor marketing narratives in mechanistic plausibility rather than purely cosmetic claims. These demand shifts expand the addressable base for 5-ALA beyond traditional medical channels, but they also require differentiated value propositions, safety data packages, and supply reliability tailored to each sector’s procurement standards.
Manufacturing and Cost Structure Improvements
Scaling production of high-purity 5-ALA and its salt forms has become a strategic priority as multi-sector demand intensifies. Advances in synthesis routes, purification processes, and quality control analytics are gradually improving cost structures and batch-to-batch consistency. The effect is twofold: it lowers barriers for formulators seeking dependable supply, and it enables incumbents to expand margins while investing in application-specific development. However, cost leadership alone is unlikely to secure durable advantage. The more durable moats are emerging around integrated quality systems, regulatory-ready documentation, and partnerships that link manufacturing capability with formulation science and end-market technical support.
Competitive Landscape and Strategic Positioning
The competitive field spans specialty pharmaceutical developers, chemical suppliers, research-grade distributors, and regional manufacturers pursuing agricultural and cosmetic applications. Rather than competing solely on price, leading players are carving out positions based on application focus, regulatory readiness, and technical service capabilities.
Differentiated Playbooks Across the Value Chain
Several companies have built recognizable identities around specific use cases. In the medical and diagnostic segment, firms with approved 5-ALA-based products for photodynamic visualization have leveraged clinical evidence, procedural training, and regulatory approvals to anchor their positions. Their advantage lies not simply in supplying the molecule, but in enabling clinical adoption through protocol clarity, product consistency, and medical affairs support.
In the research and reagent space, established chemical suppliers compete on purity certification, documentation reliability, and breadth of catalog support. Their customers prioritize batch traceability and analytical validation, which makes quality systems and supplier credibility central to retention. In the industrial and specialty chemical segment, manufacturers that can provide high-purity intermediates and customized synthesis options gain relevance among formulators who need flexibility in specifications and scale. Meanwhile, regional players in Asia have expanded their footprint by addressing both pharmaceutical and agricultural biostimulant demand, often combining API production with formulation exploration tailored to local crop and market conditions.
Strategic Advantages and Ecosystem Positioning
The most defensible positions emerge where molecule supply intersects with application expertise. Companies that combine reliable purification and manufacturing with regulatory documentation, stability data, and end-use technical support create friction for customers considering multi-sourcing or switching to lower-cost alternatives. In diagnostic and therapeutic niches, approval status and clinical protocol alignment function as strong barriers to entry. In agricultural and cosmetic channels, success increasingly depends on demonstrating consistent performance, safety profiles, and supply continuity rather than competing on commodity pricing alone.
This landscape is also being shaped by selective external collaboration. Major pharmaceutical and biotechnology players have shown interest in exploring enhanced 5-ALA formulations for photodynamic applications, signaling that formulation innovation and partnership-driven development can accelerate value creation even when internal R&D capacity is constrained. Such collaborations often focus on improving efficacy, expanding treatment or diagnostic windows, or tailoring delivery characteristics, which reinforces the broader industry shift toward formulation-led differentiation.
Market Structure Evolution: Consolidation, Specialization, and New Entrants
The market is neither fully consolidated nor highly fragmented; it is evolving through a combination of specialization and selective consolidation. In research-grade and reagent segments, brand trust and analytical reliability support stable positioning, while in commercial-scale pharmaceutical and agricultural segments, scale, regulatory readiness, and application support increasingly matter. New entrants are likely to appear where application gaps remain: niche cosmetic actives, regional agricultural biostimulant programs, and next-generation formulation concepts that improve stability, targeting, or ease of use. The strategic implication is clear: competitive advantage will belong to firms that define a precise application focus, build the corresponding regulatory and technical evidence base, and align supply chain capabilities with that focus rather than pursuing undifferentiated volume expansion.
5-Aminolevulinic Acid Hydrochloride Market
Forward-Looking Trends and Commercial Implications
Looking ahead to the 2026–2032 window, three trends are likely to shape how value is created and captured in the 5-ALA market.
Application-Specific Formulation as a Core Differentiator
The next phase of growth will increasingly reward companies that tailor 5-ALA products to specific end-use requirements rather than selling a uniform molecule across all channels. In medical and diagnostic settings, this means optimizing administration timing, concentration ranges, and procedural compatibility. In agriculture, it means developing formulations aligned with foliar application, stress resilience, and compatibility with existing crop management programs. In cosmetics, it means prioritizing stability, sensory attributes, and claim-supportive safety data. The commercial opportunity lies in building a portfolio architecture where each product variant is backed by the right evidence package, regulatory positioning, and technical support for its intended market.
Levulinic Acid Market
Regulatory Clarity as a Market Access Accelerator
As regulatory frameworks continue to mature, segments that secure clearer pathways will experience faster scaling, while ambiguous segments will remain dependent on workaround strategies or narrower use cases. Companies that proactively invest in data generation, dossier preparation, and early engagement with health authorities will be better positioned to convert scientific potential into commercial reach. Conversely, businesses that rely on regulatory ambiguity as a temporary advantage may face increasing scrutiny as standards tighten and downstream customers demand demonstrated compliance. The strategic lesson is to treat regulatory preparation as a growth investment rather than a compliance cost.
Supply Chain Integration and Regional Capacity Expansion
Demand diversification across regions and applications will pressure the industry to build more resilient, regionally balanced supply capability. Where production remains overly concentrated, downstream buyers will seek redundancy, quality guarantees, and localized technical support. The likely response is a mix of expanded regional manufacturing, strengthened analytical and quality frameworks, and closer integration between suppliers and formulators. This shift creates opportunities for players that can offer dependable supply, transparent documentation, and the flexibility to support application-specific requirements. It also raises the stakes for firms that cannot meet increasing quality and consistency expectations as commercial volumes grow.
These trends carry inherent uncertainty. Regulatory timelines can shift, clinical adoption can plateau if procedural barriers persist, and agricultural or cosmetic adoption can be sensitive to economic cycles and input-cost dynamics. Competitive entry may compress margins in certain segments, and formulation claims will face higher scrutiny as markets mature. The businesses that navigate these risks most effectively will be those that combine disciplined application focus with credible data, robust quality systems, and flexible commercial models.
Strategic Recommendations for Decision-Makers
For executives and investors evaluating exposure to 5-ALA, the opportunity is real but increasingly segmented. Value creation will depend less on broad commodity positioning and more on targeted application strategies, regulatory alignment, and supply chain reliability.
For Manufacturers and Product Developers
- Define a clear primary application focus and build the supporting evidence package, quality documentation, and technical support around it. A molecule-centric strategy without application-specific differentiation is increasingly vulnerable to competition and margin pressure.
- Treat formulation science and delivery protocols as core IP. Improvements in stability, timing flexibility, compatibility, and ease of use can create defensible positioning, especially in medical and diagnostic channels where procedural fit matters.
- Invest in regulatory readiness early. Proactive data generation, dossier preparation, and engagement with relevant authorities reduce time-to-access and improve customer confidence, particularly when downstream buyers are risk-averse.
For Investors and Strategic Capital Allocators
- Evaluate exposure by application pathway rather than by aggregate market growth alone. Segments with clearer regulatory status, established clinical or agronomic use, and repeatable procurement cycles tend to offer more predictable value capture than ambiguous or early-stage segments.
- Look for combination value: manufacturing reliability plus formulation capability plus application-specific support. Companies that only compete on volume or price may face structural margin risk as quality and compliance expectations rise.
- Monitor partnership activity and selective collaborations that signal formulation innovation or expanded indications. Such moves often preview where the next wave of differentiation will emerge.
For Procurement and Commercial Buyers
- Prioritize supplier consistency, analytical validation, and documentation completeness over lowest-unit-cost options, especially when formulations are integrated into regulated or performance-sensitive workflows.
- Align sourcing strategies with end-use requirements. A supplier strong in research-grade reliability may not be the best fit for commercial-scale agricultural or cosmetic programs, and vice versa.
- Build contingency planning into supply agreements. As demand grows across multiple sectors, multi-source strategies, clear quality specifications, and contractual clarity on documentation and batch traceability can reduce operational risk.
Moving from Insight to Execution
The 5-Aminolevulinic Acid market is entering a phase where breadth of opportunity is giving way to the need for precision in execution. Growth will continue, but the distribution of value will increasingly favor companies that combine scientific credibility, application-specific product design, regulatory preparedness, and dependable supply. For decision-makers, the strategic task is to identify which segment aligns with organizational capabilities, which evidence and compliance gaps must be closed, and how supply partnerships should be structured to support growth without exposing the business to unnecessary quality or continuity risk.
Detailed segmentation data, company-level profiling, and scenario-based forecasts can materially improve the quality of strategic planning in this environment. For organizations seeking a deeper, data-rich view of regional dynamics, application breakdown, competitive positioning, and tailored commercial options, the full PW Consulting market research report provides the structured detail and customized analytical support needed to translate these trends into concrete execution plans.
For detailed analysis of this topic, please visit the official page: 5-Aminolevulinic Acid Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Master Data Management Market: Strategic Trends and Commercial Opportunities in a Consolidating Data Economy
The global enterprise data landscape is undergoing a structural transformation, with Master Data Management (MDM) emerging as a critical control layer between fragmented operational systems and AI-driven decision processes. Market valuations have moved steadily upward through the 2020–2025 cycle, climbing from approximately $7.5 billion to $13.3 billion, and forward projections indicate sustained momentum through 2032. A compound annual growth rate of 12.5 percent places MDM among the faster-growing infrastructure categories in enterprise software, reflecting its shift from a specialized governance function to a strategic prerequisite for analytics, automation, and customer-facing applications.
This trajectory is not merely a reflection of incremental IT spending. It signals a deeper realignment in how organizations treat foundational data as a reusable, governed asset rather than a byproduct of operational databases. As organizations pursue data unification across customer, product, supplier, and organizational domains, MDM has become the connective tissue for compliance adherence, operational efficiency, and AI model reliability. For executives and capital allocators, the market's expansion carries both operational urgency and investment relevance. Grasping where value is concentrating, where vendor strategies are diverging, and how regulatory and technological pressures are reshaping procurement decisions is essential for positioning in the next phase of data management adoption.
Market Snapshot: Expansion With Maturing Structure
The MDM market's progression from 2020 through 2025 illustrates a category that has moved beyond early experimentation into mainstream enterprise deployment. Revenue growth accelerated notably as cloud architectures matured, data governance requirements hardened, and organizations recognized that AI initiatives frequently fail without reliable foundational data. Looking toward the 2026–2032 horizon, continued expansion is anticipated, with the market potentially reaching levels above $30 billion by the end of the forecast period. Growth velocity is expected to remain strong, though the character of that growth is changing as consolidation pressures and platform integration agendas reshape vendor positioning and buyer expectations.
Alongside top-line expansion, market structure is becoming more concentrated. A small group of large platform providers and specialized leaders now commands a significant share of enterprise engagements, while mid-tier and niche vendors compete on interoperability, domain specificity, and deployment simplicity. This concentration matters for decision-makers because it changes the purchasing environment: risk is shifting toward integration complexity, vendor lock-in, and the ability to govern data that spans both legacy and next-generation systems. At the same time, concentration is creating clearer reference architectures and more defined evaluation criteria for enterprises that need MDM to support cross-functional data products.
Core Challenges and Inflection Points
Despite strong demand, MDM adoption continues to face friction that limits the pace at which organizations can convert data unification ambitions into durable production outcomes. One persistent challenge is an operational paradox: many enterprises want MDM to be comprehensive, but comprehensive deployments often stall under the weight of governance overhead, cross-departmental alignment, and change management. MDM is no longer a one-time master data cleanup exercise; it increasingly requires continuous stewardship, workflow discipline, and integration with data quality and observability practices. Organizations that underestimate these operating requirements frequently encounter delayed time-to-value and reduced adoption across business units.
A second inflection point involves the collision between AI ambitions and data readiness. Enterprise interest in generative AI, agentic workflows, and advanced analytics has accelerated the realization that model performance and trustworthiness depend heavily on the consistency, lineage, and contextual completeness of master data. This has reframed MDM from a back-office governance concern to a front-line enabler of AI use cases. The challenge is that many existing MDM deployments were not designed for high-velocity, AI-ready data products. Bridging that gap requires new integration patterns, metadata enrichment, and governance that can accommodate both strict regulatory controls and the flexibility demanded by modern data architectures.
A third challenge is regulatory and compliance fragmentation across geographies and sectors. As privacy obligations, reporting mandates, and industry-specific standards continue to evolve, MDM implementations must support auditable stewardship, hierarchy management, and recordkeeping without becoming brittle. Compliance is no longer a side benefit; it is becoming a design constraint that shapes vendor selection, data model architecture, and operational workflows. Enterprises operating in multiple jurisdictions or regulated industries face a more complex balancing act between speed of deployment and durability of governance.
Primary Growth Drivers Reshaping the Market
Several interrelated forces are intensifying demand for MDM and changing the way solutions are evaluated. The first is technological innovation centered on AI-augmented data unification and cloud-native data foundations. MDM platforms are increasingly expected to support intelligent matching, automated stewardship, and continuous data quality feedback loops, reducing the manual burden that historically slowed adoption. This is particularly relevant as organizations attempt to scale data products across functions without proportionally increasing specialized labor. Embedded training, certification, and guided workflows are becoming part of the value proposition because they lower the practical cost of adoption and help standardize data governance practices across teams.
The second driver is the regulatory environment, which is turning data governance from an optional discipline into a compliance necessity. Privacy regulations and sector-level requirements are expanding the scope of data that must be traceable, correctable, and consistently governed. MDM architectures that provide documented stewardship workflows, hierarchy controls, and audit-ready trails are becoming more attractive in environments where data errors or inconsistent records create legal, operational, or reputational exposure. In parallel, emerging sustainability and environmental reporting expectations are adding new categories of master data that require governance and consistency, extending the relevance of MDM beyond traditional customer and product domains.
The third driver is demand-side behavior, particularly the growing expectation that enterprise data should support real-time, customer-centric, and cross-functional use cases. Organizations are moving away from treating master data as static reference content toward viewing it as an active input to segmentation, personalization, supply continuity, product lifecycle management, and trusted analytics. That shift creates demand for MDM solutions capable of producing reliable golden records, supporting multi-domain unification, and integrating with broader data platforms and cloud ecosystems. As consumers and business users alike expect more coherent experiences and more accurate information, the cost of fragmented master data becomes more visible and more consequential.
The fourth driver relates to the evolving cost and integration structure of enterprise data environments. Organizations are increasingly managing hybrid landscapes that blend legacy systems, cloud data platforms, and specialized applications. MDM that can operate across these environments without forcing a full platform replacement is gaining relevance because it reduces migration risk and preserves existing investments. This dynamic favors solutions that offer flexible deployment models, strong integration hooks, and the ability to function as a governed data layer rather than a closed ecosystem. The market is therefore rewarding vendors that can reduce complexity rather than add another rigid layer of infrastructure.
Competitive Dynamics and Strategic Positioning
The competitive landscape reflects a mix of platform-scale providers, specialized MDM vendors, and emerging entrants with strong cloud or AI orientations. Large enterprise platform companies continue to anchor the market by embedding MDM capabilities within broader data management and business application ecosystems. Their advantage lies in cross-functional reach, existing customer relationships, and the ability to connect master data governance with ERP, analytics, and cloud infrastructure strategies. In this context, MDM becomes part of a wider harmonization and AI-readiness agenda, which can simplify procurement for organizations already committed to a primary platform but can also raise integration dependency concerns for those seeking vendor flexibility.
Specialized vendors, meanwhile, compete on depth, agility, and targeted domain strengths. Some emphasize AI-powered SaaS platforms for multi-domain unification and governance, with particular attention to integration with widely used CRM and data ecosystems. Others differentiate through cloud-native architectures that support rapid scaling across business functions and simplify data cleaning and unification. Several leaders have positioned around multi-domain data platforms with strong governance, AI-ready data products, and native integration into modern cloud data warehouses. A further segment focuses on augmented platforms that combine MDM with embedded data quality and automation, appealing to organizations that want governance and quality in a single operational flow. In regulated verticals, product information management-oriented vendors extend MDM capabilities into lifecycle and compliance use cases where traceability and controlled authoring are critical.
Recent strategic movements make the consolidation theme especially visible. Major platform transactions completed in recent years demonstrate how MDM is being absorbed into broader data management and business data clouds. These moves are designed to strengthen AI-ready data unification across both native and external systems, while also expanding the reach of governance, quality, and master data capabilities within larger ecosystems. For buyers, this signals a market in which MDM is increasingly evaluated not as a standalone utility but as part of a larger data architecture strategy. The practical implication is that vendor selection is becoming more about ecosystem fit, integration roadmap, and long-term governance model than about point-feature comparison alone.
At the same time, analyst recognition and product releases indicate that differentiation remains highly active. Leadership placements in independent evaluations, continued platform releases, and public commitments to AI-powered MDM and broader ecosystem integration show that competition is not simply about scale. Vendors are competing on stewardship usability, compliance readiness, interoperability, and the ability to lower labor and training barriers to adoption. These factors matter because they influence not just initial purchase decisions but the likelihood that MDM will be operationalized effectively across the enterprise.
PW Consulting Information & Electronics Research Center
Strategic Implications of Market Evolution
One clear trend is the convergence of MDM with broader data governance, data quality, and data product thinking. The market is moving toward solutions that can serve as governed data foundations for multiple downstream consumers, including analytics, AI, customer operations, and supply chain processes. This convergence is reducing the isolation of MDM as a niche repository and increasing its role as an active contributor to enterprise data value chains. Organizations that treat MDM as a product platform rather than a static catalog are more likely to extract sustained value from their investments.
Another trend is the growing importance of interoperability across heterogeneous environments. As companies continue to accumulate cloud data platforms, legacy systems, and specialized applications, MDM must bridge gaps without demanding full architectural standardization. Solutions that support flexible integration, strong metadata handling, and consistent governance across environments are positioned to capture demand from enterprises that need progress without wholesale replacement. This favors a more practical, integration-aware buying posture, where evaluation criteria emphasize time-to-value, data product readiness, and operational maintainability.
A third trend is the increasing alignment between MDM and compliance-driven data operations. The demand for auditable workflows, stewardship accountability, and reliable hierarchy management is expanding the functional scope of MDM implementations. This is particularly relevant for organizations operating across regions or industries with distinct data obligations. MDM is increasingly expected to help demonstrate control, support reporting, and reduce exposure from inconsistent or poorly governed foundational data. In this environment, solution evaluation increasingly includes evidence of governance maturity, not just unification capability.
Digital Rights Management (DRM) Market
Future Outlook: Three Strategic Trajectories
Over the next three to five years, the MDM market is likely to be shaped by the continued blending of governance, AI readiness, and platform integration. One trajectory is the acceleration of AI-native MDM capabilities that support automated matching, stewardship assistance, and continuous data quality improvement. This will not eliminate the need for human oversight, but it should reduce the operational friction that has historically constrained scale. Commercial opportunities will arise for vendors and implementers that can demonstrate measurable improvements in data consistency, time-to-golden-record, and stewardship efficiency without sacrificing control.
A second trajectory is deeper embedding of MDM into broader data and application ecosystems. As enterprises pursue unified data foundations for analytics and AI, MDM is likely to be evaluated more often as part of a combined platform strategy rather than a discrete project. This creates opportunities for organizations that can connect master data governance with cloud data platforms, CRM workflows, and operational systems in a coherent way. It also raises the stakes for enterprises that must manage dependency risk and ensure that MDM remains adaptable if platform strategies shift.
Patient Data Management Systems (PDMS) Market
A third trajectory involves the widening applicability of MDM into sustainability, supply chain, and regulated product data contexts. As reporting obligations and operational transparency requirements grow, governed master data will become more relevant to environmental compliance, product traceability, and cross-border trade documentation. Commercial value will accrue to organizations that can extend MDM beyond traditional customer and product domains into new governance-sensitive areas. The uncertainty here lies in how quickly standards, data definitions, and audit expectations will crystallize across industries and regions, which will influence the pace of adoption in these newer use cases.
Actions for Decision-Makers Across Different Roles
For enterprise executives and strategy teams, the central task is to treat MDM as an operational capability with measurable business outcomes rather than a data cleanup initiative. That means defining the data domains that matter most to revenue, compliance, and customer experience, then investing in governance workflows, stewardship accountability, and integration to AI or analytics pipelines. Prioritizing use cases that produce visible improvements in customer data consistency, product information accuracy, or regulatory readiness can accelerate organizational support and reduce the risk of stalled deployments.
For technology and procurement leaders, the evaluation criteria should extend beyond feature lists to the reality of operating the platform in a hybrid enterprise. Important considerations include how well the solution supports multi-domain unification, how easily it integrates with existing cloud data environments, how it handles stewardship and compliance workflows, and how it lowers training and operational costs through usability and guided processes. Procurement decisions should also account for long-term adaptability, especially as platform consolidation, ecosystem integrations, and AI readiness requirements continue to evolve.
For investors and market participants, the key is to distinguish between vendors with durable differentiation and those that are primarily riding platform momentum. Value creation will increasingly depend on the ability to maintain AI-ready data products, support multi-domain governance, and demonstrate measurable improvements in data quality and operational efficiency. Monitoring strategic consolidation, ecosystem integrations, and analyst recognition can provide useful signals, but the underlying question remains whether a vendor's MDM capability is becoming a genuine enabler of enterprise data products or mainly a feature within a broader platform narrative.
Conclusion: Data Foundations as Strategic Leverage
The MDM market is expanding in a context where data is no longer a side concern but a core organizational capability. Growth is being driven by AI readiness demands, regulatory complexity, cloud-based data architectures, and the growing cost of inconsistent master data across customer, product, and operational domains. At the same time, the market is consolidating and maturing, which means the strategic question for most organizations is not whether to strengthen master data governance, but how to do so in a way that delivers durable, scalable value.
Organizations that succeed will be those that align MDM with real business outcomes, choose integration paths that reduce friction, and build governance models that can support both compliance and AI-driven innovation. Given the pace of change, timely access to detailed segment-level data, vendor benchmarking, and use-case-specific guidance can materially improve planning accuracy and investment confidence. For those seeking a deeper view of segmentation dynamics, competitive positioning, and tailored strategic options, the full PW Consulting research report provides a more granular basis for decision-making and next-step execution planning.
For detailed analysis of this topic, please visit the official page: Master Data Management (MDM) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Posture Correctors Market: Why 6.5% CAGR and Fragmented Demand Rewrite Strategy
By pmarketresearch, 2026-09-21
Navigating the Posture Correctors Market: Strategic Shifts and Commercial Trajectories (2026–2032)
The posture correction landscape is undergoing a structural transformation. Once confined to clinical rehabilitation and basic ergonomic aids, the category has absorbed consumer wellness demand, smart-device integration, and cost pressures from global manufacturing. The sector has expanded from a $134.2 million baseline in 2020 to an estimated $186.0 million in 2025, with the trajectory continuing toward the high $280 million range by 2032. A compound annual growth rate of 6.5 percent across the 2026–2032 forecast window signals steady, rather than explosive, expansion. This pace rewards disciplined execution: companies that align product architecture, compliance readiness, and channel strategy will capture disproportionate value, while those relying on generic positioning will face margin compression and channel consolidation.
Three structural realities define the current market state. First, the category sits at the intersection of consumer self-care and clinical expectation, creating tension around efficacy claims, user retention, and reimbursement pathways. Second, pricing dispersion—from roughly $15 for passive supports to the high $90s for smart wearables—reflects divergent value propositions that are not yet fully resolved by consumer education or procurement standards. Third, the competitive field is moderately concentrated, with the top three players accounting for around 25 percent of revenue and the top five near 35 percent, leaving meaningful space for differentiation but also inviting consolidation moves that reshape distribution leverage.
Market Landscape and Core Challenges
The revenue curve shows a notable inflection between 2022 and 2023, followed by more measured gains through 2025. This pattern aligns with a market that has absorbed pandemic-era ergonomic attention and is now normalizing around sustained workplace habits, active aging, and a broader acceptance of posture as a wellness indicator rather than a purely medical issue. Growth is no longer driven by a single catalyst; it is being distributed across adult consumers seeking daily comfort, geriatric users requiring stability, and younger segments influenced by screen-time awareness and athletic recovery practices.
The first core challenge is claim validation and user adherence. Passive braces and support devices can deliver immediate perceptual relief, but long-term posture change depends on neuromuscular retraining, habit formation, and behavioral design. Products that rely solely on mechanical correction often face churn once the initial discomfort subsides, while offerings that integrate feedback loops or training protocols must prove that their cues produce durable outcomes. The gap between short-term comfort and sustained alignment remains the category’s most persistent commercial friction.
The second challenge involves reimbursement ambiguity and channel dependency. While many posture correctors are positioned as consumer or wellness products, their functional overlap with spinal support and post-trauma stabilization places them near clinical categories. In the current policy environment, posture correctors are generally treated as Class I devices in the United States, which means premarket notification is not required provided basic labeling standards are met. At the same time, there are no dedicated CPT or HCPCS reimbursement codes in the 2026 Medicare Physician Fee Schedule final rule for these devices, and FDA registration remains required for manufacturers even without hospital billing codes. This combination limits institutional procurement as a reliable growth engine and elevates the importance of direct-to-consumer, retail, and professional-channel strategies.
The third challenge is cost architecture and product tiering. Medical-grade fabrics and polymer components influence unit economics, and the spread between passive and smart models creates a bifurcated market. Manufacturers must decide whether to compete on accessibility and volume, or on sensing, feedback, and app-linked engagement. This decision is not cosmetic: it shapes supply chain complexity, after-sales support, and the credibility of efficacy narratives. Companies that attempt to straddle both tiers without clear segmentation risk diluting brand signal and inflating operational cost.
Key Demand Drivers
Technology innovation and behavioral design
Smart wearables have introduced a new value layer to the category. Devices that combine haptic feedback with app-based tracking are shifting the conversation from static correction to active training. The most relevant innovation is not the sensor itself, but the behavioral loop around it: short, repeated cues that encourage habit formation and make posture correction feel achievable rather than prescriptive. Products that have reached meaningful user bases through this model illustrate the commercial potential of engagement-led design. The emergence of two-week habit-formation narratives, for example, reflects an understanding that adoption depends on measurable progress and low-friction daily use. This design philosophy is increasingly expected by consumers who compare posture tools to fitness and sleep technologies.
Beyond wearables, the broader innovation frontier includes material comfort, ergonomic geometry, and hybrid product architectures. Cushion-based seating support, posture bands, and neuromuscular activation approaches each address different user pain points. The strategic question is how to combine immediate relief with longer-term correction without overcomplicating the product or the purchase decision. Companies that clarify this balance are better positioned to defend price and reduce returns.
Policy and regulatory environment
Regulatory clarity is simultaneously enabling and constraining. On the enabling side, Class I classification and 510(k) exemption reduce time-to-market barriers for many posture correctors, provided labeling and registration requirements are satisfied. Harmonized quality management expectations, such as ISO 13485 references across global supply chains, also support cross-border compliance and can smooth distributor onboarding in multiple markets. On the constraining side, the absence of dedicated reimbursement codes keeps posture correctors largely outside institutional payment flows, reinforcing a consumer and professional-channel orientation. This does not block growth, but it does reshape the economics: customer acquisition, retention, and repeat purchase cycles matter more than bulk clinical procurement.
Worldwide Spinal Orthosis Market
For manufacturers, this environment rewards upfront compliance discipline. Registration readiness, labeling consistency, and documentation that supports professional recommendations can become differentiators in channels where clinicians, physiotherapists, and ergonomic advisors influence purchase decisions. In contrast, brands that treat compliance as an afterthought face higher friction when scaling internationally or entering retail and professional networks.
Demand-side behavior and lifestyle shifts
Demand is being reshaped by the normalization of remote and hybrid work, increased screen time, and a growing awareness of musculoskeletal discomfort as a daily quality-of-life issue. Adults represent the largest application segment by volume, reflecting both workplace ergonomics and self-directed wellness spending. At the same time, geriatric and pediatric segments are gaining relevance for different reasons: aging populations seek stability and fall-prevention support, while younger users are influenced by posture education, sports recovery, and parent-guided ergonomic interventions.
Behaviorally, consumers are comparing posture products against broader wellness categories. They expect comfort, discretion, and evidence-informed claims. They also respond to tools that integrate into existing routines rather than requiring a separate regimen. This places a premium on minimalist design, intuitive wear patterns, and clear instructions that connect product use to tangible outcomes such as reduced discomfort or improved sitting posture during long work sessions.
Supply chain and cost structure dynamics
Cost structures remain sensitive to material selection and assembly complexity. Medical-grade fabric and polymer components establish a pricing floor for products that want to signal durability and skin-safe wear, while smart components add electronics, software support, and return-rate management. These choices affect not only unit price but also margin resilience when input costs fluctuate. Manufacturers relying on single-region sourcing face greater exposure, while those with diversified supplier bases and clear bill-of-materials segmentation can adjust faster to cost pressure.
The distribution side is also evolving. Recent activity shows companies expanding through acquisition and channel integration, signaling that scale and reach are becoming increasingly valuable. Product launches targeting immediate posture and alignment needs suggest that firms are prioritizing fast-turn use cases alongside longer-term support solutions. These moves indicate a market in which manufacturers are trying to balance breadth, speed, and specialization rather than relying on a single product narrative.
Competitive Landscape and Leading Strategies
The competitive field is defined by divergent approaches to the same core problem: how to improve posture in a way that users will actually sustain. One cluster emphasizes immediate mechanical support and comfort. Brands in this group focus on cushions, bands, and orthotic-style supports that address pelvic alignment, spinal support, and post-trauma stabilization. Their value proposition is tangible and often easy to demonstrate, which makes them attractive in professional referrals and retail environments where quick perceived benefit matters.
A second cluster emphasizes neuromuscular activation and natural posture training. These offerings aim to reduce dependence on constant wear by encouraging the body to maintain better alignment through balance and muscle engagement. This approach appeals to users who want longer-term change without feeling permanently braced. It also aligns with a broader shift toward active correction rather than passive restriction.
Worldwide Hip Orthosis Market
A third cluster centers on smart feedback and habit formation. Wearable devices that use vibration cues and app-based tracking are designed to make posture correction a short, repeatable behavior. By framing the product as a training tool rather than a permanent support, these brands try to solve the adherence problem that limits many passive devices. Their commercial success depends on software experience, user onboarding, and credible progress metrics as much as on hardware quality.
Other players contribute through specialization. Some focus on spinal orthoses and stabilization lines for post-trauma and longer-term support, reinforcing credibility in clinical-adjacent channels. Others extend into sports performance and joint support, where posture and alignment intersect with athletic movement. Still others pursue brand-led distribution through professional and direct channels, using specialized positioning to avoid competing solely on price.
Recent company-level moves illustrate how the landscape is evolving. One major sports medicine supplier expanded its bracing and posture support lineup through acquisition, integrating new devices into existing distribution channels. This kind of move increases assortment depth and can strengthen retailer relationships, but it also raises the bar for portfolio clarity: buyers increasingly expect coherent product families rather than loosely connected SKUs. Elsewhere, a medical products company appointed new leadership with a mandate to drive growth in posture correction and spinal bracing, a signal that posture is being treated as a strategic segment rather than a byproduct of broader orthopedic offerings. At the same time, another firm launched new products aimed at immediate posture correction and alignment needs, reflecting continued investment in fast-cycle use cases. Together, these developments point to a market where both scale plays and targeted launches are being used to capture share.
Market structure appears poised for selective consolidation rather than uniform concentration. Moderate concentration at the top leaves room for specialized entrants, but channel economics increasingly reward breadth, compliance readiness, and brand trust. New entrants are most likely to succeed by solving a specific user problem well—smart training for desk workers, discreet support for active aging, or comfortable seating aids for hybrid workplaces—rather than by launching general-purpose posture products into saturated retail channels. The differentiation frontier is moving toward integration: hardware that is comfortable and durable, behavior design that supports adherence, and channel strategy that matches the product’s intended use.
Forward Outlook: Trends and Commercial Opportunities
From passive support to behavior-led correction
Over the next three to five years, the most commercially relevant shift is likely to be the continued migration from static correction toward feedback-informed training. This does not mean passive devices will disappear; many users will still want immediate comfort and support. However, products that combine ergonomic design with lightweight cues and simple progress tracking will gain relevance because they address the adherence gap that limits long-term outcomes. The commercial opportunity lies in packaging this experience clearly: users should understand what the product does in the first minutes, what changes over weeks, and how success is measured. Brands that articulate this journey effectively can reduce returns, improve word-of-mouth, and support premium pricing within the smart and hybrid tiers.
Channel rebalancing and professional influence
As reimbursement remains limited and direct consumer competition intensifies, professional and ergonomic channels will become more important as trust intermediaries. Physiotherapists, workplace wellness programs, chiropractors, and ergonomic consultants can reduce purchase uncertainty by aligning products with specific use cases. The strategic implication is that manufacturers should design for recommendability: clear labeling, consistent quality, and product narratives that distinguish post-trauma support from daily posture training. Companies that make it easy for professionals to recommend the right product for the right user will gain a defensible channel advantage, especially where retail shelves are crowded and online comparisons are fragmented.
PW Consulting
Segmented product architecture and pricing clarity
The pricing spread across passive and smart models will likely persist, but successful portfolios will become more deliberate about segmentation. The opportunity is to avoid internal cannibalization by defining separate use cases, user journeys, and price anchors for each tier. For example, seating support and posture bands can anchor accessibility and immediate comfort, while smart wearables and neuromuscular solutions can target habit formation and longer-term training. When segmentation is clear, marketing becomes more efficient, customer expectations are better aligned, and after-sales support can be tailored to product complexity. Companies that treat pricing as a strategic map rather than a reactive lever will be better equipped to defend margins as competition increases.
Risks and uncertainties
The outlook carries real uncertainty. Regulatory classifications may be revisited as posture devices continue to blur consumer and clinical boundaries, potentially reshaping labeling expectations or market access requirements. Reimbursement dynamics could shift if professional usage patterns change or if institutions seek standardized ergonomic interventions, but reliance on such changes would be speculative. On the demand side, adoption can stall if users perceive limited long-term benefit, if app-based features create friction, or if competing wellness categories draw attention and spending elsewhere. Supply-side risks include material cost volatility, component availability for smart models, and the operational burden of managing returns and support for connected products. Finally, consolidation could tighten distribution leverage for smaller brands, making channel partnerships and professional credibility more valuable than ever.
Strategic Implications for Decision-Makers
For manufacturers and product leaders
- Define a clear posture problem and avoid over-broad positioning. Products that solve a specific use case—desk-related discomfort, post-trauma stabilization, active sitting, or habit-based training—can communicate value more precisely and reduce return rates.
- Invest in adherence mechanics as much as hardware. Comfort, discretion, and intuitive wear matter, but so do cues, onboarding, and simple progress feedback. If the product depends on repeated use, the experience must make repetition easy.
- Align compliance and documentation with your target channel. Registration readiness, labeling consistency, and quality system references become commercially relevant when professionals, retailers, or international distributors are part of the growth plan.
- Segment the portfolio deliberately. Separate accessibility-driven products from engagement-driven products so that pricing, marketing, and support do not blur together and undermine margin.
For investors and strategic planners
- Look for durable differentiation rather than feature novelty. Sensor-led products can attract attention, but long-term value depends on retention, user outcomes, and channel trust. Evaluate whether a company has a credible path to repeat use and recommendability.
- Assess channel resilience. Companies with diversified routes to market—consumer, professional, retail, and direct—may be better positioned if reimbursement remains limited or if retail competition intensifies.
- Monitor consolidation signals. Acquisitions and leadership changes focused on posture and spinal support suggest that scale and portfolio coherence are becoming strategic assets. Consider how target companies would fit within a consolidating distribution environment.
For procurement and channel decision-makers
- Match the device to the user outcome. Immediate relief, postural training, and stabilization are not interchangeable needs. Procurement criteria should reflect whether the priority is comfort, alignment support, or behavior change.
- Prioritize consistency and recommendability. In professional and workplace settings, documentation, labeling clarity, and predictable quality often matter more than marginal feature differences. Products that are easy to explain and safe to recommend reduce adoption friction.
- Evaluate total cost of ownership for smart solutions. Connected devices may require app support, user onboarding, and return management. Procurement should weigh these operational factors alongside unit price.
The posture correctors market is maturing into a more disciplined competition between comfort, correction, and compliance. Growth at a steady mid-single-digit pace will reward companies that can articulate a specific posture problem, build an experience people will actually use, and position themselves where trust can be earned—whether through professional recommendation, retail clarity, or direct consumer engagement. For decision-makers seeking deeper segment mapping, regional dynamics, pricing architecture, and customized scenario planning, the full PW Consulting research report provides the detailed breakdowns and forward modeling needed to translate these trends into precise commercial choices.
For detailed analysis of this topic, please visit the official page: Posture Correctors Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com