

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
BCTMP Market 2026: The Real Drivers Behind the 5.25% CAGR Growth Trajectory

Beyond Volume: Strategic Realignment in the Bleached Chemi-ThermoMechanical Pulp Market
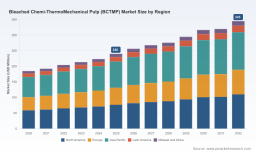
The Bleached Chemi-ThermoMechanical Pulp (BCTMP) market stands at a structural inflection point. Over the past five years, the segment has expanded steadily, with industry revenue climbing from approximately $185 million in 2020 to an estimated $240 million in 2025. Forward-looking projections indicate the market will surpass $345 million by 2032, translating to a compound annual growth rate of roughly 5.25% between 2026 and 2032. This trajectory is not merely a function of incremental demand growth; it reflects a broader reconfiguration of fiber economics, regulatory expectations, and downstream application requirements. BCTMP has carved out a strategic middle ground between mechanical pulps and fully chemical pulps, offering producers a high-yield, energy-efficient pathway to deliver brightness and bulk properties that align with modern paperboard, tissue, and specialty printing formats. Yet the reliability of this middle ground is being tested by tightening environmental mandates, shifting consumer-facing material preferences, and capital allocation pressures across a fragmented but increasingly active producer base.
For executives and strategic planners navigating fiber procurement, capacity planning, or portfolio allocation, the BCTMP segment warrants close attention precisely because it sits at the intersection of cost discipline and performance customization. The market’s growth is real, but its composition is changing. Volume expansion alone no longer guarantees margin resilience or customer retention. The following analysis maps the forces reshaping the BCTMP landscape, distinguishes durable drivers from transient cycles, and frames the strategic choices that will separate adaptive operators from those exposed to regulatory friction and competitive squeeze.
Market Context and Core Challenges
The current BCTMP market is defined by three overlapping realities. First, demand continues to track upward, but the growth is uneven across end-use categories and geographies, creating pockets of oversupply in mature paper segments and acute tightness in tissue and lightweight packaging grades. Second, the industry is confronting a regulatory and sustainability transition that is no longer a future concern but a present-day capital and operational constraint. Third, cost structures are being reshaped by input volatility, energy integration requirements, and the need to maintain consistent pulp specifications under more complex bleaching and effluent management protocols.
One of the most immediate challenges is the tension between capacity additions and demand absorption. Several major producers have brought new lines online or expanded existing facilities, particularly in Europe and Asia, while traditional newsprint and printing volumes continue to erode in multiple markets. The result is a market where aggregate capacity can grow while the highest-value grades become increasingly contested. Producers are being forced to differentiate on fiber blend, brightness, bulk, and drainage characteristics rather than compete purely on tonnage. This shift raises the operational bar: consistency at scale, flexibility in grade conversion, and the ability to validate sustainable sourcing claims have become baseline expectations rather than optional enhancements.
A second challenge lies in the regulatory environment. Effluent discharge standards, water stewardship requirements, and carbon reduction targets are tightening across major producing regions. These rules do not merely impose compliance costs; they reshape the economics of mill operation by increasing the returns to energy recovery, process integration, and cleaner production technologies while penalizing older configurations that rely on less efficient bleaching or higher discharge loads. At the same time, downstream customers and brand owners are increasingly tying procurement decisions to traceable and deforestation-free fiber, meaning compliance is becoming a commercial prerequisite, not just an environmental one.
A third challenge is cost and margin volatility. BCTMP production is sensitive to fiber quality, chemical consumption, utilities, and transport. Mills that can integrate biomass-derived energy, recover and reuse process streams, and optimize chemical usage gain a structural cost advantage. Those without such integration face more exposed cost curves and less flexibility when input prices spike. In a market where procurement contracts increasingly reference sustainability attributes and consistent specification performance, cost leadership is being redefined around efficiency, recovery, and traceability rather than sheer scale alone.
Key Drivers Reshaping the BCTMP Market
Technology Innovation and Process Differentiation
Process innovation remains a central driver of competitive positioning in BCTMP. Producers are moving beyond generic high-yield pulps toward recipes that balance bulk, brightness, and strength while reducing chemical and energy intensity. Bleaching configurations that emphasize environmentally compliant reagents, reduced effluent loads, and flexible grade adjustment are becoming differentiators. In practical terms, mills are designing for controllability: the ability to deliver distinct hardwood and softwood variants, adjust bulk and drainage profiles for specific board or tissue needs, and maintain brightness stability without relying on heavier chemical regimes. These capabilities support premiumization in tissue and hygiene grades, where bulk and softness are critical, and enable lighter-weight packaging designs that depend on high-bulk pulp to maintain stiffness at lower grammages.
Recent equipment and line commissioning activity illustrates this direction. In China, a major phase startup expanded BCTMP capacity and reflected the continued push to localize high-yield pulp supply for board and packaging applications. In Europe, a Nordic producer introduced a bleached hardwood BCTMP grade derived from Nordic birch fibers, engineered for high bulk and high brightness, with specifications that can be adjusted for different end-use requirements. These moves signal a broader industry shift: BCTMP is increasingly positioned as a customizable, grade-specific input rather than a commodity bulk fiber. The strategic implication is that production flexibility, specification engineering, and quality consistency are becoming as valuable as volume.
Policy and Regulatory Realignment
Policy frameworks are reshaping both the cost floor and the market access conditions for BCTMP. Stricter effluent norms and carbon reduction targets require ongoing investment in cleaner production and treatment infrastructure. At the same time, regulatory regimes focused on sustainable sourcing are pushing traceability and deforestation-free fiber into procurement criteria. These dynamics elevate the importance of mills that can document chain-of-custody, demonstrate responsible forestry, and operate processes compatible with lower-emission targets. Mills that integrate biomass energy and black liquor recovery are better positioned to navigate carbon pricing and renewable energy expectations, converting compliance from a burden into a competitive lever.
Regulatory pressure also interacts with downstream substitution dynamics. As brands and converters seek materials that support lighter-weight designs, recyclable packaging formats, and hygiene product performance, BCTMP’s high-yield and bulk properties make it relevant to these targets, provided the fiber can be sourced and produced in ways that align with corporate sustainability commitments. In effect, regulation is compressing the market into two directions at once: it raises the operational bar for producers, while simultaneously creating demand pull from end-users who need fiber that meets both performance and sustainability specifications.
Demand-Side Reconfiguration
Downstream demand is being reshaped by two long-running shifts: the contraction of legacy printing and newsprint channels and the expansion of tissue, hygiene, and lightweight packaging applications. Tissue and hygiene products continue to represent a substantial share of BCTMP consumption, driven by sustained consumer demand and product engineering that favors bulk, softness, and absorbency. Packaging applications, particularly lightweight coated board and cartonboard structures, also rely on high-bulk pulp to achieve stiffness goals without adding mass. This application mix favors producers with grade flexibility and the ability to serve multiple end-use clusters from a single asset base.
Worldwide Unbleached Kraft Pulp (UKP) Market
Consumer-facing expectations are reinforcing this shift. Hygiene brands are increasingly optimizing for comfort and performance while also seeking materials that align with broader environmental narratives. In packaging, converters and brand owners are pursuing weight reduction and material efficiency, which translates into demand for pulps that contribute bulk and surface properties at lower basis weights. These behaviors change the commercial calculus for BCTMP suppliers: customers are not just buying volume, they are buying engineered fiber attributes that help them hit downstream performance and sustainability targets.
Supply Chain and Cost Structure Evolution
The economics of BCTMP production are increasingly defined by integration, energy recovery, and logistics. Mills with co-located energy recovery, efficient water management, and robust chemical reuse systems enjoy more stable cost structures and greater resilience to utility and input fluctuations. Conversely, producers reliant on less integrated configurations face more exposed margins. Logistics and fiber sourcing patterns matter as well, particularly as mills seek fiber that meets provenance and sustainability expectations while remaining cost-competitive across regional transport routes.
This dynamic is encouraging both operational modernization and strategic realignment of sourcing footprints. Some producers are optimizing around local fiber availability and established logistics corridors, while others are upgrading process lines to improve yield, reduce chemical demand, and enhance grade flexibility. The practical effect is a market where cost advantage is less about raw tonnage and more about total system efficiency, including energy, water, chemicals, and traceability.
Competitive Landscape and Leading Strategies
The BCTMP space features a diverse set of participants spanning North American integrated producers, Nordic mills with strong sustainability positioning, and Asian operators expanding capacity to serve regional board and tissue demand. Several incumbents hold meaningful scale in specific grades, while newer or expanding players are pursuing targeted capacity additions and product specialization. The overall market structure reflects moderate concentration, with a handful of large producers accounting for a substantial share of output, but with enough fragmentation to sustain active competition on grade, region, and application focus.
Leading producers differentiate through a combination of grade breadth, process sustainability, and integration. North American operators continue to supply softwood and hardwood BCTMP variants for tissue, packaging, and printing-related uses, often leveraging regional fiber logistics and established customer relationships. Nordic producers emphasize high-yield and environmentally compatible bleaching configurations, aligning their product attributes with tissue and packaging needs while reinforcing sustainability credentials through traceable fiber and lower-impact processes. Asian producers are expanding to meet localized demand for lightweight board and tissue grades, reinforcing the geographic diversification of supply.
Strategic differentiation is increasingly tied to three themes. First, grade engineering: mills that can deliver specific bulk, brightness, and drainage profiles for tissue, board, or specialty applications command more favorable positioning than those offering undifferentiated volume. Second, sustainability integration: producers that can connect fiber sourcing, process chemistry, and energy recovery to verifiable environmental outcomes are better positioned for customers whose procurement decisions incorporate traceability and compliance requirements. Third, operational flexibility: the ability to adjust production across grades, manage specification consistency, and respond to regional demand shifts is becoming a valuable asset in a market where end-use mix continues to evolve.
The competitive dynamic is shifting along two axes. On the consolidation side, larger producers are strengthening their positions through operational scale, integration, and product specialization, which can raise barriers for smaller players without comparable process or sourcing advantages. On the fragmentation and new entry side, capacity additions in select regions and targeted grade launches are creating localized competition and expanding optionality for downstream buyers. This combination suggests a market that will remain active and multi-polar, with winners determined less by geography alone and more by the ability to deliver the right fiber attributes with defensible cost and compliance profiles.
Notable Industry Movements and What They Signal
Several recent developments illustrate how the competitive and strategic themes are playing out in practice. One European producer launched a high-bulk, high-brightness hardwood BCTMP grade from Nordic birch fibers, highlighting the push toward specification customization and sustainable forestry alignment. Another operator completed a modernization program that raised daily capacity and reflected the continued emphasis on scale and efficiency improvements in producing regions. A Nordic mill advanced the design phase for a new BCTMP line, signaling confidence in demand for high-yield pulp in tissue and packaging applications. Meanwhile, a phase startup in China added capacity for BCTMP, reinforcing the trend toward regional supply growth tied to board and hygiene demand.
PW Consulting
These moves collectively indicate that investment is flowing toward capacity where demand is strongest and toward grades where differentiation is most defensible. The pattern is not simply additive; it is selective. Producers are expanding where they can combine volume growth with usable grade flexibility, credible sustainability positioning, and integration advantages. That selectivity matters for buyers and investors because it shapes where competition intensifies, where supply tightens, and where pricing power is likely to be contested.
Strategic Outlook: Trends and Opportunities for 2026–2032
Looking ahead, three trends are likely to define the BCTMP market over the next several years. First, application-led grade specialization will deepen. As tissue, hygiene, and lightweight packaging continue to absorb growth while legacy printing volumes decline, producers will face stronger incentives to customize bulk, brightness, and drainage characteristics. Mills capable of producing distinct hardwood and softwood variants with consistent quality and flexible specifications will capture more value than those competing solely on volume. This trend favors assets and operating models that can shift output across applications without sacrificing specification integrity.
Second, sustainability and compliance will increasingly function as commercial gateways. Traceable fiber, deforestation-free sourcing, and cleaner production are becoming connected to procurement decisions and market access. Mills that can demonstrate process efficiency, energy recovery, and responsible sourcing will find more options in customer qualification processes, while those with weaker documentation or higher-impact configurations may face narrower pathways to premium segments. The opportunity here is not compliance alone but the ability to use credible sustainability attributes as part of a differentiated value proposition, particularly in applications where downstream brands are sensitive to material positioning.
Third, cost and margin discipline will be redefined by integration and recovery. Energy efficiency, water stewardship, chemical optimization, and black liquor or biomass-derived energy recovery will increasingly separate resilient producers from exposed ones. As carbon costs and regulatory expectations rise, the economic premium on integrated, lower-intensity operations will grow. The strategic upside lies in combining cost stability with grade flexibility, enabling producers to serve higher-value applications while maintaining margin durability through cycles.
These trends create clear commercial opportunities. Producers can pursue premiumization through specification control, target application clusters with stronger demand momentum, and invest in process configurations that reduce exposure to regulatory and energy cost pressure. Buyers can use grade selectivity and supplier qualification to secure fiber that supports both performance and compliance goals. Investors can focus on assets and operators with credible integration, traceability, and grade flexibility, recognizing that future returns will be tied to operational adaptability as much as to capacity scale. At the same time, uncertainty persists around the pace of legacy paper decline, the stringency and timing of regulatory implementation, and the extent to which regional capacity additions will outpace absorption in specific grades. Market participants should treat these as dynamic variables rather than fixed assumptions, monitoring capacity announcements, specification adoption, and compliance-driven qualification shifts as leading indicators.
Decision-Maker Playbook: Actions for Manufacturers, Investors, and Buyers
For pulp producers and paperboard or tissue manufacturers, the priority is to align grade strategy with end-use demand and compliance readiness. Operators should map their product portfolio against the applications where BCTMP attributes add the most value, ensure specification flexibility where customers are optimizing for bulk, brightness, or drainage, and verify that sourcing and process practices can withstand documentation and traceability requirements. Where feasible, investment in energy recovery, chemical efficiency, and effluent management will strengthen both cost resilience and market access. The practical question is whether current assets and operating practices can shift output toward higher-value grades without sacrificing consistency or compliance credibility.
For investors, the focus should be on structural advantages rather than headline capacity alone. Favorable opportunities are likely to emerge where operators demonstrate integration benefits, grade flexibility across tissue and packaging applications, and credible sustainability positioning that aligns with evolving buyer requirements. Capacity additions are meaningful, but their value depends on absorption quality, specification differentiation, and cost discipline. Monitoring modernization programs, grade launches, and regional supply shifts provides earlier signal than aggregate capacity figures, particularly in a market where competitive advantage is increasingly defined by how fiber is produced and qualified rather than how much is produced.
For procurement and sourcing teams, the actionable move is to treat BCTMP selection as an engineered input decision, not a generic commodity purchase. Buyers should define specification priorities for their end-use formats, qualify suppliers on both performance consistency and traceability or compliance documentation, and assess total delivered cost with energy, logistics, and regulatory exposure in mind. Diversifying across suppliers with complementary grade strengths and regional footprints can reduce exposure to localized tightness while preserving access to the fiber attributes needed for product performance and packaging efficiency. As qualification criteria evolve, early alignment with suppliers that can meet both technical and sustainability expectations will reduce friction in downstream product development and customer-facing claims.
The BCTMP market is expanding, but its value creation is shifting from volume growth toward grade engineering, compliance readiness, and operational integration. That shift rewards participants who can read application-specific demand, adapt specifications, and operate with credible sustainability and cost structures. For decision-makers who need granular segment data, regional nuance, and tailored scenario analysis to translate these themes into concrete investment, sourcing, or production choices, a deeper data set can sharpen the path from insight to execution.
Worldwide Unbleached Wood Pulp Market
For detailed analysis of this topic, please visit the official page: Bleached Chemi-ThermoMechanical Pulp (BCTMP) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com