

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Makeup Brushes Market: 5.4% CAGR and the Natural Bristle Shift Reshaping Growth

The Makeup Brushes Market at an Inflection Point: Strategic Trends and Commercial Opportunities
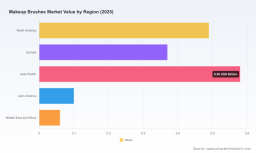
The global makeup brushes market has entered a phase of structural transformation. Valued at approximately 1.6 billion USD in 2025, the market has grown steadily from 1.05 billion USD in 2020, reflecting a compound annual growth rate of 5.4 percent through the forecast horizon extending to 2032. By the close of the projection period, revenue is expected to approach 2.6 billion USD. This trajectory signals more than incremental expansion; it points to a market where consumer expectations, material innovation, regulatory pressure, and supply chain reconfiguration are converging to reshape competitive dynamics. For manufacturers, brand owners, and investors, the question is no longer whether the market will grow, but how value will be allocated across segments, geographies, and business models over the next several years.
Hairbrush Market
Market Snapshot and Structural Context
The makeup brushes market has demonstrated resilient demand across economic cycles, supported by the broader expansion of professional and consumer beauty routines. Growth has been underpinned by higher utilization frequency, a widening palette of application techniques, and the normalization of brush-based makeup application as a standard beyond niche or professional use. The market’s expansion from 2020 to 2025 reflects both post-pandemic recovery in personal care spending and the continued penetration of brush-based application in everyday routines. Looking ahead, the forecast period points to a measured but consistent climb, with acceleration expected as product innovation and channel expansion reinforce one another.
Despite the positive trajectory, the market faces a small number of decisive challenges that will separate scalable operators from those constrained by cost, compliance, or positioning. First, input cost volatility and trade policy friction are reshaping the economics of production and sourcing. Second, material and sustainability expectations are changing procurement criteria, pushing manufacturers to justify brush construction beyond performance alone. Third, differentiation is becoming harder as category familiarity increases, forcing players to compete on craftsmanship, customization, and brand narrative rather than basic functionality. These pressures are not isolated; they interact to influence pricing power, margin structure, and the pace at which new capacity can be commercialized.
Key Drivers Reshaping the Market
Material Innovation and Performance Engineering
Material choice remains one of the most consequential decisions in brush design, influencing application feel, durability, washability, and cost. The market continues to see a balance between natural and synthetic options, with each serving distinct performance profiles and consumer preferences. Natural fibers are still associated with elegance, softness, and blending quality, while synthetic alternatives have broadened their appeal through consistency, 내구성, and evolving feel characteristics. The commercial significance lies in the fact that performance tradeoffs are narrowing. Manufacturers are investing in fiber engineering, filament grading, and ferrule construction to improve snap, shed resistance, and rinse behavior. That matters commercially because it allows product lines to target multiple use cases without compromising on perceived quality. As application techniques become more refined, consumers and professionals alike are evaluating brushes not just by whether they apply product, but by how precisely they control placement, blend, and finish.
Recent product launches illustrate how material and design improvements are becoming a visible competitive lever. In early 2026, Jenny Patinkin introduced a sustainable luxury powder and bronzer brush built entirely from post-consumer recycled materials, including nylon bristles and an aluminum ferrule. This launch signals that premium positioning can coexist with recycled inputs, expanding the commercial vocabulary for sustainability beyond basic compliance. Around the same time, Alpine launched face brushes with matching eye brushes featuring updated handle designs, emphasizing coordinated sets and tactile differentiation. These moves show that innovation is not limited to fiber chemistry; it also extends to set architecture, user experience, and visual identity. For commercial stakeholders, the implication is clear: material and design innovation are increasingly intertwined, and the strongest offerings are those that connect performance claims with recognizable product language.
Regulatory Pressure and Trade Cost Realignment
Trade policy has become a central variable in the makeup brushes market’s cost structure. US tariff dynamics have raised the effective cost of imported brushes and related components, with baseline rates and higher surcharges pushing average rates higher by early 2026. Higher duties on Chinese-origin imports have increased landed costs for many finished brushes and components, altering the economics of offshore production and cross-border distribution. At the same time, the broader beauty sector has faced elevated average tariff rates on imports, with combined rates on certain Chinese goods reaching levels that directly affect cosmetic brush supply chains. In some cases, tariff exposure on packaging and component inputs has reached levels that drive price increases, particularly for smaller brands with limited ability to absorb cost shocks.
This regulatory environment is prompting reactive and strategic responses. Some large players have chosen to reinvest tariff refunds into price reductions on makeup products, including brushes, in order to protect volume and consumer perception after cost increases. That approach highlights a broader strategic tension: whether to pass costs through, compress margins, or offset pressure through operational efficiency and sourcing changes. For the market overall, the consequence is a reconfiguration of cost-sensitive volume flows and a greater premium on supply chain flexibility. Companies that can diversify sourcing, manage duty exposure, and maintain consistent lead times are gaining an advantage in an environment where cost predictability is increasingly scarce.
Demand-Side Shifts in Consumer and Professional Use
Demand is being shaped by two reinforcing dynamics: higher standards for application quality and broader adoption of brush-based routines across consumer segments. Consumers are increasingly attentive to finish quality, hygiene, and tool longevity, while professional users continue to prioritize precision, control, and repeatability. This dual demand structure is expanding the commercial relevance of both premium and value-oriented offerings, but with different winning criteria in each tier. In premium segments, buyers are evaluating craftsmanship, material provenance, and design coherence. In more price-sensitive segments, the battleground is reliability, set composition, and the perceived value of multi-piece kits.
PW Consulting
The market is also benefiting from the continued normalization of at-home application as a routine rather than a specialized activity. Brush use is no longer confined to advanced enthusiasts; it is becoming part of standard grooming and makeup workflows. That broadening user base increases the importance of intuitive design, clear use cases, and accessible product architectures. It also encourages brands to think in terms of system selling, where brushes are positioned alongside application habits, tutorials, and routine-building narratives. The commercial opportunity lies in converting casual users into repeat purchasers by reducing friction in product choice and improving perceived outcomes.
Supply Chain Reconfiguration and Production Geography
Production geography is being reconsidered as companies weigh cost, lead time, duty exposure, and operational resilience. Recent operational updates from factories involved in professional makeup brush production indicate ongoing attention to capacity, process standardization, and geographic diversification. Updates from facilities in Cambodia and other production locations reflect a wider interest in expanding or consolidating manufacturing footprints beyond traditional hubs. This matters because brush manufacturing is labor-intensive in finishing, assembly, and quality inspection, making location decisions sensitive to labor availability, process maturity, and export logistics.
At the same time, supply chain pressure is encouraging a more deliberate approach to supplier relationships and production control. Some manufacturers are deepening OEM and ODM capabilities to serve brand clients with customized specifications, while others are strengthening in-house control over ferrule fitting, fiber insertion, and trimming to protect consistency. The strategic direction is toward more transparent production pathways and more flexible order structures, especially for brands that need to balance speed, customization, and cost. In practice, this means that competitive advantage is increasingly defined by the ability to deliver consistent quality across varying order sizes, maintain compliance with material and labeling expectations, and adapt quickly when sourcing conditions shift.
Competitive Landscape and Leading Strategies
Established Manufacturers and Positioning Logic
The competitive field includes manufacturers with distinct positioning across price tiers, materials, and customer models. Guangzhou Yafei Makeup Brush Co., Ltd. operates as a professional cosmetic brush manufacturer offering a broad range of makeup brushes with custom options, positioning itself around breadth of catalog and flexibility for brand clients. Ningbo Chungfat Brushes Factory, Ltd. extends beyond makeup brushes into related categories such as hair brushes, combs, nail brushes, and bath tools, suggesting a strategy built on cross-category manufacturing scale and export orientation. Fay Cosmetic Brushes Co., Ltd., active since 2010, emphasizes OEM and ODM customization with multiple production facilities, indicating a focus on repeatable custom production and capacity to serve varied brand requirements.
On the premium side, Hakuhodo Co., Ltd. represents a long-standing Japanese manufacturer of handmade premium makeup brushes using fine natural and synthetic materials, with a heritage that supports a craftsmanship-based positioning. Cangzhou Hexin Brush Making Co., Ltd., operating as part of HWASHIN CORPORATION, reflects a larger corporate manufacturing footprint in cosmetic and makeup brushes, where scale, process control, and integrated operations can support consistent output and broader commercial reach. These profiles illustrate a spectrum from customization-focused manufacturers to heritage-led premium makers and scale-oriented producers. The strategic lesson is that different buyers value different combinations of speed, customization, materials, and brand story, and the most resilient manufacturers are those that can clearly own a position rather than compete generically across all attributes.
Strategic Differentiation and Recent Moves
Recent product and operational activity points to several differentiation paths. In material and sustainability terms, recycled-content brushes and updated handle designs indicate that brands are seeking visible points of difference that resonate with conscious consumption and aesthetic preferences. In commercial terms, customization capabilities and multi-facility production are becoming important for serving brand partners who need variations in ferrule design, handle aesthetics, filament blends, and packaging-ready finishes. The direction of travel is toward more modular product architecture, where core construction can be adapted without sacrificing quality or lead time.
There is also a growing distinction between manufacturers that compete primarily on volume and cost and those that compete on perceived quality and brand alignment. The latter group often relies on material narrative, finishing quality, and design consistency to support pricing. The former must lean on process efficiency, sourcing discipline, and order flexibility. Both models can be viable, but they require different operational capabilities and different customer engagement strategies. Market evolution is likely to reward clarity of positioning, because buyers are increasingly able to compare offerings across performance, aesthetics, and procurement criteria.
Market Structure: Consolidation, Fragmentation, and New Entry
The market structure remains relatively fragmented, with a meaningful share concentrated among leading players but ample room for specialized manufacturers and regional suppliers. Concentration levels indicate that the largest companies hold a notable share, yet the market is broad enough to accommodate niche craftsmanship, regional production, and custom-service models. This combination creates opportunities for both consolidation and differentiation. Larger producers may gain from scale in sourcing, standardized quality control, and broader distribution relationships. Smaller or specialized producers may gain from customization, faster iteration, and stronger brand partnerships in premium or boutique segments.
New entry and re-entry are likely in areas where trade cost shifts, material innovation, or regional production incentives alter the economics. factories updating operations in new locations suggest that production geography is still being optimized, and that some brands are looking for alternative sourcing pathways. At the same time, the bar for successful entry is rising because buyers have more access to product information, material claims, and comparative reviews. Entrants will need a clear value proposition, whether that comes from material innovation, design distinctiveness, customization speed, or a compelling brand narrative.
Future Trends and Commercial Implications
Premiumization with Verifiable Material Claims
One of the most visible trends is the continued push toward premiumization, supported by material storytelling and design refinement. The commercial opportunity lies in aligning premium pricing with verifiable attributes such as fiber quality, ferrule durability, wash performance, and sustainable sourcing choices. Buyers are increasingly skeptical of vague claims, so the winning offerings will likely be those that can connect premium feel with traceable construction and repeatable quality. For manufacturers, this means investing in consistent finishing, tested material combinations, and product language that accurately reflects what the brush delivers. For brand owners, it means selecting tools that can be credibly positioned within a broader routine or ritual, rather than relying on aesthetics alone.
Sustainability as Procurement Criteria, Not Peripheral Messaging
Sustainability is increasingly embedded in purchasing decisions rather than treated as add-on messaging. Recycled materials, durable construction, and longer service life are becoming relevant to both consumer perception and brand compliance requirements. The trend suggests that sustainability will matter most when it is linked to product performance and lifecycle value. A brush that is marketed as sustainable but fails on shedding, shape retention, or ease of cleaning will undermine the claim. Conversely, an offering that combines recycled inputs with reliable application and durable construction can support both commercial and reputational goals. The risk is greenwashing fatigue; the opportunity is to make sustainability operational by designing it into materials, processes, and product longevity.
Supply Chain Agility as a Margin Defense
As tariff exposure and sourcing costs remain unpredictable, supply chain agility will likely become a defining competitive capability. Companies that can shift order volumes, qualify alternative production sites, and maintain stable lead times will be better positioned to protect margins without sacrificing service levels. This trend favors organizations that invest in supplier diversity, documentation discipline, and flexible manufacturing arrangements. It also favors brands that can plan assortments with cost variation in mind, balancing higher-duty items with lower-exposure alternatives where feasible. The uncertainty lies in the durability of current trade conditions and the speed with which new sourcing patterns become stable. Until then, flexibility is a strategic asset.
Strategic Actions for Decision Makers
For Manufacturers
Own a clear positioning rather than competing on every attribute. Decide whether the business will win through customization speed, craftsmanship narrative, material performance, or cost-efficient scale, and build processes around that choice. Strengthen consistency in ferrule fitting, filament placement, and finishing because quality variation erodes trust quickly in tool categories. Where possible, expand modular production capabilities so that handle, ferrule, and bristle variations can be managed without sacrificing lead time. Monitor trade and duty exposure continuously, and evaluate whether certain SKUs or component inputs should be sourced differently to reduce volatility.
For Investors
Look for operators with defensible differentiation and resilient commercial models. In this market, durability of advantage often comes from material expertise, customization relationships, and the ability to maintain quality across order sizes. Assess whether a company’s growth depends on transient cost advantages or on genuine product and service differentiation. Pay attention to sustainability positioning only when it is supported by product performance and manufacturing discipline, because the market is increasingly sensitive to the gap between claim and experience. Also consider how exposed a business is to tariff-sensitive sourcing, and whether it has alternatives that can preserve margin under shifting trade conditions.
Cosmetics Brushes Market
For Brand Owners and Procurement Teams
Treat brush selection as a strategic part of product experience rather than a commodity accessory. Prioritize tools that match the intended application method, user skill level, and routine architecture. When sourcing, balance price with consistency, durability, and the ability to customize where it matters most. Build supplier relationships that allow for clear specifications, repeatable quality, and responsiveness when trade or material conditions change. Evaluate sustainability claims against actual construction and lifecycle performance to avoid disconnects between messaging and consumer experience.
Closing Perspective
The makeup brushes market is moving from broad-based growth toward a more competitive environment where execution quality, material credibility, and supply chain flexibility determine outcomes. The combination of steady demand expansion, evolving material expectations, and shifting trade costs creates both opportunity and pressure. Companies that define their positioning clearly, invest in consistent manufacturing quality, and adapt sourcing strategies to a less predictable cost environment are best placed to capture value. For decision makers seeking deeper segmentation, company-level benchmarks, and tailored assessment of sourcing or product strategy, the full PW Consulting market report provides more granular data and structured recommendations to support next-step planning.
For detailed analysis of this topic, please visit the official page: Makeup Brushes Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com