

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Rugged Tablet Market 2026: Beyond the 5.8% CAGR Story—Examining Growth Dynamics

The Rugged Tablet Market: Navigating Volatility, AI Integration, and Supply Chain Shifts
The rugged tablet sector stands at a strategic inflection point. What was once a niche hardware category defined primarily by durability and compliance certifications has transformed into a technology platform where artificial intelligence, edge computing, and supply chain resilience converge. With the market closing 2025 at approximately 972 million USD and projected to reach over 1.4 billion USD by 2032, the sector is expanding at a steady compound annual growth rate of 5.8 percent. This trajectory is neither explosive nor stagnant; it is the hallmark of a mature market undergoing structural re-invention rather than cyclical expansion. For executives and investors, the question is no longer whether rugged tablets will grow, but where value will concentrate as hardware differentiation shifts toward software integration, semiconductor access, and regulatory positioning.
PW Consulting
The market expansion from roughly 748 million USD in 2020 to the current baseline reflects a compounding alignment of defense modernization, industrial digitization, and field-service transformation. Growth has not been linear. Post-pandemic procurement cycles, semiconductor availability constraints, and shifting public-sector budgets introduced volatility that rewarded companies with flexible supply chains and diversified end-market exposure. Looking ahead, the forecast period through 2032 suggests that revenue gains will increasingly depend on higher-margin configurations, AI-enabled form factors, and regional supply chain restructuring rather than volume-driven commoditization. The market's trajectory is clear, but the competitive map beneath that trajectory is being redrawn.
Market Landscape and Core Tensions
The sector's fundamental dynamic is a tension between performance ambition and supply chain reality. Rugged tablets are engineered to function in extremes: temperature swings, dust immersion, impact shock, and electromagnetic interference. Historically, meeting those requirements meant premium pricing, slower innovation cycles, and dependence on specialized component suppliers. Today, the same durability thresholds are being paired with compute architectures that demand higher power delivery, advanced thermal management, and memory bandwidth. That pairing is exposing manufacturers to a new layer of complexity: ruggedness is no longer the hardest engineering problem, but it remains the most expensive one to maintain while integrating AI workloads and next-generation connectivity.
The first core challenge is the shifting hierarchy of what buyers value. In many deployments, ruggedness has become a baseline expectation rather than a differentiating advantage. Procurement teams in aerospace, defense, manufacturing, and field operations now evaluate devices through the lens of software ecosystem compatibility, device management scalability, and total cost of ownership across refresh cycles. Hardware that survives a six-foot drop is table stakes; hardware that integrates cleanly into AI-assisted workflows and field data architectures is where procurement attention concentrates. This shift is forcing manufacturers to decide whether they compete as device builders or as operational technology platforms.
A second challenge is the uneven cadence between product innovation and component availability. The industry has entered a phase in which long-horizon semiconductor lead times interact with short-cycle product roadmaps. When memory and microcontroller lead times extend beyond typical procurement windows, production schedules, configuration options, and launch timing all become harder to synchronize. This does not stop demand, but it reshapes fulfillment patterns, inventory strategies, and margin predictability. Manufacturers with diversified component sourcing and flexible bill-of-materials engineering are better positioned to absorb disruptions, while those dependent on concentrated semiconductor nodes face more volatile planning horizons.
A third challenge is regulatory and geopolitical pressure on the underlying materials and components that make rugged devices possible. The sector relies on displays, batteries, memory, and specialized substrates that are tied to critical mineral supply chains and electronics manufacturing geographies. Trade investigations, tariff frameworks, and export-control dynamics introduce uncertainty not only for cost but also for product compliance and sourcing continuity. This environment favors organizations that treat supply chain resilience as a strategic capability rather than a procurement function.
Key Drivers Shaping the Market
The market's direction is being shaped by a combination of technological, regulatory, demand-side, and supply-side forces. The most consequential of these are not operating in isolation; they are reinforcing one another and reshaping where competitive advantage can be built.
Technology Innovation and AI Migration to the Edge
One of the most significant shifts is the migration of AI capabilities from backend systems to field-deployed hardware. Rugged tablets are increasingly positioned as edge nodes rather than passive terminals. Recent product announcements show vendors building devices around processors designed for AI inference, extending battery architectures to support higher-performance compute, and layering MIL-STD and ingress protection certifications onto AI-capable platforms. This trend matters because it changes the purchase logic. A rugged tablet with local AI processing can support offline workflow assistance, image-based inspection, speech-to-text field documentation, and rapid device-side decision support. Those capabilities reduce dependency on uninterrupted connectivity and enable more autonomous field operations.
The technology trajectory is also visible in the broader computing architecture transition. Devices are being designed around processors that emphasize efficiency and integrated acceleration for AI tasks, which matters in environments where thermal envelopes and battery capacity are constrained. The result is a new product tier in which ruggedness and on-device intelligence are being offered as a combined value proposition rather than separate features. This creates an opening for manufacturers that can deliver robust hardware without sacrificing computational relevance, but it also raises the engineering bar for thermal design, power management, and software optimization.
Policy, Regulation, and Compliance as Market Architecture
Policy dynamics are increasingly shaping product roadmaps and sourcing strategies. Rugged tablets are heavily represented in defense, public safety, aerospace, and regulated industrial environments, where certification requirements act as both a barrier to entry and a competitive anchor. Military-grade standards, ingress protection ratings, and sector-specific compliance frameworks remain central to purchase decisions, especially in government and critical infrastructure procurement. At the same time, supply-side regulation around critical minerals and processed components is becoming more consequential. Investigations into processed critical minerals, broader ministerial frameworks for securing non-domestic supply, and periodic export-control suspensions all influence which component pathways are viable and at what cost.
For the rugged tablet market, this means regulation is not only a compliance burden; it is a structural force in supply chain design. Vendors that can demonstrate certification credibility while maintaining transparent sourcing and alternative component pathways are gaining an advantage in procurement conversations where risk tolerance is falling. The policy environment also rewards modularity and configuration flexibility, since regulatory shifts can alter which components are accessible, affordable, or compliant in specific regions.
Demand-Side Transformation in Field Operations
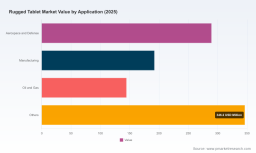
End-user demand is changing in ways that extend beyond sector-level growth. In manufacturing and heavy industry, the push toward predictive maintenance, digital work instructions, and real-time equipment data has increased the need for devices that can operate in harsh conditions while integrating with enterprise systems. In oil and gas and similar environments, the operational imperative is to reduce downtime and improve remote inspection workflows, which favors durable, connected devices with strong battery endurance. In aerospace and defense, the trend is toward devices that can support secure field workflows, rugged mobility, and integration with broader digital infrastructure.
Fully Rugged Tablets Market
A notable demand-side shift is the blending of commercial and operational requirements. Field personnel now expect interfaces and software experiences that resemble consumer-grade usability, while operations leaders still demand durability and manageability. That tension has accelerated the appeal of semi-rugged and fully rugged form factors that offer balanced trade-offs between protection, weight, and user experience. It also encourages device makers to invest in software ecosystems, enterprise integration, and device management tooling, because a rugged tablet that is difficult to deploy at scale loses real-world value regardless of its hardware specifications.
Supply Chain and Cost Structure Pressures
Cost structure dynamics are being reshaped by demand for advanced components and concentration risk in critical inputs. Rising prices and extended lead times for materials used in battery housings, displays, and conductive components have introduced upward pressure on bill-of-materials costs. These pressures are not uniform across all configurations, but they are especially visible in higher-specification devices where materials intensity and performance requirements intersect. At the same time, semiconductor prioritization patterns have made it more difficult to guarantee component access on predictable timelines, which affects production planning and inventory strategy.
Rugged Notebooks Market
This environment is pushing manufacturers toward several strategic responses. Some are designing for component substitution and broader supplier qualification. Others are shifting toward platform strategies that allow families of devices to share core components while varying levels of ruggedization, display quality, or compute capability. The most effective approaches combine engineering flexibility with procurement discipline, allowing companies to preserve margins while maintaining delivery reliability. In a market where durability remains non-negotiable, the ability to manage input volatility without compromising product integrity is becoming a differentiating capability.
Competitive Landscape and Leading Strategies
The competitive field includes established rugged-device specialists, diversified enterprise hardware players, and regional manufacturers with strong presence in defense and industrial channels. The market is moderately concentrated at the top, with a significant share held by a small group of leaders, but the broader roster remains diverse. That combination matters because the category spans multiple form factors, certification requirements, and vertical applications, making it difficult for any single product architecture to dominate across all use cases.
Zebra Technologies has built its position around rugged mobile computing with a strong orientation toward logistics, warehousing, and industrial workflow integration. Its strategy emphasizes scanning, enterprise connectivity, and deployment scalability rather than ruggedness alone. That positioning reflects a broader truth in the category: for many commercial users, value lies in how well a device fits into operational workflows and data systems, not just in its ability to withstand harsh conditions.
Getac and Panasonic Toughbook continue to serve as anchors in fully rugged and defense-facing segments. Getac's emphasis on fully rugged industrial tablets, customization, and MIL-STD compliance suits environments where device failure carries high operational risk. Panasonic's reputation for durable devices certified to military standards supports its strong presence in public safety, defense, and industrial deployments. Both companies benefit from long-standing credibility in high-stakes sectors, which helps in procurement cycles where trust, certification history, and service support weigh heavily.
Winmate, RuggON, and Durabook illustrate how manufacturers are evolving product portfolios to combine ruggedness with newer compute and AI capabilities. Durabook's recent Copilot+ PC tablet launch, with Intel Core Ultra processors and strong protection ratings, exemplifies the movement toward higher-performance rugged computing. RuggON's AI-driven tablet with MIL-STD-810H and IP65 certification shows similar intent, targeting construction, defense, and IoT-oriented deployments. These moves suggest that a growing segment of the market is being shaped by devices that aim to bridge field durability with modern AI-ready architectures.
Dell Rugged and Samsung Electronics bring the advantage of large enterprise ecosystems and broad brand familiarity. Dell's rugged Latitude devices and Samsung's Galaxy Tab Active Pro line both fit into larger mobility strategies for organizations that want rugged capability without decoupling from mainstream device management, procurement, or support relationships. Their presence adds competitive pressure on specialists to demonstrate not just durability but also integration simplicity and total cost of ownership.
Honeywell, DT Research, MobileDemand, and Emdoor Information round out a competitive map that remains segmented by vertical strength. Honeywell's rugged computing portfolio aligns with industrial, transportation, and public safety use cases. DT Research emphasizes healthcare, military, and logistics applications with specialized certifications. MobileDemand focuses on industrial tablets and mobile POS contexts, particularly in construction and warehouse settings. Emdoor Information has been active in presenting high-performance rugged tablets and AI laptops at major trade events, indicating a strategy oriented toward enterprise and industrial visibility and performance positioning.
Strategic Positioning and Differentiation
The clearest differentiation strategy in the current market is the combination of durability with AI-readiness and enterprise integration. Companies that can offer MIL-STD and ingress protection certifications alongside modern processor architectures, AI software partnerships, and manageable device fleets are building the strongest value narratives. Another differentiating axis is vertical specialization. Vendors that understand the procurement language, certification priorities, and workflow requirements of a particular sector are often able to command stronger positioning than generalists, especially in defense, public safety, and regulated industrial environments.
Partnerships are also becoming a strategic lever rather than a supporting tactic. Recent collaboration activity shows manufacturers linking hardware with software providers and platform ecosystems to accelerate AI capability integration and field-service functionality. This matters because rugged hardware alone is increasingly insufficient as a final value proposition; the ability to pair durable devices with intelligent software workflows is becoming a decisive factor in competitive evaluations.
Market Evolution and Structural Shifts
The competitive landscape is evolving along several directions at once. One is consolidation pressure at the high end, where established players with strong certification records, service networks, and vertical relationships are well positioned to defend share. Another is differentiation at the platform level, where new product cycles are creating opportunities for entrants or expanding players that can combine ruggedness with newer compute architectures and AI capabilities. A third is regional and supply-chain repositioning, as companies adjust sourcing and manufacturing pathways in response to minerals-related policy and component availability dynamics.
The net effect is a market that is not heading toward a single dominant architecture, but toward a layered competitive structure. Fully rugged devices will remain essential in the most demanding deployments. Semi-rugged devices will continue to capture users who need a balance of protection and usability. AI-capable rugged tablets will likely gain share as field operations increasingly depend on local intelligence, offline support, and tighter integration with enterprise data systems. The winners will be those who align product design, sourcing, and vertical go-to-market strategy with the specific risk and workflow profile of their target customers.
Future Outlook: Three Trends for the Next Three to Five Years
The next several years are likely to be defined by three interrelated trends. The first is the normalization of AI-enabled rugged devices as a distinct product tier. As more devices incorporate processors and software stacks designed for on-device intelligence, the category will increasingly be evaluated not only by survivability but by operational augmentation. This shift creates opportunities for vendors that can package rugged hardware with practical AI use cases, such as field inspection support, voice-assisted documentation, and offline workflow assistance. The opportunity is not simply to add a processor; it is to make AI usable in environments where connectivity, power, and environmental stress are all constraints.
The second trend is supply chain re-architecture. Critical mineral investigations, minerals ministerial frameworks, and periodic export-control dynamics are likely to keep sourcing strategy in sharp focus. Over the next few years, more manufacturers are expected to qualify alternative component pathways, regionalize certain supply relationships, and design for substitution flexibility. This trend favors organizations that invest early in supply resilience and transparent sourcing narratives, particularly in government and defense procurement where continuity risk is scrutinized closely.
The third trend is vertical specialization becoming more explicit in product strategy. Rather than positioning rugged tablets as generic durable devices, vendors are increasingly aligning form factors, certification sets, and software partnerships with the requirements of aerospace and defense, manufacturing, oil and gas, healthcare logistics, and field service. This trend creates stronger competitive moats in sectors where procurement processes are relationship-heavy and certification-driven, but it also requires deeper domain expertise and more tailored service models.
These trends carry both opportunity and uncertainty. AI integration can unlock higher-value deployments, but only if software, device management, and user training are treated as part of the product. Supply chain diversification can reduce risk, but it can also raise short-term costs and complicate engineering coordination. Vertical specialization can deepen customer relationships, but it can limit scale advantages if pursued too narrowly. Executives should therefore treat these trends as a portfolio of choices rather than a single direction.
Strategic Implications for Decision-Makers
Manufacturers should decide early whether the strategic goal is category breadth or vertical depth. A breadth strategy depends on modular platforms, broad certification coverage, and flexible sourcing to serve multiple sectors. A depth strategy depends on concentrated domain expertise, tailored software partnerships, and strong procurement relationships in selected verticals. Both can work, but they require different engineering, sales, and supply chain investments. In the current environment, AI-readiness and component resilience should be treated as enabling capabilities for whichever strategy is chosen, not as optional upgrades.
Investors should evaluate the market with attention to platform transitions and sourcing exposure rather than headline growth alone. Revenue expansion is expected, but margin quality will increasingly depend on device mix, software-enabled value, and the ability to manage component and materials volatility. Companies that are building AI-capable rugged platforms, securing supply pathways for critical inputs, and aligning with high-trust verticals are better positioned for durable advantage than those competing primarily on ruggedness as a standalone attribute.
Procurement leaders and operational technology decision-makers should approach rugged tablet selection as a platform decision with downstream implications for workflow, manageability, and supply continuity. Device evaluation should extend beyond drop ratings and ingress protection to include AI compatibility, enterprise integration, support models, and component sourcing resilience where applicable. In sectors sensitive to regulatory and supply-chain uncertainty, procurement teams may benefit from understanding not only which device is selected, but how the vendor manages certification continuity and component substitution risk over the asset life cycle.
For stakeholders seeking deeper segmentation, configuration-level demand patterns, regional procurement dynamics, and company-specific benchmarking, a more detailed research package can provide the granularity needed to turn these strategic themes into operational decisions. The full report expands on the segmentation structure, heat points in supply chain exposure, competitive positioning across major manufacturers, and scenario-based outlooks that support planning under variable regulatory and component-availability conditions.
For detailed analysis of this topic, please visit the official page: Rugged Tablet Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com