

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Mammography X-ray Unit Market: Why 8.75% CAGR & Shifting Digital Demand Redefine Growth

Strategic Trends and Commercial Opportunities in the Mammography X-ray Unit Market
The global mammography equipment sector has entered a decisive phase of structural expansion. Valued at approximately $1.15 billion in 2020, the market has grown steadily through 2025, crossing the $1.65 billion threshold. Over the coming years, the trajectory projects sustained momentum, with revenue expected to approach the $3 billion mark by 2032, translating to a compound annual growth rate of 8.75 percent. This growth is not merely a function of broader healthcare spending; it reflects a fundamental shift in how imaging systems are engineered, deployed, and reimbursed. For manufacturers, investors, and healthcare procurement teams, the market is evolving from a volume-driven replacement cycle into a technology-and-outcomes-led upgrade environment.
The macro picture, however, masks underlying asymmetries. Regional deployment patterns, modality preferences, and clinical use cases are converging around digital capabilities and screening-first workflows. At the same time, the market remains highly concentrated, with a small group of players accounting for the majority of share. That concentration creates both resilience and friction: established incumbents benefit from installed-base loyalty and service ecosystems, while emerging entrants test the boundaries of clinical differentiation and capital efficiency. Understanding where value is being created—and where it is being eroded—requires looking beyond top-line numbers to the operational and regulatory forces reshaping purchasing decisions.
Market Snapshot and Core Challenges
The overall market size reflects a steady climb from 2020 through 2025, with a pronounced acceleration expected over the forecast horizon. This cadence aligns with capital equipment replacement cycles, expanded screening participation in mature markets, and the gradual modernization of imaging fleets in emerging regions. The growth rate is supported by a mix of fresh unit sales and the recurring economics tied to system upkeep, calibration, and software-enabled upgrades. Yet the headline figures do not tell the full story. Three structural challenges are reshaping how the market behaves and where commercial opportunities are forming.
Challenge 1: Concentrated Supply and the Cost of Differentiation
With a small number of companies commanding the majority of market share, competition has shifted from pure hardware parity to integrated clinical value. Leading vendors compete on workflow integration, dose management, image quality reproducibility, and service reliability. For newer or smaller players, this environment raises the bar for entry: differentiation must be clinically credible and economically defensible, not just technically novel. The challenge is not simply to launch a system, but to demonstrate that a new configuration can reduce total cost of ownership, improve throughput, or enhance diagnostic confidence in ways that matter to facilities and payers.
PW Consulting
Challenge 2: Regulatory Rigor and the Burden of Compliance
Mammography is one of the most tightly regulated imaging modalities. Equipment must meet specific performance and dose standards, and operating sites are expected to maintain rigorous quality control routines. Compliance is not a one-time approval event; it is a continuous operational commitment. Facilities must conduct regular testing, address deviations promptly, and document corrective actions. For manufacturers, this means that product design, training, documentation, and service support must be engineered for sustained compliance—not just initial installation. For buyers, the regulatory layer influences procurement choices, as the cost of non-compliance and downtime can outweigh the upfront price difference between systems.
Challenge 3: Capital Sensitivity Amid Evolving Reimbursement Dynamics
Mammography systems represent significant capital investments, with pricing spread across entry-level, intermediate, and premium configurations depending on features such as three-dimensional imaging capability. At the same time, service contracts add a recurring cost dimension that facilities must plan for over the life of the equipment. On the revenue side, imaging services are tied to specific coding frameworks, and reimbursement outcomes depend on Medicare and private payer policies. This combination creates a tension familiar to capital equipment markets: clinical ambition must be reconciled with budget realism. Buyers increasingly weigh not only acquisition cost, but also the likelihood of sustained reimbursement coverage, utilization patterns, and the operational efficiency gains that can justify premium configurations.
Key Drivers Shaping the Market
The growth trajectory is underpinned by forces that extend beyond simple demand expansion. These drivers interact with one another, creating a market in which technology, regulation, and purchasing behavior reinforce new standards of care.
Technological Innovation and Clinical Value Creation
Digital mammography has become the dominant modality, with digital systems representing the majority of revenue and analog systems playing a diminishing role. The shift reflects more than legacy replacement; it reflects the operational and diagnostic advantages of digital workflows, including improved image handling, integration with downstream reporting, and the ability to support advanced acquisition modes. Three-dimensional capabilities and newer imaging architectures have further raised expectations around lesion visibility, dose optimization, and reading efficiency. These innovations are not merely feature upgrades; they change the economics of screening and diagnostic workflows by influencing recall rates, throughput, and radiologist confidence.
Recent milestones illustrate the pace of clinical exploration in this space. In early 2026, a first-in-human clinical study of a 4D mammography system reached enrollment completion at a regional health facility, signaling continued interest in higher-dimensional acquisition approaches and their potential to improve lesion characterization or workflow efficiency. Whether such approaches ultimately scale depends on clinical evidence, reproducibility, and the ability to integrate into routine practice without disrupting throughput. What is clear is that the market is actively testing the boundaries of acquisition geometry, image reconstruction, and workflow design.
Medical X-Ray Generator Market
Policy and Regulatory Environment as a Market Architect
Regulatory frameworks do more than set minimum standards; they shape procurement behavior, service expectations, and product roadmaps. In the United States, mammography systems are subject to equipment standards that include average glandular dose limits under federal rulemaking, and facilities must maintain quarterly quality control testing per manufacturer specifications, with corrective actions required if tests fail. This regulatory environment elevates the importance of reliable hardware design, consistent calibration, and responsive service infrastructure.
Regulatory guidance also evolves in ways that affect testing practices and equipment validation. Recent updates have revised phantom testing references, aligning quality assurance practices with current standards and commercial phantom solutions. While such changes may appear procedural, they matter commercially because they influence validation protocols, service training, and the documentation that facilities rely on to maintain compliance. For manufacturers, the operational implication is clear: regulatory alignment must be embedded into product lifecycle management, not treated as a separate compliance exercise.
Demand-Side Shifts in Screening and Diagnostic Workflows
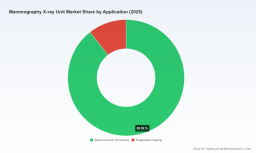
Clinical demand is increasingly organized around screening as the dominant application, with diagnostic imaging representing a smaller share of usage. This pattern reflects both public health priorities and the operational logic of early detection programs. Screening-driven demand tends to favor systems that can handle higher volumes, maintain consistent image quality across broad patient populations, and support efficient reading workflows. At the same time, diagnostic demand remains important for problem-solving, recall evaluation, and symptomatic assessment, which keeps advanced imaging capabilities relevant across the product spectrum.
Behaviorally, healthcare organizations are paying closer attention to total cost of ownership and clinical outcomes, not just unit price. The decision to adopt premium configurations is increasingly tied to expected improvements in workflow efficiency, dose management, and diagnostic confidence, balanced against reimbursement realities. This demand-side evolution is pushing vendors to present not just equipment, but integrated solutions that bundle acquisition, training, service, and workflow optimization.
Supply-Side and Cost Structure Dynamics
The market’s cost structure is defined by a wide price spectrum across system tiers, with premium configurations commanding materially higher investment. This gradient creates an environment in which service contracts, parts availability, and upgrade paths have outsized importance. Annual service agreements typically vary with system age and feature set, making lifecycle cost a central element of procurement planning. In addition, the concentration of market share among leading vendors reinforces the importance of service networks and installed-base support, since many facilities prioritize reliability and long-term support over speculative new entrants.
For manufacturers, supply-side strategy increasingly involves balancing premium innovation with accessible configurations that meet the needs of smaller facilities or cost-sensitive markets. For buyers, the key question is how to select systems that fit clinical requirements without creating avoidable operational or financial strain over the equipment’s life. The result is a market where commercial success depends as much on service economics and compliance readiness as on hardware specifications.
Competitive Landscape and Leading Strategies
The competitive field is broad, spanning established global medtech and imaging companies as well as regional manufacturers and specialized innovators. This mix creates a layered competitive environment in which incumbents compete on ecosystem depth, while challengers attempt to carve out niches through clinical novelty, cost efficiency, or regional focus.
Strategic Positioning of Core Players
Hologic, GE HealthCare, and Siemens Healthineers represent the scale end of the market, where breadth of portfolio, installed-base leverage, and service infrastructure matter. These companies typically compete by integrating mammography into wider imaging and women’s health ecosystems, emphasizing workflow connectivity, dose management, and reproducibility across sites. Their strategic advantage lies in the ability to support large deployments, offer consistent service coverage, and align equipment with broader enterprise imaging and IT strategies.
FUJIFILM, Philips, and Canon Medical Systems bring strong imaging heritage and differentiated technology narratives. Their positioning often emphasizes image quality, system design, and workflow integration, with an eye toward supporting both screening throughput and diagnostic precision. Meanwhile, companies such as Konica Minolta, Carestream Health, Planmed, and IMS Giotto illustrate the value of specialized positioning. These players often target specific clinical use cases, regional markets, or configuration preferences, using focused product strategies to compete against broader portfolios.
On the emerging and regional side, companies such as Metaltronica, Beijing Wandong Medical Technology, Perlong Medical Equipment, and Shenzhen Angell Technology reflect the continued presence of cost-conscious manufacturing ecosystems and regional demand. Their commercial challenge is to demonstrate reliability, regulatory alignment, and service viability in markets where procurement decisions are highly sensitive to upfront price and local support.
Newer entrants such as Calidar highlight a different strategic pathway: clinical differentiation through novel acquisition concepts. In this case, early clinical study activity points to an innovation-focused approach that seeks to establish a distinct value proposition. Whether such a strategy scales will depend on the strength of clinical evidence, regulatory navigation, and the ability to position the system within existing workflows without imposing excessive operational complexity.
Market Evolution: Consolidation, Differentiation, and New Entry
The market is unlikely to become uniformly fragmented. Concentration in the upper tier is supported by the economics of service, compliance, and enterprise integration, which favor companies with broad reach and mature support structures. At the same time, differentiation remains possible through technology advances, workflow innovation, and regional specialization. New entrants are most likely to succeed when they can demonstrate a credible clinical benefit, fit into existing compliance and service expectations, and offer a clear economic rationale for switching or augmenting existing fleets.
For incumbents, the strategic imperative is to protect installed-base value while continuing to upgrade systems and service offerings in ways that align with regulatory expectations and clinical demand. For challengers, the opportunity lies in identifying segments where premium incumbents may be over-indexed on capability, or where regional demand is better served by focused product and support models. The broader trend is not a single winner-takes-all dynamic, but a layered market in which different players compete on different axes of value.
Future Trends and Commercial Opportunities
Looking ahead over the next three to five years, several trends are likely to define where growth and margin potential concentrate.
Trend 1: Digital-First Deployment and Advanced Acquisition Maturity
Digital systems will continue to dominate new deployments, while analog installations decline further as replacement cycles and modernization programs progress. Beyond the broad digital shift, more advanced acquisition approaches will mature from early research and limited adoption toward more mainstream consideration, particularly where evidence supports workflow or diagnostic gains. Commercial opportunity lies not only in selling higher-end systems, but in designing upgrade paths, software enhancements, and service models that allow facilities to move along the capability curve without full fleet replacement.
Medical X-Ray Tube Market
Trend 2: Compliance and Quality Assurance as Commercial Leverage
Regulatory expectations and quality control requirements will remain central to purchasing behavior. Facilities will increasingly favor vendors that make compliance easier to maintain through intuitive testing workflows, clear documentation, and responsive service. Manufacturers that embed compliance support into the product experience—rather than treating it as a separate service line—can turn a regulatory burden into a competitive advantage. This creates opportunities for service contracts, training programs, and digital quality management tools that reduce administrative friction for sites.
Trend 3: Total Cost of Ownership and Outcome-Linked Procurement
Buyers will continue to weigh acquisition price against lifecycle cost, reimbursement risk, and operational outcomes. As a result, vendors that can articulate how a system affects throughput, recall dynamics, dose management, and service reliability will have an advantage in competitive evaluations. The commercial opportunity here is to shift conversations from unit price to value over time, including service predictability, consumables efficiency, and integration with existing imaging IT and reporting workflows.
Risks and Uncertainties
These trends are not without risk. Reimbursement changes can alter the economic logic of premium configurations, especially if coding or payer policies shift in ways that affect facility revenue. Regulatory updates can increase testing and documentation burdens or change validation requirements, influencing procurement timing and service expectations. In addition, clinical novelty does not automatically translate into adoption; new acquisition modes must prove themselves in routine practice, with acceptable workflow impact and reproducible results. Finally, competitive intensity may compress margins in certain segments, particularly where regional manufacturers compete aggressively on price or where incumbents face pressure to modernize fleets without triggering full replacement cycles.
Actionable Guidance for Decision Makers
Different stakeholders face different strategic questions, but all benefit from a clear view of where value is forming and how the market is likely to evolve.
For Manufacturers and Technology Providers
- Design for lifecycle value, not just launch features. Emphasize serviceability, compliance support, and upgrade pathways that extend relevance across multiple procurement cycles.
- Align product narratives with operational outcomes. Frame capabilities in terms of throughput, dose management, reading efficiency, and quality assurance, not only image quality claims.
- Prepare for layered competition. Defend installed-base value while identifying segments where a focused configuration, regional support model, or clinical innovation can open new opportunities.
For Investors
- Focus on ecosystems, not only units. Recurring service economics, installed-base durability, and regulatory alignment often matter as much as new hardware sales.
- Watch for differentiation that is clinically and economically credible. Novel acquisition concepts or software-enabled workflows should be evaluated against adoption friction, evidence trajectory, and integration demands.
- Monitor concentration dynamics and regional expansion. High share among leading players creates stability, but also raises the importance of service reach, local support, and the ability to participate in modernization cycles across diverse markets.
For Healthcare Procurement and Facility Leaders
- Evaluate total cost of ownership with service and compliance in mind. Acquisition price is only one part of the equation; service contracts, downtime risk, and quality control support can shape financial outcomes over the life of the system.
- Match configuration to clinical mission and utilization patterns. Premium capabilities may be justified in high-volume or complex diagnostic environments, while simpler configurations may better serve sites with narrower use cases and tighter capital constraints.
- Request evidence of workflow integration and support reliability. Confirm that vendors can demonstrate not only system performance, but also the operational support needed to maintain compliance and minimize disruption.
For decision makers navigating this market, the most valuable intelligence is granular and current: segmentation details, regional deployment patterns, pricing and service economics, regulatory timelines, and competitive moves that affect procurement timing. Access to a complete research report can provide the depth needed to translate these dynamics into procurement strategy, investment thesis, or commercial planning. The broader market trajectory points to continued growth, but the distribution of value will depend on how well organizations align product strategy, compliance readiness, and service economics with evolving clinical demand.
For detailed analysis of this topic, please visit the official page: Mammography X-ray Unit Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com