

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
PW Consulting: Twist Dispensing Closure Market Hits $480.5M in 2025, Projected to Hit $678.83M by 2032
By pmarketresearch, 2026-09-16
Global Twist Dispensing Closure Market: Strategic Intelligence for 2026 Decision-Making
The global twist dispensing closure market stands at a critical inflection point in 2026. As packaging engineers, procurement leaders, and sustainability officers navigate shifting regulatory mandates, raw material volatility, and evolving consumer expectations, access to rigorous, forward-looking market intelligence has become a non-negotiable component of strategic planning. This analysis introduces our latest comprehensive market research on the Worldwide Twist Dispensing Closure Market, designed to equip executive teams with the structural clarity needed to allocate capital, shape product roadmaps, and position supply chains for the forecast period extending through 2032.
The market has demonstrated consistent expansion over the past half-decade, with total revenue growing from approximately 375.2 million USD in 2020 to an estimated 480.5 million USD in 2025. Looking ahead, the trajectory remains constructive, projected to reach 509.17 million USD in 2026 and climb to 678.83 million USD by 2032. This growth profile reflects a compound annual growth rate of 5.06 percent across the forecast horizon, underpinned by steady demand across food and beverage, personal care, household and industrial, and pharmaceutical applications. The expansion is neither accidental nor superficial; it is being engineered by regulatory pressure, material science advancements, and a competitive landscape that rewards speed-to-market and sustainability integration.
Why 2026 Represents a Decisive Strategic Window
For organizations operating in or adjacent to the closure ecosystem, 2026 is not merely another planning cycle. It is the year when several structural forces converge. Extended Producer Responsibility frameworks in the European Union have matured, and parallel regulatory momentum in North America is accelerating the adoption of mono-material and fully recyclable closure architectures. Simultaneously, the EU Single-Use Plastics Directive has already mandated tethered closures on beverage containers below three liters since July 2024, creating a ripple effect that is reshaping engineering priorities across dispensing and twist closure formats. These mandates are no longer theoretical compliance checkboxes; they are active drivers of design, tooling, and supply chain reconfiguration.
At the same time, raw material economics are injecting both risk and opportunity into procurement strategies. The dominant production inputs for twist dispensing closures remain polypropylene and high-density polyethylene resins, but regional price dispersion is pronounced. As of April 2026, polypropylene pricing has been observed at approximately 1.43 USD per kilogram in North America, 2.1 USD per kilogram in Europe, and 1.26 USD per kilogram in Northeast Asia. This geographic spread creates competitive asymmetry: manufacturers with localized sourcing footprints or flexible procurement architectures can protect margins more effectively, while others face pressure to pass costs downstream or absorb them through design optimization. Understanding how these material dynamics interact with regional demand intensity and regulatory timelines is precisely where strategic planning must be grounded in data, not intuition.
The competitive intensity of the market further underscores the urgency of informed decision-making. The sector exhibits a moderately concentrated structure, with the top three participants capturing roughly 32.4 percent of collective revenue and the top five accounting for approximately 45.8 percent. This concentration profile suggests that while scale players exert meaningful influence over pricing norms and standard-setting, there remains substantial room for differentiated innovation, niche application specialization, and regional leverage. Companies that can align product architecture with sustainability mandates, consumer convenience expectations, and regional material cost realities will be best positioned to capture disproportionate value as the market expands toward its 2032 endpoint.
What This Market Research Delivers: Practical Intelligence for Execution
This research report is engineered to move beyond high-level commentary and deliver actionable architecture for strategic planning. It provides a granular mapping of market size and growth trajectories across the historical window of 2020 through 2025, then extends into a disciplined forecast framework covering 2026 through 2032. The analysis decomposes the market along multiple operational dimensions, enabling teams to understand where demand is accumulating, which material choices are gaining traction, and how end-use applications are reshaping closure specifications.
Key structural components of the report include:
- A comprehensive historical and forecast revenue model that tracks overall market progression and isolates growth drivers across the forecast period, giving leadership teams a reliable baseline for capacity planning and investment timing.
- A segment-level decomposition that examines how material preferences, end-use application demand, and regional market dynamics interact, enabling more precise product positioning and go-to-market sequencing.
- A competitive landscape assessment that profiles leading participants, evaluates their strategic positioning, and maps recent product launches and innovation signals to broader market trends.
- An industry context analysis that integrates raw material pricing behavior, regulatory developments, and sustainability-driven design shifts into a unified view of market dynamics, helping teams anticipate constraints and opportunities before they materialize in the P&L.
The report is intentionally structured to support cross-functional use. Procurement teams can leverage the material and regional context to refine sourcing strategies and negotiate with a clearer understanding of cost dispersion. Product development groups can align closure architecture decisions with regulatory trajectories and end-use requirements. Commercial leaders can use the competitive profiling and market size progression to prioritize territories, applications, and partnership opportunities. By consolidating these perspectives into a single, coherent framework, the research reduces the friction between strategic intent and operational execution.
Worldwide Twist Dispensing Closure Market
Competitive Landscape: Who Is Shaping the Market and How
The twist dispensing closure market is defined by a diverse set of participants whose strategies span scale manufacturing, specialized dispensing innovation, sustainability-led redesign, and regional footprint optimization. Understanding these players is essential for benchmarking, partnership evaluation, and competitive positioning.
Silgan Holdings Inc., headquartered in Stamford, Connecticut, maintains a strong presence through its Twist-Off and PT closure offerings, including Plasti-Twist mono-material variants with liners and induction heat seals. These solutions are engineered for liquid foods, non-carbonated beverages, and dispensing applications, reflecting a focused approach to food and beverage packaging where seal integrity and material efficiency matter.
AptarGroup Inc., based in Crystal Lake, Illinois, provides a broad portfolio of dispensing closures across food, beverage, personal care, and pharmaceutical markets. Its emphasis on innovative and sustainable twist and flip-top dispensing solutions highlights a strategic alignment with consumer convenience and environmental goals, an orientation that has become increasingly central as regulators and end-users converge on recyclability and ease of use.
Berry Global Group, Inc., operating from Evansville, Indiana, manufactures dispensing closures alongside pump and valve systems, including twist dispensing options for personal care, household chemicals, pharmaceutical, and consumer goods packaging. Its multi-category footprint enables integrated packaging solutions that can reduce assembly complexity and streamline supplier relationships for downstream customers.
Closure Systems International Inc. (CSI), headquartered in Indianapolis, Indiana, is a global producer of sustainable closure solutions, including Twist and Flip tethered designs for beverage, food, dairy, and industrial fluid applications. Its focus on high-speed application systems underscores the operational importance of line efficiency and throughput in competitive manufacturing environments.
O.Berk Company LLC, based in Hackensack, New Jersey, supplies plastic dispensing twist open and twist close closures and caps for liquids, lotions, paints, and viscous materials across plastic, glass, and metal containers. Its coverage of healthcare, personal care, and industrial markets reflects a versatile positioning that serves applications where resealability and dispensing control are critical.
Dispenser Pump Market
Mold-Rite Plastics, operating as MRP Solutions in the United States, is an injection molded plastic closures manufacturer offering dispensing closures through lines that include Weatherchem Flapper and Stull Technologies Ultra Light hinged, disc tops, twist caps, and Flip-N-Squeeze products. Its portfolio spans personal care, household, and pharmaceutical packaging, illustrating the importance of design variety and application specificity in a fragmented demand environment.
Amcor Plc, headquartered in Zurich, Switzerland, produces plastic caps and bottle closures, including screw, snap, flip-top, and dispensing closures with child-resistant, tamper-evident, and senior-friendly options. Its emphasis on safety features and broad market coverage aligns with regulatory and consumer expectations that increasingly treat closure functionality as a multidimensional requirement rather than a single-purpose component.
TriMas Packaging, based in the United States, delivers specialty dispensing, closure, and flexible packaging solutions, including tamper-evident, child-resistant, and dispensing closures for beauty, personal care, food, and industrial applications. Its specialty orientation positions it to serve customers who require customized performance attributes and regulatory compliance features.
BERICAP Holding GmbH, a German manufacturer of plastic caps and closures for food, beverage, and non-food markets, brings a global manufacturing footprint to dispensing and twist closure solutions. Its geographic reach supports customers seeking consistent supply across regions while navigating local compliance and material availability considerations.
Guala Closures S.p.A., headquartered in Alessandria, Italy, provides non-refillable closures, safety closures, tamper-evident systems, and dispensing solutions for beverage and other packaging applications. Its focus on safety and non-refillable design reflects ongoing industry attention to consumer protection and product integrity.
Beyond established positioning, recent innovation activity signals how quickly the competitive frontier is moving. In February 2024, AptarGroup launched an innovative twist dispensing closure for personal care products featuring a child-resistant design and an emphasis on eco-friendly packaging solutions. More recently, in April 2026, Tri-Sure introduced TulipCap, a two-part innovative twist cap for plastic containers that uses a polyethylene overcap, with optional post-consumer recycled material, and a thermoplastic elastomer insert for a gas-tight seal. These developments illustrate a dual strategic thrust: safety and convenience features are being integrated without compromising sustainability objectives, and material innovation is being used to close the gap between performance requirements and recyclability mandates.
Market Dynamics: Regulation, Materials, and the Sustainability Imperative
The market's trajectory is being reshaped by a set of interlocking dynamics that extend well beyond simple demand growth. Regulatory pressure is the most visible catalyst. Extended Producer Responsibility regulations in the EU, with expanding influence in North America, are driving innovation toward mono-material and fully recyclable closure designs, including for dispensing and twist closures. This shift is not cosmetic; it affects resin selection, liner compatibility, tooling design, and end-of-life processing pathways. Companies that treat recyclability as a design parameter from the outset are better positioned to meet compliance requirements while preserving functional performance.
The EU Single-Use Plastics Directive has already mandated tethered closures on beverage containers below three liters since July 2024, accelerating development of tethered dispensing and twist closure formats. This mandate has catalyzed engineering investment in attachment mechanisms, user experience, and production line compatibility. As tethered designs become more prevalent, the competitive advantage will increasingly belong to manufacturers who can deliver reliable tethered performance at scale while maintaining cost discipline and material efficiency.
Material sourcing and pricing behavior add another layer of strategic complexity. Twist dispensing closures are primarily manufactured from polypropylene and high-density polyethylene resins, and the price environment is regionally uneven. The April 2026 pricing dispersion for polypropylene across North America, Europe, and Northeast Asia demonstrates that Sourcing strategies cannot be universally replicated; they must be calibrated to regional cost structures, logistics corridors, and customer concentration. In parallel, manufacturers are incorporating post-consumer recycled resin in closures such as polyethylene overcaps to meet sustainability mandates and improve recyclability. This trend creates a direct link between regulatory compliance, material procurement, and product design, reinforcing the need for integrated planning rather than siloed decision-making.
Together, these dynamics suggest that the market's next phase of growth will be characterized by a tighter coupling of performance, compliance, and cost. Organizations that map these interdependencies clearly will be able to make more confident decisions about capacity expansion, material transitions, and product portfolio prioritization.
How to Use This Intelligence for 2026 Strategy
Access to a structured market view is only valuable if it translates into decision-making clarity. This research is designed to support several high-impact strategic actions. Leaders can use the historical and forecast trajectory to validate capacity investments and timing assumptions, ensuring that expansion plans are aligned with credible demand progression rather than optimistic speculation. Teams can use the segment decomposition to identify where application demand is most resilient and where material preferences are consolidating, enabling more targeted product development and inventory positioning. Competitive profiling allows organizations to benchmark their innovation cadence, assess partnership opportunities, and anticipate moves by scale players and specialized innovators alike.
Equally important, the integration of regulatory and material context provides a lens for scenario planning. As EPR frameworks expand and tethered closure requirements become more entrenched, companies that have already mapped the implications for resin selection, liner compatibility, and manufacturing throughput will face fewer disruptions. Those that have not will be forced into reactive adjustments that can compress margins and delay time-to-market. The research framework presented here is intended to reduce that uncertainty by making the relationships between regulation, materials, competitive behavior, and demand visible and actionable.
Final Thoughts: Turning Market Visibility into Strategic Advantage
The Worldwide Twist Dispensing Closure Market is expanding along a measured but durable growth path, supported by application diversity, regulatory-driven innovation, and a competitive landscape that rewards both scale and specialization. For decision-makers in 2026, the strategic question is no longer whether the market is growing, but how to align product architecture, sourcing strategy, and competitive positioning with the forces that are actively shaping that growth. The convergence of sustainability mandates, material cost dispersion, tethered closure requirements, and evolving end-use expectations creates a decision environment that rewards precision, foresight, and disciplined execution.
This market research was built to provide exactly that level of clarity. It consolidates historical performance, forecast trajectory, segment structure, competitive profiling, and industry dynamics into a single analytical foundation, enabling leadership teams to move from observation to action with confidence. The macro outline is clear; the operational details that will determine success or failure in specific regions, applications, and material pathways are where the deepest value lies.
To access the full market sizing, segment breakdowns, regional and application details, competitive benchmarks, and the complete forecast framework, visit the source page for the Worldwide Twist Dispensing Closure Market research. The complete report is structured to support immediate strategic use, giving your team the granular intelligence needed to turn 2026 planning into durable competitive advantage through 2032 and beyond.
For detailed analysis of this topic, please visit the official page: Worldwide Twist Dispensing Closure Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Unveiling the Strategic Value of Agar Resin Market Intelligence for 2026 Decision-Making
In an era where biopharmaceutical innovation and industrial bioprocessing converge at unprecedented speed, the agar resin sector stands at a critical inflection point. The Worldwide Agar Resin Market study published by PW Consulting is not merely a statistical summary; it is a strategic compass designed to guide executive teams, procurement leaders, and R&D directors through the complex terrain of supply chain volatility, technological transition, and competitive realignment. As organizations finalize their 2026 investment roadmaps, access to rigorously validated market intelligence has shifted from a luxury to an operational imperative.
The 2026-2032 outlook embedded in this research captures a market that has already demonstrated remarkable structural resilience and accelerating expansion. Historical data reveals a trajectory that moved from approximately 205 million USD in 2020 to an estimated 312 million USD in 2025, reflecting both consistent end-user demand and the gradual maturation of specialized manufacturing capabilities. The forecast extends this momentum, with the overall market positioned to cross 331 million USD in 2026 and continue its upward climb toward 580 million USD by 2032. The compound annual growth rate of 9.24 percent across the forecast window underscores a sector that is far more than a niche commodity; it is an enabling pillar for downstream purification, life sciences research, and high-value biochemical applications.
Worldwide Agar Resin Market
What separates this analysis from generic industry overviews is its deliberate focus on actionable intelligence. Corporate strategists cannot afford to base capital allocation, capacity planning, or vendor partnerships on surface-level narratives. The report provides a layered diagnostic framework that connects macroeconomic indicators, raw material microstructures, and competitive behavior into a coherent decision-support system. In the following sections, we outline the foundational architecture of the research and demonstrate how it translates into measurable strategic advantage for organizations operating in 2026.
A Research Architecture Built for Practical Execution
The study is structured to bridge the gap between high-level forecasting and on-the-ground operational realities. Rather than presenting isolated figures, the analysis maps interdependent variables that influence pricing behavior, capacity utilization, and regional supply reliability. Executive readers will find a multi-dimensional segmentation model that isolates critical market axes without overwhelming decision-makers with fragmented data points. The intent is to help teams identify where their product portfolios, procurement strategies, and geographic footprints intersect with the highest-value growth corridors.
Agar Market
Core Diagnostic Components
The report delivers a comprehensive set of analytical modules designed for immediate integration into corporate planning cycles. These include a historical reconstruction of market evolution from 2020 through 2025, a forward-looking assessment covering 2026 to 2032, and a rigorous examination of the structural forces shaping supply-demand equilibrium. Key components include:
- A detailed segmentation overview that breaks down the market by functional type, commercial application, and geographic distribution, allowing leadership teams to benchmark their positioning against broader structural patterns.
- A competitive landscape evaluation that profiles the companies shaping supply, innovation, and pricing behavior across the value chain, with focused attention on business models, manufacturing philosophies, and geographic reach.
- An in-depth analysis of raw material dynamics, capturing how seaweed cultivation cycles, climate sensitivity, and industrial demand from parallel sectors influence feedstock availability, processing margins, and inventory risk.
- Scenario-based interpretation tools that help strategists evaluate how shifts in regulatory expectations, bioprocessing adoption, and R&D spend could alter demand intensity over the forecast horizon.
Each module is designed to feed directly into strategic workflows. Procurement managers can use the raw material assessment to anticipate procurement windows and negotiate with greater confidence. Commercial leaders can map application trends to identify where customer budgets are expanding and where substitution risks may emerge. Corporate development teams can leverage the competitive profiles to evaluate partnership opportunities, acquisition targets, and capacity alignment strategies.
Competitive Architecture and Strategic Alignment
One of the most valuable contributions of the market study is its granular but strategically framed examination of the companies driving the agar resin ecosystem. The competitive field includes manufacturers that operate across multiple grade specifications, from food and bacteriological applications to high-purity agarose formulations optimized for chromatography and bioprocessing. The analysis does not merely list companies; it interprets their strategic posture, geographic footprint, and capability focus so that readers can understand where consolidation pressure, differentiation opportunity, and technology-led advantage are likely to materialize.
Incumbents and Differentiated Specialists
Several established firms anchor the supply architecture. Hispanagar S.A., based in Burgos, Spain, remains a leading manufacturer of high-quality agar, agarose, and related hydrocolloids derived from red seaweeds, supplying food, bacteriological, and bioprocessing grades, including materials engineered for agarose resin production. In India, Marine Hydrocolloids, part of the Meron Group and headquartered in Kochi, Kerala, represents a major producer and exporter of food-grade and bacteriological-grade agar-agar powder and strips, with substantial capacity serving global food, confectionery, and adjacent applications. B&V srl, known as The Agar Company and located in Gattatico, Italy, specializes in a broad spectrum of agar-agar powders spanning food-grade, pre-activated, microbiology, cosmetic, pharma, and technical grades, with an emphasis on custom formulations. In Indonesia, PT Agarindo Bogatama and PT Surya Indoalgas both draw on local seaweed cultivation and extraction capabilities, maintaining export-oriented operations that reach multiple international markets, including Japan and Germany.
On the bioprocessing side of the value chain, Global BioIngredients, headquartered in Doral, Florida and operating with manufacturing partners in Spain and Mexico, supplies premium food-grade, bacteriological, and plant tissue culture agar while collaborating on agarose formulations optimized for resin manufacturing and bioprocessing use. Bio-Works Technologies AB, based in Sweden, has carved out a distinctive position through its WorkBeads line, producing agarose-based chromatography resins using proprietary and patented methods that support sustainable manufacturing of agar and agarose beads for biopharmaceutical purification. Agarose Bead Technologies, a European manufacturer operating from Spain, focuses on high-performance agarose resins for bioprocessing and offers standard and customized chromatography resins that span laboratory through commercial scale.
Recent Strategic Movements That Shape 2026 Outlooks
The competitive environment is not static, and the report incorporates recent developments that directly influence how organizations should interpret capacity, innovation, and positioning risk. In October 2025, Agarose Bead Technologies advanced a continued expansion of production capacity and international presence for agarose resins used in bioprocessing, signaling a deliberate push to capture growing demand for purification-grade materials. Earlier, in January 2024, Bio-Works Technologies AB received a patent grant for an innovative method to manufacture agar and agarose beads using natural vegetable oils instead of fossil-based oils, an escalation of sustainability-focused engineering that enables greener chromatography resins and could influence procurement preferences among environmentally conscious end users.
These developments matter because they illustrate two simultaneously unfolding dynamics: capacity expansion in bioprocessing-oriented resin manufacturing and technology differentiation through more sustainable process design. For buyers and competitors alike, such moves alter the terms of engagement. Organizations evaluating supplier relationships or internal production strategies must consider not only price and availability, but also the pace at which sustainability claims, scale advantages, and application-specific customization are becoming competitive differentiators.
Raw Material Realities and Supply Chain Fragility
The strategic value of the study extends deeply into the upstream conditions that determine margin stability and supply predictability. Agar resin production ultimately depends on the availability and quality of seaweed feedstocks, and the report treats this dependency as a central source of both opportunity and vulnerability. In Asia, agar-agar prices experienced a continuous increase over 2025, driven by strong demand from food and pharmaceutical sectors in China and India. This pressure is not isolated to one region; it reflects a broader pattern in which parallel industrial demand can absorb available supply and raise the cost floor for specialized grade production.
The global aquaculture context adds further nuance. Global aquaculture production of algae reached 37.8 million tonnes in 2022, yet high-quality Gelidium and Gracilaria suitable for agar extraction remain susceptible to climate change and ocean temperature fluctuations. This sensitivity creates supply constraints and price volatility that can ripple through processing operations, particularly when harvest timing, seasonal yield variation, and cultivation limits intersect with fixed manufacturing schedules. Seaweed feedstock availability and quality directly affect thin manufacturing margins for agar processors, while seasonal harvest variations and cultivation limits contribute to inventory and working capital pressures.
Implications for Procurement and Capacity Planning
For executive teams, these raw material conditions carry practical consequences. Forecasting alone is insufficient if procurement strategies cannot absorb sudden feedstock tightening or quality variability. The report emphasizes that organizations need to model not only average price trends, but also the probability and impact of supply shocks tied to environmental volatility and cross-sector demand competition. Working capital planning becomes more critical when inventory must buffer against harvest irregularities, and supplier relationships become more strategic when grade consistency and traceability are essential to downstream performance.
By embedding these realities into the market analysis, the study helps decision-makers avoid the common mistake of treating the agar resin market as a purely demand-driven growth story. The supply side is equally formative. Organizations that internalize the interaction between aquaculture constraints, regional price momentum, and processing economics are better positioned to time purchases, negotiate flexible contracts, and evaluate whether backward integration, long-term supplier partnerships, or diversified sourcing offers the best risk-adjusted path for 2026 and beyond.
Market Structure, Concentration, and Strategic Positioning
The competitive concentration embedded in the overall market structure provides additional context for corporate planning. The analysis highlights a landscape in which a relatively small group of participants accounts for a substantial share of value capture, while a broader base of specialized manufacturers competes on grade differentiation, regional proximity, and application-specific performance. This structure has direct implications for pricing power, partnership economics, and entry feasibility.
High concentration among the leading participants often signals mature capabilities, established customer relationships, and stronger negotiating leverage with suppliers and buyers alike. At the same time, the presence of specialized producers demonstrates that differentiation remains viable, particularly where firms can offer tailored formulations, sustainable process attributes, or stronger integration between raw material sourcing and resin performance. For organizations evaluating where to compete, this dual structure suggests that broad commodity positioning may face tighter margin pressure, whereas specialty-grade relevance, application alignment, and sustainability credentials may offer more durable value.
The report is designed to help strategists interpret this structure without relying on simplistic market-share narratives. Instead, it encourages a functional reading of the landscape: which participants are expanding capacity, which are advancing process innovation, which are anchored in specific geographic or grade niches, and where consolidation or collaboration is likely to reshape the field. Such interpretation is essential for companies deciding whether to pursue supplier selection based primarily on cost, quality assurance, innovation continuity, or supply resilience.
Translating Market Intelligence into 2026 Decisions
The overarching objective of this Worldwide Agar Resin Market study is to convert complex market behavior into practical strategic guidance. In 2026, the organizations that outperform will be those that treat market intelligence as a dynamic input to operational design rather than a static reference point. That means aligning demand forecasts with supplier capability assessments, connecting sustainability developments to procurement preferences, and evaluating geographic exposure in light of feedstock volatility and regional price dynamics.
The study supports this objective by offering a structured way to interrogate the market. Executives can use it to identify where growth is most likely to concentrate, where supply-side risk is most acute, where competitive differentiation is being built, and where strategic partnerships may create disproportionate value. It also helps teams challenge internal assumptions, especially those that underestimate the influence of environmental constraints on raw material availability or that overstate the stability of pricing in a market shaped by multiple competing demand sources.
Why the Full Report Matters for Executive Planning
Strategic decision-making in a market of this complexity requires detail that cannot be fully conveyed in a summary overview. To capture the full depth of the analysis, including the precise segmentation interpretation, the company-by-company competitive mapping, the raw material scenario implications, and the forecast trajectory across multiple market dimensions, readers are encouraged to access the complete PW Consulting Worldwide Agar Resin Market report. The published study contains the structured datasets, interpretive commentary, and competitive intelligence that executive teams need to operationalize the insights described here.
For leaders preparing investment plans, sourcing strategies, product positioning, or partnership evaluations for 2026, the complete report provides the evidentiary foundation necessary to reduce uncertainty and improve the quality of strategic choices. It is designed to be referenced repeatedly during planning cycles, not read once and filed away.
Recommended Strategic Actions for 2026
Based on the directional signals captured in the research, organizations can begin aligning their decision frameworks around several priorities that the study explores in greater depth:
- Reassess supplier portfolios with explicit attention to grade consistency, sustainability attributes, and the capacity trajectories of bioprocessing-focused resin manufacturers.
- Incorporate raw material volatility into working capital and inventory models, especially where procurement depends on seaweed feedstocks subject to seasonal and environmental variability.
- Evaluate application-side demand intensity by distinguishing between biopharmaceutical production requirements, academic and research needs, and diagnostic laboratory consumption patterns, since each creates different procurement behaviors and growth drivers.
- Monitor competitive signals tied to capacity expansion and process innovation, particularly where patented or proprietary manufacturing methods may alter long-term cost structures and sustainability positioning.
- Consider geographic sourcing diversification in light of regional price pressures and the concentration of demand in major industrial markets.
The agar resin market is advancing on multiple fronts at once: sustained demand growth, evolving bioprocessing requirements, sustainability-driven manufacturing innovation, and persistent raw material fragility. In that environment, the organizations that make the best decisions will be those equipped with the most reliable intelligence. PW Consulting's Worldwide Agar Resin Market study is built for exactly that purpose, offering a comprehensive, strategically oriented, and execution-ready view of a market that continues to gain importance across the life sciences and industrial bioprocessing landscape.
For detailed analysis of this topic, please visit the official page: Worldwide Agar Resin Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Adult VAD Market to Reach $2.7B by 2032, Driven by 5.81% CAGR
By pmarketresearch, 2026-09-16
Strategic Intelligence for the Adult VAD Landscape: Why the 2026 Decision-Maker Needs This Report
The global adult ventricular assist device (VAD) market stands at a critical inflection point. As device engineering matures, reimbursement frameworks evolve, and clinical evidence accumulates, the strategic question is no longer whether mechanical circulatory support will expand, but where capital, R&D, and commercial resources should be deployed for maximum return. Our latest Worldwide Adult Ventricular Assist Device Market study delivers the structured intelligence required to answer that question with precision.
From an investment standpoint, the trajectory is unmistakable. Historical revenue climbed from roughly $1,385.4 million in 2020 to $1,845.5 million by 2025, demonstrating consistent upward momentum even amid regulatory scrutiny and supply chain headwinds. The forecast window projects this expansion to continue, with the market estimated at $1,941.1 million in 2026 and anticipated to reach $2,742.1 million by 2032. This growth path reflects a compound annual growth rate of 5.81 percent across the 2026 to 2032 forecast horizon, signaling a market that is scaling methodically rather than spiking on short-term novelty. For executives planning multi-year roadmaps, that cadence offers a reliable baseline for capacity planning, partnership evaluation, and portfolio positioning.
Worldwide Adult Ventricular Assist Device Market
Yet macro numbers alone do not guide execution. Strategic advantage in this space depends on understanding how demand is distributed across device architectures, clinical indications, and regional ecosystems. The report dissects these structural layers without reducing them to superficial tables. Readers will encounter a rigorous examination of left-sided, right-sided, and biventricular configurations, alongside destination therapy, bridge-to-transplant, and bridge-to-recovery applications. Equally important, the analysis maps regional adoption patterns across North America, Europe, Asia Pacific, and the Rest of World, providing context for where infrastructure maturity, clinical trial activity, and reimbursement readiness intersect. Rather than presenting isolated figures, the study connects these dimensions to operational implications, helping leadership identify which segments justify accelerated investment and which require measured entry or partnership strategies.
The competitive environment demands equally granular attention. The market is tightly concentrated, with the top three firms capturing approximately 88.5 percent of revenue and the top five accounting for 94.2 percent. This structure shapes pricing dynamics, clinical adoption pathways, and the feasibility of new entrant positioning. Abbott Laboratories anchors a significant portion of the landscape through its HeartMate 3 LVAD platform, an FDA-cleared solution for both bridge-to-transplant and destination therapy in adults with advanced heart failure. Recent five-year MOMENTUM 3 trial data, reported in October 2024, demonstrated 58 percent survival free of disabling stroke or transplant, reinforcing the device's clinical narrative and long-term value proposition. Abbott's sustained evidence generation illustrates how clinical credibility translates into durable market positioning.
Competitive Architecture and the Implications of Recent Moves
Medtronic's HeartWare HVAD System remains a historically significant centrifugal flow LVAD used for adult bridge-to-transplant and destination therapy, but the competitive picture is complicated by a Class I recall issued in December 2021. The FDA advisory has effectively constrained new implant recommendations, and ongoing support remains limited, altering the risk calculus for centers evaluating centrifugal platforms. This situation underscores a broader strategic reality: device reliability, post-market surveillance responsiveness, and clinical communication are now inseparable from commercial viability. Firms operating in this segment must navigate not only innovation cycles but also the reputational and operational consequences of field safety actions.
Total Artificial Heart Market
LivaNova PLC has moved aggressively to expand its footprint with the RELINANT VAD, a next-generation centrifugal LVAD designed for adults requiring bridge-to-transplant or bridge-to-recovery support. After securing CE Mark approval for full commercialization in Europe in June 2024, the company has positioned itself to compete more directly in mature European centers while also building the evidence base needed for broader adoption. Berlin Heart GmbH contributes a distinct mechanical profile through the EXCOR Adult VAD, a pneumatically driven external system approved under CE Mark for short- and long-term support in biventricular failure. Its November 2023 launch of a next-generation controller, with improved usability and battery life, demonstrates how incremental engineering improvements can enhance clinician acceptance and patient mobility even within established product categories.
Syncardia Systems rounds out the competitive set with the SynCardia Total Artificial Heart, an FDA-approved bridge-to-transplant option for adults with biventricular failure who are not candidates for VAD support. This total artificial heart pathway addresses a specific unmet need in end-stage biventricular disease, highlighting how segment differentiation can create defensible niches even in a concentrated market. Together, these players illustrate that competitive advantage in adult VADs is not determined solely by first-to-market timing, but by the interplay of regulatory standing, clinical evidence, post-market execution, and fit to distinct patient populations.
Regulatory and Reimbursement Dynamics That Shape Commercial Reality
The strategic weight of the adult VAD market cannot be evaluated without confronting its regulatory intensity. In the United States, the FDA classifies adult VADs as Class III devices, requiring premarket approval under 21 CFR 870.02. This designation creates a high barrier to entry and places a premium on robust clinical data packages, manufacturing consistency, and lifecycle management. The implication for market participants is clear: speed-to-market is subordinate to proof of safety and effectiveness, and companies that invest early in comprehensive clinical programs often secure a durable regulatory moat.
European dynamics impose their own structure. Under the EU Medical Device Regulation, VADs require Notified Body certification under Annex II, with mandatory post-market surveillance plans that extend oversight far beyond initial approval. This framework elevates the importance of real-world evidence generation, traceability, and ongoing risk management. For organizations planning cross-border launches, the cost of compliance is not a one-time event but a continuous operational commitment that affects resource allocation, partner selection, and launch sequencing.
Reimbursement architecture is equally decisive. In the United States, CMS DRG 003 covers LVAD implants, with an average payment of approximately $142,000 for destination therapy under the FY2025 IPPS final rule issued in August 2024. This reimbursement baseline influences hospital adoption economics, case volume planning, and the willingness of centers to invest in program infrastructure. In parallel, the 2024 AMA CPT manual updated CPT code 33975 for LVAD implantation to include percutaneous approaches, reflecting procedural evolution and potentially affecting billing pathways, operative planning, and the economic calculus of less invasive deployment strategies. These reimbursement nuances matter because they shape the practical feasibility of adoption at the institutional level, where clinical enthusiasm must align with financial sustainability.
What the Report Delivers for 2026 Decision-Making
This study is structured to move beyond descriptive market mapping and into actionable intelligence. It provides a comprehensive analysis of market size and forecast behavior across the full 2020 to 2032 period, giving leadership a defensible baseline for scenario planning. The segmentation framework examines device type, application, and regional distribution in a way that highlights where demand is consolidating and where white space may still exist. Rather than isolating each axis, the report analyzes how these dimensions interact, enabling readers to assess, for example, how a shift in clinical preference toward one device architecture could influence regional growth profiles or how reimbursement readiness might accelerate or delay adoption in specific markets.
The competitive section delivers firm-level profiles that connect product positioning, regulatory status, and recent corporate events to strategic implications. By integrating developments such as MOMENTUM 3 long-term data, RELINANT VAD's European clearance, and EXCOR controller modernization, the analysis shows how individual events alter competitive momentum and what they signal for future share dynamics. The regulatory and reimbursement review ties these commercial threads together by identifying the compliance and payment frameworks that determine which strategies are viable in practice. Together, these components create a decision-ready picture of the market's current structure and its likely direction.
For 2026 planning, the report is designed to support several core executive functions. It helps strategy teams evaluate entry and expansion timing by clarifying where evidence, regulation, and reimbursement are converging. It supports product and R&D leaders in assessing which clinical needs remain underserved and where incremental innovation could yield adoption advantages. It informs investor and partnership discussions by framing the concentration landscape, the significance of recent field actions, and the durability of evidence-driven positioning. And it provides marketing and market access teams with the structural context needed to align messaging with the reimbursement and institutional realities that govern procurement decisions.
Why This Intelligence Matters Now
The adult VAD market is not simply growing; it is maturing into a more complex, evidence-driven, and regulation-intensive arena. That maturation creates both opportunity and risk. Opportunity exists for organizations that can align device capability with robust clinical proof, navigate Class III approval pathways efficiently, and demonstrate value within existing reimbursement structures. Risk accumulates for those that underestimate the operational burden of post-market surveillance, overlook the financial realities of hospital adoption, or misread competitive signals in a concentrated landscape. The companies that succeed in 2026 and beyond will be those that treat market intelligence as a strategic asset rather than a periodic reference.
This report offers the depth, structure, and forward-looking framing required to make that judgment with confidence. The full study contains the detailed segmentation figures, regional breakdowns, and firm-level assessments that executives need to convert insight into action. For decision-makers shaping capital allocation, product strategy, and market access plans, the complete analysis provides the evidence base to move from hypothesis to commitment.
For detailed analysis of this topic, please visit the official page: Worldwide Adult Ventricular Assist Device Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Oilseed Extraction Equipment Market Hits $5.25B in 2025, Projecting 5.12% CAGR to 2032
By pmarketresearch, 2026-09-16
Navigating the Global Oilseed Extraction Equipment Market: Strategic Intelligence for 2026 Decision-Making
Setting the Stage: Why Market Intelligence Matters Now
The global oilseed extraction equipment market stands at a critical inflection point. As agricultural processors, engineering firms, and capital allocators navigate shifting feedstock economics, tightening sustainability mandates, and accelerating technological adoption, the ability to make precise, forward-looking investment decisions has never been more vital. This analysis draws from our latest Worldwide Oilseed Extraction Equipment Market research, a comprehensive intelligence framework designed to translate complex market signals into actionable strategy.
Our investigation spans the historical trajectory from 2020 through 2025 and projects market evolution across the 2026–2032 forecast horizon. The research is structured to serve multiple enterprise functions: procurement planning, capacity expansion modeling, competitive positioning, and risk assessment. Rather than offering static snapshots, the study maps the underlying forces that will shape equipment demand, pricing architecture, and regional deployment patterns over the coming years.
For executives evaluating capital projects or assessing vendor partnerships in 2026, this research provides the analytical rigor required to separate short-term market noise from long-term structural shifts. The following sections outline the market's developmental arc, the operational realities shaping equipment selection, the competitive forces at play, and the practical tools embedded within the full report.
Market Trajectory and Growth Architecture
To understand where the market is heading, it is essential to first map its historical footing. The global oilseed extraction equipment market has demonstrated consistent expansion over the past half-decade, reflecting sustained demand for edible oils, biofuels, and specialty oil fractions. Revenue across the tracked period illustrates a clear upward trajectory, rising from approximately USD 4,210.5 million in 2020 to USD 5,250.0 million in 2025.
This baseline positions the market for an estimated valuation of USD 5,842.21 million in 2026, with growth continuing through the forecast window. By 2032, market revenue is projected to approach USD 7,446.57 million, reflecting a compound annual growth rate of 5.12 percent across the 2026–2032 period. These figures convey more than aggregate expansion; they signal the pace at which processing capacity modernization, efficiency upgrades, and emerging regional demand are being absorbed into the global equipment ecosystem.
Such growth is neither uniform nor accidental. It reflects a combination of factors, including evolving seed crop economics, downstream processing requirements, and the gradual replacement of legacy extraction infrastructure. For decision-makers, this trajectory underscores the importance of timing: equipment purchases, plant expansions, and technology transitions undertaken in 2026 must account for both near-term profitability and medium-term structural demand.
Defining the Scope: What This Research Delivers
A robust market study must move beyond top-line projections to examine the operational dimensions that actually determine project success. Our research is built around a multi-layered framework that connects market sizing with the practical variables that procurement teams, plant managers, and strategy leaders encounter daily.
Worldwide Oilseed Extraction Equipment Market
The report dissects the market across three primary analytical lenses: equipment type, seed feedstock, and geographic deployment. These dimensions are not examined in isolation. Instead, they are cross-referenced to reveal how regional processing habits, feedstock availability, and technology preferences intersect to shape demand. The analysis covers solvent extraction systems, mechanical pressing equipment, and pre-treatment machinery, alongside major seed categories including soybeans, rapeseed and canola, sunflower seeds, palm kernels, and other seed variants.
Geographic coverage spans five macro regions, enabling a comparative understanding of where installation activity, replacement cycles, and capacity additions are most concentrated. This territorial mapping is essential for firms evaluating export opportunities, localizing service operations, or assessing competitive exposure in specific markets.
Operational and Supply-Side Dynamics Shaping Equipment Demand
Market growth does not occur in a vacuum. Several operational and material dynamics are actively shaping how extraction equipment is specified, manufactured, and deployed. Understanding these forces is essential for aligning procurement strategy with ground-level realities.
One of the most significant variables affecting equipment economics is the input material environment. Stainless steel remains a foundational material for corrosion-resistant components in extraction machinery and food processing systems. In 2026, the global stainless steel market reached an estimated valuation of USD 146.1 billion, with pricing influenced by nickel, chromium, and energy costs. Regional price differentials further complicate procurement planning. In March 2026, stainless steel prices in Northeast Asia stood at approximately USD 1.79 per kilogram, while Southeast Asia prices reached USD 2.48 per kilogram. These variances reflect localized demand from food processing equipment sectors and upstream feedstock cost fluctuations, directly influencing equipment manufacturing costs and regional pricing strategies.
Grain and Seed Cleaning Equipment (Grain & Seed Cleaning Equipment) Market
Parallel to material economics, operational efficiency has become a central focus for modern extraction facilities. Automation control systems are increasingly implemented in oil mills to improve throughput, energy efficiency, and yield in extraction processes. At the same time, energy-saving technologies such as smart temperature control, heat energy recovery, and high-efficiency transmission systems are being integrated into contemporary pressing equipment to reduce consumption. These innovations are not merely technical enhancements; they are becoming core procurement criteria for processors seeking to lower operating costs and improve margin resilience.
Regulatory compliance also continues to shape facility design and equipment configuration. Processing operations must adhere to food safety standards, including requirements for infrastructure such as handwashing sinks with water temperatures between 100 and 120 degrees Fahrenheit in production areas. While individual regulatory details may appear granular, collectively they influence floor layout, equipment spacing, sanitation workflows, and ancillary system specifications. Firms that anticipate these compliance dimensions early can avoid redesign costs and commissioning delays.
Competitive Landscape: Navigating a Fragmented Yet Concentrated Arena
The competitive environment in oilseed extraction equipment reflects a balance between focused market power and broad participation across technology tiers and geographies. Our analysis indicates that the top three players account for approximately 32.4 percent of market revenue, while the top five participants represent roughly 46.8 percent. This level of concentration suggests that while leading incumbents hold meaningful share, there remains substantial room for specialized suppliers, regional manufacturers, and technology-focused entrants.
Several established firms anchor the competitive landscape, each bringing distinct capabilities to the market. Anderson International Corp, based in Cleveland, Ohio, is recognized as the inventor of the continuous mechanical screw press and designs, manufactures, and commissions full oilseed processing systems encompassing preparation, mechanical pressing, and extrusion equipment for both low and high-oil-content seeds, with operations spanning more than 100 countries. French Oil Mill Machinery Company, headquartered in Piqua, Ohio, operates as a custom designer and manufacturer of oilseed screw presses, roller mills, and related extraction equipment, supplying processors in over 80 countries. CPM, alongside Crown Iron Works, provides high-performance extraction equipment and advanced solvent extraction technologies capable of handling a wide variety of oilseeds, delivering reliable solutions for oil and meal production.
On the global stage, Myande Group Co., Ltd., based in Yangzhou, Jiangsu, China, is a leading supplier of complete oilseed preparation, extraction equipment, and turnkey plants for oils and fats processing, having delivered significant global crushing capacity with a strong presence across Asia and beyond. Additional notable participants include GOYUM Screw Press of Ludhiana, Punjab, India, which manufactures and exports solvent extraction plants, screw presses, and complete oilseed processing machinery for edible and non-edible oils; Henan Huatai Cereals and Oils Machinery Co., Ltd. of Henan, China, which specializes in oilseed pretreatment, solvent extraction, and refining equipment with comprehensive processing lines; Bühler Group of Uzwil, Switzerland, which offers oilseed processing equipment and solutions within its broader grain and oil processing portfolio; RoseDowns of Hull, United Kingdom, known for its Sterling Series screw presses and established reputation in mechanical extraction; and Muez Hest of India, which provides turnkey oil extraction plants and solvent extraction solutions for oilseeds worldwide.
Competitive differentiation in this market increasingly depends on technology integration, service responsiveness, and the ability to offer scalable solutions across seed types and processing volumes. Recent industry activity illustrates how firms are maintaining visibility and advancing their commercial positioning. In May 2026, French Oil Mill Machinery Company exhibited its oilseed processing equipment at the AOCS Annual Meeting & Expo, showcasing solutions for processors running or planning oilseed extraction operations. In June 2026, CPM scheduled participation in multiple industry events including BioInnovAsia, FENAGRA, BioFuels, and OleoFuels, highlighting extraction equipment for oilseed and related processing. Also in June 2026, the 19th International Grain and Oil Exhibition in Guangzhou featured oil extraction equipment, pre-press machines, and extraction and separation equipment, drawing industry participants focused on the latest processing technologies.
Why This Research Matters for 2026 Strategy
For organizations making capital allocation, vendor selection, or market entry decisions in 2026, the value of this research lies in its ability to connect high-level market direction with the granular considerations that determine project outcomes. Equipment purchases are rarely isolated transactions; they are multi-year commitments that interact with feedstock contracts, energy costs, regulatory environments, and downstream product demand. A rigorous market intelligence foundation enables executives to evaluate those interdependencies with greater confidence.
Strategic users will find particular value in the report's structured approach to demand modeling, competitive benchmarking, and regional assessment. The analysis helps answer practical questions: which equipment categories are expanding most rapidly and why; how feedstock preferences vary by geography; what operational trends are reshaping procurement criteria; and where competitive intensity is rising or easing. By integrating material cost dynamics, efficiency-driven technology adoption, and compliance considerations, the study provides a holistic lens for planning and negotiation.
The research is also designed to support scenario planning. Because the forecast period extends through 2032, decision-makers can stress-test capacity investments against multiple growth paths and assess the timing of replacement cycles, technology upgrades, and geographic expansion. This forward-looking orientation is essential in a market where equipment lifecycles, installation lead times, and service capabilities all influence long-term operating economics.
Key Takeaways and What the Full Report Unlocks
The global oilseed extraction equipment market is expanding against a backdrop of evolving technology, shifting material costs, and diverse regional demand. While aggregate growth signals are clear, the strategic implications vary significantly by segment, geography, and operational context. Understanding where to focus investment, how to evaluate suppliers, and which trends merit close monitoring requires detailed, cross-referenced analysis rather than broad market summaries.
The full Worldwide Oilseed Extraction Equipment Market research report provides the depth and structure needed to move from strategic curiosity to concrete action. It delivers segment-level breakdowns, regional demand mapping, competitive profiling, and operational insight that together form a comprehensive decision-support toolkit. For procurement teams, it informs specification priorities and vendor evaluation; for strategy leaders, it clarifies growth vectors and competitive exposure; for investors and lenders, it supports demand validation and risk assessment.
To access the complete dataset, detailed segment analysis, comprehensive company profiles, and the full forecast framework, readers are encouraged to explore the full report via the source page. The intelligence contained within is designed to equip organizations with the clarity required to make confident, evidence-based decisions throughout 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Worldwide Oilseed Extraction Equipment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Medical Hemostatic Clip Market Hits $580.25M in 2025, Projects 7.2% CAGR to 2032
By pmarketresearch, 2026-09-16
## Navigating the Global Medical Microscopic Hemostatic Clip Market: Strategic Intelligence for 2026 and Beyond
The landscape of minimally invasive and microsurgical interventions is evolving at an unprecedented pace, driven by an aging global population, rising prevalence of vascular and gastrointestinal pathologies, and sustained demand for precision vessel management. Within this ecosystem, medical microscopic hemostatic clips have emerged as indispensable tools, bridging the gap between surgical efficacy and patient safety. Our latest market study on the Worldwide Medical Microscopic Hemostatic Clip Market delivers a comprehensive, data-grounded intelligence framework designed specifically for executive decision-makers navigating the 2026-2032 horizon.
This analysis serves as a strategic preview of the full report, highlighting the macro trajectory, competitive architecture, and regulatory-commercial dynamics that will define market positioning over the next seven years. The complete publication contains granular segmentation matrices, scenario-based forecasting, and actionable go-to-market blueprints that exceed the scope of this overview.
Market Macro Architecture: From Baseline Recovery to Sustained Expansion
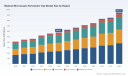
Over the historical observation window of 2020 through 2025, the global microscopic hemostatic clip market demonstrated resilient growth, navigating supply chain recalibrations, procedural volume rebounds, and iterative product innovation. The sector expanded from a baseline of approximately 410.25 million USD in 2020 to an estimated 580.25 million USD in 2025, reflecting a cumulative trajectory shaped by procedural adoption in advanced surgical centers and the gradual replacement of legacy ligation methods with clip-based occlusion systems.
Looking ahead, the forecast period from 2026 to 2032 projects a sustained compound annual growth rate of 7.2 percent, translating the market toward a projected valuation approaching 944.01 million USD by the terminal forecast year. This expansion is not merely a function of volume recovery; it reflects structural shifts in surgical planning, reimbursement optimization, and the increasing integration of microclip technologies into standardized endoscopic and microsurgical workflows.
Structural Drivers Shaping the Growth Trajectory
Several interlocking forces are reinforcing the long-term expansion outlook:
-
Procedural migration toward minimally invasive platforms: As surgical teams increasingly favor approaches that minimize tissue trauma and accelerate recovery, clip-based hemostasis provides a predictable, rapid-deployment alternative to suturing or thermal coagulation in delicate microsurgical fields.
-
Material science standardization: Modern microclips are engineered from titanium Grade 1, annealed for optimal malleability while maintaining biological inertness, MRI compatibility, and radiolucency. This material consistency reduces procedural variability and supports long-term implant safety profiles.
-
Regulatory clarity and compliance maturity: Devices in this category are classified under established frameworks such as 21 CFR 878.4300 (product code FZP) in the United States, requiring adherence to general controls including good manufacturing practices and labeling standards. In parallel, European manufacturers align with DIN EN ISO 13485 and legacy 93/42/EEC certification pathways, reinforcing cross-regional quality assurance expectations.
-
Reimbursement pathway optimization: The introduction of dedicated coding mechanisms, including HCPCS Code C9901 for outpatient defect closure procedures using repositionable hemostasis clips, has improved cost transparency and supported broader adoption in ambulatory surgical environments.
Competitive Architecture and Strategic Positioning
The market exhibits a moderately concentrated structure, with the top three participants accounting for approximately 62.45 percent of aggregate revenue and the top five reaching roughly 78.12 percent. This concentration reflects the specialized nature of microsurgical instrumentation, where manufacturing precision, regulatory clearances, and clinical credibility create meaningful barriers to entry. Yet the landscape remains dynamic, characterized by targeted product launches, regulatory milestones, and strategic reallocation of distribution rights.
Leading Commercial Players and Strategic Differentiation
The competitive field is anchored by a cohort of specialized manufacturers and diversified surgical instrument groups, each carving distinct positioning through product architecture, clinical specialization, and channel strategy:
-
Synovis Micro Companies Alliance, Inc. (Baxter): Operates from Birmingham, Alabama, and offers the GEM MicroClip and SuperFine MicroClip titanium hemostatic microclip lines, engineered for microsurgical vessel occlusion under microscopic visualization. These platforms feature chevron-shaped designs with atraumatic teeth and dedicated appliers. In early 2025, the company secured FDA 510(k) clearance for the GEM ZIPCLIP automatic microclip applier, preloaded with 15 titanium microclips, signaling a move toward workflow automation and reduced intraoperative handling complexity.
-
Peter Lazic GmbH: Based in Tuttlingen, Germany, this firm specializes in high-quality microsurgical instruments, including aneurysm clips and related hemostatic solutions tailored for neurosurgical and microsurgical applications. Its certification footprint under DIN EN ISO 13485 and CE marking frameworks reinforces its reputation in highly regulated procedural environments.
-
S&T Microsurgical Instruments: Operating from Neuhausen, Switzerland, the company develops and manufactures microsurgical instruments and sutures, with product distribution executed through partner networks to reach microsurgeon applications focused on vessel control.
-
Scanlan International, Inc.: Headquartered in Saint Paul, Minnesota, Scanlan maintains a dedicated microsurgical line featuring VASCU-STAT Bulldog clamps and micro clamps designed for small to medium vessel hemostasis across varied surgical fields.
-
Kapp Surgical Instrument Inc.: Located in Cleveland, Ohio, Kapp focuses on custom stainless steel surgical instruments and implants, including solutions adapted for microsurgical applications, enabling bespoke configurations for institutional and procedural specificity.
-
Amsel Medical Corporation: Based in Cambridge, Massachusetts, Amsel offers the SCureClamp with iDOT technology, an FDA-cleared and CE-marked mechanical vessel occluder designed for tubular structures where metal ligation clips are indicated, expanding the mechanical occlusion toolbox beyond traditional clip geometry.
-
MicroSurgical Technology: An active United States-based provider of microsurgical instruments, including hemostatic clip solutions for delicate procedures, reinforcing the breadth of the specialized instrumentation supply base.
Recent Market Catalysts: Launches, Acquisitions, and Regulatory Milestones
The competitive rhythm has accelerated through a series of consequential events that illustrate how incumbents and emerging players are reshaping product access and procedural reach:
-
In March 2025, Olympus Corporation introduced the Retentia HemoClip, a single-use hemostasis clip featuring 360-degree rotation, one-step deployment, and three sizing options optimized for GI bleeding control and defect closure. This launch underscores the continuing convergence between endoscopic hemostasis and clip-based closure technologies.
-
In March 2026, Micro-Tech Endoscopy signed a definitive agreement to acquire global distribution rights for the DuraClip repositionable hemostasis clip product line from CONMED. This transaction reflects a strategic push to consolidate access to repositionable clip platforms, which offer intraoperative flexibility and may reduce revision-related procedural friction.
Polymer Ligating Clips Market -
Earlier in January 2025, Synovis Micro Companies Alliance, Inc. received FDA 510(k) clearance for the GEM ZIPCLIP automatic microclip applier, a regulatory milestone that highlights growing clinician demand for preloaded, automated delivery systems that streamline vessel occlusion in microsurgical settings.
Segmentation Dynamics: Technology, Application, and Regional Flow
While the overall market trajectory is defined by the headline growth rates and revenue scale outlined above, the real strategic value lies in understanding how technology types, clinical applications, and regional demand patterns interact to shape procurement priorities, R&D allocation, and channel investment. The complete report unpacks these dimensions with detailed volume and value estimates, but several structural observations merit executive attention.
Technology Architecture: Rotatable Versus Non-Rotatable Platforms
The market is bifurcated between rotatable hemostatic clips and non-rotatable variants, each serving distinct procedural requirements. Rotatable designs offer intraoperative orientation flexibility, which can be particularly valuable in endoscopic and laparoscopic contexts where access angles are constrained and repositioning may reduce the risk of misdeployment. Non-rotatable clips, by contrast, continue to serve use cases where fixed geometry, tactile familiarity, and cost efficiency align with established surgical workflows. The comparative adoption balance between these two categories is shaped by procedural mix, surgeon preference, and the pace at which automated applier systems broaden the usability of advanced clip geometries.
Application Landscape: Endoscopy, Laparoscopy, and Adjunctive Use
Clinical application segmentation reveals a clear hierarchy of demand concentration. Gastrointestinal endoscopy represents a dominant application domain, reflecting the high procedural volume of GI bleeding management and mucosal defect closure, where clip-based hemostasis offers rapid deployment and predictable occlusion. Laparoscopic surgery constitutes a substantial secondary application stream, driven by the broader shift toward minimally invasive abdominal procedures that require reliable vessel control in confined operative fields. A remaining portion of demand flows into other medical procedures, encompassing specialized microsurgical and adjunctive use cases where clip-based occlusion complements broader hemostatic strategies.
Regional Demand Distribution
Regional demand patterns reflect differences in surgical infrastructure maturity, procedural reimbursement frameworks, and the penetration of advanced endoscopic and microsurgical capabilities. North America continues to anchor a substantial share of global demand, supported by established ambulatory surgical volumes, robust device regulation pathways, and early adoption of repositionable and automated clip platforms. Europe follows as a significant demand center, shaped by rigorous quality certification expectations and a strong base of specialized microsurgical instrument manufacturers. The Asia Pacific region represents a rapidly expanding demand pool, where procedural volume growth, healthcare capacity expansion, and increasing access to minimally invasive technologies are accelerating market participation. Latin America and the Middle East and Africa collectively form emerging demand corridors, where incremental capacity building and selective technology adoption are gradually broadening the addressable market base. The full report quantifies these regional dynamics with precise value estimates and trend projections, while this preview intentionally preserves the broader narrative arc.
Strategic Imperatives for 2026 Decision-Making
Product Portfolio and Innovation Roadmapping
Executives should evaluate whether current product architectures adequately address the converging demand for rotational flexibility, single-use convenience, and automated applier integration. The recent FDA clearance for preloaded automatic microclip appliers and the launch of 360-degree rotatable single-use clips indicate that workflow simplification is becoming a competitive differentiator rather than a supplementary feature. Strategic portfolio planning should therefore prioritize platform modularity, applier-clip compatibility, and sizing breadth aligned to high-frequency procedural indications.
Regulatory and Quality System Alignment
Given the classification of titanium hemostatic microclips as Class II implantable devices under established regulatory codes, and the expectation of ISO 13485-aligned quality systems for CE-marked products, compliance strategy must be treated as a market access enabler rather than a back-office function. Companies seeking expanded footprint should ensure that design controls, labeling, and manufacturing documentation support both domestic clearances and international certification requirements, particularly when pursuing distribution partnerships or cross-border market entry.
Channel Strategy and Distribution Architecture
The acquisition of global distribution rights for repositionable clip product lines illustrates how distribution control can accelerate market reach without requiring in-house manufacturing expansion. Organizations should assess whether their current channel model favors direct institutional sales, distributor partnerships, or hybrid architectures, and whether repositioning rights, exclusive territories, or co-marketing arrangements could strengthen competitive positioning in high-growth application areas such as GI endoscopy and laparoscopic surgery.
Reimbursement and Economic Value Storytelling
With outpatient coding mechanisms now available for defect closure procedures using repositionable hemostasis clips, economic value propositions must extend beyond clinical performance to encompass procedural efficiency, turnover optimization, and total cost of care. Sales and market access teams should develop institution-specific narratives that link clip-based hemostasis to reduced procedure time, fewer ancillary ligation steps, and compatible outpatient billing pathways, particularly in health systems incentivized by throughput and resource utilization metrics.
Report Content and Operational Utility
This market study is engineered to translate macro trends into executable strategy. Beyond the headline sizing and growth projections, the full report delivers a structured operational toolkit that includes:
-
Detailed segmentation analysis covering technology types, clinical applications, and regional demand distributions, with historical trajectory and forecast pathways that support demand planning and revenue modeling.
-
Competitive profiling of leading manufacturers and specialized instrument providers, including product architecture, regulatory status, and strategic moves such as launches, acquisitions, and distribution agreements.
Worldwide Medical Microscopic Hemostatic Clip Market -
Market concentration analysis that clarifies the balance between established incumbent share and the entry space available for differentiated technologies or regional partnerships.
-
Industry context integration covering regulatory classification expectations, quality system certification norms, reimbursement coding developments, and material specifications that influence product design and procurement decisions.
-
Strategic scenario framing that helps leadership teams assess how shifts in procedural adoption, automation adoption, and distribution consolidation may alter competitive positioning across the 2026-2032 period.
Each section is designed to support concrete decisions in product development prioritization, market entry sequencing, pricing architecture, and channel investment. The full publication moves beyond descriptive market characterization into actionable intelligence, enabling teams to benchmark their current positioning against the evolving competitive field and to identify the most defensible growth pathways.
Conclusion: Converting Market Visibility into Strategic Advantage
The Worldwide Medical Microscopic Hemostatic Clip Market is poised for sustained expansion, but the abundance of growth opportunity will reward organizations that can convert market visibility into disciplined execution. The projected 7.2 percent CAGR through 2032, the maturation of automated and rotatable clip platforms, and the ongoing consolidation of distribution rights all point to a market where differentiation increasingly depends on workflow integration, regulatory readiness, and channel control. At the same time, the concentration profile of the competitive field suggests that scale advantages and specialized clinical credibility will continue to influence procurement preferences in high-volume settings.
This preview offers a strategic orientation to the forces shaping the market, but the complete report provides the granular segmentation data, company-level profiling, and scenario-based insights necessary to translate direction into action. For executives preparing 2026 investment decisions, product roadmaps, and market access strategies, the full study functions as a decision-grade intelligence asset, connecting macro momentum to the operational details that determine competitive outcomes.
For detailed analysis of this topic, please visit the official page: Worldwide Medical Microscopic Hemostatic Clip Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Cloud IDS IPS Market to Reach $7,673.83M by 2032, Driven by 15.2% CAGR
By pmarketresearch, 2026-09-16
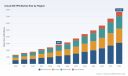
Navigating the Next Wave of Cloud IDS/IPS: Strategic Imperatives for 2026 Decision-Makers
The cloud security landscape is undergoing a structural transformation, driven by expanding attack surfaces, regulatory complexity, and the relentless migration of critical workloads to distributed cloud environments. As organizations move beyond perimeter-centric defense models, Cloud Intrusion Detection and Prevention Systems (IDS/IPS) have become indispensable components of modern security architectures. PW Consulting’s newly released Worldwide Cloud IDS IPS Market research provides a comprehensive, data-grounded view of this evolving ecosystem, offering enterprise leaders, investors, and technology strategists the analytical clarity required to navigate 2026 and beyond.
This market research is designed not merely as a retrospective snapshot, but as a forward-looking strategic compass. By synthesizing historical trajectories, forward-looking projections, competitive positioning, and macro-level industry dynamics, the study equips decision-makers with actionable intelligence to align security investments with broader organizational objectives. The following overview highlights the core analytical dimensions of the report and explains why its insights are particularly critical for strategic planning in the current cycle.
Market Trajectory and the Strategic Value of Forward-Looking Intelligence
The global Cloud IDS/IPS market has demonstrated consistent expansion over the past half-decade, reflecting the accelerating adoption of cloud-native security controls across industries. From 2020 through 2025, the market advanced from approximately USD 1,350 million to USD 2,850 million, signaling robust demand for integrated detection and prevention capabilities that can operate seamlessly across public, private, and hybrid cloud deployments. Looking ahead, the forecast period from 2026 to 2032 outlines a continued growth trajectory, with the market projected to reach USD 3,169.93 million in 2026 and expand to USD 7,673.83 million by 2032. The implied compound annual growth rate of 15.2 percent underscores the sustained momentum behind cloud security investment.
For enterprise strategists, these figures are more than headline metrics. They represent a structural shift in how organizations allocate cybersecurity budgets, prioritize vendor evaluations, and architect defensive layers. A growth environment of this magnitude introduces both opportunity and complexity. Companies that understand the underlying demand drivers, deployment preferences, and concentration patterns within the vendor landscape can position themselves more effectively—whether through procurement strategy, partnership selection, or internal capability development. The report’s forward-looking framework helps leaders anticipate where market weight will shift, how deployment models will evolve, and which organizational segments are likely to drive incremental adoption.
Importantly, the study maintains analytical discipline by emphasizing macro-level market direction without obscuring the need for granular, context-specific decision-making. By presenting overall size evolution, growth rates, and structural breakdowns in a cohesive narrative, the research enables readers to grasp the scale of the opportunity while recognizing that segmentation-level dynamics require deeper exploration. This approach ensures that strategic planning is grounded in credible market sizing while preserving the necessity of access to detailed segmentation data for precise investment and procurement decisions.
Competitive Landscape: Who Is Shaping the Cloud IDS/IPS Ecosystem
The vendor ecosystem surrounding Cloud IDS/IPS is characterized by a blend of established network security incumbents, cloud platform providers, and specialized security innovators. Market concentration metrics indicate that the top three players account for 45.5 percent of market revenue, while the top five collectively represent 62.3 percent, suggesting a moderately consolidated landscape where scale, platform integration, and ecosystem reach confer meaningful advantages. Yet the presence of numerous specialized and emerging participants ensures that differentiation remains possible through technology architecture, deployment flexibility, and domain-specific threat intelligence.
Cisco Systems continues to anchor its offering around cloud-native and hybrid Cloud IDS/IPS solutions integrated with its Secure Firewall portfolio and broader cloud security platforms, targeting threat detection and prevention across public, private, and hybrid environments. Fortinet emphasizes scalable cloud network security through FortiGate Cloud and cloud-delivered IPS/IDS capabilities, leveraging AI-driven threat intelligence to support organizations seeking unified protection across distributed infrastructures. Trend Micro focuses on Cloud IPS and HIPS solutions, including managed rule groups designed to simplify AWS Cloud IPS deployments and enable automated threat prevention. Palo Alto Networks positions Prisma Cloud as a comprehensive cloud workload and network threat detection platform with integrated IDS/IPS functionalities, appealing to enterprises seeking consolidated cloud security controls.
Check Point Software Technologies contributes Quantum Cloud and Infinity platform solutions with advanced Cloud IPS/IDS designed for threat prevention across heterogeneous cloud environments. CrowdStrike extends behavioral-based threat detection and prevention through Falcon Cloud Security, with capabilities that reach into cloud IDS/IPS functions and support organizations prioritizing identity- and behavior-centric security models. Zscaler delivers Cloud IPS as part of its Zero Trust Exchange platform, emphasizing inline, cloud-native intrusion prevention across all traffic flows. IBM Security offers managed Cloud IDS/IPS services integrated with IBM Cloud and hybrid environments, using AI to enhance threat detection and operational response. Microsoft provides Defender for Cloud with IDPS capabilities for Azure and multi-cloud environments, combining threat intelligence and anomaly detection within a widely adopted enterprise ecosystem.
Cloud platform providers also play a pivotal role. Amazon Web Services supports intelligent threat detection through GuardDuty and enables partner Cloud IPS solutions such as Trend Micro for network-level protection within AWS environments. Google Cloud offers Cloud IDS for cloud-native network threat detection, including identification of malware, spyware, and command-and-control attacks. Juniper Networks delivers cloud-delivered and virtual IDS/IPS solutions integrated with SRX firewalls and SD-WAN, supporting organizations that prioritize network-centric security architectures. Sophos incorporates cloud-based IDS/IPS capabilities within its Managed Detection and Response and intercept solutions, targeting cloud workloads with managed service-oriented approaches.
Worldwide Cloud IDS IPS Market
Recent developments illustrate how rapidly this competitive field is evolving. In November 2025, Trend Micro partnered with AWS to offer one-click TrendAI managed rule groups for Cloud IPS and HIPS in the AWS Marketplace, enabling automated threat prevention without requiring extensive manual rule management. Earlier, in March 2025, Deutsche Telekom’s Open Telekom Cloud introduced a cloud firewall with integrated IDS and IPS capabilities designed to secure both north-south and east-west traffic through real-time detection and prevention. These moves reflect broader industry trends toward automation, marketplace-enabled deployment, and tighter integration between cloud infrastructure and security controls.
Understanding these competitive dynamics is essential for organizations evaluating vendor relationships, assessing integration pathways, and anticipating shifts in feature prioritization. The report’s competitive analysis section provides structured profiles and contextual evaluation frameworks that help readers compare offerings not only by feature lists, but by deployment philosophy, ecosystem compatibility, and strategic alignment with organizational cloud roadmaps.
Worldwide Cloud VPN Market
Deployment Models, Organizational Segments, and the Regional Dimension
The market’s structure reflects a balanced but evolving split between deployment approaches. Public cloud deployments represent a substantial share of market activity, while private and hybrid cloud configurations remain highly relevant for organizations with stringent data handling requirements, legacy integration needs, or regulatory constraints. This dual trajectory indicates that Cloud IDS/IPS solutions must be evaluated not only on cloud-native performance, but also on their ability to interoperate across heterogeneous environments and support consistent policy enforcement.
Organizational size further shapes adoption patterns. Large enterprises constitute a significant portion of market demand, driven by complex multi-cloud strategies, scale-sensitive threat landscapes, and the need for centralized visibility across distributed assets. At the same time, small and medium enterprises represent a meaningful and growing segment, as cloud security becomes more accessible through managed services, marketplace deployments, and simplified rule management. The report explores how these organizational segments differ in procurement behavior, operational maturity, and technology expectations, providing context for both vendors seeking to refine go-to-market strategies and enterprises planning security transformations.
Regionally, the market spans multiple geographies with differing regulatory environments, cloud adoption maturity, and infrastructure constraints. North America, Europe, Asia Pacific, and Rest of World each present distinct demand characteristics shaped by local cloud ecosystems, compliance frameworks, and security vendor presence. The study examines these regional dynamics at a macro level, highlighting how geography influences deployment preferences, certification requirements, and vendor selection criteria. By integrating regional context without oversimplifying local nuances, the research supports more informed multinational planning and region-specific investment prioritization.
Readers seeking precise regional revenue allocations, deployment-model percentages, or organization-size breakdowns will find that the full report provides the detailed segmentation data necessary for granular market entry, forecasting, and competitive benchmarking. This layered approach ensures that executive summaries convey strategic direction while preserving the depth required for operational planning.
Industry Dynamics Shaping Cloud IDS/IPS Demand in 2026
Beyond vendor competition and segmentation patterns, several macro-level dynamics are reshaping the Cloud IDS/IPS market. Energy costs and infrastructure economics are increasingly relevant to cloud security planning. Data center electricity demand surged by 17 percent in 2025, with AI-focused facilities growing even faster, raising operational costs for cloud security infrastructure. In the United States, data center annual energy use reached approximately 176 TWh in 2023, representing 4.4 percent of US electricity, and projections suggest this figure could double or triple by 2028. These trends affect the economics of hosting cloud IDS/IPS workloads, influence provider pricing models, and encourage demand for efficiency-aware security architectures.
Regulatory and certification pathways are also in flux. The US Department of Defense initiated the sunset of the DoDIN Approved Products List program, with testing concluding by December 2025 and repository maintenance continuing into FY 2026. This transition affects certification pathways for cloud security products and introduces new considerations for government-adjacent and regulated-sector buyers. At the same time, data sovereignty laws and cross-border data flow restrictions continue to influence deployment decisions, particularly in regulated industries and regions with strict localization requirements. Organizations must therefore evaluate Cloud IDS/IPS solutions not only on technical performance, but also on their ability to support compliance obligations, data residency expectations, and evolving audit frameworks.
These dynamics reinforce the value of a research perspective that connects market sizing with operational realities. The report incorporates such industry context to help readers understand why demand is shifting, where cost and compliance pressures are most acute, and how vendors and buyers alike are adapting their strategies. By situating market growth within these broader forces, the study provides a more complete foundation for strategic decision-making than a purely revenue-focused analysis could offer.
What the Report Delivers: Practical Intelligence for Strategic Planning
PW Consulting’s Worldwide Cloud IDS IPS Market research is structured to support a wide range of strategic use cases. It combines historical market data, forward-looking projections, segmentation analysis, competitive profiling, and industry-context integration into a single cohesive reference. The report is designed to help organizations answer questions that directly affect planning cycles: how fast is demand expanding, which deployment models are gaining relative traction, where concentration risk lies within the vendor base, and what macro-level factors should be incorporated into budgeting and architecture decisions.
Key components include detailed market size tracking from 2020 through 2032, growth-rate analysis across the forecast period, and structured segmentation views that break down demand by region, deployment model, and organization size. Competitive profiles examine the strategic positioning, solution scope, and recent moves of major participants, while recent development tracking highlights product launches, partnerships, and integration milestones that signal where the market is heading. The inclusion of industry-context factors such as energy economics, regulatory transitions, and data sovereignty considerations ensures that market analysis remains grounded in operational reality.
For executives, procurement leaders, and security architects, the report serves as a decision-support tool that can inform vendor shortlisting, investment prioritization, cloud migration planning, and risk assessment. For investors and market strategists, it offers a structured view of market concentration, growth drivers, and competitive differentiation that can support portfolio evaluation and market-entry analysis. By balancing accessible macro-level insights with the availability of deeper segmentation data, the research is built to guide both high-level strategy and more detailed market-specific planning.
Why This Research Matters for 2026 Decision-Making
The 2026 planning cycle will be shaped by organizations that can align security investment with cloud strategy, regulatory expectations, and operational economics. Cloud IDS/IPS is no longer a peripheral control; it is a central element of threat detection, workload protection, and multi-environment visibility. In a market expanding at a sustained double-digit pace and featuring a competitive mix of network security leaders, cloud platform providers, and specialized innovators, the ability to interpret market structure and vendor positioning becomes a strategic advantage.
This research provides that interpretive foundation. It helps leaders distinguish between short-term feature competition and longer-term architectural value, evaluate where deployment flexibility matters most, and anticipate how regulatory and infrastructure pressures may influence procurement and hosting decisions. By presenting credible market sizing, structured segmentation, and competitive context within a unified analytical framework, the study reduces uncertainty and supports more disciplined planning.
For teams seeking precise regional allocations, deployment-model percentages, organization-size breakdowns, or detailed vendor revenue positioning, the complete report offers the segmentation depth required for targeted action. Engaging with the full dataset enables stakeholders to move from strategic orientation to executable planning with confidence.
Next Steps for Stakeholders Seeking Market Clarity
Organizations preparing for 2026 security budgeting, cloud architecture reviews, or vendor evaluations will benefit from a research asset that connects market growth with competitive and operational context. PW Consulting’s Worldwide Cloud IDS IPS Market study is designed for exactly that purpose: to provide a credible, forward-looking, and practically useful view of where the market stands and where it is headed.
Readers interested in exploring the full segmentation data, detailed vendor profiles, and extended industry-context analysis are encouraged to access the complete report through our official research portal. There, stakeholders can retrieve the granular market breakdowns, regional and deployment-specific figures, and structured competitive assessments needed to translate strategic insight into measurable action.
For detailed analysis of this topic, please visit the official page: Worldwide Cloud IDS IPS Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Subsea Flowlines Market to Reach $6.98B by 2032, Growing at 5.5% CAGR
By pmarketresearch, 2026-09-16
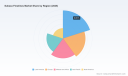
Navigating the Depths: Strategic Imperatives in the Worldwide Subsea Flowlines Market Through 2032
The global offshore energy landscape is undergoing a structural transformation, driven by the relentless pursuit of hydrocarbon reserves in increasingly challenging environments and the parallel emergence of low-carbon subsea applications. As operators push development envelopes into ultra-deepwater regimes and complex pre-salt formations, the subsea flowline sector has evolved from a commoditized infrastructure component into a strategic enabler of project economics and operational resilience. Our latest Worldwide Subsea Flowlines Market research synthesizes historical performance, forward-looking demand trajectories, and competitive maneuvering to provide decision-makers with a rigorous analytical framework for 2026 and beyond.
The Macro Trajectory: Sustained Growth Anchored in Deepwater Expansion
Between 2020 and 2025, the worldwide subsea flowlines market demonstrated consistent upward momentum, expanding from approximately USD 3,673 million to a baseline valuation of USD 4,800 million in 2025. This historical growth phase was characterized by accelerated project sanctioning in Latin American pre-salt basins, sustained EPIC activity across European continental shelves, and renewed exploration commitments in Africa and Asia-Pacific offshore blocks. Looking ahead, our forecast period spanning 2026 through 2032 projects a compound annual growth rate of 5.5 percent, positioning the market to surpass USD 6.98 billion by the terminal year.
This trajectory is not merely a function of volume expansion. The revenue composition is being recalibrated by shifting project architectures that prioritize longer tie-back distances, standardized manufacturing protocols, and integrated subsea production systems. Operators are increasingly willing to absorb higher upfront material and installation costs when lifecycle reliability, flow assurance, and reduced intervention frequency are factored into net present value calculations. Consequently, demand for high-performance rigid pipelines, flexible conduit systems, and specialized composite solutions continues to outpace broader offshore capital expenditure cycles.
Segmentation Dynamics: Material Science, Water Depth, and Regional Shifts
The structural composition of flowline spending reveals distinct operational priorities across project phases and geographic basins. Material selection has become a critical differentiator, with carbon steel maintaining dominant deployment volumes due to its established fabrication infrastructure and cost efficiency in moderately corrosive environments. Simultaneously, flexible pipe systems are capturing disproportionate attention for their installation versatility, fatigue resistance, and suitability for complex tie-back geometries. Composite and alternative material solutions represent a smaller but strategically significant share, particularly in applications requiring specialized thermal insulation or weight reduction for ultra-deepwater tie-backs.
Water depth stratification further illuminates market evolution. Shallow-water applications continue to anchor baseline project activity, particularly in established producing regions where brownfield expansions and subsea tie-backs to existing platforms drive incremental demand. Deepwater segments reflect the bulk of new greenfield investment, supported by advanced rigid flowline engineering and robust EPCI delivery models. Ultra-deepwater deployments, while operationally demanding, command premium value allocation due to specialized coating requirements, high-pressure design envelopes, and the integration of thermally managed pipe-in-pipe configurations.
Regional demand patterns underscore the globalization of offshore development strategies. Latin American basins remain central to large-scale flowline procurement, reinforced by multi-well pre-salt developments and integrated SURF packages. European project pipelines maintain steady activity levels, particularly in mature fields undergoing optimization and new gas-focused developments. The Middle East and Africa region continues to attract major infrastructure commitments, while Asia-Pacific and North American markets exhibit more selective, technology-driven procurement cycles. These regional variations are not uniform; they reflect localized regulatory frameworks, supply chain maturity, and the strategic positioning of global contractors relative to national oil company priorities.
Competitive Architecture: Consolidated Leadership and Specialized Niches
The market exhibits a moderately concentrated competitive landscape, with the top three participants capturing a majority of large-scale EPCI and material supply contracts, and the top five collectively accounting for nearly three-quarters of total market revenue. This concentration reflects the capital intensity of deepwater project delivery, the necessity of integrated engineering expertise, and the risk-sharing requirements inherent in complex flowline installations.
TechnipFMC and Subsea 7 stand as anchor players, leveraging comprehensive design, fabrication, and installation capabilities across rigid and flexible flowline portfolios. Subsea 7's recent engagement on substantial Brazilian pre-salt SURF awards illustrates the scale of contract activity flowing to integrators capable of managing multi-well flowline networks and tie-back architectures. Saipem similarly reinforces its positioning through full EPCI delivery on extensive production flowline systems, with recent major contract wins in South American offshore developments highlighting the importance of regional execution readiness and proprietary installation methodologies.
Aker Solutions contributes a differentiated value proposition through standardized and modular flowline technologies optimized for harsh-environment deployments, often executed through strategic alliances that extend SURF delivery reach. Baker Hughes, including its OneSubsea portfolio, competes across both flexible pipe systems and integrated subsea production architectures, with substantial contract awards for pre-salt flexible pipe deliveries emphasizing the convergence of flowline and production system procurement.
The material supply chain is equally consequential. Tenaris and Vallourec anchor the rigid line pipe segment, providing offshore-grade piping solutions with corrosion-resistant options and premium connection technologies tailored for deepwater and ultra-deepwater applications. Recent contract activity in Brazilian deepwater projects underscores the continued reliance on high-specification seamless pipe and advanced connection systems to meet stringent pressure and corrosion performance thresholds. ITP Interpipe addresses a specialized but growing niche through highly insulated pipe-in-pipe solutions designed for thermal management and flow assurance in extreme temperature conditions, reflecting the industry's broader shift toward engineered flowline architectures that mitigate hydrate formation and viscosity challenges.
Supporting players such as Oceaneering International, Dril-Quip, Prysmian Group, and Nexans complete the ecosystem by delivering critical connection systems, wellhead compatibility solutions, umbilicals, and power cable components that integrate directly with flowline installations. In an environment where tie-back reliability and system interoperability dictate project outcomes, these specialist contributions often determine the difference between marginal and optimized field performance.
Technology Innovation and Market Catalysts Reshaping Procurement Strategies
Flowline demand is being accelerated by several converging industry dynamics. Rising offshore exploration and production investments continue to stimulate procurement for greenfield developments, while demand for subsea tie-backs to existing infrastructure enables cost-effective exploitation of marginal and satellite fields in deepwater regions. This tie-back paradigm reduces surface facility requirements and accelerates time-to-production, but it simultaneously elevates the technical requirements for flowline materials, connection systems, and installation precision.
Regulatory and standards evolution further shapes procurement pathways. Updated international design and operation requirements for subsea production systems, encompassing oil, gas, and low-carbon energy applications, are prompting operators to reevaluate material specifications and verification protocols. Compliance with contemporary standards has become a baseline expectation, reinforcing the advantage of suppliers capable of delivering certified, traceable, and consistently manufactured flowline components.
From a materials standpoint, clad pipe technologies utilizing corrosion-resistant alloy layers over carbon steel substrates are gaining traction in environments subject to elevated CO₂, H₂S, and high-chloride concentrations. This material evolution addresses long-term integrity concerns without the full cost penalty of solid alloy construction, creating a compelling middle ground for operators balancing CAPEX constraints with lifecycle reliability. Parallel advancements in electrically heat-traced flowlines and insulated pipe-in-pipe systems are extending operational reach by maintaining fluid temperatures across longer tie-backs, directly improving flow assurance and reducing intervention risk. An industry collaborative initiative recently introduced next-generation subsea flowline heating technology that enables cable installation after pipeline laying, offering tangible reductions in installation complexity, cost, and emissions footprint.
Strategic Value for 2026 Decision-Making
For executives navigating capital allocation, vendor selection, and long-term project planning, this market research delivers actionable intelligence across multiple decision dimensions. The forecast framework enables scenario modeling for flowline procurement budgets, allowing operators and contractors to align procurement timelines with anticipated contract award cycles and installation vessel availability. The segmentation analysis clarifies where material and depth-specific demand is expanding fastest, supporting targeted investment in fabrication capacity, coating facilities, and specialized connection technologies. Competitive profiling illuminates execution risk, regional capability gaps, and partnership opportunities, particularly for organizations seeking to optimize EPCI consortia or secure resilient supply chains for high-specification pipe and flexible conduit systems.
The report also integrates recent contract developments and technology milestones into a forward-looking context, helping stakeholders distinguish between transient project spikes and structural demand shifts. By contextualizing major awards in Brazilian pre-salt developments, South American SURF packages, and European and African infrastructure commitments, the analysis provides a realistic benchmark for contract sizing, delivery sequencing, and market share dynamics. For material suppliers, the research highlights converging pressure on corrosion mitigation, thermal management, and premium connection performance, reinforcing the strategic importance of differentiated manufacturing capabilities and certification readiness.
What the Report Delivers
This comprehensive study is structured to support both strategic planning and operational execution. It provides a rigorous historical assessment covering the 2020 through 2025 period, establishing a defensible baseline against which forward projections can be evaluated. The forecast model extends through 2032, incorporating macroeconomic indicators, offshore investment cycles, and technology adoption patterns that influence flowline procurement rates. Segmentation analysis examines material categories, water depth classifications, and regional distribution without exposing sensitive contract-level granularity, enabling readers to understand demand architecture while preserving the analytical depth necessary for competitive benchmarking.
The competitive landscape section profiles leading integrators, pipe manufacturers, connection specialists, and umbilicals and cable providers, detailing headquarters positioning, service portfolios, and recent contract activity. These profiles are accompanied by a curated set of recent industry developments, including major award announcements, collaborative technology initiatives, and standards updates that directly affect flowline design, installation, and lifecycle management. Supplementary context addresses raw material trends, regulatory evolution, and macro-level offshore investment dynamics, ensuring that decision-makers can interpret market size and growth figures within a broader operational and policy environment.
Accessing the Full Intelligence Architecture
The Worldwide Subsea Flowlines Market research is designed as a decision-grade intelligence asset. While this overview establishes the strategic contours of market expansion, competitive concentration, and technology-driven demand drivers, the complete report contains detailed segmentation breakdowns, granular regional and material-level revenue trajectories, company-specific market share estimations, and forward-looking contract pipeline indicators that transform high-level trends into executable strategy. For organizations seeking to optimize procurement timing, evaluate partnership structures, or position manufacturing and service capabilities against evolving deepwater and ultra-deepwater requirements, the full analysis provides the granularity required to convert market insight into competitive advantage.
As offshore development continues to push into more complex geological and operational territories, the subsea flowline sector will remain a critical determinant of project economics, delivery certainty, and long-term integrity. Our research equips stakeholders with the analytical foundation to navigate that complexity with confidence throughout 2026 and the decade ahead.
Worldwide Subsea Flowlines Market
Worldwide Subsea Sensors Market
For detailed analysis of this topic, please visit the official page: Worldwide Subsea Flowlines Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting NVH Market Hits $14.19B in 2025; Forecast 5.85% CAGR to $21.12B by 2032
By pmarketresearch, 2026-09-16
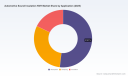
Unlocking Acoustic Excellence: Strategic Imperatives in the Automotive Sound Insulation NVH Market Through 2032
The automotive industry is undergoing a profound transformation where noise, vibration, and harshness (NVH) management has evolved from a secondary comfort feature to a critical determinant of brand value, regulatory compliance, and vehicle performance. As electrification reshapes powertrain acoustics and stringent global regulations tighten noise emission thresholds, the demand for advanced sound insulation materials and solutions has entered a new phase of accelerated growth. Our latest market research report on the Automotive Sound Insulation NVH Market provides a comprehensive, data-driven blueprint for navigating this dynamic landscape, offering enterprise decision-makers the precise intelligence required to secure competitive advantage in the coming decade.
Drawing on extensive primary research, cross-validated industry datasets, and forward-looking modeling, this study captures the full trajectory of market evolution from historical baselines through a robust forecast horizon extending to 2032. The analysis is anchored in verified market sizing that reflects sustained momentum across the value chain. Building on a foundation that surpassed the 14,000 million USD threshold in the base year, the market is projected to reach new highs by the end of the forecast period, driven by material innovation, regional manufacturing expansion, and the relentless pursuit of cabin refinement. A compound annual growth rate of 5.85 percent underscores a resilient, structurally supported expansion path that rewards organizations capable of aligning product portfolios, supply chain strategies, and partnership ecosystems with emerging acoustic demands.
The Strategic Imperative for 2026 Decision-Making
As organizations step into 2026, the window for proactive positioning is narrowing. Multiple regulatory milestones, technology transitions, and shifting consumer expectations are converging to redefine competitive benchmarks. Enterprise leaders must move beyond incremental product updates and embrace holistic acoustic strategies that integrate material science, vehicle architecture, and sustainability mandates. This report is engineered to support precisely that transition. It moves past surface-level trend descriptions to deliver actionable frameworks that guide capital allocation, sourcing decisions, R&D prioritization, and market entry or expansion strategies.
The study is particularly timely given the phased implementation of stricter acoustic regulations across major markets. Regulatory bodies are tightening permissible noise limits for passenger cars, vans, buses, and commercial trucks, with additional reductions becoming applicable in the 2026 timeframe. Simultaneously, updated testing protocols and urban noise weighting standards are raising the bar for certification, compelling manufacturers to incorporate higher-performance absorption, damping, and insulation materials earlier in the design cycle. These dynamics do not merely create compliance pressure; they open pathways for differentiated acoustic engineering, lightweight material substitution, and premium cabin positioning. Decision-makers who understand where these regulatory tailwinds intersect with consumer willingness to pay will be best positioned to convert acoustic performance into measurable commercial value.
Market Architecture and Growth Catalysts
The market structure reflects a mature yet rapidly evolving ecosystem in which material diversity, application specificity, and regional manufacturing footprints interact to shape competitive outcomes. Our analysis examines how acoustic absorption, vibration damping, and thermal-acoustic insulation categories command distinct demand profiles across vehicle segments. Each application domain carries unique engineering constraints, cost tolerances, and performance thresholds, and the report maps these nuances to help stakeholders identify high-return development areas rather than pursuing undifferentiated material proliferation.
Material innovation continues to act as a primary growth catalyst. The industry is witnessing accelerated adoption of advanced elastomers, microcellular polyurethanes, engineered foams, fiber-based assemblies, and mono-material architectures designed for easier recycling and improved acoustic efficiency. Lightweight acoustic components are no longer optional extras; they are integral to achieving range optimization in electric vehicles while maintaining or enhancing interior quietness. The report details how these material shifts interact with procurement economics, production scalability, and end-of-life sustainability requirements, enabling organizations to forecast cost structures and evaluate substitution scenarios with greater confidence.
Regional manufacturing capability and localized supply resilience also play decisive roles in market dynamics. Demand concentration varies significantly across geographies, reflecting differences in vehicle production volumes, regulatory timelines, and consumer expectations for cabin refinement. The analysis highlights how leading production hubs and emerging assembly regions are reshaping sourcing strategies, inventory planning, and logistics optimization. Rather than presenting static regional snapshots, the study connects geographic demand patterns to operational implications, including supplier proximity, tariff exposure, and the strategic balancing of global material standards with local performance specifications.
Competitive Landscape: The Architects of Acoustic Performance
The competitive environment is defined by a concentrated group of globally established players who combine material science expertise, application engineering capabilities, and deep vehicle integration experience. Market concentration data indicates that the top three competitors collectively hold a notable share of the landscape, while the leading five firms account for a majority of industry activity. This structure signals an environment where scale, proprietary formulations, and long-term OEM relationships create meaningful barriers to entry, yet it also reveals opportunities for specialized innovators who can deliver differentiated acoustic performance, sustainability credentials, or cost-optimized integration solutions.
Autoneum Holding AG continues to reinforce its position as a global leader in acoustic and thermal management, with a strong emphasis on lightweight fiber-based NVH components and high recycled content formulations. Its recent engagement at the Automotive Acoustics Conference 2025 highlighted ongoing focus on body and powertrain NVH, lightweight acoustic construction, and sustainable material pathways for electric vehicles. At IAA Mobility 2025, the company showcased a portfolio of sustainable NVH solutions, including mono-material carpet systems and advanced fiber-based shielding technologies, signaling a clear strategic commitment to circular design and acoustic efficiency in tandem.
BASF SE maintains a powerful presence through its microcellular polyurethane elastomers and engineered foam systems, which are widely utilized for chassis components, engine mounts, and acoustic insulation applications demanding superior vibration control. 3M Company extends its reputation for material versatility with Thinsulate acoustic insulation, Flexile Acoustic Material, and a broader suite of dampening solutions tailored to sound absorption and lightweight interior noise control. The Dow Chemical Company contributes specialized polyurethane acoustic foams, polyolefin elastomers, and cavity-filling systems that enable customized NVH dampening across varied vehicle architectures.
Vibracoustic SE has carved out a specialized strength in NVH components such as mounts, air springs, bushings, and decoupling systems, with a growing emphasis on electric vehicle powertrain noise and vibration control. Its recent application work on premium electric pickup platforms demonstrates how advanced hydro bushings and air spring systems can elevate both comfort and performance characteristics. Sumitomo Riko Company Limited brings deep expertise in rubber-based and polymer NVH materials, mounts, and insulators, reinforcing Japan's sustained influence in precision vibration management. Henkel AG & Co. KGaA adds value through adhesive dampers, structural reinforcements, and lightweight composite materials that support vibration damping and acoustic performance without compromising design flexibility. ElringKlinger AG rounds out the competitive field with focused offerings in sealing, shielding, and acoustic management for powertrain and interior environments. Together, these players illustrate a market where differentiation arises from formulation IP, application-specific engineering, and the ability to meet evolving sustainability and weight-reduction mandates simultaneously.
Regulatory and Technology Dynamics Shaping the Road Ahead
Regulatory evolution remains one of the most powerful forces reordering NVH investment priorities. The progressive tightening of noise limits, combined with mandatory testing updates that introduce revised urban noise weighting and high-load evaluation procedures, is pushing manufacturers to treat acoustic performance as a design-phase requirement rather than a late-stage adjustment. Compliance is increasingly tied to material selection, structural damping strategies, and integrated insulation architectures. Organizations that anticipate these requirements can reduce rework risk, accelerate validation cycles, and build regulatory readiness into their product roadmaps.
Worldwide Automotive Noise, Vibration, and Harshness Materials Market
At the same time, electrification is altering the acoustic signature of the vehicle fleet. While electric powertrains eliminate many traditional engine noise sources, they amplify the relative importance of road noise, wind noise, tire-contact acoustics, and ancillary system vibrations. This shift requires a more refined balance between absorption, damping, and insulation materials, as well as greater attention to cavity treatment, floor insulation, and inner dash assemblies. The report evaluates how these technology-driven changes influence material demand patterns, testing protocols, and the competitive positioning of suppliers that can deliver holistic acoustic packages rather than single-function components.
Sustainability is no longer a peripheral consideration; it is increasingly embedded in procurement criteria and product approval processes. Recycled content, mono-material designs, reduced VOC emissions, and recyclable acoustic assemblies are becoming prerequisites for supplier selection in many programs. The convergence of acoustic performance and environmental responsibility creates both complexity and opportunity. Companies that can demonstrate verified sustainability metrics alongside measurable NVH improvement will be able to command stronger value propositions and longer-term program security.
What This Report Delivers: Operational Intelligence for Execution
This study is structured to support practical, high-stakes decision-making across R&D, procurement, strategy, and commercial teams. It provides a rigorous segmentation analysis that clarifies how material types, application functions, and regional demand patterns interact to shape market opportunities. Rather than offering broad directional commentary, the report connects each segment to specific operational implications, including development focus areas, sourcing considerations, and go-to-market prioritization.
The competitive assessment goes beyond corporate profiles to examine strategic positioning, technology emphasis, partnership activity, and product showcase behavior observed across recent industry events and program disclosures. By linking these activities to underlying market forces, the analysis helps readers interpret where incumbents are reinforcing their strengths, where they are extending into adjacent capabilities, and where gaps may exist for new or differentiated offerings. Recent conference participation, trade show innovation showcases, and targeted program applications are contextualized as indicators of strategic intent and technological direction, giving readers a current view of how leading players are shaping the next generation of NVH solutions.
The forecast methodology is designed to support scenario planning and investment timing. It integrates historical performance trends with forward-looking assumptions about regulatory adoption, vehicle platform transitions, material substitution rates, and regional production shifts. This framework allows decision-makers to evaluate demand trajectories under varying conditions, test the resilience of product portfolios, and identify inflection points where early action can generate disproportionate returns. The report also provides a structured view of market concentration dynamics, helping stakeholders understand the degree of competitive crowding, the influence of leading suppliers, and the strategic implications for pricing, negotiation leverage, and partnership design.
Automotive Sound Insulation NVH Market
To bridge analysis and execution, the study includes actionable recommendations for material portfolio optimization, supplier engagement strategies, program targeting, and sustainability alignment. It is intended to serve as a reference point for evaluating new product initiatives, prioritizing development resources, and assessing the commercial viability of acoustic solutions in specific vehicle segments. By grounding strategic recommendations in disciplined data analysis, the report enables organizations to move from observation to action with confidence.
Positioning for the Next Wave of Acoustic Innovation
The Automotive Sound Insulation NVH Market is entering a phase where success will depend on the ability to integrate acoustic engineering, material performance, regulatory foresight, and sustainability commitments into a coherent commercial strategy. Organizations that treat NVH as a cross-functional value driver rather than a component-level specification will be better equipped to win program approval, differentiate cabin experience, and secure long-term supplier relevance. This report is built to provide the intelligence foundation required for that strategic shift.
Detailed segmentation breakdowns, granular regional and application-level revenue estimates, competitive share analyses, and forward scenario modeling are presented in the full report for teams that require complete decision-grade intelligence. Readers seeking the comprehensive data architecture, segment-level forecasts, and operational playbooks necessary to shape 2026 planning cycles are encouraged to access the complete study through our official report page. There, the full depth of market sizing, segmentation insights, competitive assessments, and strategic recommendations is available to support precise, evidence-based action across the automotive acoustic value chain.
For detailed analysis of this topic, please visit the official page: Automotive Sound Insulation NVH Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com