

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting NVH Market Hits $14.19B in 2025; Forecast 5.85% CAGR to $21.12B by 2032

Unlocking Acoustic Excellence: Strategic Imperatives in the Automotive Sound Insulation NVH Market Through 2032
The automotive industry is undergoing a profound transformation where noise, vibration, and harshness (NVH) management has evolved from a secondary comfort feature to a critical determinant of brand value, regulatory compliance, and vehicle performance. As electrification reshapes powertrain acoustics and stringent global regulations tighten noise emission thresholds, the demand for advanced sound insulation materials and solutions has entered a new phase of accelerated growth. Our latest market research report on the Automotive Sound Insulation NVH Market provides a comprehensive, data-driven blueprint for navigating this dynamic landscape, offering enterprise decision-makers the precise intelligence required to secure competitive advantage in the coming decade.
Drawing on extensive primary research, cross-validated industry datasets, and forward-looking modeling, this study captures the full trajectory of market evolution from historical baselines through a robust forecast horizon extending to 2032. The analysis is anchored in verified market sizing that reflects sustained momentum across the value chain. Building on a foundation that surpassed the 14,000 million USD threshold in the base year, the market is projected to reach new highs by the end of the forecast period, driven by material innovation, regional manufacturing expansion, and the relentless pursuit of cabin refinement. A compound annual growth rate of 5.85 percent underscores a resilient, structurally supported expansion path that rewards organizations capable of aligning product portfolios, supply chain strategies, and partnership ecosystems with emerging acoustic demands.
The Strategic Imperative for 2026 Decision-Making
As organizations step into 2026, the window for proactive positioning is narrowing. Multiple regulatory milestones, technology transitions, and shifting consumer expectations are converging to redefine competitive benchmarks. Enterprise leaders must move beyond incremental product updates and embrace holistic acoustic strategies that integrate material science, vehicle architecture, and sustainability mandates. This report is engineered to support precisely that transition. It moves past surface-level trend descriptions to deliver actionable frameworks that guide capital allocation, sourcing decisions, R&D prioritization, and market entry or expansion strategies.
The study is particularly timely given the phased implementation of stricter acoustic regulations across major markets. Regulatory bodies are tightening permissible noise limits for passenger cars, vans, buses, and commercial trucks, with additional reductions becoming applicable in the 2026 timeframe. Simultaneously, updated testing protocols and urban noise weighting standards are raising the bar for certification, compelling manufacturers to incorporate higher-performance absorption, damping, and insulation materials earlier in the design cycle. These dynamics do not merely create compliance pressure; they open pathways for differentiated acoustic engineering, lightweight material substitution, and premium cabin positioning. Decision-makers who understand where these regulatory tailwinds intersect with consumer willingness to pay will be best positioned to convert acoustic performance into measurable commercial value.
Market Architecture and Growth Catalysts
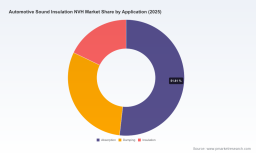
The market structure reflects a mature yet rapidly evolving ecosystem in which material diversity, application specificity, and regional manufacturing footprints interact to shape competitive outcomes. Our analysis examines how acoustic absorption, vibration damping, and thermal-acoustic insulation categories command distinct demand profiles across vehicle segments. Each application domain carries unique engineering constraints, cost tolerances, and performance thresholds, and the report maps these nuances to help stakeholders identify high-return development areas rather than pursuing undifferentiated material proliferation.
Material innovation continues to act as a primary growth catalyst. The industry is witnessing accelerated adoption of advanced elastomers, microcellular polyurethanes, engineered foams, fiber-based assemblies, and mono-material architectures designed for easier recycling and improved acoustic efficiency. Lightweight acoustic components are no longer optional extras; they are integral to achieving range optimization in electric vehicles while maintaining or enhancing interior quietness. The report details how these material shifts interact with procurement economics, production scalability, and end-of-life sustainability requirements, enabling organizations to forecast cost structures and evaluate substitution scenarios with greater confidence.
Regional manufacturing capability and localized supply resilience also play decisive roles in market dynamics. Demand concentration varies significantly across geographies, reflecting differences in vehicle production volumes, regulatory timelines, and consumer expectations for cabin refinement. The analysis highlights how leading production hubs and emerging assembly regions are reshaping sourcing strategies, inventory planning, and logistics optimization. Rather than presenting static regional snapshots, the study connects geographic demand patterns to operational implications, including supplier proximity, tariff exposure, and the strategic balancing of global material standards with local performance specifications.
Competitive Landscape: The Architects of Acoustic Performance
The competitive environment is defined by a concentrated group of globally established players who combine material science expertise, application engineering capabilities, and deep vehicle integration experience. Market concentration data indicates that the top three competitors collectively hold a notable share of the landscape, while the leading five firms account for a majority of industry activity. This structure signals an environment where scale, proprietary formulations, and long-term OEM relationships create meaningful barriers to entry, yet it also reveals opportunities for specialized innovators who can deliver differentiated acoustic performance, sustainability credentials, or cost-optimized integration solutions.
Autoneum Holding AG continues to reinforce its position as a global leader in acoustic and thermal management, with a strong emphasis on lightweight fiber-based NVH components and high recycled content formulations. Its recent engagement at the Automotive Acoustics Conference 2025 highlighted ongoing focus on body and powertrain NVH, lightweight acoustic construction, and sustainable material pathways for electric vehicles. At IAA Mobility 2025, the company showcased a portfolio of sustainable NVH solutions, including mono-material carpet systems and advanced fiber-based shielding technologies, signaling a clear strategic commitment to circular design and acoustic efficiency in tandem.
BASF SE maintains a powerful presence through its microcellular polyurethane elastomers and engineered foam systems, which are widely utilized for chassis components, engine mounts, and acoustic insulation applications demanding superior vibration control. 3M Company extends its reputation for material versatility with Thinsulate acoustic insulation, Flexile Acoustic Material, and a broader suite of dampening solutions tailored to sound absorption and lightweight interior noise control. The Dow Chemical Company contributes specialized polyurethane acoustic foams, polyolefin elastomers, and cavity-filling systems that enable customized NVH dampening across varied vehicle architectures.
Vibracoustic SE has carved out a specialized strength in NVH components such as mounts, air springs, bushings, and decoupling systems, with a growing emphasis on electric vehicle powertrain noise and vibration control. Its recent application work on premium electric pickup platforms demonstrates how advanced hydro bushings and air spring systems can elevate both comfort and performance characteristics. Sumitomo Riko Company Limited brings deep expertise in rubber-based and polymer NVH materials, mounts, and insulators, reinforcing Japan's sustained influence in precision vibration management. Henkel AG & Co. KGaA adds value through adhesive dampers, structural reinforcements, and lightweight composite materials that support vibration damping and acoustic performance without compromising design flexibility. ElringKlinger AG rounds out the competitive field with focused offerings in sealing, shielding, and acoustic management for powertrain and interior environments. Together, these players illustrate a market where differentiation arises from formulation IP, application-specific engineering, and the ability to meet evolving sustainability and weight-reduction mandates simultaneously.
Regulatory and Technology Dynamics Shaping the Road Ahead
Regulatory evolution remains one of the most powerful forces reordering NVH investment priorities. The progressive tightening of noise limits, combined with mandatory testing updates that introduce revised urban noise weighting and high-load evaluation procedures, is pushing manufacturers to treat acoustic performance as a design-phase requirement rather than a late-stage adjustment. Compliance is increasingly tied to material selection, structural damping strategies, and integrated insulation architectures. Organizations that anticipate these requirements can reduce rework risk, accelerate validation cycles, and build regulatory readiness into their product roadmaps.
Worldwide Automotive Noise, Vibration, and Harshness Materials Market
At the same time, electrification is altering the acoustic signature of the vehicle fleet. While electric powertrains eliminate many traditional engine noise sources, they amplify the relative importance of road noise, wind noise, tire-contact acoustics, and ancillary system vibrations. This shift requires a more refined balance between absorption, damping, and insulation materials, as well as greater attention to cavity treatment, floor insulation, and inner dash assemblies. The report evaluates how these technology-driven changes influence material demand patterns, testing protocols, and the competitive positioning of suppliers that can deliver holistic acoustic packages rather than single-function components.
Sustainability is no longer a peripheral consideration; it is increasingly embedded in procurement criteria and product approval processes. Recycled content, mono-material designs, reduced VOC emissions, and recyclable acoustic assemblies are becoming prerequisites for supplier selection in many programs. The convergence of acoustic performance and environmental responsibility creates both complexity and opportunity. Companies that can demonstrate verified sustainability metrics alongside measurable NVH improvement will be able to command stronger value propositions and longer-term program security.
What This Report Delivers: Operational Intelligence for Execution
This study is structured to support practical, high-stakes decision-making across R&D, procurement, strategy, and commercial teams. It provides a rigorous segmentation analysis that clarifies how material types, application functions, and regional demand patterns interact to shape market opportunities. Rather than offering broad directional commentary, the report connects each segment to specific operational implications, including development focus areas, sourcing considerations, and go-to-market prioritization.
The competitive assessment goes beyond corporate profiles to examine strategic positioning, technology emphasis, partnership activity, and product showcase behavior observed across recent industry events and program disclosures. By linking these activities to underlying market forces, the analysis helps readers interpret where incumbents are reinforcing their strengths, where they are extending into adjacent capabilities, and where gaps may exist for new or differentiated offerings. Recent conference participation, trade show innovation showcases, and targeted program applications are contextualized as indicators of strategic intent and technological direction, giving readers a current view of how leading players are shaping the next generation of NVH solutions.
The forecast methodology is designed to support scenario planning and investment timing. It integrates historical performance trends with forward-looking assumptions about regulatory adoption, vehicle platform transitions, material substitution rates, and regional production shifts. This framework allows decision-makers to evaluate demand trajectories under varying conditions, test the resilience of product portfolios, and identify inflection points where early action can generate disproportionate returns. The report also provides a structured view of market concentration dynamics, helping stakeholders understand the degree of competitive crowding, the influence of leading suppliers, and the strategic implications for pricing, negotiation leverage, and partnership design.
Automotive Sound Insulation NVH Market
To bridge analysis and execution, the study includes actionable recommendations for material portfolio optimization, supplier engagement strategies, program targeting, and sustainability alignment. It is intended to serve as a reference point for evaluating new product initiatives, prioritizing development resources, and assessing the commercial viability of acoustic solutions in specific vehicle segments. By grounding strategic recommendations in disciplined data analysis, the report enables organizations to move from observation to action with confidence.
Positioning for the Next Wave of Acoustic Innovation
The Automotive Sound Insulation NVH Market is entering a phase where success will depend on the ability to integrate acoustic engineering, material performance, regulatory foresight, and sustainability commitments into a coherent commercial strategy. Organizations that treat NVH as a cross-functional value driver rather than a component-level specification will be better equipped to win program approval, differentiate cabin experience, and secure long-term supplier relevance. This report is built to provide the intelligence foundation required for that strategic shift.
Detailed segmentation breakdowns, granular regional and application-level revenue estimates, competitive share analyses, and forward scenario modeling are presented in the full report for teams that require complete decision-grade intelligence. Readers seeking the comprehensive data architecture, segment-level forecasts, and operational playbooks necessary to shape 2026 planning cycles are encouraged to access the complete study through our official report page. There, the full depth of market sizing, segmentation insights, competitive assessments, and strategic recommendations is available to support precise, evidence-based action across the automotive acoustic value chain.
For detailed analysis of this topic, please visit the official page: Automotive Sound Insulation NVH Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com