

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Global Subsea Flowlines Market to Reach $6.98B by 2032, Growing at 5.5% CAGR

Navigating the Depths: Strategic Imperatives in the Worldwide Subsea Flowlines Market Through 2032
The global offshore energy landscape is undergoing a structural transformation, driven by the relentless pursuit of hydrocarbon reserves in increasingly challenging environments and the parallel emergence of low-carbon subsea applications. As operators push development envelopes into ultra-deepwater regimes and complex pre-salt formations, the subsea flowline sector has evolved from a commoditized infrastructure component into a strategic enabler of project economics and operational resilience. Our latest Worldwide Subsea Flowlines Market research synthesizes historical performance, forward-looking demand trajectories, and competitive maneuvering to provide decision-makers with a rigorous analytical framework for 2026 and beyond.
The Macro Trajectory: Sustained Growth Anchored in Deepwater Expansion
Between 2020 and 2025, the worldwide subsea flowlines market demonstrated consistent upward momentum, expanding from approximately USD 3,673 million to a baseline valuation of USD 4,800 million in 2025. This historical growth phase was characterized by accelerated project sanctioning in Latin American pre-salt basins, sustained EPIC activity across European continental shelves, and renewed exploration commitments in Africa and Asia-Pacific offshore blocks. Looking ahead, our forecast period spanning 2026 through 2032 projects a compound annual growth rate of 5.5 percent, positioning the market to surpass USD 6.98 billion by the terminal year.
This trajectory is not merely a function of volume expansion. The revenue composition is being recalibrated by shifting project architectures that prioritize longer tie-back distances, standardized manufacturing protocols, and integrated subsea production systems. Operators are increasingly willing to absorb higher upfront material and installation costs when lifecycle reliability, flow assurance, and reduced intervention frequency are factored into net present value calculations. Consequently, demand for high-performance rigid pipelines, flexible conduit systems, and specialized composite solutions continues to outpace broader offshore capital expenditure cycles.
Segmentation Dynamics: Material Science, Water Depth, and Regional Shifts
The structural composition of flowline spending reveals distinct operational priorities across project phases and geographic basins. Material selection has become a critical differentiator, with carbon steel maintaining dominant deployment volumes due to its established fabrication infrastructure and cost efficiency in moderately corrosive environments. Simultaneously, flexible pipe systems are capturing disproportionate attention for their installation versatility, fatigue resistance, and suitability for complex tie-back geometries. Composite and alternative material solutions represent a smaller but strategically significant share, particularly in applications requiring specialized thermal insulation or weight reduction for ultra-deepwater tie-backs.
Water depth stratification further illuminates market evolution. Shallow-water applications continue to anchor baseline project activity, particularly in established producing regions where brownfield expansions and subsea tie-backs to existing platforms drive incremental demand. Deepwater segments reflect the bulk of new greenfield investment, supported by advanced rigid flowline engineering and robust EPCI delivery models. Ultra-deepwater deployments, while operationally demanding, command premium value allocation due to specialized coating requirements, high-pressure design envelopes, and the integration of thermally managed pipe-in-pipe configurations.
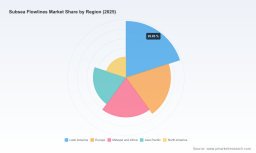
Regional demand patterns underscore the globalization of offshore development strategies. Latin American basins remain central to large-scale flowline procurement, reinforced by multi-well pre-salt developments and integrated SURF packages. European project pipelines maintain steady activity levels, particularly in mature fields undergoing optimization and new gas-focused developments. The Middle East and Africa region continues to attract major infrastructure commitments, while Asia-Pacific and North American markets exhibit more selective, technology-driven procurement cycles. These regional variations are not uniform; they reflect localized regulatory frameworks, supply chain maturity, and the strategic positioning of global contractors relative to national oil company priorities.
Competitive Architecture: Consolidated Leadership and Specialized Niches
The market exhibits a moderately concentrated competitive landscape, with the top three participants capturing a majority of large-scale EPCI and material supply contracts, and the top five collectively accounting for nearly three-quarters of total market revenue. This concentration reflects the capital intensity of deepwater project delivery, the necessity of integrated engineering expertise, and the risk-sharing requirements inherent in complex flowline installations.
TechnipFMC and Subsea 7 stand as anchor players, leveraging comprehensive design, fabrication, and installation capabilities across rigid and flexible flowline portfolios. Subsea 7's recent engagement on substantial Brazilian pre-salt SURF awards illustrates the scale of contract activity flowing to integrators capable of managing multi-well flowline networks and tie-back architectures. Saipem similarly reinforces its positioning through full EPCI delivery on extensive production flowline systems, with recent major contract wins in South American offshore developments highlighting the importance of regional execution readiness and proprietary installation methodologies.
Aker Solutions contributes a differentiated value proposition through standardized and modular flowline technologies optimized for harsh-environment deployments, often executed through strategic alliances that extend SURF delivery reach. Baker Hughes, including its OneSubsea portfolio, competes across both flexible pipe systems and integrated subsea production architectures, with substantial contract awards for pre-salt flexible pipe deliveries emphasizing the convergence of flowline and production system procurement.
The material supply chain is equally consequential. Tenaris and Vallourec anchor the rigid line pipe segment, providing offshore-grade piping solutions with corrosion-resistant options and premium connection technologies tailored for deepwater and ultra-deepwater applications. Recent contract activity in Brazilian deepwater projects underscores the continued reliance on high-specification seamless pipe and advanced connection systems to meet stringent pressure and corrosion performance thresholds. ITP Interpipe addresses a specialized but growing niche through highly insulated pipe-in-pipe solutions designed for thermal management and flow assurance in extreme temperature conditions, reflecting the industry's broader shift toward engineered flowline architectures that mitigate hydrate formation and viscosity challenges.
Supporting players such as Oceaneering International, Dril-Quip, Prysmian Group, and Nexans complete the ecosystem by delivering critical connection systems, wellhead compatibility solutions, umbilicals, and power cable components that integrate directly with flowline installations. In an environment where tie-back reliability and system interoperability dictate project outcomes, these specialist contributions often determine the difference between marginal and optimized field performance.
Technology Innovation and Market Catalysts Reshaping Procurement Strategies
Flowline demand is being accelerated by several converging industry dynamics. Rising offshore exploration and production investments continue to stimulate procurement for greenfield developments, while demand for subsea tie-backs to existing infrastructure enables cost-effective exploitation of marginal and satellite fields in deepwater regions. This tie-back paradigm reduces surface facility requirements and accelerates time-to-production, but it simultaneously elevates the technical requirements for flowline materials, connection systems, and installation precision.
Regulatory and standards evolution further shapes procurement pathways. Updated international design and operation requirements for subsea production systems, encompassing oil, gas, and low-carbon energy applications, are prompting operators to reevaluate material specifications and verification protocols. Compliance with contemporary standards has become a baseline expectation, reinforcing the advantage of suppliers capable of delivering certified, traceable, and consistently manufactured flowline components.
From a materials standpoint, clad pipe technologies utilizing corrosion-resistant alloy layers over carbon steel substrates are gaining traction in environments subject to elevated CO₂, H₂S, and high-chloride concentrations. This material evolution addresses long-term integrity concerns without the full cost penalty of solid alloy construction, creating a compelling middle ground for operators balancing CAPEX constraints with lifecycle reliability. Parallel advancements in electrically heat-traced flowlines and insulated pipe-in-pipe systems are extending operational reach by maintaining fluid temperatures across longer tie-backs, directly improving flow assurance and reducing intervention risk. An industry collaborative initiative recently introduced next-generation subsea flowline heating technology that enables cable installation after pipeline laying, offering tangible reductions in installation complexity, cost, and emissions footprint.
Strategic Value for 2026 Decision-Making
For executives navigating capital allocation, vendor selection, and long-term project planning, this market research delivers actionable intelligence across multiple decision dimensions. The forecast framework enables scenario modeling for flowline procurement budgets, allowing operators and contractors to align procurement timelines with anticipated contract award cycles and installation vessel availability. The segmentation analysis clarifies where material and depth-specific demand is expanding fastest, supporting targeted investment in fabrication capacity, coating facilities, and specialized connection technologies. Competitive profiling illuminates execution risk, regional capability gaps, and partnership opportunities, particularly for organizations seeking to optimize EPCI consortia or secure resilient supply chains for high-specification pipe and flexible conduit systems.
The report also integrates recent contract developments and technology milestones into a forward-looking context, helping stakeholders distinguish between transient project spikes and structural demand shifts. By contextualizing major awards in Brazilian pre-salt developments, South American SURF packages, and European and African infrastructure commitments, the analysis provides a realistic benchmark for contract sizing, delivery sequencing, and market share dynamics. For material suppliers, the research highlights converging pressure on corrosion mitigation, thermal management, and premium connection performance, reinforcing the strategic importance of differentiated manufacturing capabilities and certification readiness.
What the Report Delivers
This comprehensive study is structured to support both strategic planning and operational execution. It provides a rigorous historical assessment covering the 2020 through 2025 period, establishing a defensible baseline against which forward projections can be evaluated. The forecast model extends through 2032, incorporating macroeconomic indicators, offshore investment cycles, and technology adoption patterns that influence flowline procurement rates. Segmentation analysis examines material categories, water depth classifications, and regional distribution without exposing sensitive contract-level granularity, enabling readers to understand demand architecture while preserving the analytical depth necessary for competitive benchmarking.
The competitive landscape section profiles leading integrators, pipe manufacturers, connection specialists, and umbilicals and cable providers, detailing headquarters positioning, service portfolios, and recent contract activity. These profiles are accompanied by a curated set of recent industry developments, including major award announcements, collaborative technology initiatives, and standards updates that directly affect flowline design, installation, and lifecycle management. Supplementary context addresses raw material trends, regulatory evolution, and macro-level offshore investment dynamics, ensuring that decision-makers can interpret market size and growth figures within a broader operational and policy environment.
Accessing the Full Intelligence Architecture
The Worldwide Subsea Flowlines Market research is designed as a decision-grade intelligence asset. While this overview establishes the strategic contours of market expansion, competitive concentration, and technology-driven demand drivers, the complete report contains detailed segmentation breakdowns, granular regional and material-level revenue trajectories, company-specific market share estimations, and forward-looking contract pipeline indicators that transform high-level trends into executable strategy. For organizations seeking to optimize procurement timing, evaluate partnership structures, or position manufacturing and service capabilities against evolving deepwater and ultra-deepwater requirements, the full analysis provides the granularity required to convert market insight into competitive advantage.
As offshore development continues to push into more complex geological and operational territories, the subsea flowline sector will remain a critical determinant of project economics, delivery certainty, and long-term integrity. Our research equips stakeholders with the analytical foundation to navigate that complexity with confidence throughout 2026 and the decade ahead.
Worldwide Subsea Flowlines Market
Worldwide Subsea Sensors Market
For detailed analysis of this topic, please visit the official page: Worldwide Subsea Flowlines Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com