

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Global Adult VAD Market to Reach $2.7B by 2032, Driven by 5.81% CAGR

Strategic Intelligence for the Adult VAD Landscape: Why the 2026 Decision-Maker Needs This Report
The global adult ventricular assist device (VAD) market stands at a critical inflection point. As device engineering matures, reimbursement frameworks evolve, and clinical evidence accumulates, the strategic question is no longer whether mechanical circulatory support will expand, but where capital, R&D, and commercial resources should be deployed for maximum return. Our latest Worldwide Adult Ventricular Assist Device Market study delivers the structured intelligence required to answer that question with precision.
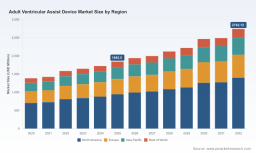
From an investment standpoint, the trajectory is unmistakable. Historical revenue climbed from roughly $1,385.4 million in 2020 to $1,845.5 million by 2025, demonstrating consistent upward momentum even amid regulatory scrutiny and supply chain headwinds. The forecast window projects this expansion to continue, with the market estimated at $1,941.1 million in 2026 and anticipated to reach $2,742.1 million by 2032. This growth path reflects a compound annual growth rate of 5.81 percent across the 2026 to 2032 forecast horizon, signaling a market that is scaling methodically rather than spiking on short-term novelty. For executives planning multi-year roadmaps, that cadence offers a reliable baseline for capacity planning, partnership evaluation, and portfolio positioning.
Worldwide Adult Ventricular Assist Device Market
Yet macro numbers alone do not guide execution. Strategic advantage in this space depends on understanding how demand is distributed across device architectures, clinical indications, and regional ecosystems. The report dissects these structural layers without reducing them to superficial tables. Readers will encounter a rigorous examination of left-sided, right-sided, and biventricular configurations, alongside destination therapy, bridge-to-transplant, and bridge-to-recovery applications. Equally important, the analysis maps regional adoption patterns across North America, Europe, Asia Pacific, and the Rest of World, providing context for where infrastructure maturity, clinical trial activity, and reimbursement readiness intersect. Rather than presenting isolated figures, the study connects these dimensions to operational implications, helping leadership identify which segments justify accelerated investment and which require measured entry or partnership strategies.
The competitive environment demands equally granular attention. The market is tightly concentrated, with the top three firms capturing approximately 88.5 percent of revenue and the top five accounting for 94.2 percent. This structure shapes pricing dynamics, clinical adoption pathways, and the feasibility of new entrant positioning. Abbott Laboratories anchors a significant portion of the landscape through its HeartMate 3 LVAD platform, an FDA-cleared solution for both bridge-to-transplant and destination therapy in adults with advanced heart failure. Recent five-year MOMENTUM 3 trial data, reported in October 2024, demonstrated 58 percent survival free of disabling stroke or transplant, reinforcing the device's clinical narrative and long-term value proposition. Abbott's sustained evidence generation illustrates how clinical credibility translates into durable market positioning.
Competitive Architecture and the Implications of Recent Moves
Medtronic's HeartWare HVAD System remains a historically significant centrifugal flow LVAD used for adult bridge-to-transplant and destination therapy, but the competitive picture is complicated by a Class I recall issued in December 2021. The FDA advisory has effectively constrained new implant recommendations, and ongoing support remains limited, altering the risk calculus for centers evaluating centrifugal platforms. This situation underscores a broader strategic reality: device reliability, post-market surveillance responsiveness, and clinical communication are now inseparable from commercial viability. Firms operating in this segment must navigate not only innovation cycles but also the reputational and operational consequences of field safety actions.
Total Artificial Heart Market
LivaNova PLC has moved aggressively to expand its footprint with the RELINANT VAD, a next-generation centrifugal LVAD designed for adults requiring bridge-to-transplant or bridge-to-recovery support. After securing CE Mark approval for full commercialization in Europe in June 2024, the company has positioned itself to compete more directly in mature European centers while also building the evidence base needed for broader adoption. Berlin Heart GmbH contributes a distinct mechanical profile through the EXCOR Adult VAD, a pneumatically driven external system approved under CE Mark for short- and long-term support in biventricular failure. Its November 2023 launch of a next-generation controller, with improved usability and battery life, demonstrates how incremental engineering improvements can enhance clinician acceptance and patient mobility even within established product categories.
Syncardia Systems rounds out the competitive set with the SynCardia Total Artificial Heart, an FDA-approved bridge-to-transplant option for adults with biventricular failure who are not candidates for VAD support. This total artificial heart pathway addresses a specific unmet need in end-stage biventricular disease, highlighting how segment differentiation can create defensible niches even in a concentrated market. Together, these players illustrate that competitive advantage in adult VADs is not determined solely by first-to-market timing, but by the interplay of regulatory standing, clinical evidence, post-market execution, and fit to distinct patient populations.
Regulatory and Reimbursement Dynamics That Shape Commercial Reality
The strategic weight of the adult VAD market cannot be evaluated without confronting its regulatory intensity. In the United States, the FDA classifies adult VADs as Class III devices, requiring premarket approval under 21 CFR 870.02. This designation creates a high barrier to entry and places a premium on robust clinical data packages, manufacturing consistency, and lifecycle management. The implication for market participants is clear: speed-to-market is subordinate to proof of safety and effectiveness, and companies that invest early in comprehensive clinical programs often secure a durable regulatory moat.
European dynamics impose their own structure. Under the EU Medical Device Regulation, VADs require Notified Body certification under Annex II, with mandatory post-market surveillance plans that extend oversight far beyond initial approval. This framework elevates the importance of real-world evidence generation, traceability, and ongoing risk management. For organizations planning cross-border launches, the cost of compliance is not a one-time event but a continuous operational commitment that affects resource allocation, partner selection, and launch sequencing.
Reimbursement architecture is equally decisive. In the United States, CMS DRG 003 covers LVAD implants, with an average payment of approximately $142,000 for destination therapy under the FY2025 IPPS final rule issued in August 2024. This reimbursement baseline influences hospital adoption economics, case volume planning, and the willingness of centers to invest in program infrastructure. In parallel, the 2024 AMA CPT manual updated CPT code 33975 for LVAD implantation to include percutaneous approaches, reflecting procedural evolution and potentially affecting billing pathways, operative planning, and the economic calculus of less invasive deployment strategies. These reimbursement nuances matter because they shape the practical feasibility of adoption at the institutional level, where clinical enthusiasm must align with financial sustainability.
What the Report Delivers for 2026 Decision-Making
This study is structured to move beyond descriptive market mapping and into actionable intelligence. It provides a comprehensive analysis of market size and forecast behavior across the full 2020 to 2032 period, giving leadership a defensible baseline for scenario planning. The segmentation framework examines device type, application, and regional distribution in a way that highlights where demand is consolidating and where white space may still exist. Rather than isolating each axis, the report analyzes how these dimensions interact, enabling readers to assess, for example, how a shift in clinical preference toward one device architecture could influence regional growth profiles or how reimbursement readiness might accelerate or delay adoption in specific markets.
The competitive section delivers firm-level profiles that connect product positioning, regulatory status, and recent corporate events to strategic implications. By integrating developments such as MOMENTUM 3 long-term data, RELINANT VAD's European clearance, and EXCOR controller modernization, the analysis shows how individual events alter competitive momentum and what they signal for future share dynamics. The regulatory and reimbursement review ties these commercial threads together by identifying the compliance and payment frameworks that determine which strategies are viable in practice. Together, these components create a decision-ready picture of the market's current structure and its likely direction.
For 2026 planning, the report is designed to support several core executive functions. It helps strategy teams evaluate entry and expansion timing by clarifying where evidence, regulation, and reimbursement are converging. It supports product and R&D leaders in assessing which clinical needs remain underserved and where incremental innovation could yield adoption advantages. It informs investor and partnership discussions by framing the concentration landscape, the significance of recent field actions, and the durability of evidence-driven positioning. And it provides marketing and market access teams with the structural context needed to align messaging with the reimbursement and institutional realities that govern procurement decisions.
Why This Intelligence Matters Now
The adult VAD market is not simply growing; it is maturing into a more complex, evidence-driven, and regulation-intensive arena. That maturation creates both opportunity and risk. Opportunity exists for organizations that can align device capability with robust clinical proof, navigate Class III approval pathways efficiently, and demonstrate value within existing reimbursement structures. Risk accumulates for those that underestimate the operational burden of post-market surveillance, overlook the financial realities of hospital adoption, or misread competitive signals in a concentrated landscape. The companies that succeed in 2026 and beyond will be those that treat market intelligence as a strategic asset rather than a periodic reference.
This report offers the depth, structure, and forward-looking framing required to make that judgment with confidence. The full study contains the detailed segmentation figures, regional breakdowns, and firm-level assessments that executives need to convert insight into action. For decision-makers shaping capital allocation, product strategy, and market access plans, the complete analysis provides the evidence base to move from hypothesis to commitment.
For detailed analysis of this topic, please visit the official page: Worldwide Adult Ventricular Assist Device Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com