

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Global Medical Hemostatic Clip Market Hits $580.25M in 2025, Projects 7.2% CAGR to 2032

## Navigating the Global Medical Microscopic Hemostatic Clip Market: Strategic Intelligence for 2026 and Beyond
The landscape of minimally invasive and microsurgical interventions is evolving at an unprecedented pace, driven by an aging global population, rising prevalence of vascular and gastrointestinal pathologies, and sustained demand for precision vessel management. Within this ecosystem, medical microscopic hemostatic clips have emerged as indispensable tools, bridging the gap between surgical efficacy and patient safety. Our latest market study on the Worldwide Medical Microscopic Hemostatic Clip Market delivers a comprehensive, data-grounded intelligence framework designed specifically for executive decision-makers navigating the 2026-2032 horizon.
This analysis serves as a strategic preview of the full report, highlighting the macro trajectory, competitive architecture, and regulatory-commercial dynamics that will define market positioning over the next seven years. The complete publication contains granular segmentation matrices, scenario-based forecasting, and actionable go-to-market blueprints that exceed the scope of this overview.
Market Macro Architecture: From Baseline Recovery to Sustained Expansion
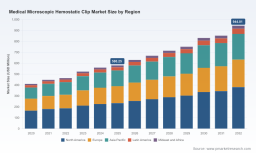
Over the historical observation window of 2020 through 2025, the global microscopic hemostatic clip market demonstrated resilient growth, navigating supply chain recalibrations, procedural volume rebounds, and iterative product innovation. The sector expanded from a baseline of approximately 410.25 million USD in 2020 to an estimated 580.25 million USD in 2025, reflecting a cumulative trajectory shaped by procedural adoption in advanced surgical centers and the gradual replacement of legacy ligation methods with clip-based occlusion systems.
Looking ahead, the forecast period from 2026 to 2032 projects a sustained compound annual growth rate of 7.2 percent, translating the market toward a projected valuation approaching 944.01 million USD by the terminal forecast year. This expansion is not merely a function of volume recovery; it reflects structural shifts in surgical planning, reimbursement optimization, and the increasing integration of microclip technologies into standardized endoscopic and microsurgical workflows.
Structural Drivers Shaping the Growth Trajectory
Several interlocking forces are reinforcing the long-term expansion outlook:
-
Procedural migration toward minimally invasive platforms: As surgical teams increasingly favor approaches that minimize tissue trauma and accelerate recovery, clip-based hemostasis provides a predictable, rapid-deployment alternative to suturing or thermal coagulation in delicate microsurgical fields.
-
Material science standardization: Modern microclips are engineered from titanium Grade 1, annealed for optimal malleability while maintaining biological inertness, MRI compatibility, and radiolucency. This material consistency reduces procedural variability and supports long-term implant safety profiles.
-
Regulatory clarity and compliance maturity: Devices in this category are classified under established frameworks such as 21 CFR 878.4300 (product code FZP) in the United States, requiring adherence to general controls including good manufacturing practices and labeling standards. In parallel, European manufacturers align with DIN EN ISO 13485 and legacy 93/42/EEC certification pathways, reinforcing cross-regional quality assurance expectations.
-
Reimbursement pathway optimization: The introduction of dedicated coding mechanisms, including HCPCS Code C9901 for outpatient defect closure procedures using repositionable hemostasis clips, has improved cost transparency and supported broader adoption in ambulatory surgical environments.
Competitive Architecture and Strategic Positioning
The market exhibits a moderately concentrated structure, with the top three participants accounting for approximately 62.45 percent of aggregate revenue and the top five reaching roughly 78.12 percent. This concentration reflects the specialized nature of microsurgical instrumentation, where manufacturing precision, regulatory clearances, and clinical credibility create meaningful barriers to entry. Yet the landscape remains dynamic, characterized by targeted product launches, regulatory milestones, and strategic reallocation of distribution rights.
Leading Commercial Players and Strategic Differentiation
The competitive field is anchored by a cohort of specialized manufacturers and diversified surgical instrument groups, each carving distinct positioning through product architecture, clinical specialization, and channel strategy:
-
Synovis Micro Companies Alliance, Inc. (Baxter): Operates from Birmingham, Alabama, and offers the GEM MicroClip and SuperFine MicroClip titanium hemostatic microclip lines, engineered for microsurgical vessel occlusion under microscopic visualization. These platforms feature chevron-shaped designs with atraumatic teeth and dedicated appliers. In early 2025, the company secured FDA 510(k) clearance for the GEM ZIPCLIP automatic microclip applier, preloaded with 15 titanium microclips, signaling a move toward workflow automation and reduced intraoperative handling complexity.
-
Peter Lazic GmbH: Based in Tuttlingen, Germany, this firm specializes in high-quality microsurgical instruments, including aneurysm clips and related hemostatic solutions tailored for neurosurgical and microsurgical applications. Its certification footprint under DIN EN ISO 13485 and CE marking frameworks reinforces its reputation in highly regulated procedural environments.
-
S&T Microsurgical Instruments: Operating from Neuhausen, Switzerland, the company develops and manufactures microsurgical instruments and sutures, with product distribution executed through partner networks to reach microsurgeon applications focused on vessel control.
-
Scanlan International, Inc.: Headquartered in Saint Paul, Minnesota, Scanlan maintains a dedicated microsurgical line featuring VASCU-STAT Bulldog clamps and micro clamps designed for small to medium vessel hemostasis across varied surgical fields.
-
Kapp Surgical Instrument Inc.: Located in Cleveland, Ohio, Kapp focuses on custom stainless steel surgical instruments and implants, including solutions adapted for microsurgical applications, enabling bespoke configurations for institutional and procedural specificity.
-
Amsel Medical Corporation: Based in Cambridge, Massachusetts, Amsel offers the SCureClamp with iDOT technology, an FDA-cleared and CE-marked mechanical vessel occluder designed for tubular structures where metal ligation clips are indicated, expanding the mechanical occlusion toolbox beyond traditional clip geometry.
-
MicroSurgical Technology: An active United States-based provider of microsurgical instruments, including hemostatic clip solutions for delicate procedures, reinforcing the breadth of the specialized instrumentation supply base.
Recent Market Catalysts: Launches, Acquisitions, and Regulatory Milestones
The competitive rhythm has accelerated through a series of consequential events that illustrate how incumbents and emerging players are reshaping product access and procedural reach:
-
In March 2025, Olympus Corporation introduced the Retentia HemoClip, a single-use hemostasis clip featuring 360-degree rotation, one-step deployment, and three sizing options optimized for GI bleeding control and defect closure. This launch underscores the continuing convergence between endoscopic hemostasis and clip-based closure technologies.
-
In March 2026, Micro-Tech Endoscopy signed a definitive agreement to acquire global distribution rights for the DuraClip repositionable hemostasis clip product line from CONMED. This transaction reflects a strategic push to consolidate access to repositionable clip platforms, which offer intraoperative flexibility and may reduce revision-related procedural friction.
Polymer Ligating Clips Market -
Earlier in January 2025, Synovis Micro Companies Alliance, Inc. received FDA 510(k) clearance for the GEM ZIPCLIP automatic microclip applier, a regulatory milestone that highlights growing clinician demand for preloaded, automated delivery systems that streamline vessel occlusion in microsurgical settings.
Segmentation Dynamics: Technology, Application, and Regional Flow
While the overall market trajectory is defined by the headline growth rates and revenue scale outlined above, the real strategic value lies in understanding how technology types, clinical applications, and regional demand patterns interact to shape procurement priorities, R&D allocation, and channel investment. The complete report unpacks these dimensions with detailed volume and value estimates, but several structural observations merit executive attention.
Technology Architecture: Rotatable Versus Non-Rotatable Platforms
The market is bifurcated between rotatable hemostatic clips and non-rotatable variants, each serving distinct procedural requirements. Rotatable designs offer intraoperative orientation flexibility, which can be particularly valuable in endoscopic and laparoscopic contexts where access angles are constrained and repositioning may reduce the risk of misdeployment. Non-rotatable clips, by contrast, continue to serve use cases where fixed geometry, tactile familiarity, and cost efficiency align with established surgical workflows. The comparative adoption balance between these two categories is shaped by procedural mix, surgeon preference, and the pace at which automated applier systems broaden the usability of advanced clip geometries.
Application Landscape: Endoscopy, Laparoscopy, and Adjunctive Use
Clinical application segmentation reveals a clear hierarchy of demand concentration. Gastrointestinal endoscopy represents a dominant application domain, reflecting the high procedural volume of GI bleeding management and mucosal defect closure, where clip-based hemostasis offers rapid deployment and predictable occlusion. Laparoscopic surgery constitutes a substantial secondary application stream, driven by the broader shift toward minimally invasive abdominal procedures that require reliable vessel control in confined operative fields. A remaining portion of demand flows into other medical procedures, encompassing specialized microsurgical and adjunctive use cases where clip-based occlusion complements broader hemostatic strategies.
Regional Demand Distribution
Regional demand patterns reflect differences in surgical infrastructure maturity, procedural reimbursement frameworks, and the penetration of advanced endoscopic and microsurgical capabilities. North America continues to anchor a substantial share of global demand, supported by established ambulatory surgical volumes, robust device regulation pathways, and early adoption of repositionable and automated clip platforms. Europe follows as a significant demand center, shaped by rigorous quality certification expectations and a strong base of specialized microsurgical instrument manufacturers. The Asia Pacific region represents a rapidly expanding demand pool, where procedural volume growth, healthcare capacity expansion, and increasing access to minimally invasive technologies are accelerating market participation. Latin America and the Middle East and Africa collectively form emerging demand corridors, where incremental capacity building and selective technology adoption are gradually broadening the addressable market base. The full report quantifies these regional dynamics with precise value estimates and trend projections, while this preview intentionally preserves the broader narrative arc.
Strategic Imperatives for 2026 Decision-Making
Product Portfolio and Innovation Roadmapping
Executives should evaluate whether current product architectures adequately address the converging demand for rotational flexibility, single-use convenience, and automated applier integration. The recent FDA clearance for preloaded automatic microclip appliers and the launch of 360-degree rotatable single-use clips indicate that workflow simplification is becoming a competitive differentiator rather than a supplementary feature. Strategic portfolio planning should therefore prioritize platform modularity, applier-clip compatibility, and sizing breadth aligned to high-frequency procedural indications.
Regulatory and Quality System Alignment
Given the classification of titanium hemostatic microclips as Class II implantable devices under established regulatory codes, and the expectation of ISO 13485-aligned quality systems for CE-marked products, compliance strategy must be treated as a market access enabler rather than a back-office function. Companies seeking expanded footprint should ensure that design controls, labeling, and manufacturing documentation support both domestic clearances and international certification requirements, particularly when pursuing distribution partnerships or cross-border market entry.
Channel Strategy and Distribution Architecture
The acquisition of global distribution rights for repositionable clip product lines illustrates how distribution control can accelerate market reach without requiring in-house manufacturing expansion. Organizations should assess whether their current channel model favors direct institutional sales, distributor partnerships, or hybrid architectures, and whether repositioning rights, exclusive territories, or co-marketing arrangements could strengthen competitive positioning in high-growth application areas such as GI endoscopy and laparoscopic surgery.
Reimbursement and Economic Value Storytelling
With outpatient coding mechanisms now available for defect closure procedures using repositionable hemostasis clips, economic value propositions must extend beyond clinical performance to encompass procedural efficiency, turnover optimization, and total cost of care. Sales and market access teams should develop institution-specific narratives that link clip-based hemostasis to reduced procedure time, fewer ancillary ligation steps, and compatible outpatient billing pathways, particularly in health systems incentivized by throughput and resource utilization metrics.
Report Content and Operational Utility
This market study is engineered to translate macro trends into executable strategy. Beyond the headline sizing and growth projections, the full report delivers a structured operational toolkit that includes:
-
Detailed segmentation analysis covering technology types, clinical applications, and regional demand distributions, with historical trajectory and forecast pathways that support demand planning and revenue modeling.
-
Competitive profiling of leading manufacturers and specialized instrument providers, including product architecture, regulatory status, and strategic moves such as launches, acquisitions, and distribution agreements.
Worldwide Medical Microscopic Hemostatic Clip Market -
Market concentration analysis that clarifies the balance between established incumbent share and the entry space available for differentiated technologies or regional partnerships.
-
Industry context integration covering regulatory classification expectations, quality system certification norms, reimbursement coding developments, and material specifications that influence product design and procurement decisions.
-
Strategic scenario framing that helps leadership teams assess how shifts in procedural adoption, automation adoption, and distribution consolidation may alter competitive positioning across the 2026-2032 period.
Each section is designed to support concrete decisions in product development prioritization, market entry sequencing, pricing architecture, and channel investment. The full publication moves beyond descriptive market characterization into actionable intelligence, enabling teams to benchmark their current positioning against the evolving competitive field and to identify the most defensible growth pathways.
Conclusion: Converting Market Visibility into Strategic Advantage
The Worldwide Medical Microscopic Hemostatic Clip Market is poised for sustained expansion, but the abundance of growth opportunity will reward organizations that can convert market visibility into disciplined execution. The projected 7.2 percent CAGR through 2032, the maturation of automated and rotatable clip platforms, and the ongoing consolidation of distribution rights all point to a market where differentiation increasingly depends on workflow integration, regulatory readiness, and channel control. At the same time, the concentration profile of the competitive field suggests that scale advantages and specialized clinical credibility will continue to influence procurement preferences in high-volume settings.
This preview offers a strategic orientation to the forces shaping the market, but the complete report provides the granular segmentation data, company-level profiling, and scenario-based insights necessary to translate direction into action. For executives preparing 2026 investment decisions, product roadmaps, and market access strategies, the full study functions as a decision-grade intelligence asset, connecting macro momentum to the operational details that determine competitive outcomes.
For detailed analysis of this topic, please visit the official page: Worldwide Medical Microscopic Hemostatic Clip Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com