

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Global Cloud IDS IPS Market to Reach $7,673.83M by 2032, Driven by 15.2% CAGR

Navigating the Next Wave of Cloud IDS/IPS: Strategic Imperatives for 2026 Decision-Makers
The cloud security landscape is undergoing a structural transformation, driven by expanding attack surfaces, regulatory complexity, and the relentless migration of critical workloads to distributed cloud environments. As organizations move beyond perimeter-centric defense models, Cloud Intrusion Detection and Prevention Systems (IDS/IPS) have become indispensable components of modern security architectures. PW Consulting’s newly released Worldwide Cloud IDS IPS Market research provides a comprehensive, data-grounded view of this evolving ecosystem, offering enterprise leaders, investors, and technology strategists the analytical clarity required to navigate 2026 and beyond.
This market research is designed not merely as a retrospective snapshot, but as a forward-looking strategic compass. By synthesizing historical trajectories, forward-looking projections, competitive positioning, and macro-level industry dynamics, the study equips decision-makers with actionable intelligence to align security investments with broader organizational objectives. The following overview highlights the core analytical dimensions of the report and explains why its insights are particularly critical for strategic planning in the current cycle.
Market Trajectory and the Strategic Value of Forward-Looking Intelligence
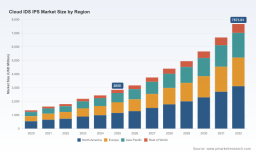
The global Cloud IDS/IPS market has demonstrated consistent expansion over the past half-decade, reflecting the accelerating adoption of cloud-native security controls across industries. From 2020 through 2025, the market advanced from approximately USD 1,350 million to USD 2,850 million, signaling robust demand for integrated detection and prevention capabilities that can operate seamlessly across public, private, and hybrid cloud deployments. Looking ahead, the forecast period from 2026 to 2032 outlines a continued growth trajectory, with the market projected to reach USD 3,169.93 million in 2026 and expand to USD 7,673.83 million by 2032. The implied compound annual growth rate of 15.2 percent underscores the sustained momentum behind cloud security investment.
For enterprise strategists, these figures are more than headline metrics. They represent a structural shift in how organizations allocate cybersecurity budgets, prioritize vendor evaluations, and architect defensive layers. A growth environment of this magnitude introduces both opportunity and complexity. Companies that understand the underlying demand drivers, deployment preferences, and concentration patterns within the vendor landscape can position themselves more effectively—whether through procurement strategy, partnership selection, or internal capability development. The report’s forward-looking framework helps leaders anticipate where market weight will shift, how deployment models will evolve, and which organizational segments are likely to drive incremental adoption.
Importantly, the study maintains analytical discipline by emphasizing macro-level market direction without obscuring the need for granular, context-specific decision-making. By presenting overall size evolution, growth rates, and structural breakdowns in a cohesive narrative, the research enables readers to grasp the scale of the opportunity while recognizing that segmentation-level dynamics require deeper exploration. This approach ensures that strategic planning is grounded in credible market sizing while preserving the necessity of access to detailed segmentation data for precise investment and procurement decisions.
Competitive Landscape: Who Is Shaping the Cloud IDS/IPS Ecosystem
The vendor ecosystem surrounding Cloud IDS/IPS is characterized by a blend of established network security incumbents, cloud platform providers, and specialized security innovators. Market concentration metrics indicate that the top three players account for 45.5 percent of market revenue, while the top five collectively represent 62.3 percent, suggesting a moderately consolidated landscape where scale, platform integration, and ecosystem reach confer meaningful advantages. Yet the presence of numerous specialized and emerging participants ensures that differentiation remains possible through technology architecture, deployment flexibility, and domain-specific threat intelligence.
Cisco Systems continues to anchor its offering around cloud-native and hybrid Cloud IDS/IPS solutions integrated with its Secure Firewall portfolio and broader cloud security platforms, targeting threat detection and prevention across public, private, and hybrid environments. Fortinet emphasizes scalable cloud network security through FortiGate Cloud and cloud-delivered IPS/IDS capabilities, leveraging AI-driven threat intelligence to support organizations seeking unified protection across distributed infrastructures. Trend Micro focuses on Cloud IPS and HIPS solutions, including managed rule groups designed to simplify AWS Cloud IPS deployments and enable automated threat prevention. Palo Alto Networks positions Prisma Cloud as a comprehensive cloud workload and network threat detection platform with integrated IDS/IPS functionalities, appealing to enterprises seeking consolidated cloud security controls.
Check Point Software Technologies contributes Quantum Cloud and Infinity platform solutions with advanced Cloud IPS/IDS designed for threat prevention across heterogeneous cloud environments. CrowdStrike extends behavioral-based threat detection and prevention through Falcon Cloud Security, with capabilities that reach into cloud IDS/IPS functions and support organizations prioritizing identity- and behavior-centric security models. Zscaler delivers Cloud IPS as part of its Zero Trust Exchange platform, emphasizing inline, cloud-native intrusion prevention across all traffic flows. IBM Security offers managed Cloud IDS/IPS services integrated with IBM Cloud and hybrid environments, using AI to enhance threat detection and operational response. Microsoft provides Defender for Cloud with IDPS capabilities for Azure and multi-cloud environments, combining threat intelligence and anomaly detection within a widely adopted enterprise ecosystem.
Cloud platform providers also play a pivotal role. Amazon Web Services supports intelligent threat detection through GuardDuty and enables partner Cloud IPS solutions such as Trend Micro for network-level protection within AWS environments. Google Cloud offers Cloud IDS for cloud-native network threat detection, including identification of malware, spyware, and command-and-control attacks. Juniper Networks delivers cloud-delivered and virtual IDS/IPS solutions integrated with SRX firewalls and SD-WAN, supporting organizations that prioritize network-centric security architectures. Sophos incorporates cloud-based IDS/IPS capabilities within its Managed Detection and Response and intercept solutions, targeting cloud workloads with managed service-oriented approaches.
Worldwide Cloud IDS IPS Market
Recent developments illustrate how rapidly this competitive field is evolving. In November 2025, Trend Micro partnered with AWS to offer one-click TrendAI managed rule groups for Cloud IPS and HIPS in the AWS Marketplace, enabling automated threat prevention without requiring extensive manual rule management. Earlier, in March 2025, Deutsche Telekom’s Open Telekom Cloud introduced a cloud firewall with integrated IDS and IPS capabilities designed to secure both north-south and east-west traffic through real-time detection and prevention. These moves reflect broader industry trends toward automation, marketplace-enabled deployment, and tighter integration between cloud infrastructure and security controls.
Understanding these competitive dynamics is essential for organizations evaluating vendor relationships, assessing integration pathways, and anticipating shifts in feature prioritization. The report’s competitive analysis section provides structured profiles and contextual evaluation frameworks that help readers compare offerings not only by feature lists, but by deployment philosophy, ecosystem compatibility, and strategic alignment with organizational cloud roadmaps.
Worldwide Cloud VPN Market
Deployment Models, Organizational Segments, and the Regional Dimension
The market’s structure reflects a balanced but evolving split between deployment approaches. Public cloud deployments represent a substantial share of market activity, while private and hybrid cloud configurations remain highly relevant for organizations with stringent data handling requirements, legacy integration needs, or regulatory constraints. This dual trajectory indicates that Cloud IDS/IPS solutions must be evaluated not only on cloud-native performance, but also on their ability to interoperate across heterogeneous environments and support consistent policy enforcement.
Organizational size further shapes adoption patterns. Large enterprises constitute a significant portion of market demand, driven by complex multi-cloud strategies, scale-sensitive threat landscapes, and the need for centralized visibility across distributed assets. At the same time, small and medium enterprises represent a meaningful and growing segment, as cloud security becomes more accessible through managed services, marketplace deployments, and simplified rule management. The report explores how these organizational segments differ in procurement behavior, operational maturity, and technology expectations, providing context for both vendors seeking to refine go-to-market strategies and enterprises planning security transformations.
Regionally, the market spans multiple geographies with differing regulatory environments, cloud adoption maturity, and infrastructure constraints. North America, Europe, Asia Pacific, and Rest of World each present distinct demand characteristics shaped by local cloud ecosystems, compliance frameworks, and security vendor presence. The study examines these regional dynamics at a macro level, highlighting how geography influences deployment preferences, certification requirements, and vendor selection criteria. By integrating regional context without oversimplifying local nuances, the research supports more informed multinational planning and region-specific investment prioritization.
Readers seeking precise regional revenue allocations, deployment-model percentages, or organization-size breakdowns will find that the full report provides the detailed segmentation data necessary for granular market entry, forecasting, and competitive benchmarking. This layered approach ensures that executive summaries convey strategic direction while preserving the depth required for operational planning.
Industry Dynamics Shaping Cloud IDS/IPS Demand in 2026
Beyond vendor competition and segmentation patterns, several macro-level dynamics are reshaping the Cloud IDS/IPS market. Energy costs and infrastructure economics are increasingly relevant to cloud security planning. Data center electricity demand surged by 17 percent in 2025, with AI-focused facilities growing even faster, raising operational costs for cloud security infrastructure. In the United States, data center annual energy use reached approximately 176 TWh in 2023, representing 4.4 percent of US electricity, and projections suggest this figure could double or triple by 2028. These trends affect the economics of hosting cloud IDS/IPS workloads, influence provider pricing models, and encourage demand for efficiency-aware security architectures.
Regulatory and certification pathways are also in flux. The US Department of Defense initiated the sunset of the DoDIN Approved Products List program, with testing concluding by December 2025 and repository maintenance continuing into FY 2026. This transition affects certification pathways for cloud security products and introduces new considerations for government-adjacent and regulated-sector buyers. At the same time, data sovereignty laws and cross-border data flow restrictions continue to influence deployment decisions, particularly in regulated industries and regions with strict localization requirements. Organizations must therefore evaluate Cloud IDS/IPS solutions not only on technical performance, but also on their ability to support compliance obligations, data residency expectations, and evolving audit frameworks.
These dynamics reinforce the value of a research perspective that connects market sizing with operational realities. The report incorporates such industry context to help readers understand why demand is shifting, where cost and compliance pressures are most acute, and how vendors and buyers alike are adapting their strategies. By situating market growth within these broader forces, the study provides a more complete foundation for strategic decision-making than a purely revenue-focused analysis could offer.
What the Report Delivers: Practical Intelligence for Strategic Planning
PW Consulting’s Worldwide Cloud IDS IPS Market research is structured to support a wide range of strategic use cases. It combines historical market data, forward-looking projections, segmentation analysis, competitive profiling, and industry-context integration into a single cohesive reference. The report is designed to help organizations answer questions that directly affect planning cycles: how fast is demand expanding, which deployment models are gaining relative traction, where concentration risk lies within the vendor base, and what macro-level factors should be incorporated into budgeting and architecture decisions.
Key components include detailed market size tracking from 2020 through 2032, growth-rate analysis across the forecast period, and structured segmentation views that break down demand by region, deployment model, and organization size. Competitive profiles examine the strategic positioning, solution scope, and recent moves of major participants, while recent development tracking highlights product launches, partnerships, and integration milestones that signal where the market is heading. The inclusion of industry-context factors such as energy economics, regulatory transitions, and data sovereignty considerations ensures that market analysis remains grounded in operational reality.
For executives, procurement leaders, and security architects, the report serves as a decision-support tool that can inform vendor shortlisting, investment prioritization, cloud migration planning, and risk assessment. For investors and market strategists, it offers a structured view of market concentration, growth drivers, and competitive differentiation that can support portfolio evaluation and market-entry analysis. By balancing accessible macro-level insights with the availability of deeper segmentation data, the research is built to guide both high-level strategy and more detailed market-specific planning.
Why This Research Matters for 2026 Decision-Making
The 2026 planning cycle will be shaped by organizations that can align security investment with cloud strategy, regulatory expectations, and operational economics. Cloud IDS/IPS is no longer a peripheral control; it is a central element of threat detection, workload protection, and multi-environment visibility. In a market expanding at a sustained double-digit pace and featuring a competitive mix of network security leaders, cloud platform providers, and specialized innovators, the ability to interpret market structure and vendor positioning becomes a strategic advantage.
This research provides that interpretive foundation. It helps leaders distinguish between short-term feature competition and longer-term architectural value, evaluate where deployment flexibility matters most, and anticipate how regulatory and infrastructure pressures may influence procurement and hosting decisions. By presenting credible market sizing, structured segmentation, and competitive context within a unified analytical framework, the study reduces uncertainty and supports more disciplined planning.
For teams seeking precise regional allocations, deployment-model percentages, organization-size breakdowns, or detailed vendor revenue positioning, the complete report offers the segmentation depth required for targeted action. Engaging with the full dataset enables stakeholders to move from strategic orientation to executable planning with confidence.
Next Steps for Stakeholders Seeking Market Clarity
Organizations preparing for 2026 security budgeting, cloud architecture reviews, or vendor evaluations will benefit from a research asset that connects market growth with competitive and operational context. PW Consulting’s Worldwide Cloud IDS IPS Market study is designed for exactly that purpose: to provide a credible, forward-looking, and practically useful view of where the market stands and where it is headed.
Readers interested in exploring the full segmentation data, detailed vendor profiles, and extended industry-context analysis are encouraged to access the complete report through our official research portal. There, stakeholders can retrieve the granular market breakdowns, regional and deployment-specific figures, and structured competitive assessments needed to translate strategic insight into measurable action.
For detailed analysis of this topic, please visit the official page: Worldwide Cloud IDS IPS Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com