

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Twist Dispensing Closure Market Hits $480.5M in 2025, Projected to Hit $678.83M by 2032

Global Twist Dispensing Closure Market: Strategic Intelligence for 2026 Decision-Making
The global twist dispensing closure market stands at a critical inflection point in 2026. As packaging engineers, procurement leaders, and sustainability officers navigate shifting regulatory mandates, raw material volatility, and evolving consumer expectations, access to rigorous, forward-looking market intelligence has become a non-negotiable component of strategic planning. This analysis introduces our latest comprehensive market research on the Worldwide Twist Dispensing Closure Market, designed to equip executive teams with the structural clarity needed to allocate capital, shape product roadmaps, and position supply chains for the forecast period extending through 2032.
The market has demonstrated consistent expansion over the past half-decade, with total revenue growing from approximately 375.2 million USD in 2020 to an estimated 480.5 million USD in 2025. Looking ahead, the trajectory remains constructive, projected to reach 509.17 million USD in 2026 and climb to 678.83 million USD by 2032. This growth profile reflects a compound annual growth rate of 5.06 percent across the forecast horizon, underpinned by steady demand across food and beverage, personal care, household and industrial, and pharmaceutical applications. The expansion is neither accidental nor superficial; it is being engineered by regulatory pressure, material science advancements, and a competitive landscape that rewards speed-to-market and sustainability integration.
Why 2026 Represents a Decisive Strategic Window
For organizations operating in or adjacent to the closure ecosystem, 2026 is not merely another planning cycle. It is the year when several structural forces converge. Extended Producer Responsibility frameworks in the European Union have matured, and parallel regulatory momentum in North America is accelerating the adoption of mono-material and fully recyclable closure architectures. Simultaneously, the EU Single-Use Plastics Directive has already mandated tethered closures on beverage containers below three liters since July 2024, creating a ripple effect that is reshaping engineering priorities across dispensing and twist closure formats. These mandates are no longer theoretical compliance checkboxes; they are active drivers of design, tooling, and supply chain reconfiguration.
At the same time, raw material economics are injecting both risk and opportunity into procurement strategies. The dominant production inputs for twist dispensing closures remain polypropylene and high-density polyethylene resins, but regional price dispersion is pronounced. As of April 2026, polypropylene pricing has been observed at approximately 1.43 USD per kilogram in North America, 2.1 USD per kilogram in Europe, and 1.26 USD per kilogram in Northeast Asia. This geographic spread creates competitive asymmetry: manufacturers with localized sourcing footprints or flexible procurement architectures can protect margins more effectively, while others face pressure to pass costs downstream or absorb them through design optimization. Understanding how these material dynamics interact with regional demand intensity and regulatory timelines is precisely where strategic planning must be grounded in data, not intuition.
The competitive intensity of the market further underscores the urgency of informed decision-making. The sector exhibits a moderately concentrated structure, with the top three participants capturing roughly 32.4 percent of collective revenue and the top five accounting for approximately 45.8 percent. This concentration profile suggests that while scale players exert meaningful influence over pricing norms and standard-setting, there remains substantial room for differentiated innovation, niche application specialization, and regional leverage. Companies that can align product architecture with sustainability mandates, consumer convenience expectations, and regional material cost realities will be best positioned to capture disproportionate value as the market expands toward its 2032 endpoint.
What This Market Research Delivers: Practical Intelligence for Execution
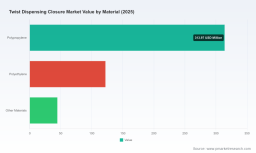
This research report is engineered to move beyond high-level commentary and deliver actionable architecture for strategic planning. It provides a granular mapping of market size and growth trajectories across the historical window of 2020 through 2025, then extends into a disciplined forecast framework covering 2026 through 2032. The analysis decomposes the market along multiple operational dimensions, enabling teams to understand where demand is accumulating, which material choices are gaining traction, and how end-use applications are reshaping closure specifications.
Key structural components of the report include:
- A comprehensive historical and forecast revenue model that tracks overall market progression and isolates growth drivers across the forecast period, giving leadership teams a reliable baseline for capacity planning and investment timing.
- A segment-level decomposition that examines how material preferences, end-use application demand, and regional market dynamics interact, enabling more precise product positioning and go-to-market sequencing.
- A competitive landscape assessment that profiles leading participants, evaluates their strategic positioning, and maps recent product launches and innovation signals to broader market trends.
- An industry context analysis that integrates raw material pricing behavior, regulatory developments, and sustainability-driven design shifts into a unified view of market dynamics, helping teams anticipate constraints and opportunities before they materialize in the P&L.
The report is intentionally structured to support cross-functional use. Procurement teams can leverage the material and regional context to refine sourcing strategies and negotiate with a clearer understanding of cost dispersion. Product development groups can align closure architecture decisions with regulatory trajectories and end-use requirements. Commercial leaders can use the competitive profiling and market size progression to prioritize territories, applications, and partnership opportunities. By consolidating these perspectives into a single, coherent framework, the research reduces the friction between strategic intent and operational execution.
Worldwide Twist Dispensing Closure Market
Competitive Landscape: Who Is Shaping the Market and How
The twist dispensing closure market is defined by a diverse set of participants whose strategies span scale manufacturing, specialized dispensing innovation, sustainability-led redesign, and regional footprint optimization. Understanding these players is essential for benchmarking, partnership evaluation, and competitive positioning.
Silgan Holdings Inc., headquartered in Stamford, Connecticut, maintains a strong presence through its Twist-Off and PT closure offerings, including Plasti-Twist mono-material variants with liners and induction heat seals. These solutions are engineered for liquid foods, non-carbonated beverages, and dispensing applications, reflecting a focused approach to food and beverage packaging where seal integrity and material efficiency matter.
AptarGroup Inc., based in Crystal Lake, Illinois, provides a broad portfolio of dispensing closures across food, beverage, personal care, and pharmaceutical markets. Its emphasis on innovative and sustainable twist and flip-top dispensing solutions highlights a strategic alignment with consumer convenience and environmental goals, an orientation that has become increasingly central as regulators and end-users converge on recyclability and ease of use.
Berry Global Group, Inc., operating from Evansville, Indiana, manufactures dispensing closures alongside pump and valve systems, including twist dispensing options for personal care, household chemicals, pharmaceutical, and consumer goods packaging. Its multi-category footprint enables integrated packaging solutions that can reduce assembly complexity and streamline supplier relationships for downstream customers.
Closure Systems International Inc. (CSI), headquartered in Indianapolis, Indiana, is a global producer of sustainable closure solutions, including Twist and Flip tethered designs for beverage, food, dairy, and industrial fluid applications. Its focus on high-speed application systems underscores the operational importance of line efficiency and throughput in competitive manufacturing environments.
O.Berk Company LLC, based in Hackensack, New Jersey, supplies plastic dispensing twist open and twist close closures and caps for liquids, lotions, paints, and viscous materials across plastic, glass, and metal containers. Its coverage of healthcare, personal care, and industrial markets reflects a versatile positioning that serves applications where resealability and dispensing control are critical.
Dispenser Pump Market
Mold-Rite Plastics, operating as MRP Solutions in the United States, is an injection molded plastic closures manufacturer offering dispensing closures through lines that include Weatherchem Flapper and Stull Technologies Ultra Light hinged, disc tops, twist caps, and Flip-N-Squeeze products. Its portfolio spans personal care, household, and pharmaceutical packaging, illustrating the importance of design variety and application specificity in a fragmented demand environment.
Amcor Plc, headquartered in Zurich, Switzerland, produces plastic caps and bottle closures, including screw, snap, flip-top, and dispensing closures with child-resistant, tamper-evident, and senior-friendly options. Its emphasis on safety features and broad market coverage aligns with regulatory and consumer expectations that increasingly treat closure functionality as a multidimensional requirement rather than a single-purpose component.
TriMas Packaging, based in the United States, delivers specialty dispensing, closure, and flexible packaging solutions, including tamper-evident, child-resistant, and dispensing closures for beauty, personal care, food, and industrial applications. Its specialty orientation positions it to serve customers who require customized performance attributes and regulatory compliance features.
BERICAP Holding GmbH, a German manufacturer of plastic caps and closures for food, beverage, and non-food markets, brings a global manufacturing footprint to dispensing and twist closure solutions. Its geographic reach supports customers seeking consistent supply across regions while navigating local compliance and material availability considerations.
Guala Closures S.p.A., headquartered in Alessandria, Italy, provides non-refillable closures, safety closures, tamper-evident systems, and dispensing solutions for beverage and other packaging applications. Its focus on safety and non-refillable design reflects ongoing industry attention to consumer protection and product integrity.
Beyond established positioning, recent innovation activity signals how quickly the competitive frontier is moving. In February 2024, AptarGroup launched an innovative twist dispensing closure for personal care products featuring a child-resistant design and an emphasis on eco-friendly packaging solutions. More recently, in April 2026, Tri-Sure introduced TulipCap, a two-part innovative twist cap for plastic containers that uses a polyethylene overcap, with optional post-consumer recycled material, and a thermoplastic elastomer insert for a gas-tight seal. These developments illustrate a dual strategic thrust: safety and convenience features are being integrated without compromising sustainability objectives, and material innovation is being used to close the gap between performance requirements and recyclability mandates.
Market Dynamics: Regulation, Materials, and the Sustainability Imperative
The market's trajectory is being reshaped by a set of interlocking dynamics that extend well beyond simple demand growth. Regulatory pressure is the most visible catalyst. Extended Producer Responsibility regulations in the EU, with expanding influence in North America, are driving innovation toward mono-material and fully recyclable closure designs, including for dispensing and twist closures. This shift is not cosmetic; it affects resin selection, liner compatibility, tooling design, and end-of-life processing pathways. Companies that treat recyclability as a design parameter from the outset are better positioned to meet compliance requirements while preserving functional performance.
The EU Single-Use Plastics Directive has already mandated tethered closures on beverage containers below three liters since July 2024, accelerating development of tethered dispensing and twist closure formats. This mandate has catalyzed engineering investment in attachment mechanisms, user experience, and production line compatibility. As tethered designs become more prevalent, the competitive advantage will increasingly belong to manufacturers who can deliver reliable tethered performance at scale while maintaining cost discipline and material efficiency.
Material sourcing and pricing behavior add another layer of strategic complexity. Twist dispensing closures are primarily manufactured from polypropylene and high-density polyethylene resins, and the price environment is regionally uneven. The April 2026 pricing dispersion for polypropylene across North America, Europe, and Northeast Asia demonstrates that Sourcing strategies cannot be universally replicated; they must be calibrated to regional cost structures, logistics corridors, and customer concentration. In parallel, manufacturers are incorporating post-consumer recycled resin in closures such as polyethylene overcaps to meet sustainability mandates and improve recyclability. This trend creates a direct link between regulatory compliance, material procurement, and product design, reinforcing the need for integrated planning rather than siloed decision-making.
Together, these dynamics suggest that the market's next phase of growth will be characterized by a tighter coupling of performance, compliance, and cost. Organizations that map these interdependencies clearly will be able to make more confident decisions about capacity expansion, material transitions, and product portfolio prioritization.
How to Use This Intelligence for 2026 Strategy
Access to a structured market view is only valuable if it translates into decision-making clarity. This research is designed to support several high-impact strategic actions. Leaders can use the historical and forecast trajectory to validate capacity investments and timing assumptions, ensuring that expansion plans are aligned with credible demand progression rather than optimistic speculation. Teams can use the segment decomposition to identify where application demand is most resilient and where material preferences are consolidating, enabling more targeted product development and inventory positioning. Competitive profiling allows organizations to benchmark their innovation cadence, assess partnership opportunities, and anticipate moves by scale players and specialized innovators alike.
Equally important, the integration of regulatory and material context provides a lens for scenario planning. As EPR frameworks expand and tethered closure requirements become more entrenched, companies that have already mapped the implications for resin selection, liner compatibility, and manufacturing throughput will face fewer disruptions. Those that have not will be forced into reactive adjustments that can compress margins and delay time-to-market. The research framework presented here is intended to reduce that uncertainty by making the relationships between regulation, materials, competitive behavior, and demand visible and actionable.
Final Thoughts: Turning Market Visibility into Strategic Advantage
The Worldwide Twist Dispensing Closure Market is expanding along a measured but durable growth path, supported by application diversity, regulatory-driven innovation, and a competitive landscape that rewards both scale and specialization. For decision-makers in 2026, the strategic question is no longer whether the market is growing, but how to align product architecture, sourcing strategy, and competitive positioning with the forces that are actively shaping that growth. The convergence of sustainability mandates, material cost dispersion, tethered closure requirements, and evolving end-use expectations creates a decision environment that rewards precision, foresight, and disciplined execution.
This market research was built to provide exactly that level of clarity. It consolidates historical performance, forecast trajectory, segment structure, competitive profiling, and industry dynamics into a single analytical foundation, enabling leadership teams to move from observation to action with confidence. The macro outline is clear; the operational details that will determine success or failure in specific regions, applications, and material pathways are where the deepest value lies.
To access the full market sizing, segment breakdowns, regional and application details, competitive benchmarks, and the complete forecast framework, visit the source page for the Worldwide Twist Dispensing Closure Market research. The complete report is structured to support immediate strategic use, giving your team the granular intelligence needed to turn 2026 planning into durable competitive advantage through 2032 and beyond.
For detailed analysis of this topic, please visit the official page: Worldwide Twist Dispensing Closure Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com