

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
PW Consulting Reports Global Wheel Balancer Touchscreen Market Hits $391M in 2025, Surging to $609.6M by 2032
By pmarketresearch, 2026-09-16
Navigating the Touchscreen Wheel Balancer Market: Strategic Insights for 2026 and Beyond
The global automotive service equipment landscape is undergoing a profound transformation, driven by the convergence of digital interfaces and precision engineering. As we move deeper into 2026, the Worldwide Wheel Balancer With Touchscreen Market stands at a critical inflection point. For industry stakeholders, OEM partners, and investment strategists, understanding the trajectory of this sector is no longer optional; it is a prerequisite for sustainable growth and competitive positioning.
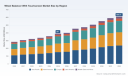
The recent historical baseline, spanning from 2020 through 2025, has established a robust foundation for this market. Valued at approximately 285.4 million USD in 2020, the sector demonstrated remarkable resilience and growth, crossing the 391.0 million USD threshold by 2025. This trajectory reflects not merely a recovery from global disruptions but an organic shift toward advanced servicing technologies. The momentum is set to accelerate, with valuations projected to reach 401.2 million USD in 2026 and climbing steadily toward 609.61 million USD by 2032. This expansion corresponds to a Compound Annual Growth Rate (CAGR) of 6.55 percent over the forecast period, signaling a healthy and sustained demand curve for high-technology balancing solutions.
This article serves as a strategic overview of the latest comprehensive market research released by PW Consulting. Our objective is to outline the macro-environmemental drivers, competitive dynamics, and technological shifts that define this space, while highlighting the specific actionable data available in the full report for those ready to deepen their intelligence edge.
Macro Dynamics and Demand Catalysts
The expansion of the wheel balancer market with touchscreen interfaces is not occurring in a vacuum. It is intrinsically linked to broader automotive aftermarket trends and manufacturing shifts. The primary engine driving this growth is the increasing volume of vehicle production coupled with a maturing aftermarket sector that demands higher efficiency and precision. Service centers and automotive 4S shops are under constant pressure to reduce turnaround times while improving accuracy. Touchscreen interfaces address this directly by simplifying operator inputs and reducing human error in measurement data entry.
Furthermore, the technology landscape within the service bay is evolving. The adoption of advanced balancing technologies, including diagnostic features and intuitive graphical user interfaces, is becoming a standard expectation rather than a premium add-on. This shift supports equipment market expansion by creating a pull effect where older, non-digital units are replaced by modern touchscreen-equipped models to maintain service quality standards.
Supply chain dynamics also play a pivotal role in shaping the market structure. Steel and electronics remain the key raw materials and components in wheel balancer manufacturing. The upstream supply chain involves a complex network of raw material suppliers, component manufacturers specializing in sensors and motors, and final machine assembly units. Any volatility in these sectors can influence production costs and lead times, making supply chain resilience a key focus for manufacturers navigating the 2026 landscape.
Regulatory pressures are also subtly reshaping the ecosystem. Environmental regulations are driving shifts toward eco-friendly materials in related wheel balancing weights, with zinc holding a growing share due to recyclability despite a price premium over lead. While this primarily affects consumables, it influences the broader context in which balancers operate, pushing manufacturers to ensure their equipment is compatible with these evolving material standards.
Wheel Balancer Market
Market Segmentation and Geographic Footprint
Understanding where value is generated within this market is crucial for strategic planning. The segmentation of the market reveals distinct preferences and adoption rates across different automation levels and application sectors. The industry is broadly divided between fully automatic and semi-automatic wheel balancers. The preference for automation is driven by the need for high throughput in busy service environments, yet semi-automatic units retain a significant presence where flexibility and lower capital expenditure are prioritized.
Application-wise, the demand is distributed across automotive 4S shops, tire service centers, and vehicle manufacturers. Each segment presents unique requirements. Automotive 4S shops often require integrated diagnostic capabilities to align with manufacturer-specific servicing protocols. Tire service centers prioritize speed and durability to handle high volumes of consumer traffic. Vehicle manufacturers utilize these systems for quality control and final assembly verification, demanding the highest levels of precision and repeatability.
Geographically, the market exhibits a diversified distribution of revenue. Asia Pacific represents a substantial portion of the market volume, reflecting the region's massive automotive production base and expanding aftermarket network. North America follows as a mature market with high adoption rates of advanced diagnostic equipment. Europe maintains a strong presence, driven by stringent regulatory standards and a dense network of specialized service providers. Latin America and the Middle East and Africa contribute to the global aggregate, offering growth opportunities as their automotive service infrastructures modernize. A detailed breakdown of regional revenue contributions and specific application share percentages is available in the full dataset, providing granular visibility for region-specific strategy formulation.
Competitive Landscape and Key Players
The competitive environment in the worldwide wheel balancer with touchscreen market is characterized by a mix of established industrial giants and specialized manufacturers. The market concentration indicates a moderately consolidated landscape, where the top three companies hold a significant share, while the top five control a majority of the market revenue. This structure suggests that while scale matters, specialized innovation and brand loyalty remain powerful differentiators.
Leading the charge are companies like CEMB S.p.A. based in Italy, which offers a wide array of touchscreen models including the ER100 GT and ER85 EVO series. Their focus on features like automatic gauges and 2-HIT technology caters to both car and truck segments. Similarly, Hunter Engineering Company in the USA maintains a strong leadership position with its SmartWeight Elite and Road Force series, emphasizing intuitive interfaces and hands-free measurement capabilities like CenteringCheck.
The North American market sees significant activity from Snap-on Equipment entities, specifically Hofmann and John Bean. Hofmann provides the geodyna series and Armored Series with touchscreen monitors and easyWeight laser placement, targeting durability and ease of use. John Bean complements this with semi-automatic laser touchscreen balancers like the B600P, focusing on high-productivity interfaces and 3D imaging.
Innovation continues to emerge from other key players. Coats Company recently launched the ProBalance E900 diagnostic wheel balancer, featuring a smart touchscreen interface and laser-powered data entry designed for high-volume tire and repair shops. This launch underscores the trend toward integrating diagnostics directly into balancing hardware. Italian manufacturers such as Giuliano Industrial and Ravaglioli S.p.A. are pushing the boundaries of automation with 3D super-automatic models and advanced rim profile detection systems. Meanwhile, German precision is represented by Beissbarth Automotive Testing Solutions GmbH, offering units with large touchscreen displays and automatic data arms.
Strategic partnerships and portfolio integrations, such as those seen with Snap-on Equipment distributing SUN and John Bean lines, highlight the importance of distribution networks in this sector. Competitors are not just selling machines; they are selling ecosystems of service efficiency. For a complete competitive profiling including detailed product line comparisons and market share estimations for all key entities, the full report provides the necessary depth.
Strategic Implications for 2026 Decision Makers
For executives and strategists operating in 2026, the insights from this market study translate into several critical action items. First, capital allocation for equipment upgrades should prioritize units with verified touchscreen capability and diagnostic integration. The data suggests that the shift toward digital interfaces is accelerating, and lagging in this adoption may result in operational inefficiencies and reduced service appeal.
Second, supply chain management requires renewed attention. Given the reliance on steel and electronics, monitoring upstream supplier stability and component availability is essential. Manufacturers and distributors should consider diversifying suppliers for critical sensors and motor components to mitigate potential bottlenecks.
Worldwide Wheel Balancer With Touchscreen Market
Third, geographic expansion strategies should be informed by the nuanced regional demand profiles. While established markets in North America and Europe offer steady returns, the growth trajectory in Asia Pacific presents opportunities for market penetration and partnership development. However, each region requires a tailored approach regarding pricing, service support, and feature prioritization.
Finally, product development teams should focus on the convergence of balancing and diagnostic functions. The launch of models like the ProBalance E900 indicates a market preference for multi-functionality. Future iterations of wheel balancers will likely need to incorporate more data connectivity, potentially leveraging Wi-Fi and cloud-based data management to integrate with broader shop management systems.
Inside the Full Market Intelligence Report
To fully capitalize on these trends, decision-makers require more than high-level summaries. The complete Worldwide Wheel Balancer With Touchscreen Market research report offers a deep dive into the mechanics of this growth. The document is structured to provide immediate utility for strategic planning, procurement, and investment analysis.
Within the full scope of the study, readers will find detailed historical data spanning from 2020 to 2025, allowing for trend analysis and baseline validation. The forecast period extends through 2032, providing a long-term view for capacity planning and R&D investment cycles. The segmentation analysis goes beyond the macro splits to explore sub-segments within regions and application types, enabling precise targeting of market opportunities.
The competitive landscape section offers comprehensive profiles of key companies, including their headquarters, specific product offerings, and recent strategic developments. This includes an analysis of recent product launches, such as the Coats Company\'s 2025 release, and how these moves impact market share dynamics. Additionally, the report delves into industry context noise, covering raw material dependencies, regulatory impacts on consumables like balancing weights, and broader macro trends influencing automotive service demand.
By accessing the full report, stakeholders gain access to specific revenue unit data in millions of USD, precise CAGR calculations for different segments, and market concentration metrics such as CR3 and CR5 values. This level of detail is essential for building financial models, assessing competitor vulnerability, and identifying white space for new product introductions.
Conclusion
The Worldwide Wheel Balancer With Touchscreen Market is poised for steady and significant expansion through 2032. Driven by technological adoption, aftermarket growth, and the need for operational efficiency, the sector offers viable opportunities for those equipped with the right intelligence. However, navigating this landscape requires more than general awareness; it demands precise data and contextual analysis.
This overview has highlighted the key drivers, competitive forces, and strategic considerations defining the market in 2026. Yet, the true power of these insights lies in the details hidden within the complete dataset. For organizations committed to leading in this space, accessing the full report is the next logical step. PW Consulting remains dedicated to providing the depth of intelligence required to turn market complexity into competitive advantage.
For detailed analysis of this topic, please visit the official page: Worldwide Wheel Balancer With Touchscreen Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Canine Mammary Tumor Treatment Market Hits $845.5M in 2025, 7.58% CAGR to 2032
By pmarketresearch, 2026-09-16
Navigating the Future of Canine Mammary Tumor Treatment: Strategic Intelligence for 2026 and Beyond
The Imperative for Precision in Veterinary Oncology
The veterinary healthcare landscape is undergoing a profound transformation, driven by an increasing humanization of pets, rising disposable incomes, and an accelerating adoption of advanced therapeutic modalities. Within this evolving ecosystem, the management of canine mammary tumors represents a critical intersection of surgical standards, emerging targeted therapies, and comparative oncology research. For industry stakeholders, investors, and strategic decision-makers, understanding the trajectory of this market is no longer optional—it is a fundamental requirement for capitalizing on growth opportunities through 2032.
Our latest market intelligence report, Worldwide Canine Mammary Tumor Treatment Market, offers a comprehensive examination of the forces shaping this sector. This briefing serves as a strategic overview, synthesizing macro-level trends, competitive dynamics, and therapeutic shifts to equip leaders with the insights necessary to navigate the forecast period. The data underscores a robust expansion trajectory, reflecting both the maturation of established treatment pathways and the incremental integration of innovation into routine veterinary practice.
Market Trajectory and Historical Resilience
The global market for canine mammary tumor treatment has demonstrated consistent growth over the historical review period. Valued at approximately 590.25 million USD in 2020, the market has expanded steadily, reaching an estimated 845.5 million USD by 2025. This positive momentum reflects the sustained demand for effective interventions, the broadening acceptance of veterinary oncology as a specialized discipline, and the economic capacity of pet owners to pursue comprehensive care options.
Looking ahead, the forecast period from 2026 to 2032 projects continued expansion, with the market anticipated to surpass the 1.4 billion USD threshold by the end of the forecast window. The compound annual growth rate (CAGR) for this interval is estimated at 7.58, signaling a healthy, sustained upswing. This growth profile suggests that while the market is building upon a solid foundation of surgical and supportive care standards, there is significant headroom for value creation through therapeutic diversification and regional market development. Stakeholders evaluating entry points, investment allocations, or product pipeline prioritization will find this macro outlook essential for aligning long-term strategies with market realities.
Cancer Treatment Drugs Market
Therapeutic Modalities: Evolution Beyond the Surgical Standard
The treatment landscape for canine mammary tumors is anchored by well-established clinical protocols, yet it is increasingly characterized by a nuanced blending of modalities. Surgery remains the primary and gold-standard treatment, with the extent of resection dictated by tumor number, size, and staging. Adjuvant chemotherapy is typically reserved for advanced or high-risk malignant cases, ensuring that intervention is both targeted and clinically appropriate.
However, the strategic narrative is shifting as targeted and immunotherapy approaches gain traction in research and off-label applications. While no targeted small-molecule or biologic therapy has received full FDA approval specifically indicated for canine mammary tumors, the current environment relies heavily on the surgical standard supplemented by the off-label use of approved oncology drugs. This regulatory reality presents both a constraint and a catalyst. It limits the immediate rollout of designated therapies but simultaneously creates a fertile ground for innovation, comparative research, and the eventual expansion of labeled indications. Companies that can bridge the gap between off-label utilization and formal regulatory pathways are positioned to capture significant value as the market matures.
Cost structures also play a pivotal role in shaping adoption patterns. Surgical removal of a single mammary tumor in dogs typically ranges between 750 and 3,000 USD, depending on variables such as tumor size, location, dog weight, and clinic-specific factors. Additional tumors can add incremental costs, influencing treatment decisions and payer behavior. These economic realities underscore the importance of clear value propositions for adjunctive therapies and highlight the sensitivity of the market to affordability and clinical outcomes.
Geographical Dynamics and Regional Opportunities
The global footprint of the canine mammary tumor treatment market is characterized by distinct regional contributions, reflecting variations in veterinary infrastructure, pet ownership trends, and economic conditions. North America continues to command a substantial share, supported by advanced veterinary networks, high awareness levels, and a strong culture of pet healthcare expenditure. Europe follows as a significant contributor, driven by consolidated animal health markets and growing investment in veterinary oncology services.
Asia Pacific represents a dynamic growth corridor, where rapid urbanization, increasing pet adoption, and improving veterinary capabilities are accelerating market penetration. Latin America and the Middle East and Africa, while representing smaller absolute contributions in the current valuation, offer emerging potential as veterinary standards rise and access to specialized care expands. For global strategists, these regional disparities highlight the importance of tailored go-to-market approaches, localized pricing strategies, and partnerships that can navigate diverse regulatory and reimbursement environments. The interplay between mature markets and high-growth regions will define the competitive calculus for the next several years.
End-User Ecosystem: Where Value Is Delivered
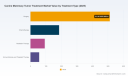
The distribution of treatment activity across end-user segments reveals critical insights into service delivery models and revenue concentration. Veterinary hospitals remain the dominant setting for intervention, leveraging comprehensive diagnostic capabilities, surgical expertise, and inpatient support. Specialty clinics contribute a significant and growing share, often serving as centers of excellence for advanced modalities, including radiation therapy and targeted treatment protocols. Academic and research institutes play a vital, albeit smaller, role in driving innovation, clinical trials, and the validation of emerging therapies.
This end-user landscape emphasizes the need for multi-channel engagement strategies. Companies developing therapeutic solutions, diagnostic tools, or service-based oncology offerings must account for the distinct procurement behaviors, clinical workflows, and decision-making units present in each setting. The convergence of standard care in hospitals with specialized innovation in clinics and research centers creates a complex but opportunity-rich environment for stakeholders that can align their offerings with the specific needs of each segment.
Competitive Landscape: Incumbents, Innovators, and Strategic Positioning
The market is defined by a competitive structure that blends established animal health giants with specialized oncology innovators and technology providers. Leading companies each bring distinct capabilities to the table, shaping the therapeutic and technological options available to veterinarians and pet owners.
Worldwide Canine Mammary Tumor Treatment Market
Zoetis Inc., headquartered in Parsippany, New Jersey, holds a prominent position through its oncology portfolio, including Palladia (toceranib phosphate), the first FDA-approved targeted therapy for canine cancers. While its primary indication centers on other malignancies, Palladia is utilized off-label or in supportive protocols for mammary tumors alongside chemotherapy and supportive care products, illustrating the cross-application potential of targeted agents in veterinary oncology. Boehringer Ingelheim Animal Health, based in Ingelheim am Rhein, Germany, provides a broad range of veterinary oncology and supportive care products, maintaining an active footprint in canine cancer management with treatments applicable to mammary tumor contexts.
Elanco Animal Health, located in Greenfield, Indiana, continues to expand its relevance through veterinary medicines and strategic acquisitions, such as Aratana, which have enriched its oncology portfolio with products used in canine cancer care, including mammary tumor settings. AB Science, headquartered in Paris, France, is advancing masitinib under brands such as Kinavet-CA1 and Masivet, a tyrosine kinase inhibitor with applications in canine cancers that is being explored for broader oncology use, including potential relevance to mammary tumors. Notably, in February 2026, the FDA granted a Minor Use in Major Species (MUMS) designation for Masivet in the treatment of canine mast cell tumors, a regulatory milestone that supports broader oncology development and signals pathway opportunities for related indications.
Technology, Precision Medicine, and the Research Frontier
Beyond pharmaceutical interventions, the competitive field includes technology and service innovators that are redefining treatment precision and accessibility. Karyopharm Therapeutics, based in Newton, Massachusetts, contributes to the targeted therapy landscape with verdinexor (Laverdia-CA1), a conditionally FDA-approved oral therapy for canine lymphoma, demonstrating the expanding scope of small-molecule options that are applicable across veterinary oncology, including mammary cases. VetDC Inc., in Fort Collins, Colorado, specializes in translating human oncology innovations to veterinary use, focusing on advancing therapies for canine cancers, including mammary tumor treatment, thereby bridging the translational gap between human and animal health.
PetCure Oncology provides advanced radiation oncology services and stereotactic radiosurgery for canine cancers, including treatment of mammary tumors, positioning itself as a service-oriented leader in localized, high-precision care. On the device side, Accuray Incorporated, in Sunnyvale, California, supplies precision radiotherapy systems such as CyberKnife and TomoTherapy, which are deployed in veterinary oncology centers for treating canine mammary tumors. Similarly, Varian Medical Systems, now part of Siemens Healthineers and headquartered in Palo Alto, California, offers radiotherapy and oncology solutions used in veterinary settings for non-surgical treatment of canine mammary tumors, reinforcing the role of advanced radiation platforms in the therapeutic mix.
FidoCure (One Health Company) introduces a precision medicine dimension by providing genomic testing-guided targeted therapies for canine cancers, including the identification of therapies effective against mammary gland tumors beyond established options like Palladia. This genomics-driven approach aligns with the broader industry shift toward personalized treatment selection. Meanwhile, CureLab Veterinary is developing Elenavet, a p62 plasmid-based immunotherapy, with initial application and proof-of-concept data in canine mammary tumors, representing an emerging immunotherapeutic frontier that could diversify the treatment armamentarium over time.
Research advancements continue to feed directly into clinical potential. Ongoing evaluation by the AKC Canine Health Foundation and Ohio State University, reported in early 2026, is examining Optical Coherence Tomography (OCT) for real-time intraoperative imaging to improve surgical margins and reduce recurrence in canine mammary tumor resection. Such innovations underscore the market's receptivity to tools that enhance surgical outcomes, lower complication rates, and improve long-term prognosis, all of which are critical drivers of stakeholder confidence and adoption.
Strategic Implications for Decision-Makers in 2026
As organizations plan for the 2026-2032 horizon, several strategic imperatives emerge from the market's structure and dynamics. First, the balance between established surgical standards and the gradual introduction of targeted, immunotherapeutic, and precision medicine approaches requires nuanced portfolio strategies. Companies must navigate the current reliance on off-label applications while preparing for the eventual maturation of labeled indications and companion diagnostics. Second, the concentration of market activity among a manageable set of leading players, with a combined share reflecting moderate but meaningful consolidation, suggests that competitive differentiation will increasingly depend on clinical evidence, service integration, and regional execution rather than volume alone.
Third, the comparative oncology paradigm—where canine mammary tumors serve as a spontaneous model for human breast cancer—creates a distinctive value proposition for research partnerships, translational pipelines, and cross-sector collaboration. This dynamic not only accelerates innovation but also opens channels for shared learnings, biomarker discovery, and therapeutic validation that can enhance product narratives and stakeholder engagement. Finally, the variability in regional maturity, end-user preferences, and cost sensitivity demands that strategies be calibrated to local realities. A one-size-fits-all approach is unlikely to capture the full opportunity set; instead, a segmented, evidence-led, and partnership-rich strategy will be essential for sustainable growth.
Access the Complete Intelligence Framework
This overview distills the strategic contours of the Worldwide Canine Mammary Tumor Treatment Market, emphasizing the macro trajectory, competitive forces, therapeutic evolution, and regional dynamics that define the landscape. However, the full depth of our analysis extends well beyond these high-level insights. The complete report provides a detailed segmentation framework across treatment types, end-user categories, and regional markets, supported by rigorous sizing, growth modeling, and scenario analysis. It also includes in-depth profiles of key companies, examinations of recent developments, and actionable recommendations for market entry, expansion, and competitive positioning.
To fully inform your 2026 decisions, we invite you to access the complete research. The detailed segmentation data, granular regional analysis, and comprehensive competitive profiling contained in the full report will enable you to move from strategic awareness to precise execution. Explore the full report to secure the intelligence needed to navigate this dynamic market with confidence and clarity.
For detailed analysis of this topic, please visit the official page: Worldwide Canine Mammary Tumor Treatment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Waterproof Phone Pouch Market Hits $450M in 2025, Projects 5.8% CAGR to 2032
By pmarketresearch, 2026-09-16
Navigating the Depths: Strategic Insights into the Worldwide Waterproof Phone Pouch Market 2026-2032
In an era where digital connectivity intersects with an increasingly adventurous lifestyle, the demand for reliable device protection has transcended niche utility to become a mainstream market imperative. As consumers take their smartphones into environments ranging from shallow beaches to deep-water professional operations, the waterproof phone pouch has emerged as a critical accessory. PW Consulting's latest comprehensive study, the Worldwide Waterproof Phone Pouch Market report, offers a definitive roadmap for stakeholders aiming to capitalize on this evolving landscape. This article serves as a strategic preview of the research, highlighting the macro-economic trajectories, competitive dynamics, and operational challenges that will define the sector through 2032.
Market Trajectory and Macro Growth Indicators
The global market for waterproof phone pouches has demonstrated resilient growth over the past half-decade, driven by a confluence of rising outdoor recreation participation and the increasing inherent value of consumer electronics. Our analysis covers historical performance from 2020 through 2025, establishing a solid baseline before projecting forward through the forecast period of 2026 to 2032.
In 2025, the market closed at a significant valuation, reflecting a steady accumulation of revenue since 2020. The trajectory indicates that the sector is not merely reacting to trends but is building sustainable momentum. Looking ahead, the forecast period suggests a continued expansion trajectory. The compound annual growth rate during the forecast window is projected at 5.8 percent. This growth rate underscores a mature yet expanding market where innovation and material science play pivotal roles in sustaining revenue streams.
Revenue scales are expected to climb substantially over the next seven years. Starting from the 2026 baseline, the market is poised to reach new highs by 2032. For strategic planners, this implies that the window for establishing market presence is open, but the competitive barrier to entry is rising alongside the market value. The sheer volume of revenue involved suggests that even marginal gains in market share can translate into significant financial outcomes for manufacturers and distributors alike.
Segmentation Dynamics: Type, Application, and Region
Understanding where revenue is generated is as crucial as knowing how much is generated. Our report dissects the market across three primary dimensions: product type, application scenario, and geographical region. Each segment presents unique value propositions and risk profiles.
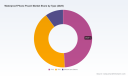
From a product type perspective, the market is divided among PVC, TPU, and Silicone and other materials. PVC continues to hold a substantial portion of the market share, largely due to its cost-effectiveness and established manufacturing supply chains. However, TPU is carving out a significant presence, appealing to consumers seeking flexible, durable, and often more environmentally conscious options. Silicone and other niche materials occupy a smaller but specialized segment, often catering to premium or specific functional use cases. The interplay between these material types is influenced by raw material pricing volatility and regulatory shifts, which we analyze in depth within the full report.
Application segmentation reveals how end-users interact with these products. Outdoor Activities remain a dominant driver of demand. This category encompasses beachgoers, swimmers, boaters, and adventure tourists who require reliable protection against water immersion. Daily Protection represents another substantial pillar, reflecting urban consumers who use waterproof pouches for peace of mind during rain or accidental spills. Professional Use, while smaller in relative volume, represents a high-value niche including marine researchers, industrial inspectors, and emergency responders who rely on these devices for critical operations.
Geographically, the market is balanced across major regions. North America and Europe maintain strong positions, driven by high consumer disposable income and established outdoor cultures. Asia Pacific presents a massive volume opportunity, fueled by manufacturing capabilities and a growing middle class with high smartphone penetration. Latin America and the Mideast and Africa regions, while currently smaller in aggregate revenue, offer growth potential as distribution networks expand and local outdoor economies develop. Our analysis avoids simplistic regional generalizations, instead focusing on the specific supply chain and demand drivers within each territory.
Competitive Landscape: Key Players and Strategic Positioning
The competitive environment is characterized by a mix of established outdoor protection brands and agile manufacturers focused on consumer accessibility. Market concentration remains relatively fragmented, with the top three players holding a modest share of the total market, indicating ample room for competition and innovation. The top five firms collectively hold less than a quarter of the market, suggesting that brand differentiation and product reliability are key battlegrounds rather than pure scale dominance.
Pelican Products, headquartered in Torrance, California, stands as a benchmark for rugged durability. Their Protector and Vault series are rated IPX8 for submersion up to 1 meter, positioning them heavily toward serious outdoor and marine users. In January 2025, Pelican launched the Air Case 1750, optimized for phone pouches with enhanced buoyancy for marine use. This move signals a strategic intent to capture the high-end marine segment where device loss is a significant financial risk.
Worldwide Waterproof Phone Pouch Market
OtterBox, based in Fort Collins, Colorado, leverages its reputation for rugged cases into the waterproof domain with their Frē series. These dry bags and universal waterproof phone cases offer protection up to 6.6 feet underwater. Demonstrating responsiveness to market cycles, OtterBox exhibited expanded Frē Series pouches compatible with the latest iPhone 16 at a CES 2025 preview in October 2024. This highlights the importance of aligning product portfolios with smartphone release schedules to capture early-adopter demand.
Lifeproof, located in Costa Mesa, California, manufactures the Nüüd and Frē waterproof pouches and cases submersible to 2 meters. Beyond basic waterproofing, Lifeproof achieved MIL-STD-810G certification for their new Frē Power waterproof pouch with integrated battery in August 2024. This certification adds a layer of military-grade assurance regarding shock and environmental resistance, appealing to professional and extreme outdoor users who demand reliability beyond standard water sealing.
On the competitive side, manufacturers based in Shenzhen, China, are driving volume and accessibility. Syncwire sells universal waterproof phone pouches with IPX8 rating specifically targeting beach and water sports use. Miady offers affordable IPX8 waterproof cellphone pouches fitting up to 6.5-inch smartphones, capturing the price-sensitive segment. Hiearcool provides roll-top closure waterproof phone dry bags rated for full submersion. These players highlight the global nature of the supply chain, where cost efficiency and rapid feature iteration compete alongside premium branding.
Industry Dynamics and Operational Headwinds
Strategic planning in this sector requires a clear view of the external forces shaking the supply chain and regulatory environment. Our report details several critical dynamics that are reshaping cost structures and compliance requirements.
Worldwide Mobile Phone Protective Cases Market
Raw material costs have become a significant variable. PVC prices for waterproof pouch production rose 8 percent year-over-year to $1,450 per metric ton due to supply chain disruptions. This increase directly impacts the margins of manufacturers relying on PVC-based products. Companies must decide whether to absorb these costs, pass them to consumers, or pivot material strategies. Simultaneously, labor costs in key manufacturing hubs are rising. Shenzhen manufacturing wages increased 6.5 percent to 25 CNY per hour, impacting pouch assembly costs. This dual pressure on materials and labor necessitates operational efficiency improvements or value engineering to maintain profitability.
Regulatory compliance is another critical vector. EU REACH regulations mandate phthalate-free PVC in consumer waterproof pouches effective January 2025. This regulation forces manufacturers exporting to or selling within Europe to reformulate their materials. Non-compliance carries the risk of market exclusion and reputational damage. Strategic firms are already adapting their supply chains to meet these standards, turning regulation into a competitive moat for those who can certify compliance early.
Quality assurance remains a persistent challenge. Over 15 waterproof pouch models were recalled in 2024 for zipper seal failures under ASTM F1306 testing. This statistic serves as a stark reminder that waterproofing claims must be backed by rigorous testing. For brands, product failure in this category is not just a financial loss but a breach of trust that can permanently alienate safety-conscious consumers. The prevalence of recalls underscores the need for robust QA protocols and potentially third-party certification to differentiate reliable products in a crowded market.
Strategic Value of the Full Report
While this overview sets the stage, the full Worldwide Waterproof Phone Pouch Market report provides the granular intelligence required to execute informed decisions. The document is designed for product managers, supply chain strategists, investors, and marketing leaders who need to move beyond macro trends to actionable specifics.
Inside the report, stakeholders will find detailed segmentation splits that quantify the revenue contributions of each region, type, and application without relying on estimates. These figures allow for precise market sizing and target identification. The competitive analysis goes further than company profiles, offering insights into market share dynamics, pricing strategies, and distribution channels used by the key players identified.
Furthermore, the report integrates the operational headwinds discussed earlier into a forward-looking risk assessment. Readers will understand how material cost trends and regulatory timelines might impact their specific product roadmaps. The inclusion of recent developments, such as product launches and certification updates, provides a timeline of innovation that helps companies anticipate competitor moves.
For organizations looking to enter or expand within this market, the data serves as a validation tool for investment cases. For incumbents, it offers a benchmark to assess their performance against the broader market growth and peer activities. The forecast period through 2032 allows for long-term capacity planning and R&D investment decisions, ensuring that strategies are aligned with the market's maturity curve.
Conclusion: Positioning for Sustainable Growth
The Worldwide Waterproof Phone Pouch Market is at an inflection point where growth is assured but competition is intensifying. The 5.8 percent CAGR through 2032 offers a compelling narrative for growth, but realizing value within that growth requires navigating material cost volatility, regulatory complexity, and a fragmented competitive field. Companies that prioritize material innovation, rigorous quality testing, and agile supply chain management will be best positioned to capture share.
PW Consulting's full market research report unlocks the detailed data and strategic frameworks necessary to turn these insights into execution. We invite industry leaders to access the complete study to gain the comprehensive intelligence needed to secure their position in this vital accessory market. The depths of the data await those ready to dive deeper into the opportunities shaping the future of waterproof phone protection.
For detailed analysis of this topic, please visit the official page: Worldwide Waterproof Phone Pouch Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: 2025 Revenue Hits $24.16B with 4.52% CAGR Outlook to 2032 in Pigment-grade TiO2
By pmarketresearch, 2026-09-16
Several Forces Are Reshaping the Global Pigment-grade Titanium Dioxide Market in 2026 and Beyond
Why This Comprehensive Market Research Matters for Strategic Decision Making
Our latest Worldwide Pigment-grade Titanium Dioxide Market report is designed for executives, procurement leaders, and investment strategists who need more than a static snapshot of today's prices. Built around a rigorous base year of 2025 and a detailed historical reconstruction spanning 2020 through 2025, this study places your decisions inside a forward-looking framework that extends through 2032. Rather than treating titanium dioxide as a single, undifferentiated commodity, the analysis maps the interplay of process technology, crystal structure, application demand, regional dynamics, and competitive behavior that will govern value creation over the next seven years. The overarching objective is simple: give leadership teams a tested vantage point for scenario planning, capacity evaluation, supply chain redesign, and portfolio prioritization in a market where structural shifts are happening faster than the traditional planning cycle.
The core revenue trajectory reflects a market that has already absorbed a full post-pandemic normalization cycle and is now building on a more stable footing. Historical sizing moved from roughly 19,342 million USD in 2020 to an estimated 24,158 million USD in 2025, with the path between those endpoints capturing both cyclical volatility and the gradual re-rating of demand fundamentals. Looking ahead, the analysis projects a sustained expansion that carries the market from approximately 25,676 million USD in 2026 toward more than 32,914 million USD by 2032. This pathway is supported by a forecast compound annual growth rate of 4.52 percent, a pace that is neither speculative nor conservative, but grounded in the cumulative effect of megatrend demand drivers, gradual capacity replumbing, and regional rebalances across the value chain.
Titanium Dioxide (TiO2) Market
What separates this report from generic market summaries is the way it turns those headline figures into decision-grade intelligence. The document does not ask you to accept an aggregate number and then guess the implications. Instead, it reconstructs how that aggregate is assembled by process routes, by crystal forms, by end-use applications, and by geography, then overlays the operational and regulatory pressures that will make or break individual segments. For strategists, this structure converts a broad top-line outlook into an actionable map of where margin, volume, and risk are likely to concentrate in the coming years.
Inside the Analysis: What Leaders Will Find in This Report
The report is organized around the practical questions that surface repeatedly in boardrooms, operating reviews, and procurement negotiations. For each commercial dimension, the analysis moves beyond descriptive market sizing to illuminate the strategic logic behind segment behavior, the levers that influence pricing power, and the operational constraints that shape future capacity deployment.
At the process level, the study separates sulfate and chloride routes as distinct strategic arenas rather than interchangeable production methods. Because these routes differ in feedstock flexibility, energy intensity, environmental footprint, and product-grade flexibility, understanding their relative share is essential for assessing supplier resilience, regional cost structures, and exposure to regulatory shifts. The chloride vs sulfate comparison is used throughout the report to frame questions about long-run competitiveness, plant economics, and the capacity decisions that will determine who can sustain scale without eroding margins.
Crystal Form Dynamics and the Rutile Dominance
The crystal structure dimension adds another layer of commercial granularity. The analysis tracks the dominance of rutile titanium dioxide alongside the specialized role of anatase titanium dioxide, showing how performance requirements, application tolerances, and end-user specifications drive material choice. Rather than treating crystal form as a technical footnote, the report evaluates how it shapes pricing tiers, customer segmentation, and the competitive positioning of producers who specialize in high-performance or niche grades versus those who compete primarily on volume and cost efficiency.
Application Fragmentation and Demand Stickiness
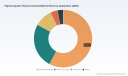
On the demand side, the report dissects the application landscape into the segments that matter most to commercial strategy, with special attention to how growth durability differs by use case. Paints and coatings represent the largest demand concentration and therefore the most important arena for volume and pricing dynamics. Plastics form a second major pillar, where pigment-grade titanium dioxide is evaluated not just as a colorant but as part of a broader formulation ecosystem influenced by automotive, consumer goods, and industrial specifications. Paper, printing inks, and a range of other applications are examined for their contribution to demand resilience, their sensitivity to substitution, and their relevance as either steady cash generators or tactical market entry points. For each application group, the analysis identifies the factors that can accelerate demand, compress it, or redirect it toward higher-value grades, allowing leaders to see where end-market durability supports capacity investment and where exposure is more cyclical.
Geographical Rebalancing and Regional Competitive Logic
The regional dimension is treated with similar commercial precision. The study maps the five major geographical arenas and examines how production concentration, import dependence, logistics costs, and local regulatory pressures affect supply security and competitive advantage. Because pigment-grade titanium dioxide is a globally traded material with meaningful regional cost and policy differentials, geographic positioning is not a background variable; it is a core determinant of margin, sourcing flexibility, and strategic bargaining power. The report uses these regional comparisons to help executives evaluate where local demand growth, export-oriented capacity, and trade-policy exposure will create the most consequential opportunities and vulnerabilities.
Throughout all of these segments, the report deliberately avoids asking readers to rely on isolated numbers taken out of context. Instead, it integrates the sizing framework with qualitative and operational intelligence: supply tightness from upstream ore markets, shifts in energy cost structures, compliance pressure from environmental regulation, and the timing of major corporate actions that alter competitive balance. That integration is what makes the forecast useful. It enables leaders to test how a change in raw material pricing, a new tariff regime, or a closure of older capacity would propagate through different segments before those changes become fully priced into the market.
The Competitive Field: Who Is Positioning Where and Why It Matters
Competitive strategy in this market depends on understanding how leading manufacturers differentiate themselves across technology, scale, geography, and application focus. The report profiles a field of major producers whose strategic choices are reshaping the market's structure and pricing behavior, and it uses those profiles to illuminate the kinds of moves that will matter most in 2026 and the years that follow.
Worldwide Pigment-grade Titanium Dioxide Market
Among global incumbents, The Chemours Company continues to anchor its strategy around the Ti-Pure brand for paints, coatings, plastics, and paper applications. Its recent launch of Ti-Pure R706, an optimized grade for water-based coatings with enhanced dispersibility, illustrates the broader industry shift toward formulation performance and regulatory-aware product development rather than volume expansion alone. Tronox Holdings extends its competitive reach through chloride-based production and a major expansion completed at its Botswana pigment-grade plant, adding significant annual capacity and underscoring the strategic importance of scale in key supply regions. Venator Materials PLC competes through specialty positioning with its TiONA and TiKON brands, targeting high-performance coatings and plastics where specification quality and customer integration can support differentiation. Kronos Worldwide remains a well-established supplier for architectural coatings, industrial finishes, and plastics, reinforcing the ongoing importance of brand trust and application consistency in a fragmented buyer environment.
The Chinese producers represent a different but equally important strategic logic. Lomon Billions Group operates at exceptional scale, with its R-996 and LM series extending into global paints and coatings markets, and its 2024 price increase announcement reflected the pressure of rising energy and raw material costs on global pricing behavior. CNNC Hua Yuan represents the high-end chloride-oriented export strategy, particularly relevant for coatings and plastics demand, while also highlighting the operational volatility that still affects parts of the Chinese supply base. Pangang Group Panzhihua Titanium shows the continued relevance of state-owned sulfate-process capacity for domestic and international paint and paper markets, a reminder that traditional routes still play a major role where cost, volume, and regional application needs align.
In Asia, the Japanese specialists Ishihara Sangyo Kaisha and Tayca Corporation illustrate a high-purity, specification-driven approach, with products like the CR-60 series and rutile grades such as R-550 serving automotive coatings, inks, and high-end plastics. In Europe, Precheza a.s. reinforces the regional specialty narrative through its PURENOL and PRETIOSA product lines for decorative paints and industrial coatings, where compliance sophistication and customer specificity matter as much as scale.
Together, these competitive profiles show a market where leadership is no longer defined solely by installed capacity. The analysis uses this competitive map to help readers identify which players are likely to defend margin through product architecture, which ones are pursuing regional capacity advantage, and where consolidation risk or disruption risk may emerge. Because the report keeps the focus on strategic posture rather than static rankings, it becomes a tool for benchmarking your own positioning against the moves that are actually shaping the next phase of the market.
Structural Realities Shaping 2026 Strategy
Any forward-looking strategy in pigment-grade titanium dioxide must account for the operational and policy forces that act as market accelerators or drags. The report integrates several of these structural realities as ongoing context for the forecast rather than as isolated news items, precisely because their effects are cumulative and often unevenly distributed across segments and regions.
Raw material conditions remain a central variable. Ilmenite ore prices averaged roughly 240 to 260 USD per metric ton in the fourth quarter of 2024, with a year-over-year increase of about 15 percent driven by supply tightness from Australia and South Africa. That kind of upstream pressure does not affect every producer equally, but it changes the cost floor for the industry and influences how aggressively capacity expansion can be justified. At the same time, electricity surcharges for titanium dioxide production in China rose by 10 to 15 percent in 2024 due to carbon emission controls, adding another layer of regional cost differentiation that strategists need to reflect in sourcing and capacity models.
Regulatory and policy developments matter just as much as cost trends. In China, the Ministry of Ecology and Environment enforced the elimination of 200,000 tons of backward sulfate-process titanium dioxide capacity by the end of 2024, a move that compresses older, less efficient supply and alters the competitive balance between process routes. In Europe, REACH compliance updates have introduced Annex XVII restrictions on nano forms for pigment-grade titanium dioxide imports, effective from 2024, which affects formulation design and market access strategies for producers serving the EU. In the United States, Section 301 tariffs on Chinese pigment-grade titanium dioxide imports remain at 25 percent as of 2025, with meaningful exposure across the supply base. That tariff environment changes sourcing logic, supplier diversification priorities, and the relative attractiveness of non-Chinese capacity for buyers who must manage landed cost and supply continuity together.
Operational volatility still punctuates an otherwise maturing market. The force majeure declaration by CNNC Hua Yuan in December 2023, related to winter production restrictions in China, is a useful reminder that even large-scale producers can face episodic constraints that ripple into availability and pricing. Similarly, Tronox's completion of its Botswana expansion in August 2024, adding 50,000 tons of annual capacity, demonstrates how targeted capacity additions can shift regional supply balances and influence competitive expectations. When these events are read alongside the broader market trajectory, they help explain why a forecast of steady growth does not imply a smooth path for every participant.
Using This Report to Strengthen Enterprise Decisions
The real value of this study lies in how it supports concrete decision-making across several functions. For procurement and supply chain leaders, the segmentation and regional analysis helps identify where sourcing diversification, contract structure, and supplier evaluation criteria should be adjusted in response to process mix, tariff exposure, and energy-driven cost shifts. For commercial and product strategy teams, the application and crystal-form analysis provides a basis for anticipating where demand will reward specification improvement versus where price competition will dominate. For corporate development and investment teams, the competitive profiles and recent developments offer a framework for evaluating acquisition targets, capacity partnerships, and market-entry strategies with a clearer sense of who is expanding, who is differentiating, and where structural constraints may limit return.
The report is designed to be used as a living reference point, not a one-time download. Its structure supports scenario testing, supplier benchmarking, and regional strategy comparison, allowing leadership teams to connect the aggregate market outlook to the operational realities that govern execution. By keeping the focus on decision-relevant integration rather than isolated data points, the analysis helps organizations prepare for a market environment in which growth is real, competition is intensifying, and the cost and policy landscape is changing fast enough to reward those who plan with precision.
Why the Full Intelligence Set Is Essential for 2026 Planning
A market of this scale and complexity cannot be managed effectively on the strength of a single headline number or a partial view of regional or application trends. The strategic picture only becomes actionable when the forecast is tied to the underlying segmentation logic, the competitive dynamics, and the structural pressures that determine how value is distributed across the value chain. The full version of the Worldwide Pigment-grade Titanium Dioxide Market report delivers that integrated picture with the level of operational detail required for serious planning. It provides the segment-level context, the company-level strategic positioning, and the policy-driven market dynamics that executives need to translate a 4.52 percent growth trajectory into practical choices about sourcing, investment, pricing, and market focus. For organizations that want to move from general market awareness to executable strategy, the complete analysis is the necessary next step.
For detailed analysis of this topic, please visit the official page: Worldwide Pigment-grade Titanium Dioxide Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Shows Worldwide Nuclear LED Market Hits $385.5M in 2025, Forecasted to Reach $573.9M by 2032
By pmarketresearch, 2026-09-16
Navigating the Nuclear Light: Strategic Imperatives in the 2026 Global Nuclear Grade LED Lighting Market
The global nuclear grade LED lighting market stands at a critical inflection point. As nuclear facilities worldwide confront aging infrastructure, stringent safety regulations, and the pressing need for operational resilience, illumination systems have evolved from passive utilities into mission-critical safety components. Our latest Worldwide Nuclear Grade LED Lighting Market research delivers a comprehensive, data-driven roadmap for executives navigating this highly specialized sector. Spanning historical performance from 2020 through 2025 and extending forward to 2032, the study quantifies market trajectories, dissects competitive dynamics, and maps the regulatory and technological forces that will define procurement strategies and capital allocation decisions in the years ahead.
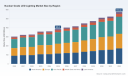
For corporate leaders responsible for facility modernization, supply chain resilience, or strategic R&D investment, this intelligence is not merely observational. It is a decision-enabling asset. The market, valued at USD 385.5 million in 2025, is projected to expand steadily to approximately USD 573.94 million by 2032, reflecting a compound annual growth rate of 5.85 percent. These figures are more than historical snapshots; they represent the underlying momentum of a sector where reliability, compliance, and technological specialization directly translate into commercial advantage. Understanding the structural drivers behind this trajectory is essential for organizations seeking to align product development, partnership strategies, and market entry initiatives with the realities of 2026 and beyond.
Market Evolution and Structural Foundations
Over the past half-decade, the nuclear grade lighting landscape has transitioned from incremental component upgrades to systematic, engineered lighting ecosystems. Historical revenue progression reveals consistent expansion: from USD 302.15 million in 2020 to USD 360.3 million in 2024, before accelerating to USD 385.5 million in 2025. This growth pattern underscores a sector that has moved beyond niche procurement cycles into sustained, demand-driven adoption. The forecasted expansion toward USD 402.45 million in 2026 and USD 511.06 million by 2030 signals that capital investment in radiation-tolerant, seismically qualified, and emergency-capable illumination is no longer discretionary. It is a foundational requirement for operational continuity.
The market's structural composition reflects this specialization. Segmentation across lighting intensity classifications reveals a dominant share allocated to moderate-radiation environment lighting, complemented by substantial allocations to high-radiation and low-radiation categories. This distribution indicates that procurement strategies are increasingly calibrated to specific operational zones within nuclear facilities, rather than relying on uniform, off-the-shelf solutions. Similarly, application-level segmentation highlights that primary deployment centers on nuclear power generation, supported by dedicated allocations for nuclear research reactors and nuclear waste and fuel management. These structural patterns demonstrate that end-user requirements are fragmenting into highly differentiated technical specifications, requiring vendors and buyers alike to move beyond generic product catalogs and engage in application-specific engineering alignment.
Regional distribution further illustrates the global footprint of this market. North America, Europe, and Asia Pacific collectively anchor the majority of demand, underscoring the need for multi-jurisdictional compliance capabilities, localized manufacturing footprints, and region-specific certification pathways. The presence of smaller but strategically meaningful allocations across the Middle East and Africa and Latin America suggests emerging procurement corridors where infrastructure development and facility modernization programs are beginning to drive specialized lighting requirements. For executives evaluating geographic expansion or supply chain diversification, understanding these regional demand architectures is essential to optimizing inventory positioning, regulatory alignment, and partnership networks.
Nuclear Valves Market
Regulatory Architecture and Technical Imperatives
In the nuclear sector, illumination is never a standalone specification. It is embedded within a dense regulatory and engineering framework that dictates material selection, testing protocols, and lifecycle performance expectations. Market participants must navigate seismic qualification standards, radiation tolerance thresholds, electromagnetic compatibility requirements, and extended emergency illumination mandates. Lighting fixtures deployed in containment areas and high-radiation zones must satisfy seismic qualification benchmarks such as those defined by IEEE-344, while also delivering prolonged emergency illumination capabilities that exceed post-incident safe shutdown requirements. These standards are not optional enhancements; they are compliance prerequisites that directly influence product design, qualification cycles, and procurement eligibility.
Radiation hardening represents another defining technical boundary. Gamma-tested luminaires engineered to withstand substantial cumulative dose exposures, including testing protocols validated at specialized facilities, illustrate the level of verification required for deployment in high-radiation environments. Compatibility with loss-of-coolant accident scenarios, the integration of radiation-tolerant electronic components, and the elimination of external driver shielding dependencies are all critical design considerations that separate qualified nuclear-grade solutions from conventional industrial lighting. Material engineering further reinforces these requirements. Stainless steel housings, smooth decontaminable surfaces, and components rated for extreme cumulative radiation exposure ensure that fixtures maintain structural integrity and operational performance under continuous environmental stress.
Quality assurance frameworks add another layer of complexity. United States nuclear facilities operate under structured quality programs and regulatory oversight that mandate rigorous documentation, traceability, and performance validation across radiation tolerance, seismic resistance, and electromagnetic compatibility dimensions. Emergency response infrastructure further intersects with environmental control standards that indirectly shape lighting system design, requiring coordinated reliability and safety planning. For manufacturers, engineering firms, and procurement teams, these regulatory intersections create both barriers to entry and opportunities for differentiation. Companies that internalize compliance as a core design principle, rather than treating it as a post-development validation step, are better positioned to secure long-term contracts, reduce qualification friction, and build trusted relationships with nuclear operators.
Competitive Landscape and Market Concentration
The competitive dynamics of this market reflect a concentrated yet highly specialized vendor ecosystem. With the top three firms collectively accounting for approximately 38.5 percent of market revenue and the top five firms representing roughly 52.4 percent, the landscape is defined by a balance of established technical leadership and agile innovation. This concentration indicates that scale alone does not guarantee market share; instead, proprietary radiation-hardening capabilities, in-house manufacturing integration, certification track records, and application-specific engineering expertise are the primary competitive differentiators.
Leading participants demonstrate the breadth of this specialization. DITO Lighting focuses on ultra radiation-resistant luminaires engineered for both air and underwater applications within nuclear power plants, emphasizing integrated driver architectures, accident condition compatibility, and vertically controlled design and manufacturing processes. Recent product evolution highlights the sector's iterative innovation pace, with model enhancements incorporating advanced chip-on-board LED configurations, redesigned mechanical housings for improved thermal and photometric performance, and enhanced safety features including thermal protection and operational mode optimization. Series consolidation strategies further illustrate how vendors streamline product architectures to reduce complexity while preserving application coverage.
Worldwide Nuclear Grade LED Lighting Market
Luminos Nuclear, operating through its affiliated engineering framework, manufactures gamma radiation-hardened luminaires validated through rigorous testing protocols and deployed across nuclear plants, research laboratories, and other high-radiation settings. Their portfolio spans stainless steel constructions and emergency variants, with end-to-end in-house production spanning mechanical, LED, and driver integration. Ahlberg Cameras contributes high-performance radiation-tolerant illumination solutions optimized for pool environments, containment areas, and hot cell operations, reinforcing the safety-critical role of reliable lighting in surveillance, maintenance, and personnel movement contexts. BIRNS, Inc. offers nuclear-grade LED systems including high-ceiling containment floodlights engineered for extreme radiation tolerance and seismically qualified emergency lighting fixtures capable of sustaining extended illumination durations, aligning product design with U.S. regulatory expectations for post-event operational safety.
Additional participants expand the competitive perimeter across specialized use cases and manufacturing philosophies. AO Sosny R&D Company develops radiation-resistant lighting engineered for hot cells, canyon spaces, underground areas, and maintenance zones within nuclear facilities, emphasizing high-input-power configurations suited to demanding operational environments. G&G Industrial Lighting produces compact radiation-resistant luminaires tolerant of accelerator-level radiation conditions, leveraging United States-based manufacturing and zero-maintenance design principles to address lifecycle cost concerns. Homewood Energy Services manufactures nuclear-grade emergency lighting fixtures governed by structured quality programs, incorporating maintenance-free battery architectures and seismic qualification to meet institutional compliance expectations. Martek Lighting supplies customized illumination solutions across nuclear, hydro, and thermal generation environments, emphasizing regulatory alignment, maintenance reduction, and operational cost optimization. LED Lighting Supply provides nuclear-grade systems engineered for radiation resistance, seismic and impact resilience, electromagnetic compatibility, and extended operational lifespans tailored to power generation facilities.
Together, these participants illustrate a market where technical credibility, certification depth, and application-specific engineering outweigh generic commercial positioning. For strategic decision-makers, this means that vendor evaluation must extend beyond catalog specifications to encompass testing documentation, qualification histories, integration capabilities, and long-term support structures. The competitive advantage will increasingly accrue to organizations that can demonstrate verifiable performance under operational stress while maintaining supply chain transparency and lifecycle service reliability.
Strategic Implications for 2026 Decision-Makers
The convergence of expanding market scale, tightening regulatory expectations, and increasingly specialized technical requirements creates a complex decision environment for 2026. Organizations operating in or adjacent to the nuclear sector must approach illumination strategy not as a procurement transaction but as a long-term operational resilience investment. Several strategic implications warrant close attention.
- Compliance as a design foundation. Seismic qualification, radiation tolerance, emergency illumination duration, and electromagnetic compatibility are no longer peripheral features. They are core design parameters that influence product architecture, qualification timelines, and market access. Procurement strategies should prioritize vendors with documented compliance frameworks and transparent testing validation rather than relying on generalized performance claims.
- Application-specific engineering alignment. As segmentation across radiation intensity levels and application domains becomes more pronounced, standardized lighting deployments will face growing operational limitations. Decision-makers should evaluate lighting solutions against zone-specific requirements, balancing radiation exposure profiles, maintenance access constraints, and emergency response integration to ensure functional alignment with facility operations.
- Lifecycle cost and maintenance architecture. The push toward zero-maintenance designs, extended operational lifespans, and maintenance-free backup systems reflects a broader industry shift toward total cost of ownership optimization. Capital expenditure decisions should incorporate long-term service reduction, replacement cycle forecasts, and operational downtime avoidance rather than focusing exclusively on initial purchase price.
- Supply chain resilience and regional compliance. With demand anchored across multiple major regions and supported by emerging procurement corridors, geographic diversification and localized manufacturing or certification capabilities can reduce regulatory friction and improve responsiveness. Organizations should assess vendor manufacturing footprints, documentation standards, and regional certification alignment as part of broader supply chain risk management.
- Technology integration and continuous innovation. Recent product iterations, including advanced LED integration, housing redesigns for mechanical and thermal stability, and series consolidation for unified application coverage, indicate that competitive differentiation will continue to emerge from engineering refinement rather than market expansion alone. Monitoring product evolution pathways and vendor R&D focus areas can inform partnership selection, specification updates, and forward-looking capital planning.
For investors, manufacturers, engineering integrators, and nuclear operators, the strategic question is no longer whether specialized illumination matters, but how to structure procurement, partnership, and innovation strategies around a market that increasingly rewards verifiable performance, regulatory fluency, and lifecycle reliability. Organizations that treat lighting as an integrated safety and operational system, rather than a discrete equipment purchase, will be better positioned to manage compliance exposure, reduce operational risk, and capture value in a steadily expanding market environment.
What the Full Study Delivers
This overview establishes the strategic context, but the complete Worldwide Nuclear Grade LED Lighting Market research provides the granular intelligence required to translate industry awareness into executable decision-making. The study maps historical revenue progression and forward-looking forecasts across the full 2020 to 2032 horizon, offering a structured view of growth momentum and market timing. It dissects segmentation dynamics across lighting intensity classifications, application domains, and regional demand architectures, enabling stakeholders to identify where procurement emphasis, engineering focus, and commercial opportunity are most concentrated.
Beyond market sizing, the research delivers detailed competitive profiling, including company-specific capabilities, product architecture strategies, testing and certification positions, and recent development activity that signals evolving technological priorities. It integrates regulatory and technical dynamics, clarifying how seismic qualification standards, radiation testing protocols, emergency illumination mandates, material engineering requirements, and quality assurance frameworks shape product eligibility and market access. This combination of market structure, competitive intelligence, and regulatory context equips executives with a comprehensive reference point for evaluating vendor landscapes, planning specification updates, assessing partnership opportunities, and aligning capital allocation with the operational realities of nuclear environments.
The full report is designed to support scenario planning, specification optimization, and strategic positioning across the 2026 to 2032 forecast window. By connecting macro growth trajectories with micro-level technical and competitive detail, it enables organizations to move from general market awareness to targeted, actionable intelligence.
Accessing the Complete Intelligence
The nuclear grade LED lighting market is entering a phase where technical precision, regulatory alignment, and strategic procurement discipline will separate long-term winners from reactive participants. The 2026 decision environment demands more than high-level market awareness. It requires verified data, structured segmentation insight, and competitive context that can inform specification, sourcing, and investment choices with confidence.
To secure the complete dataset, detailed segmentation breakdowns, full competitive profiles, and forward-looking scenario analysis, access the full Worldwide Nuclear Grade LED Lighting Market research report. The comprehensive study provides the depth and structure necessary to translate industry trajectory into concrete corporate strategy.
For detailed analysis of this topic, please visit the official page: Worldwide Nuclear Grade LED Lighting Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Solenoid Reversing Valve Market Hits $962.46M in 2025, Poised for $1.38B by 2032
By pmarketresearch, 2026-09-16
Strategic Imperatives in the Global Solenoid Reversing Valve Market: A 2026 Outlook
The global solenoid reversing valve industry stands at a critical inflection point. Driven by an accelerating energy transition, tightening refrigerant regulations, and sustained HVAC modernization programs across both developed and emerging economies, demand for precision switching components is evolving faster than traditional procurement cycles can accommodate. For engineering leaders, procurement directors, and corporate strategists navigating 2026 decision-making windows, understanding the trajectory of this sector is no longer optional. It is a foundational requirement for capital allocation, supply chain resilience, and product roadmap alignment.
Our newly released Worldwide Solenoid Reversing Valve Market study delivers a comprehensive, data-grounded examination of the sector from 2020 through 2032. Built for practitioners who require actionable intelligence rather than high-level projections, the report maps historical performance, forecasts demand under multiple adoption scenarios, and dissects the competitive dynamics shaping procurement leverage and innovation pipelines. Below, we outline the strategic architecture of the research and highlight the key themes that will define market participation in the coming years.
Historical Baseline and Forward Trajectory
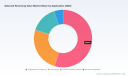
The solenoid reversing valve market has demonstrated consistent expansion over the past half-decade, anchored by structural demand from climate control equipment and industrial fluid power applications. Between 2020 and 2025, global revenue climbed from approximately 745.2 million USD to 962.46 million USD, reflecting a compound annual growth rate that underscores the sector's resilience against supply chain disruptions and raw material volatility. The forecast horizon extends this trajectory through 2032, with market sizing indicating continued upward momentum as heat pump penetration accelerates and commercial refrigeration networks undergo refrigerant transition upgrades.
The projected CAGR of 5.24 percent across the 2026 to 2032 forecast window reflects a market that is growing steadily rather than explosively, a profile that rewards disciplined portfolio management and long-term supplier relationships over speculative inventory positioning. Forecasts anticipate market valuation crossing the 1.3 billion USD threshold by the end of the decade, with intermediate milestones highlighting the pacing of adoption across HVAC retrofits, new residential builds, and industrial automation deployments. These figures provide a baseline for scenario planning, enabling organizations to calibrate production capacity, inventory buffers, and regional distribution strategies against a quantifiable demand curve.
Importantly, the macro trajectory does not obscure near-term friction. Fluctuations in base material costs, particularly steel, have introduced variability into component manufacturing economics. Spot pricing for hot rolled coil in the United States has moved within a defined band over the past year, stabilizing amid trade policy uncertainty before climbing again in early 2026 as mill pricing actions and industrial demand intersect. These input cost dynamics influence valve body fabrication, housing production, and downstream margin structures, making material price intelligence a necessary complement to demand forecasting in operational planning.
Structural Demand Drivers and Technology Shifts
The thematic core of the market's expansion rests on the convergence of energy efficiency mandates and refrigerant compliance requirements. Heat pump systems have emerged as a primary growth vector, with adoption rates climbing across residential and light commercial segments as building codes tighten and electrification incentives take effect. This shift places direct pressure on four-way and three-way reversing valve design specifications, particularly regarding compatibility with low-GWP refrigerants and natural refrigerant blends. Manufacturers that can deliver reliable cycle reversal performance while meeting maximum operating pressure thresholds and UL recognition standards are positioned to capture premium positioning in specification-driven procurement environments.
Residential air conditioning and heat pump installations continue to represent the largest application concentration, but commercial HVAC systems and industrial refrigeration are generating meaningful incremental volume as facility operators modernize aging equipment and align with decarbonization targets. The solenoid reversing valve's role in directional control for refrigerant circuits, pneumatic automation lines, and hydraulic machinery means the market is inherently cross-sectoral. Yet the growth composition is uneven, with certain applications benefiting from faster replacement cycles and others facing longer capital approval timelines. Understanding where volume concentration sits, and how that concentration shifts as regulatory deadlines approach, is essential for prioritizing sales coverage, service support, and engineering customization resources.
Solenoid Valves Market
Technology evolution is also reshaping competitive expectations. Stainless steel configurations, advanced PTFE and metal slide mechanisms, and intelligent control integration are becoming differentiators rather than optional enhancements. The transition toward next-generation valve architectures is not merely a product line extension; it reflects a broader industry push toward durability in harsh operating environments, reduced leakage profiles, and compatibility with the refrigerant chemistry that will dominate the next decade of HVAC and refrigeration deployment. Organizations that map their development pipelines against these specification trends will be better equipped to negotiate with specifiers and capture design-in opportunities early in the equipment development cycle.
Competitive Architecture and Strategic Positioning
The market exhibits a concentrated competitive landscape, with a small group of established players commanding a substantial share of total revenue. High concentration levels indicate that scale advantages, brand recognition in specification channels, and entrenched service networks create meaningful barriers for new entrants. At the same time, the composition of leadership varies by application domain, with certain organizations dominating HVAC and heat pump reversing solutions while others maintain strong positions in industrial hydraulics, pneumatics, and mobile fluid power.
Sanhua Holding Group has solidified its reputation as a leading global supplier of four-way reversing valves for HVAC and heat pump applications, offering both the established SHF series and next-generation SHF-G stainless steel models engineered for compatibility with common HFC/HCFC refrigerants and natural refrigerant alternatives. The company's recent product introductions and trade show participation underscore a strategy centered on expanding material ranges, improving performance in heat pump duty cycles, and aligning with intelligent control ecosystems. This approach reflects the broader competitive reality that reversing valve suppliers must now engage with system-level integration requirements, not just component-level specifications.
Danfoss continues to offer a broad portfolio of solenoid valves and reversing solutions for refrigeration and air conditioning, with EVR solenoid valves and four-way reversing configurations that address both commercial and industrial cooling architectures. Parker Hannifin maintains a strong footprint in hydraulic and pneumatic solenoid reversing valves, including directional control products for industrial and mobile applications, while Bosch Rexroth supplies hydraulic solenoid reversing valves and directional control platforms such as the 4WE series for industrial machinery. Robertshaw and Wilspec focus more narrowly on heat pump reversing valves for residential and commercial HVAC systems, with Robertshaw emphasizing PTFE and metal slide mechanisms and Wilspec building a reputation in geothermal and seasonal switching applications where durable configurations are critical.
Regional and application-specific specialists further shape the landscape. DunAn produces reversing valves and electromagnetic four-way solutions for HVAC and refrigeration networks. SMC Corporation delivers pneumatic solenoid valves and directional control products that function as reversing components in automation environments. ASCO, operating under Emerson, provides solenoid valves and control solutions with directional configurations applicable to fluid power reversing setups. Shandong Yikaide Hydraulic Co., Ltd. concentrates on hydraulic solenoid reversing valves for industrial hydraulic systems. The diversity of this roster highlights a market in which competitive advantage is frequently derived from application specialization, regional distribution strength, and the ability to meet distinct certification and pressure-rating requirements across geographies.
Recent corporate activity reinforces the pace of innovation. In late 2025, Sanhua introduced its next-generation SHF-G series four-way reversing valves with an expanded stainless steel range designed to improve performance in heat pump systems. In early 2026, the company showcased intelligent control technologies, including reversing valve solutions, at a major industry exposition. These moves illustrate how leading suppliers are synchronizing product upgrades with system-level intelligence, a pattern that procurement teams should monitor as they evaluate supplier roadmaps and total cost of ownership assumptions.
Regulatory, Material, and Operational Dynamics
Market performance cannot be separated from the compliance and input cost environment. Reversing valves deployed in heat pump and HVAC applications must satisfy UL recognition and adhere to maximum operating pressure ratings, such as the 650 psig threshold commonly referenced for compatibility with HFC refrigerants in global markets. These requirements influence material selection, manufacturing tolerances, and validation testing cycles. As refrigerant transitions accelerate, suppliers that can demonstrate compliance with evolving pressure and fluid compatibility specifications while maintaining manufacturing throughput will hold a distinct advantage in specification capture and aftermarket support.
On the input side, steel pricing remains a central variable for valve body and component production. Recent price movements have cycled through a stabilization phase before resuming an upward trajectory, driven by mill pricing adjustments and demand from construction and industrial sectors that overlap with solenoid valve manufacturing supply chains. Organizations with diversified sourcing strategies, forward procurement contracts, or design flexibility to accommodate alternate material grades are better positioned to absorb cost volatility without eroding margin expectations. For downstream equipment manufacturers, this underscores the value of supplier partnerships that provide transparency on material pass-through mechanisms and lead-time reliability.
Worldwide Solenoid Reversing Valve Market
Beyond pricing and compliance, the broader market dynamic is being shaped by the increasing adoption of heat pump systems for energy-efficient heating and cooling. This trend directly drives demand for reliable four-way solenoid reversing valves that can operate reliably with low-GWP and natural refrigerants. As building owners, OEMs, and integrators align procurement with sustainability targets, the reversing valve is transitioning from a commodity-adjacent component to a specification-critical element whose performance characteristics influence system efficiency claims, warranty exposure, and end-user satisfaction. Strategic buyers are responding by tightening qualification criteria, expanding field reliability benchmarks, and placing greater weight on supplier track records in refrigerant transition scenarios.
What the Full Study Delivers
The Worldwide Solenoid Reversing Valve Market research is structured to translate macro trends into operational guidance. Rather than offering a single aggregate figure, the report decomposes market size across product configurations, application categories, and regional demand centers, allowing readers to identify where volume concentration, growth pacing, and competitive intensity intersect. The segmentation analysis clarifies how different valve architectures and end-use environments contribute to total market value, enabling more precise capacity planning, channel strategy, and product mix decisions.
The study also maps the competitive environment in detail, profiling the leading organizations that define pricing norms, specification standards, and innovation velocity. Company-level assessments cover product portfolio scope, application focus, geographic presence, and recent strategic actions, providing a practical reference for supplier evaluation, partnership screening, and competitive benchmarking. Beyond company profiles, the report integrates industry context spanning raw material conditions, regulatory specifications, and macro adoption trends, ensuring that readers can interpret market size and share data within the operational realities that shape procurement and production decisions.
Forecast content extends across a multi-year horizon, giving strategists a structured basis for scenario planning. Historical data establishes the baseline trajectory, while forward projections support demand modeling for new product introductions, regional expansion initiatives, and inventory strategy. The research is designed to serve cross-functional audiences, from R&D and product management teams evaluating design-in opportunities to supply chain leaders stress-testing supplier resilience and commercial teams calibrating market entry or share-gain plans.
Strategic Implications for 2026 Decision-Makers
For organizations operating in or adjacent to the solenoid reversing valve market, the 2026 landscape rewards precision over generalization. The convergence of heat pump adoption, refrigerant transition requirements, and concentrated supplier dynamics means that procurement strategy, product specification, and supplier selection must be informed by granular market intelligence rather than broad industry narratives. Companies that understand how demand is distributed across applications and regions, which suppliers are advancing material and control innovations, and how compliance and input cost pressures affect total cost of ownership will be better positioned to protect margins and capture growth.
The full report provides the depth required to translate these themes into concrete plans. It offers the segmentation breakdowns, competitive profiles, and forward forecasts necessary to support capital allocation, sourcing strategy, and technology roadmap decisions with confidence. For executives and analysts preparing for the remainder of the decade, the study serves as both a diagnostic baseline and a planning framework, connecting historical performance to forward demand in a manner that supports disciplined, evidence-based strategy.
Access the complete Worldwide Solenoid Reversing Valve Market research to obtain the full set of market size estimates, segmentation splits, competitive assessments, and forward projections that underpin the analysis presented here. The detailed intelligence contained in the report is intended to support high-stakes decision-making across product development, procurement, sales strategy, and regional expansion planning throughout 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Worldwide Solenoid Reversing Valve Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Packaging Outsert and Inserts Market to Reach $6.95B by 2032 Amid 6.0% CAGR
By pmarketresearch, 2026-09-16
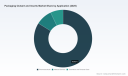
Strategic Intelligence for 2026: Navigating the Packaging Outsert and Inserts Market
In the rapidly evolving landscape of pharmaceutical and healthcare packaging, the packaging outsert and inserts market stands as a critical nexus of regulatory compliance, patient safety, and supply chain efficiency. As we move through 2026, industry leaders face a complex matrix of challenges ranging from raw material volatility to stringent new environmental regulations. Understanding the trajectory of this sector is not merely an exercise in market sizing; it is a strategic imperative for operations, procurement, and long-term planning. This article serves as a precursor to our comprehensive market research report, designed to equip decision-makers with the high-level insights necessary to navigate the forecast period through 2032.
The market has demonstrated remarkable resilience and growth over the past half-decade. Historical data from 2020 through 2025 indicates a steady upward trajectory, reflecting the expanding complexity of pharmaceutical products and the non-negotiable requirement for clear patient information. Looking ahead, the forecast period from 2026 to 2032 projects continued expansion, driven by the increasing volume of healthcare products requiring secondary packaging documentation. This growth is not linear; it is punctuated by technological advancements, regulatory shifts, and changing consumption patterns across key global regions. Our latest study dissect this evolution, offering a granular view of where value is being created and where risks are accumulating.
Macro Market Dynamics and Performance Trajectory
Analyzing the historical performance provides a baseline for understanding the scale of opportunity. Between 2020 and 2025, the market capitalized on heightened healthcare demands and entrenched regulatory frameworks requiring detailed patient information leaflets. The transition from historical years into the current forecast period reveals a market that is consolidating its position while adapting to new constraints. The projected compound annual growth rate indicates a steady expansion pace, suggesting that demand for outsert and inserts remains inelastic relative to price fluctuations in the short term, owing to its critical role in drug safety and compliance.
However, growth does not occur in a vacuum. The market size at the base year of 2025 established a significant valuation, setting the stage for the forecast period. As we project forward to 2032, the market is expected to reach new valuation heights. This growth is influenced by several factors, including the proliferation of specialized medical treatments that require detailed Instructions for Use (IFUs) and the global push for multilingual packaging to support international distribution. Yet, this expansion is tempered by cost pressures and regulatory tightening, creating a divergent environment where efficiency and compliance are the primary differentiators for market participants.
Segmentation Insights and Material Constraints
The market is structurally defined by its segmentation across type, application, and geography. By type, the division between outsert and inserts represents distinct manufacturing processes and logistical considerations. Outserts, often utilized for primary safety information or outer carton labeling, and inserts, which provide detailed internal documentation, serve complementary roles in the pharmaceutical supply chain. The balance between these two segments influences production capacity requirements and inventory management strategies for manufacturers. Understanding the relative demand drivers for each type is crucial for optimizing production lines and managing supply chain resilience.
In terms of application, the pharmaceutical sector dominates the landscape, reflecting the stringent regulatory requirements associated with drug distribution. Medical devices and cosmetics also constitute significant portions of the market, each with unique compliance profiles. The pharmaceutical application segment drives the majority of volume, necessitating high-precision folding, serialization, and adherence to FDA and international standards. Meanwhile, the medical device and cosmetics sectors introduce additional complexity regarding material safety and user interface design, requiring versatile manufacturing capabilities from suppliers.
Geographically, the market distributes demand across major regions including North America, Europe, Asia Pacific, and the Rest of World. Each region presents distinct regulatory environments and supply chain dynamics. North America and Europe remain mature markets with high compliance standards, while Asia Pacific represents a growing hub for manufacturing and consumption. The distribution of market share across these regions underscores the importance of localized compliance strategies and supply chain agility. A procurement strategy focused solely on one region may expose companies to volatility elsewhere, making a diversified supply base increasingly valuable.
Regulatory Pressure and Sustainability Trends
The regulatory environment in 2026 is undergoing a significant transformation, particularly concerning sustainability and end-of-life management. In the United States, the landscape of Extended Producer Responsibility (EPR) laws is expanding rapidly. As of late 2025, several states including Maine, Oregon, Colorado, California, Minnesota, Maryland, and Washington have enacted comprehensive EPR laws for packaging and paper products. These laws require producers to fund the end-of-life management of their packaging, shifting the cost burden and incentivizing more sustainable design choices. Furthermore, in 2026, additional states such as New Hampshire, Wisconsin, and Georgia have introduced or advanced similar bills, signaling a nationwide trend toward greater producer accountability for paper and packaging materials.
Packaging Outsert and Inserts Market
Across the Atlantic, the European Union's Packaging and Packaging Waste Regulation (PPWR), effective from August 2026, imposes rigorous requirements on packaging design. This regulation mandates recyclable packaging design, minimizes harmful substances, and sets recycled content targets for non-contact plastic packaging starting in 2030. For the outsert and inserts market, which relies heavily on paperboard and specialized folding cartons, these regulations necessitate a reevaluation of material sourcing and design protocols. Companies must now consider not only the dimensional compliance of their inserts but also their recyclability and environmental footprint. This regulatory shift is not merely a compliance exercise; it is a strategic signal that sustainability will be a key differentiator in vendor selection and market access.
Parallel to regulatory changes, raw material costs remain a persistent concern. The U.S. Producer Price Index for folding paperboard boxes and packaging components has shown fluctuation, reflecting broader inflationary pressures in the supply chain. Additionally, global wood pulp import prices have established a baseline that influences the cost structure of paper-based inserts. Packaging remains a leading application for wood pulp, meaning that fluctuations in pulp markets directly impact the cost of goods for pharmaceutical inserts. Manufacturers and buyers alike must monitor these indices closely, as margins in packaging can be thin and sensitive to material cost spikes. Strategic procurement contracts and material diversification are becoming essential tools for managing this volatility.
Competitive Landscape and Manufacturer Innovation
The competitive landscape is characterized by a market structure that is fragmented yet featuring key players with significant specialized capabilities. The concentration ratio among the top competitors remains relatively dispersed, indicating that while large players exist, there is substantial room for specialized manufacturers to compete on quality, compliance, and service. Leading companies in this space are not just competing on price; they are differentiating through technological innovation, capacity expansion, and adherence to rigorous quality standards such as cGMP and ISO certifications.
Worldwide Aircraft Galley Inserts Market
Several core companies exemplify the strategic depth of the market. Winpak, based in Norwood, New Jersey, specializes in precision-manufactured product inserts, outserts, and MedGuides, utilizing high-precision equipment to meet strict FDA dimensional requirements. Their focus on converting large-format printed sheets into compact formats suitable for automated application highlights the technical precision required in this sector. Similarly, CCL Healthcare, headquartered in Etobicoke, Canada, offers customizable folded patient leaflet inserts and outserts with capabilities extending to hundreds of panels and pages, produced under controlled facilities with a focus on multilingual and regulatory compliance.
Nosco, with multiple facilities across the USA, emphasizes stitched booklets and intricately folded inserts using advanced folding equipment, catering to pharmaceutical, natural health, and CPG markets with a strong emphasis on consistency. Colbert Packaging Corp, located in Kenosha, Wisconsin, manufactures custom paperboard folding cartons and high-capacity pharmaceutical inserts using patented folding procedures. Graphic Packaging International provides leaflets and packaging inserts tailored from specific paper grades, including mandatory patient alert cards for medication safety. These companies illustrate the diversity of technical capabilities available to support complex healthcare packaging needs.
Recent developments highlight the dynamic nature of this competitive field. Colbert Packaging Corporation expanded its capacity in early 2026 by adding a new blanking die cutter to its Kenosha facility, aimed at boosting production efficiency for paperboard packaging including inserts. This move signals an anticipation of continued demand and a commitment to maintaining throughput capabilities. In Europe, Faller Packaging pioneered digitally-printed pharmaceutical leaflets with the installation of a 4th SCREEN TruePress Jet in 2025, demonstrating a push toward digital printing technologies to meet high standards in leaflet production and potentially offering greater flexibility in short runs or customized information. Additionally, Winpak introduced Medform DT in late 2025 as part of advancements in pharmaceutical packaging components, showcasing ongoing product innovation in inserts and outserts.
Other notable players include RLG Healthcare, which produces package inserts and IFUs with precision printing and folding down to very small dimensions for automated equipment compliance; Tursso Companies, offering design-to-manufacture capabilities with strict quality protocols under ISO and GMP standards; and Flottman Company, delivering precision folding services with advanced serialization for regulatory-compliant integration. The presence of these diverse capabilities suggests that buyers can find specialized partners for specific needs, but the fragmentation also means that due diligence on technical capacity and regulatory track record is essential.
Strategic Value of Comprehensive Market Research
For enterprises operating in 2026, the decision to invest in deep market intelligence is a strategic one. The Packaging Outsert and Inserts Market report provides more than just historical data; it offers a structured framework for understanding the interplay between regulatory shifts, material costs, and competitive dynamics. The report details every segmentation slice, from regional breakdowns to application-specific trends, allowing stakeholders to identify where their specific products fit within the broader value chain. This granularity is essential for risk assessment and opportunity identification.
Furthermore, the report covers recent developments and company profiles extensively. By analyzing the capacity expansions, product introductions, and technological adoptions of key players, the research helps enterprises benchmark their own strategies against industry leaders. Understanding who is expanding capacity, who is moving toward digital printing, and who is innovating in material formats can inform supply chain partnerships and competitive positioning. The inclusion of regulatory context, such as the specific states enacting EPR laws and the timelines for EU PPWR compliance, provides actionable intelligence for compliance planning and sustainability strategy development.
Raw material insights are also integral to the analysis. With fluctuations in paperboard indices and wood pulp prices, access to detailed data on material flows and cost drivers enables more accurate budgeting and procurement planning. The report contextualizes these material trends within the broader market forecast, helping users anticipate cost pressures before they impact margins. Additionally, the analysis of market concentration helps buyers understand the bargaining dynamics in the supplier market, whether they are negotiating against a consolidated few or a broader field of competitors.
In an era where supply chain resilience and regulatory compliance are paramount, the Packaging Outsert and Inserts Market report serves as a vital tool for strategic planning. It equips operations managers, procurement leaders, and strategists with the foresight needed to navigate the complexities of 2026 and beyond. The insights contained within move beyond the surface-level headlines to provide the depth required for informed decision-making.
To access the complete suite of data, including exact regional valuations, detailed segmentation revenues, and full company profiles, we invite you to explore the full report. This intelligence is designed to be the foundation for your strategic decisions in the coming years, ensuring that your organization remains agile, compliant, and competitive in a growing and evolving market.
For detailed analysis of this topic, please visit the official page: Packaging Outsert and Inserts Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Multi-Gigabit Switch Market to Reach $23.9B by 2032, Growing at 18.52% CAGR
By pmarketresearch, 2026-09-16
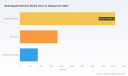
Navigating the Multi-Gigabit Era: Strategic Insights for the 2026 Network Infrastructure Landscape
Executive Summary
The global networking infrastructure is undergoing a seismic shift. As enterprises, data centers, and service providers grapple with exponential data growth, the transition from traditional Gigabit Ethernet to multi-gigabit solutions has moved from a niche upgrade to a foundational requirement. Our latest comprehensive study, the Worldwide Multi-Gigabit Switches Market, provides a definitive look at this transformation. Spanning historical analysis from 2020 through 2025 and a robust forecast period extending to 2032, this report equips decision-makers with the intelligence needed to navigate capital allocation, vendor selection, and technology roadmap planning in an increasingly congested and bandwidth-hungry environment.
The multi-gigabit switch market is not merely growing; it is accelerating. Driven by the proliferation of Wi-Fi 7, the densification of IoT devices, the demands of AI-driven surveillance, and the relentless expansion of cloud architectures, the need for 2.5 Gbps, 5 Gbps, and 10 Gbps port speeds is reshaping procurement strategies. This article outlines the strategic value of our research, highlighting the macroeconomic trajectories, competitive contours, and operational pressures that define the landscape for 2026 and beyond.
Market Trajectory and Growth Dynamics
Our analysis captures a market that has demonstrated remarkable resilience and expansion over the past half-decade. From a base of approximately 2.84 billion USD in 2020, the worldwide multi-gigabit switches market has consistently climbed, reaching an estimated 7.28 billion USD by 2025. This progression reflects the compounding effects of post-pandemic digitalization, the modernization of legacy campus networks, and the early adoption of higher-speed standards in edge deployments.
Looking forward, the growth narrative intensifies. The market is projected to breach the 8.88 billion USD threshold in 2026 and continue its upward march, surpassing 10.47 billion USD in 2027 and 12.40 billion USD by 2028. By the end of the forecast horizon in 2032, the market size is anticipated to approach 23.92 billion USD. This trajectory is underpinned by a compound annual growth rate (CAGR) of 18.52 percent during the 2026-2032 period. For strategic planners, this rate signals more than simple volume increase; it indicates a structural re-pricing of network capacity, where multi-gigabit connectivity is becoming the default expectation rather than a premium feature.
This aggressive expansion creates both opportunity and complexity. Organizations must balance the urgency of upgrading infrastructure against budget constraints and supply chain realities. Our report dissects these growth vectors to help stakeholders identify where demand is clustering and how adoption curves differ across deployment models and port configurations, without relying on superficial generalizations.
Strategic Implications of the 2026-2032 Forecast
The forecast period presents a critical window for investment planning. As the market scales from roughly 8.89 billion USD in 2026 toward a peak exceeding 23.91 billion USD in 2032, the competitive intensity will likely sharpen. Companies that delay strategic positioning risk being priced out of key segments or locked into obsolete architectures. Conversely, early movers can leverage scale, optimize total cost of ownership, and capture market share in emerging sub-segments such as industrial hardening and AI-integrated edge networking.
Our report provides a granular view of these dynamics, enabling procurement leaders to model procurement schedules, IT directors to assess technology refresh cycles, and investors to evaluate the risk-return profiles of key players. We deliberately reserve the detailed segment revenue breakdowns and regional share percentages for the full study, ensuring that clients gain a nuanced, actionable advantage rather than generic market snapshots.
Competitive Landscape and Vendor Intelligence
The multi-gigabit switches ecosystem is characterized by a mix of established networking giants, specialized industrial providers, and agile innovators targeting specific deployment niches. Understanding the strategic positioning of these players is essential for navigating procurement negotiations, assessing supply chain risks, and identifying partnership opportunities.
At the enterprise and data center tier, vendors like Cisco Systems and Arista Networks set the pace. Cisco's comprehensive portfolio, including the Catalyst 9000 series and Nexus platforms, continues to anchor many large-scale campus and data center deployments with support for 2.5G, 5G, and 10G speeds. Arista Networks, meanwhile, focuses heavily on high-performance 10G+ Ethernet switches tailored for cloud and data center environments, appealing to organizations with stringent latency and throughput requirements.
The edge and SMB segments reveal a more fragmented but highly dynamic field. TP-Link and NETGEAR have carved out significant presence by offering cost-effective multi-gigabit solutions, often with Power over Ethernet (PoE) capabilities, targeting home offices, small businesses, and prosumer applications. TP-Link's Omada series and NETGEAR's expanded port offerings illustrate how affordability and feature density are driving adoption in these volume-driven segments.
A notable trend is the convergence of networking and storage or specialized applications. QNAP has entered the fray with cost-effective switches like the QSW series, integrating multi-gigabit ports directly into NAS-centric and SMB networks, thereby reducing bottlenecks for storage-heavy workloads. Similarly, EnGenius Technologies has moved quickly to align its hardware with next-generation wireless standards; in July 2025, the company launched the ECS2530FP, a Layer 2+ switch featuring 24 x 2.5GbE PoE++ ports with 90W power delivery and six 10G SFP+ uplinks, specifically designed to support Wi-Fi 7 access points, AI surveillance systems, and VoIP deployments. This product strategy underscores the growing importance of PoE++ and high-power delivery in converged edge networks.
Industrial and hardened switching represent another critical axis of competition. Companies such as TRENDnet, Omnitron Systems, Lantronix, and PLANET Technology are tailoring multi-gigabit switches to withstand harsh environments, offering ruggedized models with 2.5G and 10G ports, robust PoE options, and specialized connectivity. These vendors serve sectors like manufacturing, transportation, and remote infrastructure, where reliability and environmental resilience are non-negotiable.
In the data center and service provider realms, Juniper Networks and Hewlett Packard Enterprise (via the Aruba CX series) continue to supply multi-gigabit and high-speed Ethernet switches that balance performance with manageability for campus, enterprise, and carrier networks. The presence of D-Link, Zyxel, and Ubiquiti further diversifies the market, with D-Link expanding its 2.5G lineup for edge networks and Ubiquiti's UniFi series catering to both prosumer and enterprise deployments with an emphasis on integrated management and ease of deployment.
The competitive landscape is not static. Throughout 2025, we observed a flurry of product launches and line expansions that signal where vendors are betting on future demand. For instance, in early 2025, QNAP announced the QSW-3205-5T, a cost-effective five-port full 10GbE switch aimed at entry-level high-speed networking, alongside the QSW-2104-2T-R2, an affordable four-port 2.5GbE plus two-port 10GbE model. D-Link expanded its 2.5G multi-gigabit switch lineup targeting edge networks later in the year. These moves illustrate an industry-wide effort to democratize multi-gigabit access, pushing higher speeds downmarket while maintaining premium offerings at the top end.
Our report includes detailed vendor profiles, recent development tracking, and a competitive benchmarking analysis that reveals how companies are differentiating themselves. We examine product roadmaps, pricing strategies, and ecosystem partnerships to give stakeholders a clear view of who is winning in which space and why. Full regional market shares and detailed segmentation revenues for each vendor are reserved for the complete study, where they are presented in the context of broader strategic implications.
Market Concentration and the Role of Scale
A key structural feature of the multi-gigabit switches market is its concentration among top players. Our analysis indicates that the top three companies command approximately 56.8 percent of market revenue, while the top five firms account for nearly 72.45 percent. This level of concentration suggests that scale, brand trust, and extensive partner ecosystems continue to exert significant influence, particularly in enterprise and data center segments where procurement processes favor established vendors with proven track records.
However, concentration does not imply stagnation. The remaining market share is fiercely contested by mid-tier and specialized players who compete on agility, niche features, price, and vertical-specific expertise. For buyers, this dynamic offers leverage: while the incumbents provide broad compatibility and comprehensive support, alternative vendors can deliver tailored solutions that reduce total cost of ownership or address unique operational requirements. Our study maps these competitive pressures in detail, helping organizations identify where they can negotiate effectively and where reliance on dominant suppliers may be strategically justified.
Industry Context and External Pressures
No market analysis is complete without acknowledging the external forces that shape purchasing behavior, cost structures, and regulatory environments. The multi-gigabit switches market does not exist in a vacuum; it is influenced by raw material dynamics, energy costs, infrastructure economics, and policy shifts that can alter the calculus of network investment.
One of the most pressing cost drivers is the price of fiber and physical infrastructure. Industry surveys indicate that fiber deployment costs are expected to rise again in 2026, with a significant majority of respondents anticipating an increase, though the magnitude varies. In parallel, the cost of single-mode fiber such as G.652D in certain markets has remained relatively stable, suggesting that regional supply chains and commodity pricing will continue to diverge. These dynamics affect the total cost of network deployments, especially where backhaul and last-mile fiber must be upgraded to support higher throughput at the edge.
Energy costs also weigh heavily on decision-making, particularly for data center operators and large-scale enterprise deployments. Electricity can account for 40 to 60 percent of total data center operating expenses, with large facilities spending millions annually on power. As multi-gigabit switches become integral to higher-density rack configurations and AI-augmented workloads, power efficiency and thermal management are moving up the priority list. Vendors that can deliver higher throughput per watt, support advanced sleep states, or integrate with intelligent power management systems gain a distinct advantage in total cost of ownership discussions.
Construction and deployment costs for core infrastructure further complicate the picture. Global average shell-and-core data center construction costs are forecasted to approach 11.3 million USD per megawatt in 2026, up from roughly 10.7 million USD per megawatt in 2025. While this metric primarily reflects facility economics, it indirectly influences networking procurement by increasing the overall capital intensity of capacity expansion. Organizations must weigh the benefits of faster internal switching against the broader cost of building or retrofitting spaces that can support higher power and cooling demands.
Regulatory developments add another layer of complexity. In the United States, the Sixth Circuit Court struck down the FCC's 2024 net neutrality order in January 2025, leading to the subsequent removal of federal net neutrality rules. While the direct impact on switch hardware is limited, such policy shifts can influence service provider investment patterns, traffic management strategies, and the broader architectural choices that enterprises make when designing hybrid or multi-vendor networks. For organizations operating across multiple jurisdictions, understanding how regulatory environments evolve is critical to long-term planning and risk mitigation.
Why These Dynamics Matter for 2026 Decision-Making
These external factors are not peripheral concerns; they are integral to the strategic value of our report. By integrating supply-side cost signals, energy economics, infrastructure benchmarks, and regulatory milestones, we provide a holistic framework for evaluating multi-gigabit switching investments. Readers of the full study gain access to scenario analyses that connect these macro pressures to specific procurement decisions, enabling them to stress-test their plans against plausible cost increases, energy price volatility, and shifting regulatory assumptions.
Report Scope and Practical Utility
The Worldwide Multi-Gigabit Switches Market report is designed to be a working document for strategy, procurement, and technology leadership. It combines rigorous historical analysis with forward-looking forecasts, supported by detailed segmentation insights, competitive profiling, and industry context. The study covers the period from 2020 through 2032, providing a consistent baseline against which both short-term tactics and long-term roadmaps can be calibrated.
Our segmentation framework examines the market across key dimensions, including port speed, deployment type, and region, allowing readers to pinpoint where demand is strongest and how adoption patterns differ by use case. We analyze the relative importance of 2.5 Gbps, 5 Gbps, and 10 Gbps port configurations, as well as the distinct characteristics of enterprise and office, data center, and residential or small office/home office deployments. Rather than presenting a flat overview, the report explores how these segments interact with vendor strategies, pricing dynamics, and infrastructure trends.
Worldwide Multi-Gigabit Switches Market
The competitive analysis goes beyond surface-level descriptions. We profile the leading companies, tracking their recent product launches, line expansions, and strategic shifts. By stitching together product announcements, market positioning, and development timelines, we reveal the cadence of innovation and the areas where vendor focus is intensifying. This approach helps readers distinguish between marketing narratives and substantive moves that affect supply availability, interoperability, and long-term support commitments.
To ensure actionable value, the report includes practical guidance on evaluating total cost of ownership, assessing power delivery requirements, and aligning switch capabilities with adjacent technologies such as Wi-Fi 7 access points, AI-enabled cameras, and storage appliances. We also address the implications of industrial hardening, PoE++ standards, and management ecosystem maturity, enabling technical teams to make informed trade-offs between performance, resilience, and operational simplicity.
Navigating the Information Asymmetry
In a market moving at this pace, information quality is a competitive asset. Generic market figures and aggregate growth rates are widely available, but the insights that drive real advantage lie in the granular connections between demand drivers, vendor behavior, cost pressures, and segment dynamics. Our report is structured to preserve that advantage: we surface the strategic patterns and the analytical scaffolding that support them, while keeping the precise segment-level numbers and detailed regional breakdowns for subscribers who need to act on them.
This approach aligns with the pace of decision-making in 2026. Organizations do not need another high-level summary; they need a credible, evidence-based reference that can inform budget cycles, vendor evaluations, architecture choices, and risk assessments. By providing a clear narrative of where the market is heading and who is shaping it, the study serves as both a planning tool and a conversation starter for cross-functional teams.
Conclusion: Turning Market Velocity into Strategic Advantage
The worldwide multi-gigabit switches market is entering a phase of accelerated expansion that will test the agility of every organization involved in network infrastructure. With a projected CAGR of 18.52 percent from 2026 to 2032 and market size scaling from nearly 8.89 billion USD in 2026 to over 23.91 billion USD by 2032, the stakes are high. The convergence of demanding applications, rising infrastructure costs, energy constraints, and a concentrated yet dynamic competitive field means that strategic clarity is more valuable than ever.
Ethernet Switches Market
Our research offers that clarity. It maps the growth path, dissects the competitive moves, contextualizes the external pressures, and provides the analytical depth required to make confident decisions. For executives, procurement leaders, and network architects, the report is a timely resource for aligning technology investments with business objectives in a year defined by both opportunity and complexity.
To access the full analysis, including detailed segmentation data, competitive benchmarks, and scenario-based guidance, we invite you to explore the complete study. The macro trends and strategic patterns highlighted here are only the beginning; the actionable intelligence that supports specific decisions is waiting within.
For detailed analysis of this topic, please visit the official page: Worldwide Multi-Gigabit Switches Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com