

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
PW Consulting Forecasts Global Nursing Mannequin Market to Hit $1.26B by 2032 With 8.12% CAGR
By pmarketresearch, 2026-09-16
Strategic Imperatives in the Global Nursing Mannequin Market: A 2026 Outlook
The healthcare education landscape is undergoing a profound transformation, driven by an relentless demand for competent nursing professionals and an increasing reliance on high-quality simulation technologies. As we move through 2026, organizations involved in the procurement, manufacturing, and distribution of nursing mannequins face a complex matrix of opportunities and challenges. The Worldwide Nursing Mannequin Market has evolved from a niche segment of medical training equipment into a critical infrastructure component for healthcare workforce development. This shift necessitates a rigorous understanding of market trajectories, competitive maneuvers, and regulatory underpinnings that define the industry today.
Our latest comprehensive market research provides a detailed examination of these dynamics. The study offers an indispensable toolkit for strategic planners, investment analysts, and executive leadership teams aiming to navigate the forecast period from 2026 to 2032. By synthesizing historical performance data with forward-looking projections, this report illuminates the path toward sustainable growth and market leadership. The following insights outline the strategic value embedded within this analysis, highlighting why timely access to this intelligence is crucial for informed decision-making in the current fiscal year.
The urgency for accurate market intelligence has never been higher. With nursing shortages persisting across developed and emerging economies, educational institutions and healthcare providers are investing heavily in simulation-based training to bridge the skills gap. Nursing mannequins serve as the cornerstone of this pedagogical approach, allowing students to practice clinical procedures, patient handling, and emergency responses in a risk-free environment. Understanding the scale and velocity of this investment is essential for stakeholders to align their capabilities with market needs.
Market Trajectory and Financial Outlook
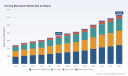
The financial architecture of the nursing mannequin sector demonstrates robust expansion, characterized by consistent revenue generation and positive growth momentum. Historical data indicates a steady climb in market valuation, reflecting the increasing integration of simulation tools into standard nursing curricula and professional competency programs. The market has progressed through a period of significant adoption, with revenue figures showing a clear upward trend from the base year benchmarks established in recent years.
Forecasts extend this positive trajectory well into the next decade. The projection for the market suggests continued appreciation in value, supported by the broader adoption of advanced patient simulators and the expansion of healthcare training facilities globally. The Compound Annual Growth Rate (CAGR) anticipated over the forecast period underscores the resilience of this sector. This growth is not merely a reflection of population demographics but is deeply tied to technological advancements in simulation fidelity and the regulatory push for standardized competency evaluation.
Stakeholders analyzing the revenue unit dynamics will observe that the volume of transactions is complemented by an increase in the average value per unit, driven by the shift toward high-fidelity models. While specific revenue streams vary across different operational segments, the aggregate picture points to a healthy economic environment for manufacturers and distributors who can effectively position their offerings against evolving customer expectations. The financial outlook provides a foundational basis for capacity planning, investment allocation, and market entry strategies.
Growth Drivers and Regional Momentum
Several key drivers are propelling the market forward. The primary catalyst remains the global imperative to enhance nursing education quality. Accreditation bodies and government regulations increasingly mandate hands-on practice hours before clinical deployment. This requirement directly fuels demand for durable, versatile, and realistic mannequins. Additionally, the expansion of vocational training programs in emerging markets is opening new revenue channels. Institutions are looking to upgrade legacy equipment to meet modern training standards, creating a replacement cycle that benefits manufacturers of advanced simulation devices.
Regional performance varies, with mature markets showing steady consolidation and growth, while developing regions exhibit higher potential for expansion as healthcare infrastructure matures. The distribution of market activity reflects the concentration of healthcare education hubs and government spending on medical training. Understanding these geographic nuances allows companies to tailor their go-to-market strategies, focusing resources on regions where regulatory support and institutional budgets align with product capabilities. The analysis delves into these variations without oversimplifying, providing a granular view of where growth is originating.
Segmentation Depth and Product Evolution
The market is stratified by product fidelity, creating distinct value propositions for different end-user needs. High-fidelity mannequins represent a significant portion of the market revenue, appealing to institutions that require comprehensive scenario-based training capabilities. These advanced simulators offer interactive physiological responses, enabling trainees to practice complex procedures such as airway management, injection, catheterization, and wound care. The demand for these high-end units is driven by the need for realistic patient handling simulations and the integration of multi-parameter monitoring systems that mimic real clinical environments.
Medium-fidelity and low-fidelity mannequins continue to hold substantial market share, catering to budget-conscious institutions and specific training modules focused on basic patient care skills. These segments benefit from the need for cost-effective training solutions that still meet competency standards. Products in this category often feature articulated limbs, washable vinyl skin, and flexible joints, allowing for repetitive practice in handling, transfer, bathing, and bandaging. The availability of interchangeable features, such as genitalia and injection pads, enhances the utility of these manikins for diverse training scenarios, including ostomy care and basic nursing procedures.
The segmentation by end-user further clarifies demand patterns. Nursing and vocational schools constitute a major consumer base, driven by the need to equip classrooms and simulation labs with sufficient units for student cohorts. Hospitals and clinics represent another critical segment, utilizing mannequins for in-service training, code blue drills, and staff competency maintenance. Additionally, military and emergency services maintain a specialized demand for simulators that support BLS and ALS integration, reflecting the high-stress environments in which these personnel operate. Each end-user group presents unique procurement cycles and specification requirements that influence product development and sales strategies.
Competitive Landscape and Key Player Dynamics
The competitive environment is characterized by a mix of established global entities and specialized manufacturers. Market concentration metrics indicate that a handful of leading companies command a significant share of total revenue, yet there remains room for innovation and niche positioning. The top firms leverage strong brand recognition, extensive product portfolios, and global distribution networks to maintain their market position. However, the landscape is dynamic, with companies continuously updating their catalogs and integrating new technologies to differentiate their offerings.
Worldwide Nursing Mannequin Market
Profiles of Market Leaders
Several organizations stand out for their strategic focus and product innovation. Laerdal Medical, based in Stavanger, Norway, is renowned for its Nursing Anne and patient care simulators that emphasize scenario-based training. Their focus spans from basic to advanced nursing skills, including patient handling and wound care. A recent development highlights their commitment to technological integration; in mid-2025, Laerdal integrated IngMar Medical ASL 5000 breathing simulation technology into their SimMan Critical Care platform, enhancing respiratory care training for advanced nursing scenarios. This move demonstrates the industry trend toward combining respiratory simulation with general patient care manikins to create more holistic training tools.
Gaumard Scientific, headquartered in Miami, Florida, offers a robust lineup including the SUSIE series and Code Blue simulators. Their products support general clinical nursing skills and integrate BLS/ALS training modules. Gaumard continues to update its educational packages, ensuring that the SUSIE S2000 Advanced Nursing Care Patient Simulator remains relevant with scenario updates and SLE educational enhancements. This ongoing catalog management signals a strategy of perpetual improvement to retain institutional customers.
In Asia, Kyoto Kagaku Co., Ltd. maintains a strong presence with its Patient Care Simulator 'Cherry' and similar nursing manikins. These devices facilitate day-to-day patient care training, covering TPN/IV routes, positioning, and basic procedures. Kyoto Kagaku's adherence to ISO 9001 quality management standards underscores the importance of manufacturing reliability in this sector, providing assurance to buyers regarding product durability and safety compliance.
European manufacturers also play a pivotal role. 3B Scientific, based in Hamburg, Germany, supplies the Patient Care Manikin BASIC/PRO and Nikki the Nursing Manikin. Their products emphasize scenario-based training with features like auscultation and interchangeable genitalia, supporting wound management and comprehensive patient care skills. Similarly, Limbs & Things from Bristol, United Kingdom, develops the Yaye advanced full-body nursing manikin and Cherry basic nursing manikin, focusing on hands-on training for daily patient care tasks.
In North America, Nasco Healthcare, including Simulaids, offers a wide range of patient care manikins and the AXEL Patient Simulator. Their portfolio includes weighted care trainers designed for nursing skills such as handling, transfer, bathing, bandaging, and injection practice. CAE Healthcare, now operating under Elevate Healthcare with global operations centered in Montreal, Quebec, produces the Juno nursing skills manikin and Apollo in nursing configuration. These units support clinical skills training including IV access, tracheostomy care, and feature interchangeable gender capabilities, catering to diverse training needs.
Mannequins Market
Recent industry developments highlight the collaborative and expansive nature of the market. In early 2026, Pocket Nurse released its 2026 Simulators and Manikins Product Catalog, featuring an expanded selection of nursing manikins from major partners like Laerdal, Gaumard, 3B Scientific, and Nasco. This catalog release illustrates how distributors are curating comprehensive solutions for educational institutions, bundling products from multiple top-tier manufacturers to meet varied curriculum requirements.
Regulatory Framework and Compliance Considerations
Navigating the regulatory landscape is a critical component of market participation. Nursing manikins used in medical simulation are classified as training devices, and manufacturers must comply with ISO 9001 quality management standards. This requirement ensures that products meet consistent quality benchmarks, reducing the risk of failure during critical training exercises. Compliance with these standards is not merely a formality; it is a prerequisite for procurement by accredited institutions that require evidence of quality assurance in their equipment sourcing.
Furthermore, medical training manikins support compliance with specific operational requirements, such as the OBRA mandates for Nurse Aide Training and Competency Evaluation Programs. Simulation devices enable scenario-based skills practice that aligns with these regulatory standards, helping institutions maintain certification and funding eligibility. The shift toward scenario-based training also necessitates that products support a range of clinical competencies, from basic patient handling to complex emergency responses.
It is also essential to recognize the intended use of these devices. Nursing manikins are strictly for instructional and simulation purposes and are not intended for human or animal clinical application. Clear labeling and adherence to this distinction are vital for liability management and ethical operation. Manufacturers and distributors must ensure that their marketing and documentation clearly communicate these boundaries to prevent misuse and maintain the integrity of the simulation industry.
Strategic Applications for Decision Makers
This market research serves as a strategic compass for a variety of stakeholders. For manufacturers, the analysis provides insights into product lifecycle management, highlighting which fidelity levels and features are gaining traction. Understanding the competitive moves of peers allows for proactive innovation and positioning. For distributors and channel partners, the report clarifies demand patterns across different educational and clinical end-users, enabling more effective inventory management and sales targeting.
Investment firms and venture capitalists can utilize the growth projections and segment analysis to assess the viability of entering or expanding within this sector. The data supports due diligence by outlining revenue potential and identifying key risk factors associated with market concentration and regulatory changes. Academic and healthcare administrators benefit from the comprehensive overview of available technologies, helping them make informed procurement decisions that align with their training objectives and budgetary constraints.
The inclusion of recent market events, such as technology integrations and catalog updates, ensures that the intelligence remains current and actionable. This real-time context allows decision-makers to anticipate shifts in supplier capabilities and market offerings. By understanding the interplay between product features, regulatory needs, and end-user demands, organizations can formulate strategies that are both resilient and adaptive.
The market for nursing mannequins is poised for sustained growth, underpinned by the critical role simulation plays in healthcare education. The convergence of technological advancement, regulatory pressure, and workforce needs creates a fertile environment for strategic investment and innovation. Companies that can navigate this landscape with accurate data and a clear understanding of competitive dynamics will be best positioned to capture value in the years ahead. This report provides the depth and breadth of analysis required to make those strategic judgments with confidence.
For detailed analysis of this topic, please visit the official page: Worldwide Nursing Mannequin Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: DPI Market Hits $545.6M in 2025, Projected to Reach $845.05M by 2032 (CAGR 6.45%)
By pmarketresearch, 2026-09-16
Strategic Imperatives in the Worldwide During Production Inspection Market: Navigating Growth from 2026 to 2032
The global manufacturing landscape is undergoing a profound transformation, driven by increasingly complex supply chains, stringent regulatory environments, and heightened consumer expectations for product quality. In this volatile context, During Production Inspection (DPI) has evolved from a routine compliance checkbox into a critical strategic lever for risk mitigation and operational excellence. As enterprises prepare their operational roadmaps for 2026 and beyond, access to granular, data-backed intelligence on the DPI market is no longer a luxury—it is a necessity for sustainable growth.
This article serves as a precursor to the comprehensive Worldwide During Production Inspection Market Research study recently published by PW Consulting. Our objective is to outline the strategic value this report offers to corporate decision-makers, highlighting the macro-economic trajectories, competitive shifts, and operational dynamics that will define the sector through 2032. While we provide a high-level overview of the market's momentum here, the specific segment breakdowns and nuanced forecasts contained within the full study are designed to empower precise strategic planning.
Market Trajectory and Macro-Economic Drivers
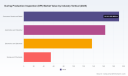
The During Production Inspection market has demonstrated resilient expansion over the past five years, reflecting the global emphasis on quality assurance amidst rising production volumes. Based on historical analysis from 2020 through 2025, the market has shown a consistent upward trajectory, moving from a baseline in the mid-390 million USD range to over 545 million USD by the base year of 2025. This growth underscores the indispensable nature of real-time quality verification in modern manufacturing ecosystems.
Looking forward, the forecast period spanning 2026 to 2032 indicates a continuation of this positive momentum. Our projections suggest that the global DPI market revenue will surpass the 580 million USD mark in 2026 and continue to climb steadily, reaching significant milestones by the end of the forecast horizon. The compound annual growth rate (CAGR) observed across this forecast window highlights a steady expansion pace, driven by increasing outsourcing of manufacturing and the need for third-party verification in cross-border trade.
- The market has consolidated its position as a critical component of supply chain integrity.
- Revenue growth is supported by both established industrial sectors and emerging manufacturing hubs.
- Operational shifts towards hybrid inspection models are influencing valuation trends.
It is important to note that while the aggregate growth figures are compelling, the true strategic value lies in understanding how this growth is distributed across various verticals and service models. The full report delves deep into these nuances, offering a breakdown that allows stakeholders to pinpoint opportunities without exposing them to the risks of aggregate-only analysis.
Structural Dynamics: Industry Verticals and Service Models
The DPI market is not monolithic; it is a fragmented ecosystem where demand drivers vary significantly by industry vertical. Sectors such as Consumer Goods and Retail, Automotive and Industrial, and Electronics and Electrical constitute the core pillars of demand. Each of these verticals faces unique compliance challenges and production complexities that necessitate tailored inspection protocols. For instance, the electronics sector demands rigorous process monitoring to handle miniaturization and component density, while the automotive industry requires stringent adherence to safety standards during assembly phases.
Simultaneously, the service delivery model is undergoing a technological inflection point. The market is currently bifurcated between traditional On-site Physical Inspection and emerging Remote Digital Monitoring solutions. On-site inspection remains the dominant revenue generator, reflecting the tangible need for physical verification of manufacturing processes, raw materials, and assembly line outputs. However, the remote segment is gaining traction as digitalization enables real-time data transmission and virtual audits, reducing travel costs and increasing inspection frequency without compromising oversight.
- High-volume sectors drive the bulk of inspection demand.
- Regulatory compliance acts as a primary catalyst for on-site services.
- Digital transformation is gradually reshaping the service model mix.
Our research dissects these structural elements to reveal where value is being created and captured. Understanding the interplay between industry-specific demands and service delivery capabilities is crucial for vendors looking to differentiate their offerings and for buyers seeking to optimize their quality control budgets.
Competitive Landscape and Strategic Positioning
The DPI market is characterized by a mix of global quality assurance giants and specialized niche players. Market concentration data indicates that while the top three players hold a notable share of the market, the top five collectively command a significant portion of revenue, suggesting a moderately fragmented landscape with room for consolidation. Key industry veterans such as SGS, Bureau Veritas, and Intertek continue to leverage their extensive global networks to provide comprehensive DPI services across electronics, automotive, and consumer goods sectors.
Worldwide During Production Inspection (DPI) Market
Regional powerhouses and specialized firms are also making significant inroads. Companies like TÜV Rheinland and TÜV SÜD focus heavily on industrial machinery, automotive components, and renewables, emphasizing process monitoring and defect prevention. Similarly, DNV and LRQA integrate DPI within broader assurance services for maritime, oil & gas, and food supply chains, highlighting the convergence of inspection with certification.
The competitive field extends to firms like DEKRA, Eurofins Scientific, UL Solutions, Kiwa, Cotecna, Applus+, and others, each bringing distinct expertise ranging from safety compliance in electronics to agro-food manufacturing verification. The strategic differential often lies in the ability to integrate DPI with broader testing, certification, and supply chain visibility services.
- Global incumbents maintain strength through scale and cross-sector presence.
- Specialized firms compete on technical expertise and regulatory knowledge.
- Integration with digital assurance tools is becoming a key differentiator.
The full report provides a detailed competitive profiling section, analyzing the strategic moves, service portfolios, and regional footprints of these key players. This analysis is vital for organizations assessing potential partnerships, acquisition targets, or competitive threats in their specific geographic or vertical markets.
Regulatory and Operational Catalysts
External pressures are significantly shaping the demand landscape for During Production Inspection. Regulatory frameworks are becoming more rigorous, compelling manufacturers to adhere to higher standards of traceability and quality verification. For example, the EU Market Surveillance Regulation has mandated inspections during production for non-food products to ensure compliance, directly impacting how companies manage their European supply chains. Such regulations create a mandatory demand floor for DPI services, insulating the market from some economic cyclicality.
Furthermore, operational dynamics are being influenced by labor market trends and standardization requirements. The median annual wage for quality control inspectors, coupled with projected employment shifts due to automation, suggests that manual inspection processes may face cost pressures or efficiency constraints. This environment accelerates the adoption of professional third-party DPI services that can offer scalable expertise without the overhead of maintaining large in-house inspection teams. Additionally, standards such as ISO/IEC 17020 establish specific requirements for the competence of inspection bodies, raising the barrier to entry and favoring established, certified providers.
Strategic Value for 2026 Decision Makers
For executives and strategists planning for the 2026 fiscal year and beyond, the PW Consulting Worldwide During Production Inspection Market Research offers actionable intelligence that goes beyond surface-level trends. The report is designed to answer critical questions regarding market sizing, growth vectors, and competitive intensity.
Decision-makers will benefit from insights into how different regions are performing, albeit without exposing specific sensitive data points in this summary. The detailed study provides the necessary granularity to assess market entry feasibility, capacity expansion plans, or investment allocations. Whether you are a provider of inspection services looking to expand your footprint or a manufacturing entity seeking to optimize your quality assurance spend, the data contained herein supports evidence-based decision-making.
- Identify high-growth segments aligned with your core competencies.
- Evaluate competitive threats based on market share dynamics.
- Align service offerings with evolving regulatory and digital trends.
- Optimize resource allocation based on verified market forecasts.
Conclusion
The Worldwide During Production Inspection Market is poised for sustained evolution, shaped by technological adoption, regulatory mandates, and the ever-present need for quality assurance in global trade. The period from 2026 to 2032 will likely see further integration of digital tools alongside traditional inspection methods, driven by efficiency demands and risk management strategies.
This overview provides a snapshot of the market's health and direction, but the full complexity and opportunity lie in the details. To access the complete dataset, including in-depth segmentation analysis, precise regional revenues, and comprehensive competitive profiles, we invite you to explore the full Worldwide During Production Inspection Market Research report. Equip your organization with the intelligence needed to navigate the future of manufacturing quality with confidence.
Worldwide Automotive Inspection Service Market
For the complete market intelligence and to download the full report, please visit the PW Consulting research portal.
For detailed analysis of this topic, please visit the official page: Worldwide During Production Inspection (DPI) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Brake Force Sensors Market Projected to Hit $897.84M by 2032
By pmarketresearch, 2026-09-16
Strategic Intelligence in Motion: Inside the Global Brake Force Sensors Market
The global automotive and industrial braking landscape is undergoing a structural transformation. As electrification accelerates, regulatory mandates tighten, and x-by-wire architectures transition from concept to production reality, the role of brake force sensors has evolved from a peripheral measurement component to a core enabler of vehicle dynamics, safety assurance, and closed-loop control. For executives navigating capital allocation, supply chain strategy, and technology roadmapping in 2026, a rigorous, forward-looking market intelligence foundation is no longer optional. This analysis introduces our latest Worldwide Brake Force Sensors Market study, designed to equip leadership teams with the analytical clarity required to make high-conviction decisions across a rapidly consolidating and technologically fragmented landscape.
Macro Trajectory and Structural Inflection Points
The brake force sensor market has demonstrated consistent expansion over the past half-decade, driven by the convergence of advanced driver assistance systems, electrification mandates, and the gradual replacement of conventional hydraulic architectures with electromechanical and fully electronic braking platforms. Historical performance from 2020 through 2025 reflects a market that has steadily outpaced broader automotive component growth, with revenue scaling from approximately $315.4 million in 2020 to $485.32 million in 2025. This progression underscores a durable demand curve anchored in both replacement cycles and new-platform integration.
Looking ahead to the 2026–2032 forecast window, the market is positioned to traverse a phase of accelerated commercialization. Revenue is projected to advance from an estimated $520.51 million in 2026 toward a trajectory that reaches $897.84 million by 2032. This expansion corresponds to a compound annual growth rate of 9.2 percent, a pace that reflects both volume-driven adoption and a gradual increase in unit value as sensor suites become more integrated, safety-certified, and functionally dense. The forecast period captures a pivotal inflection: the transition from pilot deployments and limited-series applications toward broader OEM qualification, higher production nomination rates, and multi-platform scaling across passenger vehicles, commercial fleets, and specialized industrial and rail environments.
Importantly, this growth is not uniformly distributed across end markets or technology families. The interplay between architectural adoption curves, certification timelines, and regional manufacturing footprints creates a set of differentiated opportunity pockets. Executives evaluating investment, partnership, or sourcing strategies in 2026 must look beyond top-line momentum and assess where technology maturity, regulatory pressure, and volume concentration intersect. Our full report dissects these structural layers in detail, but the overarching takeaway is clear: brake force sensing is evolving from a discrete component category into an embedded systems discipline, and the competitive advantages of the next cycle will belong to organizations that align technology roadmaps, compliance readiness, and customer qualification pathways early.
Report Architecture: Operational Intelligence for 2026 Decision-Making
This study is constructed as an executive-grade decision-support instrument rather than a retrospective data summary. It integrates historical baselines, forward-looking modeling, technology segmentation, application mapping, competitive profiling, and regulatory impact analysis into a cohesive framework. The objective is to translate market complexity into actionable business logic across strategy, procurement, product development, and corporate development functions.
Worldwide Brake Force Sensors Market
- Forecast methodology grounded in multi-year historical records and structured to capture both base-case adoption and scenario sensitivity across key demand drivers.
- Technology-level assessment spanning strain gauge architectures, piezoelectric solutions, and emerging capacitive and optical approaches, with emphasis on performance envelopes, integration complexity, and cost-to-value positioning.
- Application-side analysis covering automotive brake-by-wire implementations, industrial braking and machinery, research and laboratory testing, and railway and aerospace systems, with attention to the distinct qualification, durability, and safety requirements in each vertical.
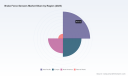
- Regional revenue baselines and operational context that illuminate where manufacturing, sourcing, and customer engagement are concentrated, helping teams evaluate geographic exposure and supply chain resilience.
- Competitive positioning data focused on market concentration, capability differentiation, and strategic movement, enabling benchmarking against incumbents and entrants operating across the sensor value chain.
- Regulatory and standards mapping that connects sensor design and system integration to functional safety expectations, braking performance requirements, and automated braking mandates, providing a practical lens for compliance planning and product definition.
Each section is designed to support a specific class of decision. Strategy teams can use the framework to prioritize geographic and vertical exposure. Product and engineering leaders can benchmark sensor technology trade-offs against system-level constraints. Procurement and supply chain executives can assess concentration risk, qualification lead times, and supplier capability. Corporate development teams can identify adjacency opportunities, partnership targets, and acquisition criteria based on technology fit and market positioning. The report does not simply describe the market; it structures the market in a way that can be directly embedded into planning cycles, investment memos, and product strategy reviews.
Technology and Application Layers: Where Value Is Created
The commercial logic of brake force sensors differs sharply depending on where they sit in the system architecture. In automotive brake-by-wire environments, sensors are increasingly central to closed-loop control strategies, calibration accuracy, and the functional performance of electromechanical brake calipers and drums. Here, value is created not merely through force measurement, but through the integration of sensing precision with control reliability, packaging constraints, and safety certification requirements. As next-generation dry brake systems move toward broader deployment, sensor selection and qualification become tightly coupled with OEM development timelines and platform architecture decisions.
Industrial braking and machinery applications follow a different logic. Demand in this segment is shaped by equipment durability, operational load profiles, and the need for reliable force measurement under variable environmental conditions. Research and laboratory testing represents a specialized but high-precision demand pool, where sensor performance, repeatability, and instrumentation compatibility often outweigh cost considerations. Railway and aerospace systems add further complexity, with qualification rigor, safety cases, and long-life reliability requirements that constrain design choices and elevate the importance of proven supplier track records.
On the technology side, strain gauge-based sensors continue to hold a substantial share of the market, reflecting their established measurement characteristics, integration maturity, and suitability for a wide range of clamping-force and pedal-force applications. Piezoelectric solutions occupy a meaningful position where dynamic response and specific load-sensing requirements come into play. Capacitive and optical sensor approaches represent a smaller but strategically important frontier, often tied to scenarios where non-contact measurement, packaging flexibility, or particular signal characteristics are prioritized. The strategic implication is that no single technology path dominates every use case. Instead, competitive positioning increasingly depends on matching sensor capability to application requirements, certification expectations, and total system cost.
Competitive Landscape and Strategic Positioning
The brake force sensor market exhibits moderate concentration, with a concentrated group of capable suppliers shaping the commercial and technical direction of the category. This structure favors organizations that combine technology depth, application-specific engineering, and consistent qualification success. Several companies stand out for the strategic relevance of their sensor portfolios and the way they align product capability with emerging braking architectures.
Sensata Technologies continues to be closely watched for its focus on micro strain gauge-based brake force sensing designed for direct clamping-force measurement in electromechanical brake calipers and drums. Its sensor work supports closed-loop control in next-generation dry brake systems for passenger cars and electric vehicles, and its production-nomination activity for multiple major automotive brake system manufacturers signals a meaningful step toward integration into future EMB platforms. For competitors and partners alike, this trajectory reinforces the importance of aligning sensor roadmaps with EMB commercialization timing and vehicle electrification strategies.
Methode Electronics brings a distinct angle through magnetoelastic brake pedal force sensors for emergency brake booster applications. Its non-contact measurement approach targets driver-applied pedal force with a specific emphasis on safety-critical boosting functions. In a market where pedal dynamics, fail-safe behavior, and emergency response performance matter, this specialization illustrates how differentiated sensing technologies can create defensible positions in targeted subsystems.
Chassis Sensor Market
TE Connectivity occupies a broad and system-oriented position, supplying force, pressure, position, and speed sensing elements integrated into automotive brake platforms that span hydraulic, electromechanical, and x-by-wire architectures. Its emphasis on functional safety compliance aligns with the direction of the industry, where safety integrity requirements increasingly shape component selection and system architecture. For organizations evaluating supplier partnerships or benchmarking internal capability, TE’s cross-platform footprint underscores the strategic weight of suppliers that can support multiple braking paradigms under unified safety and integration frameworks.
FUTEK Advanced Sensor Technology focuses on pedal force sensing for brake, accelerator, and clutch pedal applications, with load cell solutions tailored to testing and measurement contexts. Strainsert provides both custom and standard force sensors and load cells for automotive brake sensing, research and development, endurance testing, validation, and OEM applications. Althen Sensors contributes specialized automotive force sensing assets, including dedicated brake pedal and hand brake force sensors for dynamic testing and safety-related measurement scenarios. Together, these suppliers highlight the breadth of the market’s demand structure: from high-volume production sensing to specialized validation, testing, and safety-oriented measurement.
From a strategic standpoint, the concentration pattern matters. A meaningful share of market revenue is associated with a relatively small group of dominant players, while the remainder is distributed across specialized contributors with strong technical niches. This creates a dual dynamic: large-scale platform suppliers benefit from qualification scale and integration leverage, while niche specialists compete on precision, customization, and application-specific performance. In 2026, the most effective strategy will likely depend on whether an organization is competing for platform-scale integration, seeking differentiated testing and measurement capabilities, or positioning itself as a compliance-ready supplier for safety-critical brake subsystems.
Regulatory Dynamics and the Compliance Imperative
Regulation and standards are no longer external constraints layered onto product design; they are becoming central drivers of sensor specification, system architecture, and supplier selection. NHTSA’s finalization of FMVSS No. 127, which requires automatic emergency braking systems—including pedestrian automatic emergency braking—on light vehicles with minimum activation above specified speed thresholds and phased implementation for vehicles manufactured after certain 2029 dates, reinforces the demand for reliable brake application sensing and supplementation. As AEB performance expectations rise, the broader ecosystem of sensing, control, and braking response becomes more tightly scrutinized.
At the same time, braking system components, including force measurement elements, must increasingly align with ISO 26262 functional safety expectations in order to achieve the required automotive safety integrity levels for critical brake control functions. This standard imposes disciplined requirements on development processes, risk assessment, verification, and safety argumentation. The practical consequence for sensor manufacturers and system integrators is that functionality alone is insufficient; traceability, robustness, and safety-case readiness now influence commercial eligibility. FMVSS 105 further specifies performance requirements for hydraulic and electric brake systems on heavier vehicles, where force measurement can support compliance testing for service and parking brake systems.
These regulatory currents shape the market in several practical ways. They raise the value of suppliers with mature documentation practices, validated development processes, and demonstrated experience in safety-relevant applications. They increase the importance of design choices that simplify compliance and reduce integration risk for OEMs and Tier suppliers. And they strengthen the strategic relevance of sensor platforms that can be qualified across multiple vehicle classes and braking architectures without fragmenting the compliance burden. For decision-makers, the implication is clear: technology performance, regulatory readiness, and qualification credibility should be evaluated together, not as separate workstreams.
2026 Decision Framework: What Leadership Should Prioritize
As organizations prepare for the next planning cycle, brake force sensor strategy should be evaluated through a multi-dimensional lens. The growth trajectory is supportive, but the more consequential questions concern where share is being created, which technology-application combinations are scaling fastest, and how compliance and qualification timing influence commercial access.
- Platform timing and integration risk: assess how sensor roadmaps align with OEM brake architecture transitions, especially around electromechanical and brake-by-wire platforms where sensing directly affects control performance.
- Qualification and safety readiness: treat functional safety, validation rigor, and documentation capability as commercial differentiators, not just engineering attributes.
- Application diversification: evaluate exposure across automotive, industrial, testing, and rail/aerospace use cases, recognizing that each vertical has distinct volume profiles, price dynamics, and qualification expectations.
- Technology fit versus technology hype: prioritize sensor approaches that match real application constraints, including packaging, durability, signal requirements, and cost structure, rather than pursuing generic specification leadership.
- Supply chain concentration and resilience: understand where revenue and capability are concentrated, and map sourcing strategies against qualification bottlenecks, lead times, and supplier dependency risk.
- Regulatory alignment as a growth enabler: use compliance deadlines and standard requirements to shape product definition, customer engagement timing, and internal investment priorities.
The organizations that will capture disproportionate value in this cycle are those that convert market momentum into disciplined execution: selecting the right application niches, aligning technology choices with system constraints, and building the compliance and qualification infrastructure needed to win on safety-critical platforms.
Accessing the Full Intelligence Package
The analysis above provides a strategic orientation, but it intentionally leaves the most decision-critical detail for the full report. The complete Worldwide Brake Force Sensors Market study delivers the comprehensive segmentation breakdowns, regional revenue baselines, application-level sizing context, technology-level positioning detail, and company-specific capability benchmarks required to support board-level planning, investment review, and product strategy formulation. It also incorporates the development timelines, regulatory dynamics, and concentration patterns that determine where commercial advantage will be won or lost over the 2026–2032 period.
For executives who need to move from market awareness to actionable positioning, the full report offers the granularity, structure, and forward-looking context necessary to support confident decision-making. The market is expanding, the technology landscape is diversifying, and the regulatory environment is raising the bar for supplier credibility. In that environment, the companies that act early with the right intelligence will be best placed to shape their exposure, manage risk, and capture the most valuable segments of the next growth cycle.
For detailed analysis of this topic, please visit the official page: Worldwide Brake Force Sensors Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Halloysite Nanotubes Market to Reach $81.18M by 2032 at 6.52% CAGR
By pmarketresearch, 2026-09-16
Strategic Intelligence for the Decade Ahead: Inside the Worldwide Halloysite Nanotubes Market Report
As industries pivot toward advanced materials that balance performance with sustainability, halloysite nanotubes (HNTs) have emerged as a critical enabler across multiple high-value sectors. From polymer reinforcement to targeted drug delivery, the unique tubular morphology and natural availability of halloysite clay are reshaping material science roadmaps. Yet, translating this technological promise into commercial reality requires more than surface-level familiarity. It demands rigorous, forward-looking intelligence that accounts for pricing dynamics, supply chain constraints, regulatory shifts, and competitive maneuvering.
PW Consulting has just released our comprehensive Worldwide Halloysite Nanotubes Market study, a strategic reference designed specifically for executive decision-makers, investment committees, and R&D leaders who must navigate this evolving landscape through 2032. This article offers a curated preview of the report's analytical architecture. It demonstrates the depth of insight available while preserving the granular segmentation data that forms the core of our commercial intelligence. For teams requiring precise forecasts, regional breakdowns, and actionable entry strategies, the full report remains the definitive source.
Why This Study Matters for 2026 Decision-Making
The materials sector is entering a period of structural recalibration. Supply chains are being reconfigured, environmental and safety regulations are tightening, and end-use industries are demanding materials that deliver measurable performance gains without compromising compliance or cost structures. Halloysite nanotubes sit at the intersection of these forces. Their natural occurrence, combined with adaptable surface chemistry and high-purity availability, positions them as a versatile platform material. However, market participants must understand not only where demand is forming, but how supply concentration, pricing premiums, and processing capabilities will shape profitability over the forecast horizon.
This report is built around that practical imperative. Rather than offering a static snapshot, it maps the market's trajectory from 2020 through 2032, anchoring historical performance to forward-looking projections. The base year of 2025 establishes a clear reference point, while the forecast period captures the expansion dynamics that will define investment and procurement decisions in the coming years. Revenue is tracked in USD millions, providing a consistent financial lens for evaluating opportunity scale and growth pacing.
The compound annual growth rate of 6.52 percent across the forecast window reflects a market that is expanding steadily rather than speculatively. This pacing is significant: it signals sustained adoption curves rather than short-lived hype cycles. For strategic planners, such a trajectory implies the need for measured capacity planning, disciplined R&D allocation, and partnership structures that can scale alongside demand without overexposing organizations to volatility. The full report dissects the drivers behind this growth cadence, separating structural demand from cyclical fluctuations and highlighting the segments where adoption is accelerating fastest.
It is equally important to recognize the market's current size and historical trajectory. The evolution from 2020 to 2025 demonstrates a market that has navigated pricing adjustments, supply refinements, and application maturation. The progression into the late 2020s and early 2030s outlines a clear expansion path, with revenue scaling materially as downstream industries integrate nanotubes into engineered solutions. These macro-level figures provide the scaffolding for more detailed analysis, but the strategic value lies in understanding the forces that pull these numbers upward or temper them at critical junctures. Our report preserves that analytical layering, ensuring that readers see both the headline trajectory and the underlying mechanics.
The Competitive Arena: Concentration, Capability, and Capital
Market structure is a decisive variable in any advanced materials space. The worldwide halloysite nanotubes market is characterized by a consolidated yet dynamic competitive landscape, where a limited number of producers hold outsized influence over supply quality, pricing benchmarks, and application-specific capabilities. Our analysis indicates that the top three players account for approximately 48.5 percent of market revenue, while the top five collectively represent around 62.15 percent. This concentration level has direct implications for procurement strategy, partnership negotiations, and new entrant positioning. Organizations seeking reliable supply or differentiated material grades must understand which firms hold the deposits, processing infrastructure, and application expertise that command premium market positioning.
Several companies define the current competitive baseline, each advancing distinct value propositions. Imerys S.A., headquartered in Paris, France, operates the high-purity halloysite deposit at Matauri Bay in New Zealand. Its product lineage is recognized for high purity and whiteness, with primary supply directed toward fine ceramics and porcelain applications. The company processes and distributes halloysite products globally, reinforcing a reputation built on material consistency and established end-market relationships. Recent operational updates reflect continued adherence to FY 2025 guidance, with stable revenues and the implementation of cost improvement programs, underscoring a disciplined approach to managing high-purity supply chains.
Alongside established mineral processors, a new wave of technology-focused entrants is reshaping the supply narrative. Ionic Mineral Technologies, based in Provo, Utah, USA, controls large high-purity halloysite deposits, including the Halloysite Hills and Silicon Ridge projects, with reserves exceeding 2.4 million tons. Its strategy extends beyond traditional clay supply: the company actively mines halloysite clay as feedstock for proprietary nano-silicon battery materials under the Ionisil™ brand, leveraging low-carbon processing methods. The operational scale is substantial, with reported mining capacity potential of 30,000 metric tons per month from surface deposits using environmentally friendly dry excavation methods. Recent developments reinforce this trajectory: in mid-2025, the company closed an oversubscribed $29 million Series B funding round to scale U.S. production of advanced battery materials derived from halloysite clay feedstock. Later in the year, it confirmed a major high-grade deposit of rare earth and critical technology metals hosted in halloysite ion-adsorption clay at its Silicon Ridge project, with grades near 2,700 ppm in the halloysite fraction, supporting vertically integrated production pathways.
The research-grade and specialty supply segment is anchored by firms that prioritize purity, customization, and immediate availability. American Elements, headquartered in Los Angeles, California, supplies high-purity Halloysite Nanotubes in various grades, reaching up to 99.995 percent purity, for research, coatings, electronics, nanocomposites, and other high-tech applications. Its model emphasizes immediate availability across research to bulk quantities, with custom specifications tailored to technical requirements. Stanford Advanced Materials, based in Lake Forest, California, offers HNTs with specified purity at or above 95 percent, alongside defined tubular morphology parameters, supporting nanomaterials research and industrial applications that depend on consistent structural characteristics.
The broader project landscape also continues to evolve. Andromeda Metals Ltd, for example, completed early works at its Great White Kaolin Project, which contains significant halloysite-kaolin resources, advancing toward Stage 1A construction with reduced equity funding requirements. This type of project progression signals incremental supply-side expansion and reinforces the importance of tracking developmental milestones alongside commercial production metrics. The full report evaluates these moves within a structured competitive framework, mapping company capabilities, resource positions, and strategic orientations without exposing the proprietary segmentation data that underpins our market share and revenue attribution models.
Drivers, Segment Structure, and Application Pathways
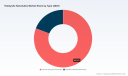
The commercial appeal of halloysite nanotubes derives from their ability to enhance material performance while retaining a natural mineral origin. Their tubular structure, surface reactivity, and compatibility with multiple formulation environments enable a range of application pathways. The market is organized around two primary type categories: natural halloysite nanotubes and modified halloysite nanotubes. This distinction matters because modification alters surface chemistry, dispersion behavior, and functional compatibility, directly influencing which downstream industries can adopt the material at scale. Our analysis examines how these type-based segments interact with processing requirements, pricing dynamics, and end-use performance criteria.
Application diversity is another defining feature. Polymer nanocomposites represent a substantial demand center, leveraging halloysite's reinforcement potential, barrier properties, and thermal stability contributions. Medical and drug delivery applications draw on the material's hollow tubular structure and biocompatibility characteristics, supporting controlled release formulations and targeted delivery concepts. Cosmetics applications exploit texture modulation, film formation, and natural origin attributes that align with consumer preferences for specialized functional ingredients. Paints and coatings formulations utilize halloysite to improve adhesion, durability, and functional additive delivery. Water treatment and other emerging use cases extend the material's addressable market into environmental and industrial processing domains.
Each application pathway carries distinct adoption curves, regulatory considerations, and performance thresholds. The full report disentangles these pathways, identifying which segments are scaling most rapidly, which are constrained by formulation complexity or certification requirements, and where modified versus natural grades create meaningful differentiation. We deliberately withhold the precise regional and application-level revenue splits in this preview, preserving the detailed segmentation architecture for clients who require transaction-ready intelligence. What can be stated is that the segmentation structure reveals clear hierarchy: certain applications command disproportionate share, while others represent high-potential, earlier-stage adoption zones that reward early strategic positioning.
Worldwide Halloysite Nanotubes Market
Boron Nitride Nanotubes (BNNT) Market
Pricing dynamics reinforce the premium nature of this material class. Pure halloysite sells at a premium price of up to approximately US$5,000 per tonne, significantly higher than standard clay materials. This premium is driven by rarity, purity requirements, and suitability for specialized nanotube applications. Such pricing creates both opportunity and risk: it supports margin potential for high-quality producers, but it also raises the stakes for downstream users who must justify material costs through measurable performance gains or regulatory compliance advantages. The report models how pricing behavior interacts with supply capacity, grade differentiation, and application elasticity, providing a realistic basis for procurement and investment planning.
Regulatory and Operational Dynamics
Advanced materials markets do not evolve in a regulatory vacuum. Halloysite clay mining operations are subject to environmental and mineral extraction regulations covering responsible mining, land restoration, water management, and environmental impact assessments. These requirements shape project timelines, capital intensity, and regional supply feasibility. In parallel, the use of halloysite in pharmaceuticals, cosmetics, and food contact materials is governed by chemical safety regulations that influence formulation acceptance, market entry pacing, and compliance cost structures.
These regulatory layers are not mere background conditions; they are strategic variables. Companies that proactively align processing methods, sourcing practices, and product documentation with evolving requirements gain durable advantages in approval speed, customer trust, and market access. The report integrates regulatory dynamics into its forward analysis, examining where compliance pathways are becoming clearer, where uncertainty persists, and how these factors affect segment-by-segment adoption timelines. This enables decision-makers to anticipate friction points rather than react to them after procurement or product development commitments have been made.
Beyond the Headlines: What the Full Study Delivers
A market overview can signal direction, but executive strategy requires structure, detail, and actionable framing. The full Worldwide Halloysite Nanotubes Market report provides a comprehensive operational toolkit designed for strategic use. It includes:
- Historical market sizing from 2020 through 2025, establishing a validated baseline that ties actual performance to identifiable demand and supply developments
- Forecast projections across the 2026 to 2032 period, with pacing that reflects application adoption, capacity expansion, and regulatory maturation rather than optimistic extrapolation
- Segment-by-segment analysis covering type categories and application pathways, with qualitative and quantitative evaluation of growth drivers, constraints, and competitive intensity
- Regional market context that situates demand centers, supply origins, and trade dynamics within a coherent geographic framework, allowing teams to assess where opportunity and exposure concentrate
- Competitive profiling of key companies, integrating resource positions, processing capabilities, product grade offerings, recent financing and project developments, and strategic orientation
- Regulatory and raw material context that connects environmental, extraction, and chemical safety requirements to practical market outcomes
- Strategic implications tailored for procurement, R&D investment, partnership formation, and market entry planning, with emphasis on realistic pacing and risk-aware positioning
The study is structured to serve multiple internal audiences within a single reference framework. Corporate development teams can use it to evaluate partnership and acquisition targets. R&D leaders can align material selection roadmaps with supply availability and grade differentiation. Procurement and supply chain executives can assess concentration risk, pricing behavior, and sourcing resilience. Investors and analysts can ground their models in a consistent set of market parameters and competitive dynamics. By maintaining a unified analytical lens, the report avoids fragmented insights and instead delivers a coordinated view that supports cross-functional decision-making.
How to Use This Intelligence
The most effective use of this report begins with clarity of purpose. Teams evaluating entry into halloysite-enabled applications should focus on the application pathway analysis, the type-based segmentation logic, and the competitive profiles that reveal which suppliers can meet specific purity, morphology, and volume requirements. Organizations already active in the market should prioritize the forecast architecture, pricing context, and regulatory trajectory to stress-test capacity plans, sourcing commitments, and product development timelines. Investors and strategic advisors can leverage the concentration analysis and company-level developments to assess where capital is flowing, which resource positions are being upgraded, and how processing strategies are shifting toward vertically integrated or low-carbon models.
This preview provides the analytical tone, the structural scope, and the strategic framing of the study. It is intentionally designed to demonstrate rigor without disclosing the full segmentation detail, regional revenue distribution, or application-specific monetary assignments that form the report's core commercial value. Those elements are essential for precise planning, and they are available in the complete Worldwide Halloysite Nanotubes Market research. For organizations that need to move from directional awareness to executable strategy, the full report offers the granularity, validation, and forward structure required to make confident 2026 and beyond decisions.
The halloysite nanotubes market is not simply expanding; it is maturing into a strategically significant materials category where purity, processing, regulation, and application fit converge to determine competitive outcomes. PW Consulting's latest study maps that convergence with the depth and discipline that enterprise decision-making demands. The complete intelligence is available now for teams ready to translate market trajectory into actionable advantage.
For detailed analysis of this topic, please visit the official page: Worldwide Halloysite Nanotubes Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Bottom Anti-Reflective Coatings Market Hits $962M in 2025, Projects 6.72% CAGR
By pmarketresearch, 2026-09-16
Strategic Imperatives in the Global Bottom Anti-Reflective Coatings Market: Positioning for 2026 and Beyond
Executive Overview
As semiconductor manufacturers push toward sub-2nm logic nodes and increasingly complex 3D NAND architectures, the role of Bottom Anti-Reflective Coatings (BARC) has evolved from a process optimization tool to a critical enabler of lithography fidelity. PW Consulting's latest Worldwide Bottom Anti-Reflective Coatings Market study delivers a comprehensive, data-driven intelligence framework designed specifically to inform capital allocation, supply chain strategy, and product roadmap decisions throughout 2026 and the subsequent forecast horizon through 2032.
The global BARC market is projected to reach approximately USD 1.52 billion by 2032, expanding at a compound annual growth rate of 6.72 percent from a 2025 baseline of USD 962.0 million. This trajectory reflects sustained demand across advanced lithography nodes, regional capacity realignments, and continuous material innovation by leading chemical suppliers. The report provides executive teams with the analytical depth required to navigate an increasingly complex competitive and regulatory landscape, while deliberately preserving granular segmentation data for direct client access to ensure strategic advantage for decision-makers who require precise, actionable intelligence.
Market Trajectory and Structural Growth Drivers
Historical performance from 2020 through 2025 demonstrates consistent expansion, with the market graduating from mid-eight-figure revenue levels to a 2024 valuation of USD 901.45 million before crossing the USD 962.0 million threshold in 2025. The forecasted period from 2026 to 2032 projects steady acceleration, with annual valuations climbing sequentially to USD 1.03 billion in 2026, USD 1.10 billion in 2027, and continuing through to the 2032 endpoint. This growth profile is underpinned by several interrelated dynamics that the report dissects in detail.
First, the transition from legacy i-line and KrF processes toward ArF immersion and early-stage extreme ultraviolet (EUV) integration continues to reshape material demand profiles. As design rules tighten, the reflectivity control and topography planarization that BARC materials provide become increasingly non-negotiable for yield enhancement. Second, regional manufacturing footprints are undergoing strategic rebalancing, with capacity investments concentrated in geographies that offer both fabrication density and supply chain resilience. Third, the market exhibits pronounced concentration among established specialty chemical players, a structural characteristic that shapes pricing behavior, technology licensing, and customer qualification cycles.
PW Consulting's analysis isolates these drivers from transient market noise, enabling readers to distinguish between structural growth and cyclical fluctuation. The report maps how lithography roadmap decisions, fab build-out schedules, and material qualification timelines interact to produce the observed demand curve, providing a forward-looking framework rather than a retrospective summary.
Competitive Landscape: Concentration, Capability, and Recent Strategic Moves
The BARC sector remains characterized by high barriers to entry, lengthy customer qualification processes, and deep integration with lithography equipment ecosystems. The report examines the competitive architecture through the lens of market concentration metrics, noting that the top three firms command approximately 65.4 percent of global revenue, while the top five collectively represent 82.15 percent. This concentration amplifies the strategic importance of monitoring product launches, capacity expansions, and regulatory certifications among the dominant suppliers.
JSR Corporation, headquartered in Tokyo, maintains a leading position in BARC materials for semiconductor lithography, with product lines such as the AR19 series optimized for ArF and KrF process environments. In October 2025, JSR introduced a new BARC material specifically engineered for EUV lithography compatible with high-NA systems, signaling a direct alignment with next-generation patterning requirements. This launch illustrates the company's strategy of frontend innovation tied to equipment roadmap milestones.
Worldwide Bottom Anti-Reflective Coatings (BARC) Market
Dow Electronic Materials, now operating under DuPont in Midland, Michigan, continues to supply BARC solutions including UV-113 and AR26N for advanced node lithography. The integration of Dow's electronic materials portfolio into DuPont's broader industrial electronics framework has implications for global sales reach, technical support infrastructure, and cross-portfolio bundling strategies. The report evaluates how this corporate restructuring affects competitive positioning within the BARC segment.
Tokyo Ohka Kogyo (TOK), based in Kawaguchi, Japan, manufactures BARC products including the NFC series for i-line, KrF, and ArF immersion lithography applications. In June 2025, TOK announced a capacity expansion at its Kawasaki plant to increase production of BARC resins, explicitly targeting demand associated with 2nm node manufacturing. This capital deployment decision reflects a forward commitment to node-specific volume growth and provides a tangible indicator of near-term supply-side dynamics.
Shin-Etsu Chemical, also headquartered in Tokyo, supplies BARC materials such as SEESOL for deep UV lithography in semiconductor fabrication facilities. In March 2025, Shin-Etsu achieved a significant certification milestone that strengthens its qualification position with major foundry and memory customers. The report contextualizes how certification events translate into revenue recognition timelines and competitive displacement opportunities within tightly managed customer supply chains.
Nissan Chemical Corporation, based in Tokyo, offers BARC products including the NFC-180 and VPC series tailored for 193nm and EUV lithography processes. The company's dual focus on established 193nm applications and next-generation EUV readiness positions it to capture demand across multiple technology transitions. AZ Electronic Materials, now part of Merck KGaA in Darmstadt, Germany, provides BARC formulations such as AZ BARLi for high-resolution lithography in microelectronics, leveraging the broader Merck electronics materials ecosystem for global distribution and technical service.
The study maps how these firms compete across product performance characteristics, regional service coverage, and node-specific qualification portfolios. By analyzing recent developments including product launches, capacity decisions, and certification achievements, the report equips readers with a current competitive intelligence baseline against which to benchmark internal strategies and partnership considerations.
Segmentation Architecture and Strategic Implications
A core strength of the report lies in its structured segmentation framework, which divides the market along three analytical dimensions: geography, material type, and lithography technology. Rather than presenting static allocation percentages, the analysis emphasizes the strategic logic underlying each segmentation axis and how shifts within these categories affect procurement planning, capacity siting, and technology investment decisions.
The regional segmentation examines how demand distribution varies across Asia Pacific, North America, Europe, and the Rest of the World. Given the concentration of advanced logic and memory fabrication in Asia Pacific, this region commands the largest share of market activity, but the report goes further to analyze how localization requirements, export control considerations, and transportation cost structures influence regional procurement strategies. The North American and European segments are evaluated through the lens of domestic semiconductor incentives, specialty chemical manufacturing footprints, and regulatory environments that shape material sourcing decisions.
The type segmentation distinguishes between Organic BARC and Inorganic BARC materials, each serving distinct application profiles and performance requirements. Organic formulations typically offer advantages in planarization and process compatibility for certain lithography workflows, while inorganic alternatives provide different reflectivity control characteristics and thermal stability profiles. The report explores how device makers select between these material classes based on node requirements, process integration constraints, and cost-performance trade-offs.
The lithography segmentation breaks down demand across ArF lithography, KrF lithography, and i-line and other legacy processes. As the industry migrates toward shorter wavelengths and higher resolution requirements, the relative weighting of these categories shifts, with implications for supplier product roadmaps and customer qualification priorities. The report details how this transition affects volume allocation, pricing dynamics, and the pace at which legacy process demand is absorbed or restructured.
Importantly, the full segmentation data, including precise regional revenue figures, type-level breakdowns, and lithography-specific allocations, is preserved within the complete research deliverable. This deliberate structure allows executive readers to absorb the strategic narrative here while reserving precise quantitative allocation data for internal planning sessions where granular figures directly inform budget models and procurement forecasts.
Market Dynamics: Supply Chain, Regulatory, and Trade Environment
Beyond structural growth and competitive positioning, the report delivers an integrated assessment of the operational dynamics that affect BARC market performance throughout the forecast period. These dynamics are not peripheral considerations; they directly influence cost structures, lead times, formulation viability, and regional market access.
On the raw material front, resin monomers such as methacrylic acid derivatives experienced an approximate 8 percent year-over-year price increase due to supply chain constraints, as documented in chemical pricing intelligence from early 2026. This input cost pressure affects formulation economics and may influence supplier pricing strategies, customer negotiation leverage, and the pace at which alternative material pathways are evaluated. The report examines how these cost dynamics propagate through the value chain and where mitigation strategies are most effective.
Regulatory developments introduce additional complexity. Under REACH Annex XVII, restrictions on certain aromatic solvents used in BARC formulations require reformulation for sales within the European Union. This regulatory requirement affects product development timelines, compliance costs, and the competitive positioning of suppliers with different reformulation capabilities. The report assesses how these constraints shape the European market landscape and influence global product platform decisions by multinational chemical manufacturers.
Trade policy developments further alter the operating environment. The US International Trade Commission imposed a 25 percent tariff on BARC imports originating from China under Section 301, effective following the post-2025 review cycle. This tariff structure affects import-dependent procurement strategies, sourcing diversification efforts, and the relative cost competitiveness of domestically produced versus imported materials within the North American market. The analysis explores how these measures interact with broader semiconductor supply chain resilience initiatives.
Transportation cost pressures add another layer of operational consideration. Shipping surcharges of approximately USD 0.15 per kilogram applied to chemical freight movements from Asia to Europe due to Red Sea disruptions, as reflected in late 2025 shipping indices. While such surcharges may fluctuate, they underscore the vulnerability of long-haul chemical logistics to geopolitical and operational disruptions, reinforcing the strategic value of regional inventory positioning and multi-sourced supply networks.
Report Scope and Practical Utility for Decision-Makers
PW Consulting's Worldwide Bottom Anti-Reflective Coatings Market study is structured to serve as a working reference for strategic planning rather than a passive overview. The deliverable includes comprehensive market sizing across historical and forecast periods, segmentation analysis that clarifies demand distribution logic, competitive profiling that connects corporate strategy to market performance, and an integrated assessment of the supply chain, regulatory, and trade factors that shape operational outcomes.
The report is designed for use by senior leadership teams in specialty chemical manufacturing, semiconductor fabrication, lithography equipment supply, and related investment contexts. It supports decisions related to capacity investment timing, product portfolio prioritization, geographic market focus, supplier selection criteria, and risk mitigation planning. By combining quantitative market trajectory with qualitative analysis of competitive moves and external dynamics, the study enables readers to construct internally consistent strategic plans grounded in current market reality.
The complete research package, including precise segmentation figures, company-level market share estimates, regional revenue breakdowns, and detailed forecast tables by type and lithography category, is available through the full report access portal. This structure ensures that executive summaries and strategic narratives can be evaluated broadly while reserving the precise quantitative intelligence that directly feeds budget models, procurement forecasts, and investment committee presentations for the intended decision-making audience.
Anti Reflective Glass Market
Conclusion: Aligning Strategy with Market Trajectory
The BARC market stands at the intersection of semiconductor technology advancement, specialty chemical innovation, and an evolving operational environment shaped by regulatory requirements and trade policy shifts. The projected growth from USD 962.0 million in 2025 to approximately USD 1.52 billion by 2032, at a 6.72 percent CAGR, reflects genuine demand expansion driven by lithography roadmap progression and fabrication intensity. However, capturing value within this trajectory requires more than awareness of the headline numbers.
Success in the 2026 decision environment demands clear understanding of how competitive concentration shapes supplier relationships, how segmentation dynamics influence procurement and capacity strategy, and how raw material costs, regulatory constraints, and trade measures affect the economics of market participation. PW Consulting's study provides the analytical foundation for these determinations, offering a structured and current intelligence base that supports informed strategic action. For organizations seeking to align their 2026 planning with the realities of a growing but structurally complex market, the full research deliverable supplies the depth required to move from strategic awareness to executable planning.
For detailed analysis of this topic, please visit the official page: Worldwide Bottom Anti-Reflective Coatings (BARC) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Dragon’s Blood Market Hits $258.4M in 2025, Projected to Hit $379.4M by 2032 at 5.64% CAGR
By pmarketresearch, 2026-09-16
Strategic Insights into the Global Dragon Blood Market: Navigating Growth and Complexity in 2026 and Beyond
Introduction: The Strategic Imperative for 2026
As the global landscape for botanical actives continues to evolve, Dragon's Blood resin stands out as a compound of significant economic and therapeutic interest. For industry leaders planning their trajectory through 2026 and toward 2032, understanding the nuances of this market is no longer optional—it is a critical component of risk management and opportunity capture. At PW Consulting, we have synthesized extensive primary and secondary research to deliver a comprehensive view of this sector. Our latest market study serves as a navigational tool for stakeholders aiming to capitalize on growth while mitigating the inherent volatility of natural ingredient supply chains.
The period from 2020 to 2025 provided a robust historical baseline, showing a steady upward trend in valuation that underscores the material's growing relevance across multiple verticals. Looking forward, our forecast period extends from 2026 to 2032, offering a long-term perspective essential for capital-intensive decisions. The overall market size has demonstrated consistent momentum, moving from 196.4 million USD in 2020 to a projected 258.4 million USD by the base year of 2025. This trajectory suggests a compound annual growth rate (CAGR) of 5.64 percent throughout the forecast horizon, indicating sustainable expansion rather than speculative bubbles.
Macro Market Dynamics and Future Trajectory
The quantitative backbone of our analysis reveals a market that is maturing yet retains sensitivity to external shocks. From the 2025 baseline of 258.4 million USD, the market is anticipated to reach 276.62 million USD in 2026. This immediate year-over-year growth sets the stage for accelerated expansion in the latter half of the decade. By 2028, valuations are projected to climb to 310.34 million USD, and the curve continues upward to reach 379.39 million USD by 2032. These figures represent more than just revenue; they reflect the increasing integration of Dragon's Blood into mainstream commercial applications.
However, growth rates are not uniform across the timeline. Analysts should note the variability in annual increments, which highlights the importance of timing market entry or expansion. For instance, the jump from 2027 to 2028 represents a significant shift in market volume, suggesting that key regulatory or technological milestones anticipated around that period could act as catalysts. Conversely, the slight moderation in growth pace towards 2031 before the final push in 2032 indicates a market approaching a new equilibrium or facing supply-side constraints that require strategic mitigation.
For decision-makers, these top-line numbers provide the scale necessary to justify investment, but they do not tell the whole story. The true value of this research lies in unpacking the drivers behind these figures without exposing the proprietary granular data that forms the core of our paid intelligence. Understanding whether growth is driven by volume expansion, price premiums, or new application penetration is vital for modeling future cash flows.
Sector Segmentation and Application Dynamics
The versatility of Dragon's Blood resin allows it to permeate diverse industry segments, each with distinct demand drivers and margin profiles. Our research dissects the market across multiple dimensions, including source material and end-use applications, to reveal where value is being created. The segmentation analysis highlights that Cosmetics and Personal Care represents a dominant share of the application landscape, reflecting the ingredient's popularity in skincare formulations aimed at repair and protection. This sector's demand is closely tied to consumer trends favoring natural and bioactive ingredients.
Dragon Blood Market
Pharmaceuticals constitute another significant pillar of demand, where the resin's traditional medicinal properties are being validated through modern standardization processes. The interplay between these two major application areas creates a complex demand structure. While cosmetics may drive volume, pharmaceuticals often drive value through higher purity requirements and regulatory hurdles. Other applications, including Dyes and Incense as well as Food and Beverage, provide niche but stable revenue streams that contribute to the overall market resilience.
On the supply side, the source segmentation indicates a reliance on specific botanical origins. Croton Lechleri remains a primary source, particularly for markets emphasizing South American provenance. However, alternative sources such as Dracaena Cinnabari and Daemonorops also contribute materially to the supply mix, offering geographical diversification that can buffer against regional supply shocks. Other botanical sources round out the portfolio, ensuring that manufacturers have options depending on their specific formulation needs and sourcing ethics.
For a detailed breakdown of revenue contributions by region or specific application sub-segments, stakeholders need to access the full proprietary dataset. The macro segmentation provided here establishes the landscape, but the precise allocation of market share across these categories contains actionable intelligence for targeting specific customer bases or supply contracts.
Competitive Landscape: Key Players and Strategic Positioning
The market structure is characterized by a mix of specialized botanical extract suppliers, large cosmetic ingredient formulators, and regional raw material distributors. Our analysis identifies several key companies that define the current competitive environment. In the premium cosmetic ingredients space, Croda Beauty stands out with its Crodarom® Dragon's Blood EC, a botanical extract positioned for antimicrobial and skin repair benefits. Their UK headquarters and focus on formulation-ready solutions make them a critical partner for Western cosmetic brands seeking reliable supply chains.
COBIOSA, based in Spain, leverages over 50 years of experience in botanical extracts to supply Dragon's Blood hydro-glycolic extract from Croton lechleri latex. Their focus on cosmetic active ingredients highlights the trend toward standardized extracts that ensure batch-to-batch consistency, a crucial factor for high-end skincare manufacturers. Similarly, New Directions Aromatics in Canada provides a liquid extract blend emphasizing emollience and sensory properties, catering to formulators who prioritize the physical characteristics of the ingredient alongside its bioactive potential.
On the raw material and bulk supply side, Amazon Andes specializes in wholesale bulk Dragon's Blood resin and extracts from sustainably wild-harvested Croton lechleri trees in the Peruvian Amazon. Their offering of raw resin, tinctures, and private-label options bridges the gap between primary production and downstream manufacturing. Hawaii Pharm and Herb Pharm represent the herbal supplement segment, producing glycerites and tinctures from various dragon blood sources for digestive and topical support, emphasizing quality control and wildcrafted origins.
In the Asian market, Sichuan XJX operates as a major supplier with extensive harvesting networks, focusing on raw resin distribution. Yunnan Seedshare distinguishes itself as a pharmaceutical-grade producer from Yunnan province, emphasizing standardized extracts and ethical sourcing. Notably, Yunnan Seedshare recently obtained FDA approval for wound-care formulations containing standardized Dragon's Blood resin extracts with 98 percent purity levels, marking a significant regulatory milestone that could open new commercial avenues in the medical device or OTC pharmaceutical sectors. Shamans Market serves a different niche, supplying resin primarily for spiritual, ceremonial, and traditional applications, illustrating the cultural breadth of demand.
The competitive dynamics are further influenced by market concentration metrics. Our data indicates a CR3 of 38.42 percent and a CR5 of 54.18 percent, suggesting a moderately consolidated market where top players hold significant influence but leave room for specialized niche operators. This structure allows for both collaboration and competition, depending on the segment in question.
Supply Chain Resilience and Regulatory Friction
One of the most critical aspects of strategizing for the Dragon Blood market is understanding the constraints inherent in the supply chain. Dragon's Blood resin is primarily sourced from Croton lechleri trees in the Peruvian Amazon, known locally as Sangre de Grado, as well as Dracaena species in Asia and Africa, and Daemonorops draco in Southeast Asia. Suppliers increasingly emphasize sustainable wild-harvesting practices to address slow tree growth and ecological constraints. This biological reality introduces a natural cap on supply expansion that price mechanisms alone cannot easily solve.
Price volatility is a persistent challenge. Raw Dragon's Blood resin spot prices exhibit annual volatility of 40 to 60 percent, influenced by manual extraction processes and supply from specific slow-growing tree species. This level of fluctuation complicates inventory management and cost forecasting for downstream manufacturers. However, value-addition strategies can mitigate some of this risk. Certified organic Dragon's Blood resin commands price premiums of 25 to 40 percent due to sustainable agroforestry initiatives. Projects in Peru have demonstrated yield improvements of up to 65 percent through such initiatives, suggesting that investment in sustainable sourcing can yield both ethical and economic returns.
Regulatory environments add another layer of complexity. In the United States, FDA oversight for Dragon's Blood resin is fragmented, classifying it variously as a supplement, cosmetic ingredient, or traditional medicine depending on intended use. This regulatory ambiguity limits full commercial exploitation to approximately 60 percent of potential applications, as companies must navigate different compliance pathways for different claims. The recent FDA approval for wound-care formulations by Yunnan Seedshare highlights the potential for regulatory progress, but it also underscores the high bar for entry into medical-grade applications. Companies aiming to expand into these higher-value segments must factor in the time and cost associated with rigorous testing and approval processes.
Why This Research Matters for 2026 Decision-Making
In an environment defined by supply volatility, regulatory fragmentation, and evolving consumer preferences, intuition is insufficient for strategic planning. The detailed intelligence contained in our full report provides the granularity required to make informed decisions. Whether you are assessing entry into the cosmetics market, evaluating supply contracts for pharmaceutical ingredients, or analyzing competitor moves in the raw material space, the specific data points hidden within our segmentation models are invaluable.
For 2026 specifically, the convergence of the projected market growth to 276.62 million USD and the evolving regulatory landscape creates a unique window for strategic action. Companies that secure sustainable supply chains now may lock in advantages as demand accelerates toward the 310.34 million USD mark in 2028. Those that understand the price premium dynamics of certified organic resin can better position their products in the premium segments of cosmetics and personal care. Furthermore, recognizing the regulatory bottlenecks allows firms to allocate resources toward initiatives that have the highest probability of approval and commercial success.
Our report goes beyond the macroeconomic trends summarized here. It offers deep dives into regional supply network capabilities, specific application formulation trends, and competitive benchmarking that allows you to calibrate your positioning against players like Croda Beauty, COBIOSA, and the emerging pharmaceutical-grade producers in Asia. It is designed to reduce uncertainty and provide a clear roadmap for navigating the next seven years of market evolution.
Golden Crucible Market
Conclusion and Call to Action
The Dragon Blood market presents a compelling opportunity for growth, backed by a consistent CAGR of 5.64 percent and a diverse application base. However, realizing this opportunity requires a nuanced understanding of the biological, regulatory, and competitive forces at play. The high-level insights provided in this article serve as a trailer for the comprehensive intelligence available in our full market study. To access the detailed segmentation data, regional breakdowns, and specific competitive metrics that will enable precise strategic planning, we invite you to explore the complete report. Equip your organization with the data needed to turn market potential into realized value in 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Dragon Blood Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Insect Repellent Supplies Market Hits $4.85B in 2025, Projected 6.3% CAGR Through 2032
By pmarketresearch, 2026-09-16
Strategic Intelligence for the Global Insect Repellent Supplies Market: Navigating Growth from 2026 to 2032
The global insect repellent supplies market stands at a pivotal juncture as enterprises prepare for the operational and strategic demands of 2026 and beyond. Drawing on comprehensive historical tracking from 2020 through 2025 and a forward-looking forecast window extending to 2032, the latest Worldwide Insect Repellent Supplies Market study delivers a rigorous, data-grounded foundation for executive decision-making. The market has demonstrated consistent expansion, with total revenue climbing from 3,550.0 million in 2020 to 4,850.0 million in 2025. Projections indicate the sector will reach approximately 5,275.98 million in 2026 and continue its upward trajectory toward 7,438.32 million by 2032, supported by a compound annual growth rate of 6.3 percent over the forecast period. These figures are not merely historical snapshots; they represent the baseline against which capacity investments, portfolio reallocations, and geographic prioritization must be calibrated in the current planning cycle.
For corporate strategists, procurement leaders, and commercial directors, the value of this research lies in its ability to translate macro-level momentum into actionable intelligence. The report avoids superficial market descriptions and instead constructs a multi-dimensional view of demand drivers, supply chain realities, regulatory evolution, and competitive positioning. By anchoring analysis in verified historical performance while mapping plausible forward scenarios, the study equips organizations with the clarity required to allocate capital efficiently, anticipate shifts in consumer and industrial procurement behavior, and identify whitespace opportunities before they become crowded.
Mapping the Market Architecture: Segmentation, Concentration, and Structural Shifts
A core strength of the analysis is its detailed segmentation framework, which dissects the market across geography, product type, and formulation chemistry. Rather than presenting static breakdowns, the research examines how each segment contributes to overall revenue dynamics and how structural factors—such as urbanization patterns, outdoor recreation trends, vector-borne disease awareness, and industrial procurement standards—reshape demand over time. The geographic footprint of the market spans five major regions, with Asia Pacific generating 1,842.48 million in revenue, North America contributing 1,196.15 million, Europe accounting for 890.03 million, Latin America at 540.65 million, and the Middle East and Africa representing 380.69 million. These regional totals illuminate where volume and value are concentrated, enabling leadership teams to weigh market-entry timing, distribution partnerships, and localized formulation strategies against operational complexity and regulatory exposure.
Worldwide Insect Repellent Supplies Market
On the product side, the market is divided into vaporizers and sprays, coils and mats, creams and roll-ons, and other supplies. Vaporizers and sprays lead with 2,139.66 million in revenue, reflecting sustained demand for convenient, high-coverage protection formats across both consumer and institutional channels. Coils and mats follow at 1,088.81 million, maintaining relevance in household and spatial protection applications, while creams and roll-ons contribute 951.57 million, underscoring continued preference for targeted, skin-applied solutions. Other supplies round out the landscape at 669.96 million, capturing niche and emerging delivery mechanisms that warrant monitoring as innovation cycles accelerate.
Formulation segmentation further clarifies the market’s directional momentum. Synthetic repellents generate 3,271.74 million, anchored by established active ingredients with well-documented efficacy profiles and broad regulatory acceptance. Natural and plant-based repellents account for 1,578.26 million, representing a rapidly evolving segment where consumer preference, ingredient sourcing, and claim substantiation intersect. The research evaluates how these two formulation pathways compete, complement, and occasionally converge, particularly as manufacturers seek to balance performance, safety perception, and supply chain resilience.
Market concentration data adds another layer of strategic context. The top three players command a combined share of 42.5 percent, while the top five reach 58.8 percent. This concentration profile signals a market where scale, brand equity, and distribution reach confer meaningful advantages, yet it also indicates sufficient openness for specialized players, regional challengers, and ingredient suppliers to capture differentiated positions. The report examines how this concentration interacts with pricing dynamics, innovation cadence, and channel control, helping organizations assess where competitive intensity is likely to intensify and where strategic maneuvering can yield disproportionate returns.
Insect Repellent Market
Competitive Landscape and Recent Industry Developments
The competitive environment is defined by a diverse set of global, regional, and specialty players, each pursuing distinct value propositions across consumer, household, outdoor, and institutional applications. Reckitt Benckiser Group plc, headquartered in Slough, United Kingdom, operates as a major global participant with a broad portfolio spanning sprays, lotions, and coils under recognized brands such as OFF! and Autan, maintaining strong visibility across multiple consumer repellent formats. S.C. Johnson & Son, Inc., based in Racine, Wisconsin, United States, is a leading manufacturer of household and spatial repellents, supplying topical liquids, aerosols, and area protection products worldwide through brands including OFF!, Raid, and Cutter. Spectrum Brands Holdings, Inc., also located in Middleton, Wisconsin, provides consumer-focused repellents under the Repel brand, offering DEET and plant-based options in sprays, lotions, and wipes for personal protection.
In emerging and high-growth markets, Godrej Consumer Products Ltd, headquartered in Mumbai, India, serves as a key provider of mosquito repellent sprays, coils, and lotions, including Goodknight and Hit, with formulations that address both synthetic and natural preferences for household and personal use. The 3M Company, based in St. Paul, Minnesota, contributes insect repellent products and related personal protective supplies designed for outdoor and industrial applications. Sawyer Products, Inc., operating from Safety Harbor, Florida, specializes in high-performance repellents, including controlled-release DEET lotions, permethrin clothing treatments, and picaridin-based products tailored for outdoor, travel, and military use. Coghlan’s Ltd., located in Winnipeg, Manitoba, Canada, serves recreational and travel markets with sprays, towelettes, and natural options for outdoor and camping scenarios.
European and ingredient-focused participants further shape the competitive fabric. Henkel AG & Co. KGaA, based in Düsseldorf, Germany, provides insect repellent formulations and consumer products for personal care and household protection across Europe and global markets. Dabur India Ltd., headquartered in Ghaziabad, India, emphasizes herbal and natural repellents, including Odomos creams and lotions, with a strong focus on ayurvedic and plant-based supplies for Indian and export markets. Thermacell Repellents Inc., from Bedford, Massachusetts, specializes in area repellent devices and mats using allethrin or similar actives, offering spatial protection without direct skin application. Citrefine International Ltd, based in the United Kingdom, manufactures and globally supplies Citriodiol, also known as oil of lemon eucalyptus or PMD, alongside formulated natural repellents for consumer and industrial use. LANXESS, through its Saltigo business in Cologne, Germany, supplies picaridin, marketed as Saltidin or Icaridin, a primary synthetic active ingredient used in numerous topical formulations worldwide. Sumitomo Chemical Co., Ltd., headquartered in Tokyo, Japan, provides pyrethroid-based and other active ingredients for household and spatial repellent devices and formulations. Rentokil Initial plc, located in Camberley, United Kingdom, integrates professional and consumer insect control and repellent supplies within broader pest management services.
Recent corporate activity highlights the market’s accelerating pace of innovation and structural change. In January 2026, BASF completed an acquisition of AgBiTech to expand biological insect control capabilities, strengthening repellent-adjacent and vector management technologies. In June 2025, Mimikai launched its first line of DEET-free insect and tick repellents using natural ingredients for personal protection, signaling continued momentum in alternative formulation strategies. In April 2025, Godrej Consumer Products introduced the Kala HIT Mosquito spray with Thunderbolt technology for household and commercial use, reflecting ongoing product-level differentiation in high-volume categories. Also in February 2025, S.C. Johnson & Son launched a high-speed manufacturing line for spatial mosquito repellents at its Nairobi, Kenya plant, underscoring capacity expansion aligned with regional demand growth. In March 2025, Thermacell Repellents released the E65 rechargeable mosquito repeller with improved battery life and fast-charging capabilities, illustrating how device-based spatial protection continues to evolve around user convenience and performance.
Regulatory Dynamics, Ingredient Supply, and Formulation Realities
Regulatory frameworks and ingredient availability exert a direct influence on product development timelines, claim substantiation, and market access. EPA guidelines under OCSPP 810.3700 specify efficacy testing requirements against Aedes, Anopheles, and Culex mosquitoes for skin-applied insect repellent products, establishing a formal benchmark for performance validation in the United States. In parallel, certain oil of lemon eucalyptus repellent products at 30 percent or less concentration have no age restrictions for use on children under three years, while other products carry specific label warnings, creating a nuanced compliance landscape that manufacturers must navigate with precision. These regulatory signals shape formulation choices, packaging language, and target demographic strategies, particularly for brands seeking to expand into family-oriented and pediatric-adjacent use cases.
On the ingredient side, Citriodiol, derived from lemon eucalyptus oil, continues as a key natural active ingredient supplied globally for effective insect repellent formulations, reinforcing the commercial viability of plant-based pathways when backed by consistent sourcing and quality control. Picaridin, marketed as Saltidin, remains a primary synthetic active ingredient used in topical repellents, valued for low odor and efficacy comparable to DEET. At the same time, the EU Biocidal Products Regulation requires ongoing approvals and dossiers for active substances used in insect repellent products, with Saltigo supporting formulators through its Product Dossier License Scheme. Together, these dynamics illustrate a market where regulatory diligence, ingredient reliability, and formulation expertise are not peripheral concerns but central determinants of competitive readiness.
Strategic Imperatives for 2026 Decision-Making
For organizations operating in or entering this market, the research translates complexity into a set of practical priorities. The first is portfolio alignment: understanding which product formats and formulation types correspond to durable demand versus cyclical or trend-driven interest, and ensuring that innovation pipelines reflect both near-term sell-through potential and longer-term positioning. The second is geographic calibration: using regional revenue patterns and local regulatory conditions to determine where to scale, where to partner, and where to defer investment until distribution or compliance readiness is sufficient. The third is competitive differentiation: recognizing that concentration at the top of the market does not eliminate opportunity for specialized players, particularly those that can combine performance credibility, convenient delivery, and ingredient transparency in ways that resonate with specific user segments.
Operational readiness forms a fourth imperative. Capacity expansions, manufacturing speed, device reliability, and supply chain consistency increasingly separate market leaders from followers, especially as spatial protection devices, rechargeable formats, and high-throughput production lines gain prominence. A fifth priority is regulatory anticipation: building internal processes that can absorb efficacy testing requirements, age-specific labeling rules, and active substance approval cycles without delaying launches or compromising claim integrity. Finally, the research supports scenario-based planning, enabling teams to model how shifts in consumer preference, raw material availability, and regional demand interact across the forecast horizon, rather than relying on single-point assumptions.
Why This Research Matters Now
The Worldwide Insect Repellent Supplies Market study is designed for leaders who need more than top-line growth figures. It integrates historical performance, forward projections, segmentation logic, competitive profiling, regulatory context, and recent corporate developments into a single analytical framework. By presenting market size trajectories, regional revenue distributions, product and formulation splits, and concentration metrics within a structured narrative, the report helps organizations identify where to strengthen existing positions, where to pursue targeted expansion, and where to monitor emerging signals before committing resources. The 6.3 percent CAGR and the progression from 5,275.98 million in 2026 toward 7,438.32 million by 2032 provide a quantified backdrop, while the detailed segmentation, company profiles, and regulatory and ingredient insights supply the operational context required to act with confidence.
Full access to the complete study reveals the deeper analytical layers that support these conclusions, including granular segment performance patterns, competitive positioning maps, regulatory impact assessments, and forward-looking scenario discussions that are essential for precise planning. For teams preparing 2026 commercial strategies, capacity decisions, and portfolio adjustments, the research offers a disciplined foundation for turning market momentum into measured, defensible action.
For detailed analysis of this topic, please visit the official page: Worldwide Insect Repellent Supplies Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting APV Market to Reach $826.67M by 2032, Growing at 8.9% CAGR
By pmarketresearch, 2026-09-16
Strategic Intelligence for 2026: Unlocking Growth in the Global Ammonium Polyvanadate Market
Executive Summary: The Imperative for Precision Intelligence
As global industries navigate the complexities of supply chain reconfiguration and the accelerating energy transition, the demand for specialized chemical intermediates has never been more critical. Ammonium Polyvanadate (APV) stands at the nexus of these trends, serving as a foundational material for metallurgical applications, chemical catalysts, and emerging energy storage technologies. For executive leadership and strategic planners, understanding the trajectory of the APV market is not merely an academic exercise but a operational necessity for capital allocation, risk management, and long-term value creation. Our latest market research publication offers a comprehensive deep dive into this sector, designed specifically to inform high-stakes decision-making throughout 2026 and beyond.
The global landscape for Ammonium Polyvanadate is characterized by robust growth dynamics driven by entrenched industrial demand and nascent technological expansions. Recent analysis indicates that the market generated significant revenue streams in the base year of 2025, building upon a consistent upward trajectory observed over the previous half-decade. With historical data tracing back to 2020, our model captures the resilience of this sector despite geopolitical headwinds and raw material volatility. The forecast period extending through 2032 suggests continued expansion, underpinned by a compound annual growth rate that underscores the material's increasing indispensability in modern manufacturing and energy infrastructure.
This report serves as a strategic compass. In an environment where supply chain transparency is paramount and regulatory frameworks are tightening, blind spots in market intelligence can lead to costly inefficiencies. Whether assessing potential partnerships, evaluating vertical integration opportunities, or forecasting input costs for downstream production, access to granular data is the differentiator between reactive management and proactive strategy. We have structured this analysis to provide clarity amidst complexity, offering a roadmap that aligns market realities with corporate objectives.
Macroeconomic Trajectory and Market Sizing
Historical Performance and Future Projections
The narrative of the APV market over the last five years is one of steady consolidation and growth. Starting from a baseline in the early 2020s, the market has demonstrated an ability to expand even as global manufacturing output fluctuated. By 2025, the total market revenue had reached a substantial milestone, reflecting the accumulated demand from key industrial sectors. This historical context is vital for understanding the baseline volatility and growth elasticity of the commodity.
Looking forward, the projection horizon from 2026 to 2032 paints a picture of accelerating opportunity. The forecast models anticipate that market valuation will climb significantly, potentially surpassing the 800 million USD mark by the early 2030s. This growth is not linear but is influenced by key inflection points related to technological adoption in energy storage and shifts in steelmaking standards. The compound annual growth rate estimated at 8.9 percent highlights a sector that is outpacing many traditional chemical intermediates. For stakeholders, this implies that early positioning in 2026 could yield compounded advantages as the market matures toward 2030 and beyond.
Drivers of Expansion
Several macro forces are converging to support this upward trajectory. First, the enduring demand for high-strength steel and specialized alloys keeps the metallurgical sector as a primary consumption hub. Second, environmental regulations are pushing industries toward cleaner production methods, where vanadium-based chemicals often play a pivotal role in catalytic processes. Third, the emerging interest in long-duration energy storage solutions introduces a new vector for demand growth, although this segment remains in its developmental infancy compared to established industrial uses. Our report dissects these drivers to help you quantify which factors will impact your specific business unit most heavily.
Segmentation Insights: Navigating Value Chains
Regional Dynamics and Supply Hubs
Geographic allocation of production and consumption is a critical component of risk assessment. The market is not uniformly distributed; rather, it is concentrated in specific zones that offer distinct advantages in terms of raw material access and manufacturing capability. Understanding the regional weight of each market helps in planning logistics, sourcing strategies, and exposure to regional regulatory changes. While detailed percentage breakdowns are reserved for the full report, the analysis highlights a dominance in the Asia Pacific region, reflecting the concentration of heavy industry and steel production capacity.
Europe and North America follow as significant contributors, driven by specialized chemical applications and strict environmental compliance requirements that favor higher-grade materials. Emerging regions in Latin America and the Middle East and Africa also present evolving opportunities, often tied to specific mining outputs or localized industrial developments. The report provides a nuanced view of these regional variances, allowing multinational corporations to tailor their regional strategies rather than applying a one-size-fits-all approach. Understanding where value is created versus where it is consumed is essential for optimizing global supply chains.
Grade and Application Segments
The market is bifurcated primarily by grade and application, each carrying different margin profiles and strategic implications. Technical Grade materials serve the bulk of the metallurgical and general chemical needs, focusing on volume and cost-effectiveness. Conversely, High Purity Grade products cater to niche applications where elemental specifications are critical, often commanding higher price points and requiring more sophisticated processing capabilities. Distinguishing between these segments is vital for suppliers deciding where to position their product lines and for buyers seeking to qualify vendors based on specification requirements.
In terms of application, Ferrovanadium Production remains the cornerstone of consumption, linked inextricably to the steel industry. However, other sectors such as Chemical Catalysts and Vanadium Redox Flow Batteries represent areas of strategic interest. The pigment and ceramics sector, while smaller in volume, offers stability. The report provides a detailed mapping of these application streams, analyzing how shifts in one sector might ripple through the others. For instance, a surge in battery technology adoption could eventually pressure supply availability for traditional metallurgical uses, a dynamic that requires careful monitoring.
Competitive Landscape and Key Players
Industry Concentration and Major Entities
The APV market exhibits a moderate level of concentration, with a significant portion of market share held by a select group of industry players. This concentration implies that price discovery and supply stability can be influenced by the strategic moves of these key entities. Market consolidation metrics indicate that the top three players command a notable share, while the top five extend their influence further. This structure suggests that competitive intelligence regarding these firms is crucial for anticipating market shifts.
Among the leading organizations, EVRAZ plc stands out as a major global vanadium producer with significant manufacturing facilities. Their operations are deeply integrated into the ferrovanadium and steel value chains, making them a bellwether for industrial demand trends. In the Asia Pacific region, companies such as Panzhihua Iron and Steel Group and Chengde Xinhua Hebei Vanadium Products play pivotal roles. These entities leverage local raw material advantages, such as vanadium-titanium magnetite ore and vanadium slag, to produce APV for downstream processing.
Other key participants include Hebei Jianlong Vanadium Products, which focuses on high-purity intermediates, and Treibacher Industrie AG, known for supplying commercial-grade materials for specialty applications in Europe. The profiles of these companies are analyzed in depth within the report, covering their production capabilities, strategic focus, and potential vulnerabilities. For competitors, understanding the capacity expansions or contract changes of these entities provides early warning signals of market tightening or loosening.
Strategic Implications of Competition
The interaction between these players defines the market's liquidity and pricing stability. Vertical integration is a common theme, with many producers moving downstream to capture more value or upstream to secure raw material feeds. This integration affects the availability of APV on the merchant market. Our analysis evaluates the degree of integration across the key players and assesses how this might impact pricing power in the forecast period. Buyers must understand whether they are dealing with fully integrated giants or merchant suppliers, as this influences negotiation leverage and supply security.
Regulatory and Geopolitical Context
Critical Raw Materials and Supply Security
The strategic importance of vanadium compounds has been recognized by major regulatory bodies, influencing policy and investment flows. Notably, the inclusion of vanadium in the European Union's Critical Raw Materials list signals a heightened focus on securing strategic supply chains. This designation can lead to incentives for domestic production, restrictions on exports, or increased funding for recycling and substitution research. Companies operating in or supplying to the European market must navigate this regulatory landscape carefully, as it may alter the cost structure and availability of materials.
Furthermore, the global production picture is subject to geopolitical shifts. Data indicates that China remains a dominant force in global vanadium output, representing a significant majority of production. This concentration creates supply chain dependencies that multinational corporations must manage. Simultaneously, production dynamics in other regions, such as Russia, have been affected by international sanctions and broader geopolitical tensions. These factors contribute to supply volatility and can create regional arbitrage opportunities or risks. Our report contextualizes these external pressures, helping firms assess their exposure to specific geographic risks.
Raw Material Foundations
The upstream context is equally important. Global vanadium production volumes provide a ceiling for downstream chemical production. With total global vanadium production measured in thousands of metric tons of contained vanadium, the bottleneck often lies in the conversion efficiency and the specific grade of ore available. Fluctuations in mining output, whether due to operational issues or policy changes, directly impact the feedstock available for APV production. Understanding these upstream constraints allows for more accurate forecasting of chemical availability and cost trajectories.
Strategic Takeaways for 2026 Decision-Makers
Capital Allocation and Investment
For investors and corporate planners, the growth projections suggest that the APV sector offers viable avenues for capital deployment. However, the heterogeneity of the market means that capital should be directed toward segments with the strongest growth fundamentals. The energy storage sector, while currently smaller in volume, represents a high-growth potential area that may require different risk appetites compared to the stable metallurgical segment. Our analysis provides the framework to evaluate these opportunities based on volume projections and margin expectations.
Supply Chain Resilience
Building resilience is a top priority for 2026. Given the geographic concentration of production and the regulatory attention on critical materials, diversifying sourcing is a prudent strategy. The report details the supplier landscape to help organizations identify alternative sources and evaluate their reliability. Long-term contracting strategies versus spot market purchases are also discussed in the context of market volatility and price trends. Securing supply in a concentrated market requires leverage and knowledge that this report aims to provide.
Technology and Substitution Risks
While APV is currently entrenched in key applications, the threat of substitution exists, particularly in catalyst and energy storage sectors. Monitoring technological advancements is essential to anticipate potential disruptions. The report includes an assessment of the competitive landscape of substitutes and the likelihood of adoption barriers. For producers, this informs R&D focus; for consumers, it informs inventory and hedging strategies. Staying ahead of technological curves ensures that market participants are not caught off guard by shifts in material specification requirements.
Worldwide Ammonium Polyvanadate (APV) Market
Worldwide Ammonium Molybdate Market
Conclusion: Accessing the Full Intelligence Picture
The Ammonium Polyvanadate market is at a pivotal juncture where historical stability meets future growth potential. The 2026-2032 forecast period offers a window of opportunity for those equipped with the right intelligence. While this overview provides a snapshot of the macro trends, regional weights, and competitive dynamics, it is only the starting point. The true value lies in the granular data, detailed company profiles, and specific quantitative forecasts that allow for precise modeling and scenario planning.
To fully leverage the insights discussed here and to access the comprehensive data tables, regional splits, and detailed implementation strategies, we invite you to explore the full Worldwide Ammonium Polyvanadate Market research report. Equip your organization with the depth of knowledge required to navigate the complexities of 2026 and secure a strategic advantage in the global marketplace. The complete intelligence package is available via our official channel, providing the detailed breakdown necessary for execution-ready strategy.
For detailed analysis of this topic, please visit the official page: Worldwide Ammonium Polyvanadate (APV) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com