

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting APV Market to Reach $826.67M by 2032, Growing at 8.9% CAGR

Strategic Intelligence for 2026: Unlocking Growth in the Global Ammonium Polyvanadate Market
Executive Summary: The Imperative for Precision Intelligence
As global industries navigate the complexities of supply chain reconfiguration and the accelerating energy transition, the demand for specialized chemical intermediates has never been more critical. Ammonium Polyvanadate (APV) stands at the nexus of these trends, serving as a foundational material for metallurgical applications, chemical catalysts, and emerging energy storage technologies. For executive leadership and strategic planners, understanding the trajectory of the APV market is not merely an academic exercise but a operational necessity for capital allocation, risk management, and long-term value creation. Our latest market research publication offers a comprehensive deep dive into this sector, designed specifically to inform high-stakes decision-making throughout 2026 and beyond.
The global landscape for Ammonium Polyvanadate is characterized by robust growth dynamics driven by entrenched industrial demand and nascent technological expansions. Recent analysis indicates that the market generated significant revenue streams in the base year of 2025, building upon a consistent upward trajectory observed over the previous half-decade. With historical data tracing back to 2020, our model captures the resilience of this sector despite geopolitical headwinds and raw material volatility. The forecast period extending through 2032 suggests continued expansion, underpinned by a compound annual growth rate that underscores the material's increasing indispensability in modern manufacturing and energy infrastructure.
This report serves as a strategic compass. In an environment where supply chain transparency is paramount and regulatory frameworks are tightening, blind spots in market intelligence can lead to costly inefficiencies. Whether assessing potential partnerships, evaluating vertical integration opportunities, or forecasting input costs for downstream production, access to granular data is the differentiator between reactive management and proactive strategy. We have structured this analysis to provide clarity amidst complexity, offering a roadmap that aligns market realities with corporate objectives.
Macroeconomic Trajectory and Market Sizing
Historical Performance and Future Projections
The narrative of the APV market over the last five years is one of steady consolidation and growth. Starting from a baseline in the early 2020s, the market has demonstrated an ability to expand even as global manufacturing output fluctuated. By 2025, the total market revenue had reached a substantial milestone, reflecting the accumulated demand from key industrial sectors. This historical context is vital for understanding the baseline volatility and growth elasticity of the commodity.
Looking forward, the projection horizon from 2026 to 2032 paints a picture of accelerating opportunity. The forecast models anticipate that market valuation will climb significantly, potentially surpassing the 800 million USD mark by the early 2030s. This growth is not linear but is influenced by key inflection points related to technological adoption in energy storage and shifts in steelmaking standards. The compound annual growth rate estimated at 8.9 percent highlights a sector that is outpacing many traditional chemical intermediates. For stakeholders, this implies that early positioning in 2026 could yield compounded advantages as the market matures toward 2030 and beyond.
Drivers of Expansion
Several macro forces are converging to support this upward trajectory. First, the enduring demand for high-strength steel and specialized alloys keeps the metallurgical sector as a primary consumption hub. Second, environmental regulations are pushing industries toward cleaner production methods, where vanadium-based chemicals often play a pivotal role in catalytic processes. Third, the emerging interest in long-duration energy storage solutions introduces a new vector for demand growth, although this segment remains in its developmental infancy compared to established industrial uses. Our report dissects these drivers to help you quantify which factors will impact your specific business unit most heavily.
Segmentation Insights: Navigating Value Chains
Regional Dynamics and Supply Hubs
Geographic allocation of production and consumption is a critical component of risk assessment. The market is not uniformly distributed; rather, it is concentrated in specific zones that offer distinct advantages in terms of raw material access and manufacturing capability. Understanding the regional weight of each market helps in planning logistics, sourcing strategies, and exposure to regional regulatory changes. While detailed percentage breakdowns are reserved for the full report, the analysis highlights a dominance in the Asia Pacific region, reflecting the concentration of heavy industry and steel production capacity.
Europe and North America follow as significant contributors, driven by specialized chemical applications and strict environmental compliance requirements that favor higher-grade materials. Emerging regions in Latin America and the Middle East and Africa also present evolving opportunities, often tied to specific mining outputs or localized industrial developments. The report provides a nuanced view of these regional variances, allowing multinational corporations to tailor their regional strategies rather than applying a one-size-fits-all approach. Understanding where value is created versus where it is consumed is essential for optimizing global supply chains.
Grade and Application Segments
The market is bifurcated primarily by grade and application, each carrying different margin profiles and strategic implications. Technical Grade materials serve the bulk of the metallurgical and general chemical needs, focusing on volume and cost-effectiveness. Conversely, High Purity Grade products cater to niche applications where elemental specifications are critical, often commanding higher price points and requiring more sophisticated processing capabilities. Distinguishing between these segments is vital for suppliers deciding where to position their product lines and for buyers seeking to qualify vendors based on specification requirements.
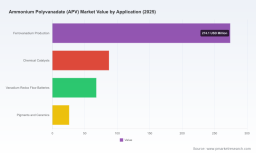
In terms of application, Ferrovanadium Production remains the cornerstone of consumption, linked inextricably to the steel industry. However, other sectors such as Chemical Catalysts and Vanadium Redox Flow Batteries represent areas of strategic interest. The pigment and ceramics sector, while smaller in volume, offers stability. The report provides a detailed mapping of these application streams, analyzing how shifts in one sector might ripple through the others. For instance, a surge in battery technology adoption could eventually pressure supply availability for traditional metallurgical uses, a dynamic that requires careful monitoring.
Competitive Landscape and Key Players
Industry Concentration and Major Entities
The APV market exhibits a moderate level of concentration, with a significant portion of market share held by a select group of industry players. This concentration implies that price discovery and supply stability can be influenced by the strategic moves of these key entities. Market consolidation metrics indicate that the top three players command a notable share, while the top five extend their influence further. This structure suggests that competitive intelligence regarding these firms is crucial for anticipating market shifts.
Among the leading organizations, EVRAZ plc stands out as a major global vanadium producer with significant manufacturing facilities. Their operations are deeply integrated into the ferrovanadium and steel value chains, making them a bellwether for industrial demand trends. In the Asia Pacific region, companies such as Panzhihua Iron and Steel Group and Chengde Xinhua Hebei Vanadium Products play pivotal roles. These entities leverage local raw material advantages, such as vanadium-titanium magnetite ore and vanadium slag, to produce APV for downstream processing.
Other key participants include Hebei Jianlong Vanadium Products, which focuses on high-purity intermediates, and Treibacher Industrie AG, known for supplying commercial-grade materials for specialty applications in Europe. The profiles of these companies are analyzed in depth within the report, covering their production capabilities, strategic focus, and potential vulnerabilities. For competitors, understanding the capacity expansions or contract changes of these entities provides early warning signals of market tightening or loosening.
Strategic Implications of Competition
The interaction between these players defines the market's liquidity and pricing stability. Vertical integration is a common theme, with many producers moving downstream to capture more value or upstream to secure raw material feeds. This integration affects the availability of APV on the merchant market. Our analysis evaluates the degree of integration across the key players and assesses how this might impact pricing power in the forecast period. Buyers must understand whether they are dealing with fully integrated giants or merchant suppliers, as this influences negotiation leverage and supply security.
Regulatory and Geopolitical Context
Critical Raw Materials and Supply Security
The strategic importance of vanadium compounds has been recognized by major regulatory bodies, influencing policy and investment flows. Notably, the inclusion of vanadium in the European Union's Critical Raw Materials list signals a heightened focus on securing strategic supply chains. This designation can lead to incentives for domestic production, restrictions on exports, or increased funding for recycling and substitution research. Companies operating in or supplying to the European market must navigate this regulatory landscape carefully, as it may alter the cost structure and availability of materials.
Furthermore, the global production picture is subject to geopolitical shifts. Data indicates that China remains a dominant force in global vanadium output, representing a significant majority of production. This concentration creates supply chain dependencies that multinational corporations must manage. Simultaneously, production dynamics in other regions, such as Russia, have been affected by international sanctions and broader geopolitical tensions. These factors contribute to supply volatility and can create regional arbitrage opportunities or risks. Our report contextualizes these external pressures, helping firms assess their exposure to specific geographic risks.
Raw Material Foundations
The upstream context is equally important. Global vanadium production volumes provide a ceiling for downstream chemical production. With total global vanadium production measured in thousands of metric tons of contained vanadium, the bottleneck often lies in the conversion efficiency and the specific grade of ore available. Fluctuations in mining output, whether due to operational issues or policy changes, directly impact the feedstock available for APV production. Understanding these upstream constraints allows for more accurate forecasting of chemical availability and cost trajectories.
Strategic Takeaways for 2026 Decision-Makers
Capital Allocation and Investment
For investors and corporate planners, the growth projections suggest that the APV sector offers viable avenues for capital deployment. However, the heterogeneity of the market means that capital should be directed toward segments with the strongest growth fundamentals. The energy storage sector, while currently smaller in volume, represents a high-growth potential area that may require different risk appetites compared to the stable metallurgical segment. Our analysis provides the framework to evaluate these opportunities based on volume projections and margin expectations.
Supply Chain Resilience
Building resilience is a top priority for 2026. Given the geographic concentration of production and the regulatory attention on critical materials, diversifying sourcing is a prudent strategy. The report details the supplier landscape to help organizations identify alternative sources and evaluate their reliability. Long-term contracting strategies versus spot market purchases are also discussed in the context of market volatility and price trends. Securing supply in a concentrated market requires leverage and knowledge that this report aims to provide.
Technology and Substitution Risks
While APV is currently entrenched in key applications, the threat of substitution exists, particularly in catalyst and energy storage sectors. Monitoring technological advancements is essential to anticipate potential disruptions. The report includes an assessment of the competitive landscape of substitutes and the likelihood of adoption barriers. For producers, this informs R&D focus; for consumers, it informs inventory and hedging strategies. Staying ahead of technological curves ensures that market participants are not caught off guard by shifts in material specification requirements.
Worldwide Ammonium Polyvanadate (APV) Market
Worldwide Ammonium Molybdate Market
Conclusion: Accessing the Full Intelligence Picture
The Ammonium Polyvanadate market is at a pivotal juncture where historical stability meets future growth potential. The 2026-2032 forecast period offers a window of opportunity for those equipped with the right intelligence. While this overview provides a snapshot of the macro trends, regional weights, and competitive dynamics, it is only the starting point. The true value lies in the granular data, detailed company profiles, and specific quantitative forecasts that allow for precise modeling and scenario planning.
To fully leverage the insights discussed here and to access the comprehensive data tables, regional splits, and detailed implementation strategies, we invite you to explore the full Worldwide Ammonium Polyvanadate Market research report. Equip your organization with the depth of knowledge required to navigate the complexities of 2026 and secure a strategic advantage in the global marketplace. The complete intelligence package is available via our official channel, providing the detailed breakdown necessary for execution-ready strategy.
For detailed analysis of this topic, please visit the official page: Worldwide Ammonium Polyvanadate (APV) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com