

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Global Halloysite Nanotubes Market to Reach $81.18M by 2032 at 6.52% CAGR

Strategic Intelligence for the Decade Ahead: Inside the Worldwide Halloysite Nanotubes Market Report
As industries pivot toward advanced materials that balance performance with sustainability, halloysite nanotubes (HNTs) have emerged as a critical enabler across multiple high-value sectors. From polymer reinforcement to targeted drug delivery, the unique tubular morphology and natural availability of halloysite clay are reshaping material science roadmaps. Yet, translating this technological promise into commercial reality requires more than surface-level familiarity. It demands rigorous, forward-looking intelligence that accounts for pricing dynamics, supply chain constraints, regulatory shifts, and competitive maneuvering.
PW Consulting has just released our comprehensive Worldwide Halloysite Nanotubes Market study, a strategic reference designed specifically for executive decision-makers, investment committees, and R&D leaders who must navigate this evolving landscape through 2032. This article offers a curated preview of the report's analytical architecture. It demonstrates the depth of insight available while preserving the granular segmentation data that forms the core of our commercial intelligence. For teams requiring precise forecasts, regional breakdowns, and actionable entry strategies, the full report remains the definitive source.
Why This Study Matters for 2026 Decision-Making
The materials sector is entering a period of structural recalibration. Supply chains are being reconfigured, environmental and safety regulations are tightening, and end-use industries are demanding materials that deliver measurable performance gains without compromising compliance or cost structures. Halloysite nanotubes sit at the intersection of these forces. Their natural occurrence, combined with adaptable surface chemistry and high-purity availability, positions them as a versatile platform material. However, market participants must understand not only where demand is forming, but how supply concentration, pricing premiums, and processing capabilities will shape profitability over the forecast horizon.
This report is built around that practical imperative. Rather than offering a static snapshot, it maps the market's trajectory from 2020 through 2032, anchoring historical performance to forward-looking projections. The base year of 2025 establishes a clear reference point, while the forecast period captures the expansion dynamics that will define investment and procurement decisions in the coming years. Revenue is tracked in USD millions, providing a consistent financial lens for evaluating opportunity scale and growth pacing.
The compound annual growth rate of 6.52 percent across the forecast window reflects a market that is expanding steadily rather than speculatively. This pacing is significant: it signals sustained adoption curves rather than short-lived hype cycles. For strategic planners, such a trajectory implies the need for measured capacity planning, disciplined R&D allocation, and partnership structures that can scale alongside demand without overexposing organizations to volatility. The full report dissects the drivers behind this growth cadence, separating structural demand from cyclical fluctuations and highlighting the segments where adoption is accelerating fastest.
It is equally important to recognize the market's current size and historical trajectory. The evolution from 2020 to 2025 demonstrates a market that has navigated pricing adjustments, supply refinements, and application maturation. The progression into the late 2020s and early 2030s outlines a clear expansion path, with revenue scaling materially as downstream industries integrate nanotubes into engineered solutions. These macro-level figures provide the scaffolding for more detailed analysis, but the strategic value lies in understanding the forces that pull these numbers upward or temper them at critical junctures. Our report preserves that analytical layering, ensuring that readers see both the headline trajectory and the underlying mechanics.
The Competitive Arena: Concentration, Capability, and Capital
Market structure is a decisive variable in any advanced materials space. The worldwide halloysite nanotubes market is characterized by a consolidated yet dynamic competitive landscape, where a limited number of producers hold outsized influence over supply quality, pricing benchmarks, and application-specific capabilities. Our analysis indicates that the top three players account for approximately 48.5 percent of market revenue, while the top five collectively represent around 62.15 percent. This concentration level has direct implications for procurement strategy, partnership negotiations, and new entrant positioning. Organizations seeking reliable supply or differentiated material grades must understand which firms hold the deposits, processing infrastructure, and application expertise that command premium market positioning.
Several companies define the current competitive baseline, each advancing distinct value propositions. Imerys S.A., headquartered in Paris, France, operates the high-purity halloysite deposit at Matauri Bay in New Zealand. Its product lineage is recognized for high purity and whiteness, with primary supply directed toward fine ceramics and porcelain applications. The company processes and distributes halloysite products globally, reinforcing a reputation built on material consistency and established end-market relationships. Recent operational updates reflect continued adherence to FY 2025 guidance, with stable revenues and the implementation of cost improvement programs, underscoring a disciplined approach to managing high-purity supply chains.
Alongside established mineral processors, a new wave of technology-focused entrants is reshaping the supply narrative. Ionic Mineral Technologies, based in Provo, Utah, USA, controls large high-purity halloysite deposits, including the Halloysite Hills and Silicon Ridge projects, with reserves exceeding 2.4 million tons. Its strategy extends beyond traditional clay supply: the company actively mines halloysite clay as feedstock for proprietary nano-silicon battery materials under the Ionisil™ brand, leveraging low-carbon processing methods. The operational scale is substantial, with reported mining capacity potential of 30,000 metric tons per month from surface deposits using environmentally friendly dry excavation methods. Recent developments reinforce this trajectory: in mid-2025, the company closed an oversubscribed $29 million Series B funding round to scale U.S. production of advanced battery materials derived from halloysite clay feedstock. Later in the year, it confirmed a major high-grade deposit of rare earth and critical technology metals hosted in halloysite ion-adsorption clay at its Silicon Ridge project, with grades near 2,700 ppm in the halloysite fraction, supporting vertically integrated production pathways.
The research-grade and specialty supply segment is anchored by firms that prioritize purity, customization, and immediate availability. American Elements, headquartered in Los Angeles, California, supplies high-purity Halloysite Nanotubes in various grades, reaching up to 99.995 percent purity, for research, coatings, electronics, nanocomposites, and other high-tech applications. Its model emphasizes immediate availability across research to bulk quantities, with custom specifications tailored to technical requirements. Stanford Advanced Materials, based in Lake Forest, California, offers HNTs with specified purity at or above 95 percent, alongside defined tubular morphology parameters, supporting nanomaterials research and industrial applications that depend on consistent structural characteristics.
The broader project landscape also continues to evolve. Andromeda Metals Ltd, for example, completed early works at its Great White Kaolin Project, which contains significant halloysite-kaolin resources, advancing toward Stage 1A construction with reduced equity funding requirements. This type of project progression signals incremental supply-side expansion and reinforces the importance of tracking developmental milestones alongside commercial production metrics. The full report evaluates these moves within a structured competitive framework, mapping company capabilities, resource positions, and strategic orientations without exposing the proprietary segmentation data that underpins our market share and revenue attribution models.
Drivers, Segment Structure, and Application Pathways
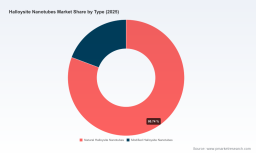
The commercial appeal of halloysite nanotubes derives from their ability to enhance material performance while retaining a natural mineral origin. Their tubular structure, surface reactivity, and compatibility with multiple formulation environments enable a range of application pathways. The market is organized around two primary type categories: natural halloysite nanotubes and modified halloysite nanotubes. This distinction matters because modification alters surface chemistry, dispersion behavior, and functional compatibility, directly influencing which downstream industries can adopt the material at scale. Our analysis examines how these type-based segments interact with processing requirements, pricing dynamics, and end-use performance criteria.
Application diversity is another defining feature. Polymer nanocomposites represent a substantial demand center, leveraging halloysite's reinforcement potential, barrier properties, and thermal stability contributions. Medical and drug delivery applications draw on the material's hollow tubular structure and biocompatibility characteristics, supporting controlled release formulations and targeted delivery concepts. Cosmetics applications exploit texture modulation, film formation, and natural origin attributes that align with consumer preferences for specialized functional ingredients. Paints and coatings formulations utilize halloysite to improve adhesion, durability, and functional additive delivery. Water treatment and other emerging use cases extend the material's addressable market into environmental and industrial processing domains.
Each application pathway carries distinct adoption curves, regulatory considerations, and performance thresholds. The full report disentangles these pathways, identifying which segments are scaling most rapidly, which are constrained by formulation complexity or certification requirements, and where modified versus natural grades create meaningful differentiation. We deliberately withhold the precise regional and application-level revenue splits in this preview, preserving the detailed segmentation architecture for clients who require transaction-ready intelligence. What can be stated is that the segmentation structure reveals clear hierarchy: certain applications command disproportionate share, while others represent high-potential, earlier-stage adoption zones that reward early strategic positioning.
Worldwide Halloysite Nanotubes Market
Boron Nitride Nanotubes (BNNT) Market
Pricing dynamics reinforce the premium nature of this material class. Pure halloysite sells at a premium price of up to approximately US$5,000 per tonne, significantly higher than standard clay materials. This premium is driven by rarity, purity requirements, and suitability for specialized nanotube applications. Such pricing creates both opportunity and risk: it supports margin potential for high-quality producers, but it also raises the stakes for downstream users who must justify material costs through measurable performance gains or regulatory compliance advantages. The report models how pricing behavior interacts with supply capacity, grade differentiation, and application elasticity, providing a realistic basis for procurement and investment planning.
Regulatory and Operational Dynamics
Advanced materials markets do not evolve in a regulatory vacuum. Halloysite clay mining operations are subject to environmental and mineral extraction regulations covering responsible mining, land restoration, water management, and environmental impact assessments. These requirements shape project timelines, capital intensity, and regional supply feasibility. In parallel, the use of halloysite in pharmaceuticals, cosmetics, and food contact materials is governed by chemical safety regulations that influence formulation acceptance, market entry pacing, and compliance cost structures.
These regulatory layers are not mere background conditions; they are strategic variables. Companies that proactively align processing methods, sourcing practices, and product documentation with evolving requirements gain durable advantages in approval speed, customer trust, and market access. The report integrates regulatory dynamics into its forward analysis, examining where compliance pathways are becoming clearer, where uncertainty persists, and how these factors affect segment-by-segment adoption timelines. This enables decision-makers to anticipate friction points rather than react to them after procurement or product development commitments have been made.
Beyond the Headlines: What the Full Study Delivers
A market overview can signal direction, but executive strategy requires structure, detail, and actionable framing. The full Worldwide Halloysite Nanotubes Market report provides a comprehensive operational toolkit designed for strategic use. It includes:
- Historical market sizing from 2020 through 2025, establishing a validated baseline that ties actual performance to identifiable demand and supply developments
- Forecast projections across the 2026 to 2032 period, with pacing that reflects application adoption, capacity expansion, and regulatory maturation rather than optimistic extrapolation
- Segment-by-segment analysis covering type categories and application pathways, with qualitative and quantitative evaluation of growth drivers, constraints, and competitive intensity
- Regional market context that situates demand centers, supply origins, and trade dynamics within a coherent geographic framework, allowing teams to assess where opportunity and exposure concentrate
- Competitive profiling of key companies, integrating resource positions, processing capabilities, product grade offerings, recent financing and project developments, and strategic orientation
- Regulatory and raw material context that connects environmental, extraction, and chemical safety requirements to practical market outcomes
- Strategic implications tailored for procurement, R&D investment, partnership formation, and market entry planning, with emphasis on realistic pacing and risk-aware positioning
The study is structured to serve multiple internal audiences within a single reference framework. Corporate development teams can use it to evaluate partnership and acquisition targets. R&D leaders can align material selection roadmaps with supply availability and grade differentiation. Procurement and supply chain executives can assess concentration risk, pricing behavior, and sourcing resilience. Investors and analysts can ground their models in a consistent set of market parameters and competitive dynamics. By maintaining a unified analytical lens, the report avoids fragmented insights and instead delivers a coordinated view that supports cross-functional decision-making.
How to Use This Intelligence
The most effective use of this report begins with clarity of purpose. Teams evaluating entry into halloysite-enabled applications should focus on the application pathway analysis, the type-based segmentation logic, and the competitive profiles that reveal which suppliers can meet specific purity, morphology, and volume requirements. Organizations already active in the market should prioritize the forecast architecture, pricing context, and regulatory trajectory to stress-test capacity plans, sourcing commitments, and product development timelines. Investors and strategic advisors can leverage the concentration analysis and company-level developments to assess where capital is flowing, which resource positions are being upgraded, and how processing strategies are shifting toward vertically integrated or low-carbon models.
This preview provides the analytical tone, the structural scope, and the strategic framing of the study. It is intentionally designed to demonstrate rigor without disclosing the full segmentation detail, regional revenue distribution, or application-specific monetary assignments that form the report's core commercial value. Those elements are essential for precise planning, and they are available in the complete Worldwide Halloysite Nanotubes Market research. For organizations that need to move from directional awareness to executable strategy, the full report offers the granularity, validation, and forward structure required to make confident 2026 and beyond decisions.
The halloysite nanotubes market is not simply expanding; it is maturing into a strategically significant materials category where purity, processing, regulation, and application fit converge to determine competitive outcomes. PW Consulting's latest study maps that convergence with the depth and discipline that enterprise decision-making demands. The complete intelligence is available now for teams ready to translate market trajectory into actionable advantage.
For detailed analysis of this topic, please visit the official page: Worldwide Halloysite Nanotubes Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com