

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Global Brake Force Sensors Market Projected to Hit $897.84M by 2032

Strategic Intelligence in Motion: Inside the Global Brake Force Sensors Market
The global automotive and industrial braking landscape is undergoing a structural transformation. As electrification accelerates, regulatory mandates tighten, and x-by-wire architectures transition from concept to production reality, the role of brake force sensors has evolved from a peripheral measurement component to a core enabler of vehicle dynamics, safety assurance, and closed-loop control. For executives navigating capital allocation, supply chain strategy, and technology roadmapping in 2026, a rigorous, forward-looking market intelligence foundation is no longer optional. This analysis introduces our latest Worldwide Brake Force Sensors Market study, designed to equip leadership teams with the analytical clarity required to make high-conviction decisions across a rapidly consolidating and technologically fragmented landscape.
Macro Trajectory and Structural Inflection Points
The brake force sensor market has demonstrated consistent expansion over the past half-decade, driven by the convergence of advanced driver assistance systems, electrification mandates, and the gradual replacement of conventional hydraulic architectures with electromechanical and fully electronic braking platforms. Historical performance from 2020 through 2025 reflects a market that has steadily outpaced broader automotive component growth, with revenue scaling from approximately $315.4 million in 2020 to $485.32 million in 2025. This progression underscores a durable demand curve anchored in both replacement cycles and new-platform integration.
Looking ahead to the 2026–2032 forecast window, the market is positioned to traverse a phase of accelerated commercialization. Revenue is projected to advance from an estimated $520.51 million in 2026 toward a trajectory that reaches $897.84 million by 2032. This expansion corresponds to a compound annual growth rate of 9.2 percent, a pace that reflects both volume-driven adoption and a gradual increase in unit value as sensor suites become more integrated, safety-certified, and functionally dense. The forecast period captures a pivotal inflection: the transition from pilot deployments and limited-series applications toward broader OEM qualification, higher production nomination rates, and multi-platform scaling across passenger vehicles, commercial fleets, and specialized industrial and rail environments.
Importantly, this growth is not uniformly distributed across end markets or technology families. The interplay between architectural adoption curves, certification timelines, and regional manufacturing footprints creates a set of differentiated opportunity pockets. Executives evaluating investment, partnership, or sourcing strategies in 2026 must look beyond top-line momentum and assess where technology maturity, regulatory pressure, and volume concentration intersect. Our full report dissects these structural layers in detail, but the overarching takeaway is clear: brake force sensing is evolving from a discrete component category into an embedded systems discipline, and the competitive advantages of the next cycle will belong to organizations that align technology roadmaps, compliance readiness, and customer qualification pathways early.
Report Architecture: Operational Intelligence for 2026 Decision-Making
This study is constructed as an executive-grade decision-support instrument rather than a retrospective data summary. It integrates historical baselines, forward-looking modeling, technology segmentation, application mapping, competitive profiling, and regulatory impact analysis into a cohesive framework. The objective is to translate market complexity into actionable business logic across strategy, procurement, product development, and corporate development functions.
Worldwide Brake Force Sensors Market
- Forecast methodology grounded in multi-year historical records and structured to capture both base-case adoption and scenario sensitivity across key demand drivers.
- Technology-level assessment spanning strain gauge architectures, piezoelectric solutions, and emerging capacitive and optical approaches, with emphasis on performance envelopes, integration complexity, and cost-to-value positioning.
- Application-side analysis covering automotive brake-by-wire implementations, industrial braking and machinery, research and laboratory testing, and railway and aerospace systems, with attention to the distinct qualification, durability, and safety requirements in each vertical.
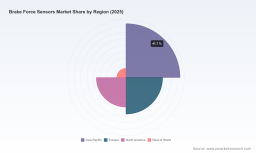
- Regional revenue baselines and operational context that illuminate where manufacturing, sourcing, and customer engagement are concentrated, helping teams evaluate geographic exposure and supply chain resilience.
- Competitive positioning data focused on market concentration, capability differentiation, and strategic movement, enabling benchmarking against incumbents and entrants operating across the sensor value chain.
- Regulatory and standards mapping that connects sensor design and system integration to functional safety expectations, braking performance requirements, and automated braking mandates, providing a practical lens for compliance planning and product definition.
Each section is designed to support a specific class of decision. Strategy teams can use the framework to prioritize geographic and vertical exposure. Product and engineering leaders can benchmark sensor technology trade-offs against system-level constraints. Procurement and supply chain executives can assess concentration risk, qualification lead times, and supplier capability. Corporate development teams can identify adjacency opportunities, partnership targets, and acquisition criteria based on technology fit and market positioning. The report does not simply describe the market; it structures the market in a way that can be directly embedded into planning cycles, investment memos, and product strategy reviews.
Technology and Application Layers: Where Value Is Created
The commercial logic of brake force sensors differs sharply depending on where they sit in the system architecture. In automotive brake-by-wire environments, sensors are increasingly central to closed-loop control strategies, calibration accuracy, and the functional performance of electromechanical brake calipers and drums. Here, value is created not merely through force measurement, but through the integration of sensing precision with control reliability, packaging constraints, and safety certification requirements. As next-generation dry brake systems move toward broader deployment, sensor selection and qualification become tightly coupled with OEM development timelines and platform architecture decisions.
Industrial braking and machinery applications follow a different logic. Demand in this segment is shaped by equipment durability, operational load profiles, and the need for reliable force measurement under variable environmental conditions. Research and laboratory testing represents a specialized but high-precision demand pool, where sensor performance, repeatability, and instrumentation compatibility often outweigh cost considerations. Railway and aerospace systems add further complexity, with qualification rigor, safety cases, and long-life reliability requirements that constrain design choices and elevate the importance of proven supplier track records.
On the technology side, strain gauge-based sensors continue to hold a substantial share of the market, reflecting their established measurement characteristics, integration maturity, and suitability for a wide range of clamping-force and pedal-force applications. Piezoelectric solutions occupy a meaningful position where dynamic response and specific load-sensing requirements come into play. Capacitive and optical sensor approaches represent a smaller but strategically important frontier, often tied to scenarios where non-contact measurement, packaging flexibility, or particular signal characteristics are prioritized. The strategic implication is that no single technology path dominates every use case. Instead, competitive positioning increasingly depends on matching sensor capability to application requirements, certification expectations, and total system cost.
Competitive Landscape and Strategic Positioning
The brake force sensor market exhibits moderate concentration, with a concentrated group of capable suppliers shaping the commercial and technical direction of the category. This structure favors organizations that combine technology depth, application-specific engineering, and consistent qualification success. Several companies stand out for the strategic relevance of their sensor portfolios and the way they align product capability with emerging braking architectures.
Sensata Technologies continues to be closely watched for its focus on micro strain gauge-based brake force sensing designed for direct clamping-force measurement in electromechanical brake calipers and drums. Its sensor work supports closed-loop control in next-generation dry brake systems for passenger cars and electric vehicles, and its production-nomination activity for multiple major automotive brake system manufacturers signals a meaningful step toward integration into future EMB platforms. For competitors and partners alike, this trajectory reinforces the importance of aligning sensor roadmaps with EMB commercialization timing and vehicle electrification strategies.
Methode Electronics brings a distinct angle through magnetoelastic brake pedal force sensors for emergency brake booster applications. Its non-contact measurement approach targets driver-applied pedal force with a specific emphasis on safety-critical boosting functions. In a market where pedal dynamics, fail-safe behavior, and emergency response performance matter, this specialization illustrates how differentiated sensing technologies can create defensible positions in targeted subsystems.
Chassis Sensor Market
TE Connectivity occupies a broad and system-oriented position, supplying force, pressure, position, and speed sensing elements integrated into automotive brake platforms that span hydraulic, electromechanical, and x-by-wire architectures. Its emphasis on functional safety compliance aligns with the direction of the industry, where safety integrity requirements increasingly shape component selection and system architecture. For organizations evaluating supplier partnerships or benchmarking internal capability, TE’s cross-platform footprint underscores the strategic weight of suppliers that can support multiple braking paradigms under unified safety and integration frameworks.
FUTEK Advanced Sensor Technology focuses on pedal force sensing for brake, accelerator, and clutch pedal applications, with load cell solutions tailored to testing and measurement contexts. Strainsert provides both custom and standard force sensors and load cells for automotive brake sensing, research and development, endurance testing, validation, and OEM applications. Althen Sensors contributes specialized automotive force sensing assets, including dedicated brake pedal and hand brake force sensors for dynamic testing and safety-related measurement scenarios. Together, these suppliers highlight the breadth of the market’s demand structure: from high-volume production sensing to specialized validation, testing, and safety-oriented measurement.
From a strategic standpoint, the concentration pattern matters. A meaningful share of market revenue is associated with a relatively small group of dominant players, while the remainder is distributed across specialized contributors with strong technical niches. This creates a dual dynamic: large-scale platform suppliers benefit from qualification scale and integration leverage, while niche specialists compete on precision, customization, and application-specific performance. In 2026, the most effective strategy will likely depend on whether an organization is competing for platform-scale integration, seeking differentiated testing and measurement capabilities, or positioning itself as a compliance-ready supplier for safety-critical brake subsystems.
Regulatory Dynamics and the Compliance Imperative
Regulation and standards are no longer external constraints layered onto product design; they are becoming central drivers of sensor specification, system architecture, and supplier selection. NHTSA’s finalization of FMVSS No. 127, which requires automatic emergency braking systems—including pedestrian automatic emergency braking—on light vehicles with minimum activation above specified speed thresholds and phased implementation for vehicles manufactured after certain 2029 dates, reinforces the demand for reliable brake application sensing and supplementation. As AEB performance expectations rise, the broader ecosystem of sensing, control, and braking response becomes more tightly scrutinized.
At the same time, braking system components, including force measurement elements, must increasingly align with ISO 26262 functional safety expectations in order to achieve the required automotive safety integrity levels for critical brake control functions. This standard imposes disciplined requirements on development processes, risk assessment, verification, and safety argumentation. The practical consequence for sensor manufacturers and system integrators is that functionality alone is insufficient; traceability, robustness, and safety-case readiness now influence commercial eligibility. FMVSS 105 further specifies performance requirements for hydraulic and electric brake systems on heavier vehicles, where force measurement can support compliance testing for service and parking brake systems.
These regulatory currents shape the market in several practical ways. They raise the value of suppliers with mature documentation practices, validated development processes, and demonstrated experience in safety-relevant applications. They increase the importance of design choices that simplify compliance and reduce integration risk for OEMs and Tier suppliers. And they strengthen the strategic relevance of sensor platforms that can be qualified across multiple vehicle classes and braking architectures without fragmenting the compliance burden. For decision-makers, the implication is clear: technology performance, regulatory readiness, and qualification credibility should be evaluated together, not as separate workstreams.
2026 Decision Framework: What Leadership Should Prioritize
As organizations prepare for the next planning cycle, brake force sensor strategy should be evaluated through a multi-dimensional lens. The growth trajectory is supportive, but the more consequential questions concern where share is being created, which technology-application combinations are scaling fastest, and how compliance and qualification timing influence commercial access.
- Platform timing and integration risk: assess how sensor roadmaps align with OEM brake architecture transitions, especially around electromechanical and brake-by-wire platforms where sensing directly affects control performance.
- Qualification and safety readiness: treat functional safety, validation rigor, and documentation capability as commercial differentiators, not just engineering attributes.
- Application diversification: evaluate exposure across automotive, industrial, testing, and rail/aerospace use cases, recognizing that each vertical has distinct volume profiles, price dynamics, and qualification expectations.
- Technology fit versus technology hype: prioritize sensor approaches that match real application constraints, including packaging, durability, signal requirements, and cost structure, rather than pursuing generic specification leadership.
- Supply chain concentration and resilience: understand where revenue and capability are concentrated, and map sourcing strategies against qualification bottlenecks, lead times, and supplier dependency risk.
- Regulatory alignment as a growth enabler: use compliance deadlines and standard requirements to shape product definition, customer engagement timing, and internal investment priorities.
The organizations that will capture disproportionate value in this cycle are those that convert market momentum into disciplined execution: selecting the right application niches, aligning technology choices with system constraints, and building the compliance and qualification infrastructure needed to win on safety-critical platforms.
Accessing the Full Intelligence Package
The analysis above provides a strategic orientation, but it intentionally leaves the most decision-critical detail for the full report. The complete Worldwide Brake Force Sensors Market study delivers the comprehensive segmentation breakdowns, regional revenue baselines, application-level sizing context, technology-level positioning detail, and company-specific capability benchmarks required to support board-level planning, investment review, and product strategy formulation. It also incorporates the development timelines, regulatory dynamics, and concentration patterns that determine where commercial advantage will be won or lost over the 2026–2032 period.
For executives who need to move from market awareness to actionable positioning, the full report offers the granularity, structure, and forward-looking context necessary to support confident decision-making. The market is expanding, the technology landscape is diversifying, and the regulatory environment is raising the bar for supplier credibility. In that environment, the companies that act early with the right intelligence will be best placed to shape their exposure, manage risk, and capture the most valuable segments of the next growth cycle.
For detailed analysis of this topic, please visit the official page: Worldwide Brake Force Sensors Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com