

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Bottom Anti-Reflective Coatings Market Hits $962M in 2025, Projects 6.72% CAGR

Strategic Imperatives in the Global Bottom Anti-Reflective Coatings Market: Positioning for 2026 and Beyond
Executive Overview
As semiconductor manufacturers push toward sub-2nm logic nodes and increasingly complex 3D NAND architectures, the role of Bottom Anti-Reflective Coatings (BARC) has evolved from a process optimization tool to a critical enabler of lithography fidelity. PW Consulting's latest Worldwide Bottom Anti-Reflective Coatings Market study delivers a comprehensive, data-driven intelligence framework designed specifically to inform capital allocation, supply chain strategy, and product roadmap decisions throughout 2026 and the subsequent forecast horizon through 2032.
The global BARC market is projected to reach approximately USD 1.52 billion by 2032, expanding at a compound annual growth rate of 6.72 percent from a 2025 baseline of USD 962.0 million. This trajectory reflects sustained demand across advanced lithography nodes, regional capacity realignments, and continuous material innovation by leading chemical suppliers. The report provides executive teams with the analytical depth required to navigate an increasingly complex competitive and regulatory landscape, while deliberately preserving granular segmentation data for direct client access to ensure strategic advantage for decision-makers who require precise, actionable intelligence.
Market Trajectory and Structural Growth Drivers
Historical performance from 2020 through 2025 demonstrates consistent expansion, with the market graduating from mid-eight-figure revenue levels to a 2024 valuation of USD 901.45 million before crossing the USD 962.0 million threshold in 2025. The forecasted period from 2026 to 2032 projects steady acceleration, with annual valuations climbing sequentially to USD 1.03 billion in 2026, USD 1.10 billion in 2027, and continuing through to the 2032 endpoint. This growth profile is underpinned by several interrelated dynamics that the report dissects in detail.
First, the transition from legacy i-line and KrF processes toward ArF immersion and early-stage extreme ultraviolet (EUV) integration continues to reshape material demand profiles. As design rules tighten, the reflectivity control and topography planarization that BARC materials provide become increasingly non-negotiable for yield enhancement. Second, regional manufacturing footprints are undergoing strategic rebalancing, with capacity investments concentrated in geographies that offer both fabrication density and supply chain resilience. Third, the market exhibits pronounced concentration among established specialty chemical players, a structural characteristic that shapes pricing behavior, technology licensing, and customer qualification cycles.
PW Consulting's analysis isolates these drivers from transient market noise, enabling readers to distinguish between structural growth and cyclical fluctuation. The report maps how lithography roadmap decisions, fab build-out schedules, and material qualification timelines interact to produce the observed demand curve, providing a forward-looking framework rather than a retrospective summary.
Competitive Landscape: Concentration, Capability, and Recent Strategic Moves
The BARC sector remains characterized by high barriers to entry, lengthy customer qualification processes, and deep integration with lithography equipment ecosystems. The report examines the competitive architecture through the lens of market concentration metrics, noting that the top three firms command approximately 65.4 percent of global revenue, while the top five collectively represent 82.15 percent. This concentration amplifies the strategic importance of monitoring product launches, capacity expansions, and regulatory certifications among the dominant suppliers.
JSR Corporation, headquartered in Tokyo, maintains a leading position in BARC materials for semiconductor lithography, with product lines such as the AR19 series optimized for ArF and KrF process environments. In October 2025, JSR introduced a new BARC material specifically engineered for EUV lithography compatible with high-NA systems, signaling a direct alignment with next-generation patterning requirements. This launch illustrates the company's strategy of frontend innovation tied to equipment roadmap milestones.
Worldwide Bottom Anti-Reflective Coatings (BARC) Market
Dow Electronic Materials, now operating under DuPont in Midland, Michigan, continues to supply BARC solutions including UV-113 and AR26N for advanced node lithography. The integration of Dow's electronic materials portfolio into DuPont's broader industrial electronics framework has implications for global sales reach, technical support infrastructure, and cross-portfolio bundling strategies. The report evaluates how this corporate restructuring affects competitive positioning within the BARC segment.
Tokyo Ohka Kogyo (TOK), based in Kawaguchi, Japan, manufactures BARC products including the NFC series for i-line, KrF, and ArF immersion lithography applications. In June 2025, TOK announced a capacity expansion at its Kawasaki plant to increase production of BARC resins, explicitly targeting demand associated with 2nm node manufacturing. This capital deployment decision reflects a forward commitment to node-specific volume growth and provides a tangible indicator of near-term supply-side dynamics.
Shin-Etsu Chemical, also headquartered in Tokyo, supplies BARC materials such as SEESOL for deep UV lithography in semiconductor fabrication facilities. In March 2025, Shin-Etsu achieved a significant certification milestone that strengthens its qualification position with major foundry and memory customers. The report contextualizes how certification events translate into revenue recognition timelines and competitive displacement opportunities within tightly managed customer supply chains.
Nissan Chemical Corporation, based in Tokyo, offers BARC products including the NFC-180 and VPC series tailored for 193nm and EUV lithography processes. The company's dual focus on established 193nm applications and next-generation EUV readiness positions it to capture demand across multiple technology transitions. AZ Electronic Materials, now part of Merck KGaA in Darmstadt, Germany, provides BARC formulations such as AZ BARLi for high-resolution lithography in microelectronics, leveraging the broader Merck electronics materials ecosystem for global distribution and technical service.
The study maps how these firms compete across product performance characteristics, regional service coverage, and node-specific qualification portfolios. By analyzing recent developments including product launches, capacity decisions, and certification achievements, the report equips readers with a current competitive intelligence baseline against which to benchmark internal strategies and partnership considerations.
Segmentation Architecture and Strategic Implications
A core strength of the report lies in its structured segmentation framework, which divides the market along three analytical dimensions: geography, material type, and lithography technology. Rather than presenting static allocation percentages, the analysis emphasizes the strategic logic underlying each segmentation axis and how shifts within these categories affect procurement planning, capacity siting, and technology investment decisions.
The regional segmentation examines how demand distribution varies across Asia Pacific, North America, Europe, and the Rest of the World. Given the concentration of advanced logic and memory fabrication in Asia Pacific, this region commands the largest share of market activity, but the report goes further to analyze how localization requirements, export control considerations, and transportation cost structures influence regional procurement strategies. The North American and European segments are evaluated through the lens of domestic semiconductor incentives, specialty chemical manufacturing footprints, and regulatory environments that shape material sourcing decisions.
The type segmentation distinguishes between Organic BARC and Inorganic BARC materials, each serving distinct application profiles and performance requirements. Organic formulations typically offer advantages in planarization and process compatibility for certain lithography workflows, while inorganic alternatives provide different reflectivity control characteristics and thermal stability profiles. The report explores how device makers select between these material classes based on node requirements, process integration constraints, and cost-performance trade-offs.
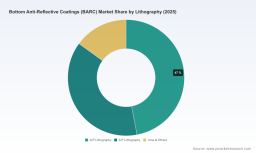
The lithography segmentation breaks down demand across ArF lithography, KrF lithography, and i-line and other legacy processes. As the industry migrates toward shorter wavelengths and higher resolution requirements, the relative weighting of these categories shifts, with implications for supplier product roadmaps and customer qualification priorities. The report details how this transition affects volume allocation, pricing dynamics, and the pace at which legacy process demand is absorbed or restructured.
Importantly, the full segmentation data, including precise regional revenue figures, type-level breakdowns, and lithography-specific allocations, is preserved within the complete research deliverable. This deliberate structure allows executive readers to absorb the strategic narrative here while reserving precise quantitative allocation data for internal planning sessions where granular figures directly inform budget models and procurement forecasts.
Market Dynamics: Supply Chain, Regulatory, and Trade Environment
Beyond structural growth and competitive positioning, the report delivers an integrated assessment of the operational dynamics that affect BARC market performance throughout the forecast period. These dynamics are not peripheral considerations; they directly influence cost structures, lead times, formulation viability, and regional market access.
On the raw material front, resin monomers such as methacrylic acid derivatives experienced an approximate 8 percent year-over-year price increase due to supply chain constraints, as documented in chemical pricing intelligence from early 2026. This input cost pressure affects formulation economics and may influence supplier pricing strategies, customer negotiation leverage, and the pace at which alternative material pathways are evaluated. The report examines how these cost dynamics propagate through the value chain and where mitigation strategies are most effective.
Regulatory developments introduce additional complexity. Under REACH Annex XVII, restrictions on certain aromatic solvents used in BARC formulations require reformulation for sales within the European Union. This regulatory requirement affects product development timelines, compliance costs, and the competitive positioning of suppliers with different reformulation capabilities. The report assesses how these constraints shape the European market landscape and influence global product platform decisions by multinational chemical manufacturers.
Trade policy developments further alter the operating environment. The US International Trade Commission imposed a 25 percent tariff on BARC imports originating from China under Section 301, effective following the post-2025 review cycle. This tariff structure affects import-dependent procurement strategies, sourcing diversification efforts, and the relative cost competitiveness of domestically produced versus imported materials within the North American market. The analysis explores how these measures interact with broader semiconductor supply chain resilience initiatives.
Transportation cost pressures add another layer of operational consideration. Shipping surcharges of approximately USD 0.15 per kilogram applied to chemical freight movements from Asia to Europe due to Red Sea disruptions, as reflected in late 2025 shipping indices. While such surcharges may fluctuate, they underscore the vulnerability of long-haul chemical logistics to geopolitical and operational disruptions, reinforcing the strategic value of regional inventory positioning and multi-sourced supply networks.
Report Scope and Practical Utility for Decision-Makers
PW Consulting's Worldwide Bottom Anti-Reflective Coatings Market study is structured to serve as a working reference for strategic planning rather than a passive overview. The deliverable includes comprehensive market sizing across historical and forecast periods, segmentation analysis that clarifies demand distribution logic, competitive profiling that connects corporate strategy to market performance, and an integrated assessment of the supply chain, regulatory, and trade factors that shape operational outcomes.
The report is designed for use by senior leadership teams in specialty chemical manufacturing, semiconductor fabrication, lithography equipment supply, and related investment contexts. It supports decisions related to capacity investment timing, product portfolio prioritization, geographic market focus, supplier selection criteria, and risk mitigation planning. By combining quantitative market trajectory with qualitative analysis of competitive moves and external dynamics, the study enables readers to construct internally consistent strategic plans grounded in current market reality.
The complete research package, including precise segmentation figures, company-level market share estimates, regional revenue breakdowns, and detailed forecast tables by type and lithography category, is available through the full report access portal. This structure ensures that executive summaries and strategic narratives can be evaluated broadly while reserving the precise quantitative intelligence that directly feeds budget models, procurement forecasts, and investment committee presentations for the intended decision-making audience.
Anti Reflective Glass Market
Conclusion: Aligning Strategy with Market Trajectory
The BARC market stands at the intersection of semiconductor technology advancement, specialty chemical innovation, and an evolving operational environment shaped by regulatory requirements and trade policy shifts. The projected growth from USD 962.0 million in 2025 to approximately USD 1.52 billion by 2032, at a 6.72 percent CAGR, reflects genuine demand expansion driven by lithography roadmap progression and fabrication intensity. However, capturing value within this trajectory requires more than awareness of the headline numbers.
Success in the 2026 decision environment demands clear understanding of how competitive concentration shapes supplier relationships, how segmentation dynamics influence procurement and capacity strategy, and how raw material costs, regulatory constraints, and trade measures affect the economics of market participation. PW Consulting's study provides the analytical foundation for these determinations, offering a structured and current intelligence base that supports informed strategic action. For organizations seeking to align their 2026 planning with the realities of a growing but structurally complex market, the full research deliverable supplies the depth required to move from strategic awareness to executable planning.
For detailed analysis of this topic, please visit the official page: Worldwide Bottom Anti-Reflective Coatings (BARC) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com