

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Solenoid Reversing Valve Market Hits $962.46M in 2025, Poised for $1.38B by 2032

Strategic Imperatives in the Global Solenoid Reversing Valve Market: A 2026 Outlook
The global solenoid reversing valve industry stands at a critical inflection point. Driven by an accelerating energy transition, tightening refrigerant regulations, and sustained HVAC modernization programs across both developed and emerging economies, demand for precision switching components is evolving faster than traditional procurement cycles can accommodate. For engineering leaders, procurement directors, and corporate strategists navigating 2026 decision-making windows, understanding the trajectory of this sector is no longer optional. It is a foundational requirement for capital allocation, supply chain resilience, and product roadmap alignment.
Our newly released Worldwide Solenoid Reversing Valve Market study delivers a comprehensive, data-grounded examination of the sector from 2020 through 2032. Built for practitioners who require actionable intelligence rather than high-level projections, the report maps historical performance, forecasts demand under multiple adoption scenarios, and dissects the competitive dynamics shaping procurement leverage and innovation pipelines. Below, we outline the strategic architecture of the research and highlight the key themes that will define market participation in the coming years.
Historical Baseline and Forward Trajectory
The solenoid reversing valve market has demonstrated consistent expansion over the past half-decade, anchored by structural demand from climate control equipment and industrial fluid power applications. Between 2020 and 2025, global revenue climbed from approximately 745.2 million USD to 962.46 million USD, reflecting a compound annual growth rate that underscores the sector's resilience against supply chain disruptions and raw material volatility. The forecast horizon extends this trajectory through 2032, with market sizing indicating continued upward momentum as heat pump penetration accelerates and commercial refrigeration networks undergo refrigerant transition upgrades.
The projected CAGR of 5.24 percent across the 2026 to 2032 forecast window reflects a market that is growing steadily rather than explosively, a profile that rewards disciplined portfolio management and long-term supplier relationships over speculative inventory positioning. Forecasts anticipate market valuation crossing the 1.3 billion USD threshold by the end of the decade, with intermediate milestones highlighting the pacing of adoption across HVAC retrofits, new residential builds, and industrial automation deployments. These figures provide a baseline for scenario planning, enabling organizations to calibrate production capacity, inventory buffers, and regional distribution strategies against a quantifiable demand curve.
Importantly, the macro trajectory does not obscure near-term friction. Fluctuations in base material costs, particularly steel, have introduced variability into component manufacturing economics. Spot pricing for hot rolled coil in the United States has moved within a defined band over the past year, stabilizing amid trade policy uncertainty before climbing again in early 2026 as mill pricing actions and industrial demand intersect. These input cost dynamics influence valve body fabrication, housing production, and downstream margin structures, making material price intelligence a necessary complement to demand forecasting in operational planning.
Structural Demand Drivers and Technology Shifts
The thematic core of the market's expansion rests on the convergence of energy efficiency mandates and refrigerant compliance requirements. Heat pump systems have emerged as a primary growth vector, with adoption rates climbing across residential and light commercial segments as building codes tighten and electrification incentives take effect. This shift places direct pressure on four-way and three-way reversing valve design specifications, particularly regarding compatibility with low-GWP refrigerants and natural refrigerant blends. Manufacturers that can deliver reliable cycle reversal performance while meeting maximum operating pressure thresholds and UL recognition standards are positioned to capture premium positioning in specification-driven procurement environments.
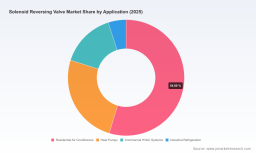
Residential air conditioning and heat pump installations continue to represent the largest application concentration, but commercial HVAC systems and industrial refrigeration are generating meaningful incremental volume as facility operators modernize aging equipment and align with decarbonization targets. The solenoid reversing valve's role in directional control for refrigerant circuits, pneumatic automation lines, and hydraulic machinery means the market is inherently cross-sectoral. Yet the growth composition is uneven, with certain applications benefiting from faster replacement cycles and others facing longer capital approval timelines. Understanding where volume concentration sits, and how that concentration shifts as regulatory deadlines approach, is essential for prioritizing sales coverage, service support, and engineering customization resources.
Solenoid Valves Market
Technology evolution is also reshaping competitive expectations. Stainless steel configurations, advanced PTFE and metal slide mechanisms, and intelligent control integration are becoming differentiators rather than optional enhancements. The transition toward next-generation valve architectures is not merely a product line extension; it reflects a broader industry push toward durability in harsh operating environments, reduced leakage profiles, and compatibility with the refrigerant chemistry that will dominate the next decade of HVAC and refrigeration deployment. Organizations that map their development pipelines against these specification trends will be better equipped to negotiate with specifiers and capture design-in opportunities early in the equipment development cycle.
Competitive Architecture and Strategic Positioning
The market exhibits a concentrated competitive landscape, with a small group of established players commanding a substantial share of total revenue. High concentration levels indicate that scale advantages, brand recognition in specification channels, and entrenched service networks create meaningful barriers for new entrants. At the same time, the composition of leadership varies by application domain, with certain organizations dominating HVAC and heat pump reversing solutions while others maintain strong positions in industrial hydraulics, pneumatics, and mobile fluid power.
Sanhua Holding Group has solidified its reputation as a leading global supplier of four-way reversing valves for HVAC and heat pump applications, offering both the established SHF series and next-generation SHF-G stainless steel models engineered for compatibility with common HFC/HCFC refrigerants and natural refrigerant alternatives. The company's recent product introductions and trade show participation underscore a strategy centered on expanding material ranges, improving performance in heat pump duty cycles, and aligning with intelligent control ecosystems. This approach reflects the broader competitive reality that reversing valve suppliers must now engage with system-level integration requirements, not just component-level specifications.
Danfoss continues to offer a broad portfolio of solenoid valves and reversing solutions for refrigeration and air conditioning, with EVR solenoid valves and four-way reversing configurations that address both commercial and industrial cooling architectures. Parker Hannifin maintains a strong footprint in hydraulic and pneumatic solenoid reversing valves, including directional control products for industrial and mobile applications, while Bosch Rexroth supplies hydraulic solenoid reversing valves and directional control platforms such as the 4WE series for industrial machinery. Robertshaw and Wilspec focus more narrowly on heat pump reversing valves for residential and commercial HVAC systems, with Robertshaw emphasizing PTFE and metal slide mechanisms and Wilspec building a reputation in geothermal and seasonal switching applications where durable configurations are critical.
Regional and application-specific specialists further shape the landscape. DunAn produces reversing valves and electromagnetic four-way solutions for HVAC and refrigeration networks. SMC Corporation delivers pneumatic solenoid valves and directional control products that function as reversing components in automation environments. ASCO, operating under Emerson, provides solenoid valves and control solutions with directional configurations applicable to fluid power reversing setups. Shandong Yikaide Hydraulic Co., Ltd. concentrates on hydraulic solenoid reversing valves for industrial hydraulic systems. The diversity of this roster highlights a market in which competitive advantage is frequently derived from application specialization, regional distribution strength, and the ability to meet distinct certification and pressure-rating requirements across geographies.
Recent corporate activity reinforces the pace of innovation. In late 2025, Sanhua introduced its next-generation SHF-G series four-way reversing valves with an expanded stainless steel range designed to improve performance in heat pump systems. In early 2026, the company showcased intelligent control technologies, including reversing valve solutions, at a major industry exposition. These moves illustrate how leading suppliers are synchronizing product upgrades with system-level intelligence, a pattern that procurement teams should monitor as they evaluate supplier roadmaps and total cost of ownership assumptions.
Regulatory, Material, and Operational Dynamics
Market performance cannot be separated from the compliance and input cost environment. Reversing valves deployed in heat pump and HVAC applications must satisfy UL recognition and adhere to maximum operating pressure ratings, such as the 650 psig threshold commonly referenced for compatibility with HFC refrigerants in global markets. These requirements influence material selection, manufacturing tolerances, and validation testing cycles. As refrigerant transitions accelerate, suppliers that can demonstrate compliance with evolving pressure and fluid compatibility specifications while maintaining manufacturing throughput will hold a distinct advantage in specification capture and aftermarket support.
On the input side, steel pricing remains a central variable for valve body and component production. Recent price movements have cycled through a stabilization phase before resuming an upward trajectory, driven by mill pricing adjustments and demand from construction and industrial sectors that overlap with solenoid valve manufacturing supply chains. Organizations with diversified sourcing strategies, forward procurement contracts, or design flexibility to accommodate alternate material grades are better positioned to absorb cost volatility without eroding margin expectations. For downstream equipment manufacturers, this underscores the value of supplier partnerships that provide transparency on material pass-through mechanisms and lead-time reliability.
Worldwide Solenoid Reversing Valve Market
Beyond pricing and compliance, the broader market dynamic is being shaped by the increasing adoption of heat pump systems for energy-efficient heating and cooling. This trend directly drives demand for reliable four-way solenoid reversing valves that can operate reliably with low-GWP and natural refrigerants. As building owners, OEMs, and integrators align procurement with sustainability targets, the reversing valve is transitioning from a commodity-adjacent component to a specification-critical element whose performance characteristics influence system efficiency claims, warranty exposure, and end-user satisfaction. Strategic buyers are responding by tightening qualification criteria, expanding field reliability benchmarks, and placing greater weight on supplier track records in refrigerant transition scenarios.
What the Full Study Delivers
The Worldwide Solenoid Reversing Valve Market research is structured to translate macro trends into operational guidance. Rather than offering a single aggregate figure, the report decomposes market size across product configurations, application categories, and regional demand centers, allowing readers to identify where volume concentration, growth pacing, and competitive intensity intersect. The segmentation analysis clarifies how different valve architectures and end-use environments contribute to total market value, enabling more precise capacity planning, channel strategy, and product mix decisions.
The study also maps the competitive environment in detail, profiling the leading organizations that define pricing norms, specification standards, and innovation velocity. Company-level assessments cover product portfolio scope, application focus, geographic presence, and recent strategic actions, providing a practical reference for supplier evaluation, partnership screening, and competitive benchmarking. Beyond company profiles, the report integrates industry context spanning raw material conditions, regulatory specifications, and macro adoption trends, ensuring that readers can interpret market size and share data within the operational realities that shape procurement and production decisions.
Forecast content extends across a multi-year horizon, giving strategists a structured basis for scenario planning. Historical data establishes the baseline trajectory, while forward projections support demand modeling for new product introductions, regional expansion initiatives, and inventory strategy. The research is designed to serve cross-functional audiences, from R&D and product management teams evaluating design-in opportunities to supply chain leaders stress-testing supplier resilience and commercial teams calibrating market entry or share-gain plans.
Strategic Implications for 2026 Decision-Makers
For organizations operating in or adjacent to the solenoid reversing valve market, the 2026 landscape rewards precision over generalization. The convergence of heat pump adoption, refrigerant transition requirements, and concentrated supplier dynamics means that procurement strategy, product specification, and supplier selection must be informed by granular market intelligence rather than broad industry narratives. Companies that understand how demand is distributed across applications and regions, which suppliers are advancing material and control innovations, and how compliance and input cost pressures affect total cost of ownership will be better positioned to protect margins and capture growth.
The full report provides the depth required to translate these themes into concrete plans. It offers the segmentation breakdowns, competitive profiles, and forward forecasts necessary to support capital allocation, sourcing strategy, and technology roadmap decisions with confidence. For executives and analysts preparing for the remainder of the decade, the study serves as both a diagnostic baseline and a planning framework, connecting historical performance to forward demand in a manner that supports disciplined, evidence-based strategy.
Access the complete Worldwide Solenoid Reversing Valve Market research to obtain the full set of market size estimates, segmentation splits, competitive assessments, and forward projections that underpin the analysis presented here. The detailed intelligence contained in the report is intended to support high-stakes decision-making across product development, procurement, sales strategy, and regional expansion planning throughout 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Worldwide Solenoid Reversing Valve Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com