

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Packaging Outsert and Inserts Market to Reach $6.95B by 2032 Amid 6.0% CAGR

Strategic Intelligence for 2026: Navigating the Packaging Outsert and Inserts Market
In the rapidly evolving landscape of pharmaceutical and healthcare packaging, the packaging outsert and inserts market stands as a critical nexus of regulatory compliance, patient safety, and supply chain efficiency. As we move through 2026, industry leaders face a complex matrix of challenges ranging from raw material volatility to stringent new environmental regulations. Understanding the trajectory of this sector is not merely an exercise in market sizing; it is a strategic imperative for operations, procurement, and long-term planning. This article serves as a precursor to our comprehensive market research report, designed to equip decision-makers with the high-level insights necessary to navigate the forecast period through 2032.
The market has demonstrated remarkable resilience and growth over the past half-decade. Historical data from 2020 through 2025 indicates a steady upward trajectory, reflecting the expanding complexity of pharmaceutical products and the non-negotiable requirement for clear patient information. Looking ahead, the forecast period from 2026 to 2032 projects continued expansion, driven by the increasing volume of healthcare products requiring secondary packaging documentation. This growth is not linear; it is punctuated by technological advancements, regulatory shifts, and changing consumption patterns across key global regions. Our latest study dissect this evolution, offering a granular view of where value is being created and where risks are accumulating.
Macro Market Dynamics and Performance Trajectory
Analyzing the historical performance provides a baseline for understanding the scale of opportunity. Between 2020 and 2025, the market capitalized on heightened healthcare demands and entrenched regulatory frameworks requiring detailed patient information leaflets. The transition from historical years into the current forecast period reveals a market that is consolidating its position while adapting to new constraints. The projected compound annual growth rate indicates a steady expansion pace, suggesting that demand for outsert and inserts remains inelastic relative to price fluctuations in the short term, owing to its critical role in drug safety and compliance.
However, growth does not occur in a vacuum. The market size at the base year of 2025 established a significant valuation, setting the stage for the forecast period. As we project forward to 2032, the market is expected to reach new valuation heights. This growth is influenced by several factors, including the proliferation of specialized medical treatments that require detailed Instructions for Use (IFUs) and the global push for multilingual packaging to support international distribution. Yet, this expansion is tempered by cost pressures and regulatory tightening, creating a divergent environment where efficiency and compliance are the primary differentiators for market participants.
Segmentation Insights and Material Constraints
The market is structurally defined by its segmentation across type, application, and geography. By type, the division between outsert and inserts represents distinct manufacturing processes and logistical considerations. Outserts, often utilized for primary safety information or outer carton labeling, and inserts, which provide detailed internal documentation, serve complementary roles in the pharmaceutical supply chain. The balance between these two segments influences production capacity requirements and inventory management strategies for manufacturers. Understanding the relative demand drivers for each type is crucial for optimizing production lines and managing supply chain resilience.
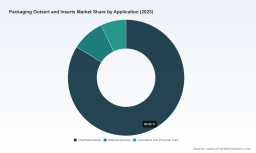
In terms of application, the pharmaceutical sector dominates the landscape, reflecting the stringent regulatory requirements associated with drug distribution. Medical devices and cosmetics also constitute significant portions of the market, each with unique compliance profiles. The pharmaceutical application segment drives the majority of volume, necessitating high-precision folding, serialization, and adherence to FDA and international standards. Meanwhile, the medical device and cosmetics sectors introduce additional complexity regarding material safety and user interface design, requiring versatile manufacturing capabilities from suppliers.
Geographically, the market distributes demand across major regions including North America, Europe, Asia Pacific, and the Rest of World. Each region presents distinct regulatory environments and supply chain dynamics. North America and Europe remain mature markets with high compliance standards, while Asia Pacific represents a growing hub for manufacturing and consumption. The distribution of market share across these regions underscores the importance of localized compliance strategies and supply chain agility. A procurement strategy focused solely on one region may expose companies to volatility elsewhere, making a diversified supply base increasingly valuable.
Regulatory Pressure and Sustainability Trends
The regulatory environment in 2026 is undergoing a significant transformation, particularly concerning sustainability and end-of-life management. In the United States, the landscape of Extended Producer Responsibility (EPR) laws is expanding rapidly. As of late 2025, several states including Maine, Oregon, Colorado, California, Minnesota, Maryland, and Washington have enacted comprehensive EPR laws for packaging and paper products. These laws require producers to fund the end-of-life management of their packaging, shifting the cost burden and incentivizing more sustainable design choices. Furthermore, in 2026, additional states such as New Hampshire, Wisconsin, and Georgia have introduced or advanced similar bills, signaling a nationwide trend toward greater producer accountability for paper and packaging materials.
Packaging Outsert and Inserts Market
Across the Atlantic, the European Union's Packaging and Packaging Waste Regulation (PPWR), effective from August 2026, imposes rigorous requirements on packaging design. This regulation mandates recyclable packaging design, minimizes harmful substances, and sets recycled content targets for non-contact plastic packaging starting in 2030. For the outsert and inserts market, which relies heavily on paperboard and specialized folding cartons, these regulations necessitate a reevaluation of material sourcing and design protocols. Companies must now consider not only the dimensional compliance of their inserts but also their recyclability and environmental footprint. This regulatory shift is not merely a compliance exercise; it is a strategic signal that sustainability will be a key differentiator in vendor selection and market access.
Parallel to regulatory changes, raw material costs remain a persistent concern. The U.S. Producer Price Index for folding paperboard boxes and packaging components has shown fluctuation, reflecting broader inflationary pressures in the supply chain. Additionally, global wood pulp import prices have established a baseline that influences the cost structure of paper-based inserts. Packaging remains a leading application for wood pulp, meaning that fluctuations in pulp markets directly impact the cost of goods for pharmaceutical inserts. Manufacturers and buyers alike must monitor these indices closely, as margins in packaging can be thin and sensitive to material cost spikes. Strategic procurement contracts and material diversification are becoming essential tools for managing this volatility.
Competitive Landscape and Manufacturer Innovation
The competitive landscape is characterized by a market structure that is fragmented yet featuring key players with significant specialized capabilities. The concentration ratio among the top competitors remains relatively dispersed, indicating that while large players exist, there is substantial room for specialized manufacturers to compete on quality, compliance, and service. Leading companies in this space are not just competing on price; they are differentiating through technological innovation, capacity expansion, and adherence to rigorous quality standards such as cGMP and ISO certifications.
Worldwide Aircraft Galley Inserts Market
Several core companies exemplify the strategic depth of the market. Winpak, based in Norwood, New Jersey, specializes in precision-manufactured product inserts, outserts, and MedGuides, utilizing high-precision equipment to meet strict FDA dimensional requirements. Their focus on converting large-format printed sheets into compact formats suitable for automated application highlights the technical precision required in this sector. Similarly, CCL Healthcare, headquartered in Etobicoke, Canada, offers customizable folded patient leaflet inserts and outserts with capabilities extending to hundreds of panels and pages, produced under controlled facilities with a focus on multilingual and regulatory compliance.
Nosco, with multiple facilities across the USA, emphasizes stitched booklets and intricately folded inserts using advanced folding equipment, catering to pharmaceutical, natural health, and CPG markets with a strong emphasis on consistency. Colbert Packaging Corp, located in Kenosha, Wisconsin, manufactures custom paperboard folding cartons and high-capacity pharmaceutical inserts using patented folding procedures. Graphic Packaging International provides leaflets and packaging inserts tailored from specific paper grades, including mandatory patient alert cards for medication safety. These companies illustrate the diversity of technical capabilities available to support complex healthcare packaging needs.
Recent developments highlight the dynamic nature of this competitive field. Colbert Packaging Corporation expanded its capacity in early 2026 by adding a new blanking die cutter to its Kenosha facility, aimed at boosting production efficiency for paperboard packaging including inserts. This move signals an anticipation of continued demand and a commitment to maintaining throughput capabilities. In Europe, Faller Packaging pioneered digitally-printed pharmaceutical leaflets with the installation of a 4th SCREEN TruePress Jet in 2025, demonstrating a push toward digital printing technologies to meet high standards in leaflet production and potentially offering greater flexibility in short runs or customized information. Additionally, Winpak introduced Medform DT in late 2025 as part of advancements in pharmaceutical packaging components, showcasing ongoing product innovation in inserts and outserts.
Other notable players include RLG Healthcare, which produces package inserts and IFUs with precision printing and folding down to very small dimensions for automated equipment compliance; Tursso Companies, offering design-to-manufacture capabilities with strict quality protocols under ISO and GMP standards; and Flottman Company, delivering precision folding services with advanced serialization for regulatory-compliant integration. The presence of these diverse capabilities suggests that buyers can find specialized partners for specific needs, but the fragmentation also means that due diligence on technical capacity and regulatory track record is essential.
Strategic Value of Comprehensive Market Research
For enterprises operating in 2026, the decision to invest in deep market intelligence is a strategic one. The Packaging Outsert and Inserts Market report provides more than just historical data; it offers a structured framework for understanding the interplay between regulatory shifts, material costs, and competitive dynamics. The report details every segmentation slice, from regional breakdowns to application-specific trends, allowing stakeholders to identify where their specific products fit within the broader value chain. This granularity is essential for risk assessment and opportunity identification.
Furthermore, the report covers recent developments and company profiles extensively. By analyzing the capacity expansions, product introductions, and technological adoptions of key players, the research helps enterprises benchmark their own strategies against industry leaders. Understanding who is expanding capacity, who is moving toward digital printing, and who is innovating in material formats can inform supply chain partnerships and competitive positioning. The inclusion of regulatory context, such as the specific states enacting EPR laws and the timelines for EU PPWR compliance, provides actionable intelligence for compliance planning and sustainability strategy development.
Raw material insights are also integral to the analysis. With fluctuations in paperboard indices and wood pulp prices, access to detailed data on material flows and cost drivers enables more accurate budgeting and procurement planning. The report contextualizes these material trends within the broader market forecast, helping users anticipate cost pressures before they impact margins. Additionally, the analysis of market concentration helps buyers understand the bargaining dynamics in the supplier market, whether they are negotiating against a consolidated few or a broader field of competitors.
In an era where supply chain resilience and regulatory compliance are paramount, the Packaging Outsert and Inserts Market report serves as a vital tool for strategic planning. It equips operations managers, procurement leaders, and strategists with the foresight needed to navigate the complexities of 2026 and beyond. The insights contained within move beyond the surface-level headlines to provide the depth required for informed decision-making.
To access the complete suite of data, including exact regional valuations, detailed segmentation revenues, and full company profiles, we invite you to explore the full report. This intelligence is designed to be the foundation for your strategic decisions in the coming years, ensuring that your organization remains agile, compliant, and competitive in a growing and evolving market.
For detailed analysis of this topic, please visit the official page: Packaging Outsert and Inserts Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com