

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: 2025 Revenue Hits $24.16B with 4.52% CAGR Outlook to 2032 in Pigment-grade TiO2

Several Forces Are Reshaping the Global Pigment-grade Titanium Dioxide Market in 2026 and Beyond
Why This Comprehensive Market Research Matters for Strategic Decision Making
Our latest Worldwide Pigment-grade Titanium Dioxide Market report is designed for executives, procurement leaders, and investment strategists who need more than a static snapshot of today's prices. Built around a rigorous base year of 2025 and a detailed historical reconstruction spanning 2020 through 2025, this study places your decisions inside a forward-looking framework that extends through 2032. Rather than treating titanium dioxide as a single, undifferentiated commodity, the analysis maps the interplay of process technology, crystal structure, application demand, regional dynamics, and competitive behavior that will govern value creation over the next seven years. The overarching objective is simple: give leadership teams a tested vantage point for scenario planning, capacity evaluation, supply chain redesign, and portfolio prioritization in a market where structural shifts are happening faster than the traditional planning cycle.
The core revenue trajectory reflects a market that has already absorbed a full post-pandemic normalization cycle and is now building on a more stable footing. Historical sizing moved from roughly 19,342 million USD in 2020 to an estimated 24,158 million USD in 2025, with the path between those endpoints capturing both cyclical volatility and the gradual re-rating of demand fundamentals. Looking ahead, the analysis projects a sustained expansion that carries the market from approximately 25,676 million USD in 2026 toward more than 32,914 million USD by 2032. This pathway is supported by a forecast compound annual growth rate of 4.52 percent, a pace that is neither speculative nor conservative, but grounded in the cumulative effect of megatrend demand drivers, gradual capacity replumbing, and regional rebalances across the value chain.
Titanium Dioxide (TiO2) Market
What separates this report from generic market summaries is the way it turns those headline figures into decision-grade intelligence. The document does not ask you to accept an aggregate number and then guess the implications. Instead, it reconstructs how that aggregate is assembled by process routes, by crystal forms, by end-use applications, and by geography, then overlays the operational and regulatory pressures that will make or break individual segments. For strategists, this structure converts a broad top-line outlook into an actionable map of where margin, volume, and risk are likely to concentrate in the coming years.
Inside the Analysis: What Leaders Will Find in This Report
The report is organized around the practical questions that surface repeatedly in boardrooms, operating reviews, and procurement negotiations. For each commercial dimension, the analysis moves beyond descriptive market sizing to illuminate the strategic logic behind segment behavior, the levers that influence pricing power, and the operational constraints that shape future capacity deployment.
At the process level, the study separates sulfate and chloride routes as distinct strategic arenas rather than interchangeable production methods. Because these routes differ in feedstock flexibility, energy intensity, environmental footprint, and product-grade flexibility, understanding their relative share is essential for assessing supplier resilience, regional cost structures, and exposure to regulatory shifts. The chloride vs sulfate comparison is used throughout the report to frame questions about long-run competitiveness, plant economics, and the capacity decisions that will determine who can sustain scale without eroding margins.
Crystal Form Dynamics and the Rutile Dominance
The crystal structure dimension adds another layer of commercial granularity. The analysis tracks the dominance of rutile titanium dioxide alongside the specialized role of anatase titanium dioxide, showing how performance requirements, application tolerances, and end-user specifications drive material choice. Rather than treating crystal form as a technical footnote, the report evaluates how it shapes pricing tiers, customer segmentation, and the competitive positioning of producers who specialize in high-performance or niche grades versus those who compete primarily on volume and cost efficiency.
Application Fragmentation and Demand Stickiness
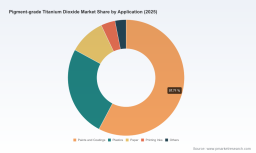
On the demand side, the report dissects the application landscape into the segments that matter most to commercial strategy, with special attention to how growth durability differs by use case. Paints and coatings represent the largest demand concentration and therefore the most important arena for volume and pricing dynamics. Plastics form a second major pillar, where pigment-grade titanium dioxide is evaluated not just as a colorant but as part of a broader formulation ecosystem influenced by automotive, consumer goods, and industrial specifications. Paper, printing inks, and a range of other applications are examined for their contribution to demand resilience, their sensitivity to substitution, and their relevance as either steady cash generators or tactical market entry points. For each application group, the analysis identifies the factors that can accelerate demand, compress it, or redirect it toward higher-value grades, allowing leaders to see where end-market durability supports capacity investment and where exposure is more cyclical.
Geographical Rebalancing and Regional Competitive Logic
The regional dimension is treated with similar commercial precision. The study maps the five major geographical arenas and examines how production concentration, import dependence, logistics costs, and local regulatory pressures affect supply security and competitive advantage. Because pigment-grade titanium dioxide is a globally traded material with meaningful regional cost and policy differentials, geographic positioning is not a background variable; it is a core determinant of margin, sourcing flexibility, and strategic bargaining power. The report uses these regional comparisons to help executives evaluate where local demand growth, export-oriented capacity, and trade-policy exposure will create the most consequential opportunities and vulnerabilities.
Throughout all of these segments, the report deliberately avoids asking readers to rely on isolated numbers taken out of context. Instead, it integrates the sizing framework with qualitative and operational intelligence: supply tightness from upstream ore markets, shifts in energy cost structures, compliance pressure from environmental regulation, and the timing of major corporate actions that alter competitive balance. That integration is what makes the forecast useful. It enables leaders to test how a change in raw material pricing, a new tariff regime, or a closure of older capacity would propagate through different segments before those changes become fully priced into the market.
The Competitive Field: Who Is Positioning Where and Why It Matters
Competitive strategy in this market depends on understanding how leading manufacturers differentiate themselves across technology, scale, geography, and application focus. The report profiles a field of major producers whose strategic choices are reshaping the market's structure and pricing behavior, and it uses those profiles to illuminate the kinds of moves that will matter most in 2026 and the years that follow.
Worldwide Pigment-grade Titanium Dioxide Market
Among global incumbents, The Chemours Company continues to anchor its strategy around the Ti-Pure brand for paints, coatings, plastics, and paper applications. Its recent launch of Ti-Pure R706, an optimized grade for water-based coatings with enhanced dispersibility, illustrates the broader industry shift toward formulation performance and regulatory-aware product development rather than volume expansion alone. Tronox Holdings extends its competitive reach through chloride-based production and a major expansion completed at its Botswana pigment-grade plant, adding significant annual capacity and underscoring the strategic importance of scale in key supply regions. Venator Materials PLC competes through specialty positioning with its TiONA and TiKON brands, targeting high-performance coatings and plastics where specification quality and customer integration can support differentiation. Kronos Worldwide remains a well-established supplier for architectural coatings, industrial finishes, and plastics, reinforcing the ongoing importance of brand trust and application consistency in a fragmented buyer environment.
The Chinese producers represent a different but equally important strategic logic. Lomon Billions Group operates at exceptional scale, with its R-996 and LM series extending into global paints and coatings markets, and its 2024 price increase announcement reflected the pressure of rising energy and raw material costs on global pricing behavior. CNNC Hua Yuan represents the high-end chloride-oriented export strategy, particularly relevant for coatings and plastics demand, while also highlighting the operational volatility that still affects parts of the Chinese supply base. Pangang Group Panzhihua Titanium shows the continued relevance of state-owned sulfate-process capacity for domestic and international paint and paper markets, a reminder that traditional routes still play a major role where cost, volume, and regional application needs align.
In Asia, the Japanese specialists Ishihara Sangyo Kaisha and Tayca Corporation illustrate a high-purity, specification-driven approach, with products like the CR-60 series and rutile grades such as R-550 serving automotive coatings, inks, and high-end plastics. In Europe, Precheza a.s. reinforces the regional specialty narrative through its PURENOL and PRETIOSA product lines for decorative paints and industrial coatings, where compliance sophistication and customer specificity matter as much as scale.
Together, these competitive profiles show a market where leadership is no longer defined solely by installed capacity. The analysis uses this competitive map to help readers identify which players are likely to defend margin through product architecture, which ones are pursuing regional capacity advantage, and where consolidation risk or disruption risk may emerge. Because the report keeps the focus on strategic posture rather than static rankings, it becomes a tool for benchmarking your own positioning against the moves that are actually shaping the next phase of the market.
Structural Realities Shaping 2026 Strategy
Any forward-looking strategy in pigment-grade titanium dioxide must account for the operational and policy forces that act as market accelerators or drags. The report integrates several of these structural realities as ongoing context for the forecast rather than as isolated news items, precisely because their effects are cumulative and often unevenly distributed across segments and regions.
Raw material conditions remain a central variable. Ilmenite ore prices averaged roughly 240 to 260 USD per metric ton in the fourth quarter of 2024, with a year-over-year increase of about 15 percent driven by supply tightness from Australia and South Africa. That kind of upstream pressure does not affect every producer equally, but it changes the cost floor for the industry and influences how aggressively capacity expansion can be justified. At the same time, electricity surcharges for titanium dioxide production in China rose by 10 to 15 percent in 2024 due to carbon emission controls, adding another layer of regional cost differentiation that strategists need to reflect in sourcing and capacity models.
Regulatory and policy developments matter just as much as cost trends. In China, the Ministry of Ecology and Environment enforced the elimination of 200,000 tons of backward sulfate-process titanium dioxide capacity by the end of 2024, a move that compresses older, less efficient supply and alters the competitive balance between process routes. In Europe, REACH compliance updates have introduced Annex XVII restrictions on nano forms for pigment-grade titanium dioxide imports, effective from 2024, which affects formulation design and market access strategies for producers serving the EU. In the United States, Section 301 tariffs on Chinese pigment-grade titanium dioxide imports remain at 25 percent as of 2025, with meaningful exposure across the supply base. That tariff environment changes sourcing logic, supplier diversification priorities, and the relative attractiveness of non-Chinese capacity for buyers who must manage landed cost and supply continuity together.
Operational volatility still punctuates an otherwise maturing market. The force majeure declaration by CNNC Hua Yuan in December 2023, related to winter production restrictions in China, is a useful reminder that even large-scale producers can face episodic constraints that ripple into availability and pricing. Similarly, Tronox's completion of its Botswana expansion in August 2024, adding 50,000 tons of annual capacity, demonstrates how targeted capacity additions can shift regional supply balances and influence competitive expectations. When these events are read alongside the broader market trajectory, they help explain why a forecast of steady growth does not imply a smooth path for every participant.
Using This Report to Strengthen Enterprise Decisions
The real value of this study lies in how it supports concrete decision-making across several functions. For procurement and supply chain leaders, the segmentation and regional analysis helps identify where sourcing diversification, contract structure, and supplier evaluation criteria should be adjusted in response to process mix, tariff exposure, and energy-driven cost shifts. For commercial and product strategy teams, the application and crystal-form analysis provides a basis for anticipating where demand will reward specification improvement versus where price competition will dominate. For corporate development and investment teams, the competitive profiles and recent developments offer a framework for evaluating acquisition targets, capacity partnerships, and market-entry strategies with a clearer sense of who is expanding, who is differentiating, and where structural constraints may limit return.
The report is designed to be used as a living reference point, not a one-time download. Its structure supports scenario testing, supplier benchmarking, and regional strategy comparison, allowing leadership teams to connect the aggregate market outlook to the operational realities that govern execution. By keeping the focus on decision-relevant integration rather than isolated data points, the analysis helps organizations prepare for a market environment in which growth is real, competition is intensifying, and the cost and policy landscape is changing fast enough to reward those who plan with precision.
Why the Full Intelligence Set Is Essential for 2026 Planning
A market of this scale and complexity cannot be managed effectively on the strength of a single headline number or a partial view of regional or application trends. The strategic picture only becomes actionable when the forecast is tied to the underlying segmentation logic, the competitive dynamics, and the structural pressures that determine how value is distributed across the value chain. The full version of the Worldwide Pigment-grade Titanium Dioxide Market report delivers that integrated picture with the level of operational detail required for serious planning. It provides the segment-level context, the company-level strategic positioning, and the policy-driven market dynamics that executives need to translate a 4.52 percent growth trajectory into practical choices about sourcing, investment, pricing, and market focus. For organizations that want to move from general market awareness to executable strategy, the complete analysis is the necessary next step.
For detailed analysis of this topic, please visit the official page: Worldwide Pigment-grade Titanium Dioxide Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com