

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Canine Mammary Tumor Treatment Market Hits $845.5M in 2025, 7.58% CAGR to 2032

Navigating the Future of Canine Mammary Tumor Treatment: Strategic Intelligence for 2026 and Beyond
The Imperative for Precision in Veterinary Oncology
The veterinary healthcare landscape is undergoing a profound transformation, driven by an increasing humanization of pets, rising disposable incomes, and an accelerating adoption of advanced therapeutic modalities. Within this evolving ecosystem, the management of canine mammary tumors represents a critical intersection of surgical standards, emerging targeted therapies, and comparative oncology research. For industry stakeholders, investors, and strategic decision-makers, understanding the trajectory of this market is no longer optional—it is a fundamental requirement for capitalizing on growth opportunities through 2032.
Our latest market intelligence report, Worldwide Canine Mammary Tumor Treatment Market, offers a comprehensive examination of the forces shaping this sector. This briefing serves as a strategic overview, synthesizing macro-level trends, competitive dynamics, and therapeutic shifts to equip leaders with the insights necessary to navigate the forecast period. The data underscores a robust expansion trajectory, reflecting both the maturation of established treatment pathways and the incremental integration of innovation into routine veterinary practice.
Market Trajectory and Historical Resilience
The global market for canine mammary tumor treatment has demonstrated consistent growth over the historical review period. Valued at approximately 590.25 million USD in 2020, the market has expanded steadily, reaching an estimated 845.5 million USD by 2025. This positive momentum reflects the sustained demand for effective interventions, the broadening acceptance of veterinary oncology as a specialized discipline, and the economic capacity of pet owners to pursue comprehensive care options.
Looking ahead, the forecast period from 2026 to 2032 projects continued expansion, with the market anticipated to surpass the 1.4 billion USD threshold by the end of the forecast window. The compound annual growth rate (CAGR) for this interval is estimated at 7.58, signaling a healthy, sustained upswing. This growth profile suggests that while the market is building upon a solid foundation of surgical and supportive care standards, there is significant headroom for value creation through therapeutic diversification and regional market development. Stakeholders evaluating entry points, investment allocations, or product pipeline prioritization will find this macro outlook essential for aligning long-term strategies with market realities.
Cancer Treatment Drugs Market
Therapeutic Modalities: Evolution Beyond the Surgical Standard
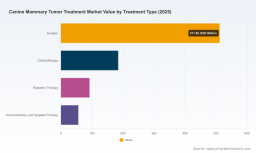
The treatment landscape for canine mammary tumors is anchored by well-established clinical protocols, yet it is increasingly characterized by a nuanced blending of modalities. Surgery remains the primary and gold-standard treatment, with the extent of resection dictated by tumor number, size, and staging. Adjuvant chemotherapy is typically reserved for advanced or high-risk malignant cases, ensuring that intervention is both targeted and clinically appropriate.
However, the strategic narrative is shifting as targeted and immunotherapy approaches gain traction in research and off-label applications. While no targeted small-molecule or biologic therapy has received full FDA approval specifically indicated for canine mammary tumors, the current environment relies heavily on the surgical standard supplemented by the off-label use of approved oncology drugs. This regulatory reality presents both a constraint and a catalyst. It limits the immediate rollout of designated therapies but simultaneously creates a fertile ground for innovation, comparative research, and the eventual expansion of labeled indications. Companies that can bridge the gap between off-label utilization and formal regulatory pathways are positioned to capture significant value as the market matures.
Cost structures also play a pivotal role in shaping adoption patterns. Surgical removal of a single mammary tumor in dogs typically ranges between 750 and 3,000 USD, depending on variables such as tumor size, location, dog weight, and clinic-specific factors. Additional tumors can add incremental costs, influencing treatment decisions and payer behavior. These economic realities underscore the importance of clear value propositions for adjunctive therapies and highlight the sensitivity of the market to affordability and clinical outcomes.
Geographical Dynamics and Regional Opportunities
The global footprint of the canine mammary tumor treatment market is characterized by distinct regional contributions, reflecting variations in veterinary infrastructure, pet ownership trends, and economic conditions. North America continues to command a substantial share, supported by advanced veterinary networks, high awareness levels, and a strong culture of pet healthcare expenditure. Europe follows as a significant contributor, driven by consolidated animal health markets and growing investment in veterinary oncology services.
Asia Pacific represents a dynamic growth corridor, where rapid urbanization, increasing pet adoption, and improving veterinary capabilities are accelerating market penetration. Latin America and the Middle East and Africa, while representing smaller absolute contributions in the current valuation, offer emerging potential as veterinary standards rise and access to specialized care expands. For global strategists, these regional disparities highlight the importance of tailored go-to-market approaches, localized pricing strategies, and partnerships that can navigate diverse regulatory and reimbursement environments. The interplay between mature markets and high-growth regions will define the competitive calculus for the next several years.
End-User Ecosystem: Where Value Is Delivered
The distribution of treatment activity across end-user segments reveals critical insights into service delivery models and revenue concentration. Veterinary hospitals remain the dominant setting for intervention, leveraging comprehensive diagnostic capabilities, surgical expertise, and inpatient support. Specialty clinics contribute a significant and growing share, often serving as centers of excellence for advanced modalities, including radiation therapy and targeted treatment protocols. Academic and research institutes play a vital, albeit smaller, role in driving innovation, clinical trials, and the validation of emerging therapies.
This end-user landscape emphasizes the need for multi-channel engagement strategies. Companies developing therapeutic solutions, diagnostic tools, or service-based oncology offerings must account for the distinct procurement behaviors, clinical workflows, and decision-making units present in each setting. The convergence of standard care in hospitals with specialized innovation in clinics and research centers creates a complex but opportunity-rich environment for stakeholders that can align their offerings with the specific needs of each segment.
Competitive Landscape: Incumbents, Innovators, and Strategic Positioning
The market is defined by a competitive structure that blends established animal health giants with specialized oncology innovators and technology providers. Leading companies each bring distinct capabilities to the table, shaping the therapeutic and technological options available to veterinarians and pet owners.
Worldwide Canine Mammary Tumor Treatment Market
Zoetis Inc., headquartered in Parsippany, New Jersey, holds a prominent position through its oncology portfolio, including Palladia (toceranib phosphate), the first FDA-approved targeted therapy for canine cancers. While its primary indication centers on other malignancies, Palladia is utilized off-label or in supportive protocols for mammary tumors alongside chemotherapy and supportive care products, illustrating the cross-application potential of targeted agents in veterinary oncology. Boehringer Ingelheim Animal Health, based in Ingelheim am Rhein, Germany, provides a broad range of veterinary oncology and supportive care products, maintaining an active footprint in canine cancer management with treatments applicable to mammary tumor contexts.
Elanco Animal Health, located in Greenfield, Indiana, continues to expand its relevance through veterinary medicines and strategic acquisitions, such as Aratana, which have enriched its oncology portfolio with products used in canine cancer care, including mammary tumor settings. AB Science, headquartered in Paris, France, is advancing masitinib under brands such as Kinavet-CA1 and Masivet, a tyrosine kinase inhibitor with applications in canine cancers that is being explored for broader oncology use, including potential relevance to mammary tumors. Notably, in February 2026, the FDA granted a Minor Use in Major Species (MUMS) designation for Masivet in the treatment of canine mast cell tumors, a regulatory milestone that supports broader oncology development and signals pathway opportunities for related indications.
Technology, Precision Medicine, and the Research Frontier
Beyond pharmaceutical interventions, the competitive field includes technology and service innovators that are redefining treatment precision and accessibility. Karyopharm Therapeutics, based in Newton, Massachusetts, contributes to the targeted therapy landscape with verdinexor (Laverdia-CA1), a conditionally FDA-approved oral therapy for canine lymphoma, demonstrating the expanding scope of small-molecule options that are applicable across veterinary oncology, including mammary cases. VetDC Inc., in Fort Collins, Colorado, specializes in translating human oncology innovations to veterinary use, focusing on advancing therapies for canine cancers, including mammary tumor treatment, thereby bridging the translational gap between human and animal health.
PetCure Oncology provides advanced radiation oncology services and stereotactic radiosurgery for canine cancers, including treatment of mammary tumors, positioning itself as a service-oriented leader in localized, high-precision care. On the device side, Accuray Incorporated, in Sunnyvale, California, supplies precision radiotherapy systems such as CyberKnife and TomoTherapy, which are deployed in veterinary oncology centers for treating canine mammary tumors. Similarly, Varian Medical Systems, now part of Siemens Healthineers and headquartered in Palo Alto, California, offers radiotherapy and oncology solutions used in veterinary settings for non-surgical treatment of canine mammary tumors, reinforcing the role of advanced radiation platforms in the therapeutic mix.
FidoCure (One Health Company) introduces a precision medicine dimension by providing genomic testing-guided targeted therapies for canine cancers, including the identification of therapies effective against mammary gland tumors beyond established options like Palladia. This genomics-driven approach aligns with the broader industry shift toward personalized treatment selection. Meanwhile, CureLab Veterinary is developing Elenavet, a p62 plasmid-based immunotherapy, with initial application and proof-of-concept data in canine mammary tumors, representing an emerging immunotherapeutic frontier that could diversify the treatment armamentarium over time.
Research advancements continue to feed directly into clinical potential. Ongoing evaluation by the AKC Canine Health Foundation and Ohio State University, reported in early 2026, is examining Optical Coherence Tomography (OCT) for real-time intraoperative imaging to improve surgical margins and reduce recurrence in canine mammary tumor resection. Such innovations underscore the market's receptivity to tools that enhance surgical outcomes, lower complication rates, and improve long-term prognosis, all of which are critical drivers of stakeholder confidence and adoption.
Strategic Implications for Decision-Makers in 2026
As organizations plan for the 2026-2032 horizon, several strategic imperatives emerge from the market's structure and dynamics. First, the balance between established surgical standards and the gradual introduction of targeted, immunotherapeutic, and precision medicine approaches requires nuanced portfolio strategies. Companies must navigate the current reliance on off-label applications while preparing for the eventual maturation of labeled indications and companion diagnostics. Second, the concentration of market activity among a manageable set of leading players, with a combined share reflecting moderate but meaningful consolidation, suggests that competitive differentiation will increasingly depend on clinical evidence, service integration, and regional execution rather than volume alone.
Third, the comparative oncology paradigm—where canine mammary tumors serve as a spontaneous model for human breast cancer—creates a distinctive value proposition for research partnerships, translational pipelines, and cross-sector collaboration. This dynamic not only accelerates innovation but also opens channels for shared learnings, biomarker discovery, and therapeutic validation that can enhance product narratives and stakeholder engagement. Finally, the variability in regional maturity, end-user preferences, and cost sensitivity demands that strategies be calibrated to local realities. A one-size-fits-all approach is unlikely to capture the full opportunity set; instead, a segmented, evidence-led, and partnership-rich strategy will be essential for sustainable growth.
Access the Complete Intelligence Framework
This overview distills the strategic contours of the Worldwide Canine Mammary Tumor Treatment Market, emphasizing the macro trajectory, competitive forces, therapeutic evolution, and regional dynamics that define the landscape. However, the full depth of our analysis extends well beyond these high-level insights. The complete report provides a detailed segmentation framework across treatment types, end-user categories, and regional markets, supported by rigorous sizing, growth modeling, and scenario analysis. It also includes in-depth profiles of key companies, examinations of recent developments, and actionable recommendations for market entry, expansion, and competitive positioning.
To fully inform your 2026 decisions, we invite you to access the complete research. The detailed segmentation data, granular regional analysis, and comprehensive competitive profiling contained in the full report will enable you to move from strategic awareness to precise execution. Explore the full report to secure the intelligence needed to navigate this dynamic market with confidence and clarity.
For detailed analysis of this topic, please visit the official page: Worldwide Canine Mammary Tumor Treatment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com