

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Shows Worldwide Nuclear LED Market Hits $385.5M in 2025, Forecasted to Reach $573.9M by 2032

Navigating the Nuclear Light: Strategic Imperatives in the 2026 Global Nuclear Grade LED Lighting Market
The global nuclear grade LED lighting market stands at a critical inflection point. As nuclear facilities worldwide confront aging infrastructure, stringent safety regulations, and the pressing need for operational resilience, illumination systems have evolved from passive utilities into mission-critical safety components. Our latest Worldwide Nuclear Grade LED Lighting Market research delivers a comprehensive, data-driven roadmap for executives navigating this highly specialized sector. Spanning historical performance from 2020 through 2025 and extending forward to 2032, the study quantifies market trajectories, dissects competitive dynamics, and maps the regulatory and technological forces that will define procurement strategies and capital allocation decisions in the years ahead.
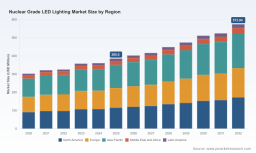
For corporate leaders responsible for facility modernization, supply chain resilience, or strategic R&D investment, this intelligence is not merely observational. It is a decision-enabling asset. The market, valued at USD 385.5 million in 2025, is projected to expand steadily to approximately USD 573.94 million by 2032, reflecting a compound annual growth rate of 5.85 percent. These figures are more than historical snapshots; they represent the underlying momentum of a sector where reliability, compliance, and technological specialization directly translate into commercial advantage. Understanding the structural drivers behind this trajectory is essential for organizations seeking to align product development, partnership strategies, and market entry initiatives with the realities of 2026 and beyond.
Market Evolution and Structural Foundations
Over the past half-decade, the nuclear grade lighting landscape has transitioned from incremental component upgrades to systematic, engineered lighting ecosystems. Historical revenue progression reveals consistent expansion: from USD 302.15 million in 2020 to USD 360.3 million in 2024, before accelerating to USD 385.5 million in 2025. This growth pattern underscores a sector that has moved beyond niche procurement cycles into sustained, demand-driven adoption. The forecasted expansion toward USD 402.45 million in 2026 and USD 511.06 million by 2030 signals that capital investment in radiation-tolerant, seismically qualified, and emergency-capable illumination is no longer discretionary. It is a foundational requirement for operational continuity.
The market's structural composition reflects this specialization. Segmentation across lighting intensity classifications reveals a dominant share allocated to moderate-radiation environment lighting, complemented by substantial allocations to high-radiation and low-radiation categories. This distribution indicates that procurement strategies are increasingly calibrated to specific operational zones within nuclear facilities, rather than relying on uniform, off-the-shelf solutions. Similarly, application-level segmentation highlights that primary deployment centers on nuclear power generation, supported by dedicated allocations for nuclear research reactors and nuclear waste and fuel management. These structural patterns demonstrate that end-user requirements are fragmenting into highly differentiated technical specifications, requiring vendors and buyers alike to move beyond generic product catalogs and engage in application-specific engineering alignment.
Regional distribution further illustrates the global footprint of this market. North America, Europe, and Asia Pacific collectively anchor the majority of demand, underscoring the need for multi-jurisdictional compliance capabilities, localized manufacturing footprints, and region-specific certification pathways. The presence of smaller but strategically meaningful allocations across the Middle East and Africa and Latin America suggests emerging procurement corridors where infrastructure development and facility modernization programs are beginning to drive specialized lighting requirements. For executives evaluating geographic expansion or supply chain diversification, understanding these regional demand architectures is essential to optimizing inventory positioning, regulatory alignment, and partnership networks.
Nuclear Valves Market
Regulatory Architecture and Technical Imperatives
In the nuclear sector, illumination is never a standalone specification. It is embedded within a dense regulatory and engineering framework that dictates material selection, testing protocols, and lifecycle performance expectations. Market participants must navigate seismic qualification standards, radiation tolerance thresholds, electromagnetic compatibility requirements, and extended emergency illumination mandates. Lighting fixtures deployed in containment areas and high-radiation zones must satisfy seismic qualification benchmarks such as those defined by IEEE-344, while also delivering prolonged emergency illumination capabilities that exceed post-incident safe shutdown requirements. These standards are not optional enhancements; they are compliance prerequisites that directly influence product design, qualification cycles, and procurement eligibility.
Radiation hardening represents another defining technical boundary. Gamma-tested luminaires engineered to withstand substantial cumulative dose exposures, including testing protocols validated at specialized facilities, illustrate the level of verification required for deployment in high-radiation environments. Compatibility with loss-of-coolant accident scenarios, the integration of radiation-tolerant electronic components, and the elimination of external driver shielding dependencies are all critical design considerations that separate qualified nuclear-grade solutions from conventional industrial lighting. Material engineering further reinforces these requirements. Stainless steel housings, smooth decontaminable surfaces, and components rated for extreme cumulative radiation exposure ensure that fixtures maintain structural integrity and operational performance under continuous environmental stress.
Quality assurance frameworks add another layer of complexity. United States nuclear facilities operate under structured quality programs and regulatory oversight that mandate rigorous documentation, traceability, and performance validation across radiation tolerance, seismic resistance, and electromagnetic compatibility dimensions. Emergency response infrastructure further intersects with environmental control standards that indirectly shape lighting system design, requiring coordinated reliability and safety planning. For manufacturers, engineering firms, and procurement teams, these regulatory intersections create both barriers to entry and opportunities for differentiation. Companies that internalize compliance as a core design principle, rather than treating it as a post-development validation step, are better positioned to secure long-term contracts, reduce qualification friction, and build trusted relationships with nuclear operators.
Competitive Landscape and Market Concentration
The competitive dynamics of this market reflect a concentrated yet highly specialized vendor ecosystem. With the top three firms collectively accounting for approximately 38.5 percent of market revenue and the top five firms representing roughly 52.4 percent, the landscape is defined by a balance of established technical leadership and agile innovation. This concentration indicates that scale alone does not guarantee market share; instead, proprietary radiation-hardening capabilities, in-house manufacturing integration, certification track records, and application-specific engineering expertise are the primary competitive differentiators.
Leading participants demonstrate the breadth of this specialization. DITO Lighting focuses on ultra radiation-resistant luminaires engineered for both air and underwater applications within nuclear power plants, emphasizing integrated driver architectures, accident condition compatibility, and vertically controlled design and manufacturing processes. Recent product evolution highlights the sector's iterative innovation pace, with model enhancements incorporating advanced chip-on-board LED configurations, redesigned mechanical housings for improved thermal and photometric performance, and enhanced safety features including thermal protection and operational mode optimization. Series consolidation strategies further illustrate how vendors streamline product architectures to reduce complexity while preserving application coverage.
Worldwide Nuclear Grade LED Lighting Market
Luminos Nuclear, operating through its affiliated engineering framework, manufactures gamma radiation-hardened luminaires validated through rigorous testing protocols and deployed across nuclear plants, research laboratories, and other high-radiation settings. Their portfolio spans stainless steel constructions and emergency variants, with end-to-end in-house production spanning mechanical, LED, and driver integration. Ahlberg Cameras contributes high-performance radiation-tolerant illumination solutions optimized for pool environments, containment areas, and hot cell operations, reinforcing the safety-critical role of reliable lighting in surveillance, maintenance, and personnel movement contexts. BIRNS, Inc. offers nuclear-grade LED systems including high-ceiling containment floodlights engineered for extreme radiation tolerance and seismically qualified emergency lighting fixtures capable of sustaining extended illumination durations, aligning product design with U.S. regulatory expectations for post-event operational safety.
Additional participants expand the competitive perimeter across specialized use cases and manufacturing philosophies. AO Sosny R&D Company develops radiation-resistant lighting engineered for hot cells, canyon spaces, underground areas, and maintenance zones within nuclear facilities, emphasizing high-input-power configurations suited to demanding operational environments. G&G Industrial Lighting produces compact radiation-resistant luminaires tolerant of accelerator-level radiation conditions, leveraging United States-based manufacturing and zero-maintenance design principles to address lifecycle cost concerns. Homewood Energy Services manufactures nuclear-grade emergency lighting fixtures governed by structured quality programs, incorporating maintenance-free battery architectures and seismic qualification to meet institutional compliance expectations. Martek Lighting supplies customized illumination solutions across nuclear, hydro, and thermal generation environments, emphasizing regulatory alignment, maintenance reduction, and operational cost optimization. LED Lighting Supply provides nuclear-grade systems engineered for radiation resistance, seismic and impact resilience, electromagnetic compatibility, and extended operational lifespans tailored to power generation facilities.
Together, these participants illustrate a market where technical credibility, certification depth, and application-specific engineering outweigh generic commercial positioning. For strategic decision-makers, this means that vendor evaluation must extend beyond catalog specifications to encompass testing documentation, qualification histories, integration capabilities, and long-term support structures. The competitive advantage will increasingly accrue to organizations that can demonstrate verifiable performance under operational stress while maintaining supply chain transparency and lifecycle service reliability.
Strategic Implications for 2026 Decision-Makers
The convergence of expanding market scale, tightening regulatory expectations, and increasingly specialized technical requirements creates a complex decision environment for 2026. Organizations operating in or adjacent to the nuclear sector must approach illumination strategy not as a procurement transaction but as a long-term operational resilience investment. Several strategic implications warrant close attention.
- Compliance as a design foundation. Seismic qualification, radiation tolerance, emergency illumination duration, and electromagnetic compatibility are no longer peripheral features. They are core design parameters that influence product architecture, qualification timelines, and market access. Procurement strategies should prioritize vendors with documented compliance frameworks and transparent testing validation rather than relying on generalized performance claims.
- Application-specific engineering alignment. As segmentation across radiation intensity levels and application domains becomes more pronounced, standardized lighting deployments will face growing operational limitations. Decision-makers should evaluate lighting solutions against zone-specific requirements, balancing radiation exposure profiles, maintenance access constraints, and emergency response integration to ensure functional alignment with facility operations.
- Lifecycle cost and maintenance architecture. The push toward zero-maintenance designs, extended operational lifespans, and maintenance-free backup systems reflects a broader industry shift toward total cost of ownership optimization. Capital expenditure decisions should incorporate long-term service reduction, replacement cycle forecasts, and operational downtime avoidance rather than focusing exclusively on initial purchase price.
- Supply chain resilience and regional compliance. With demand anchored across multiple major regions and supported by emerging procurement corridors, geographic diversification and localized manufacturing or certification capabilities can reduce regulatory friction and improve responsiveness. Organizations should assess vendor manufacturing footprints, documentation standards, and regional certification alignment as part of broader supply chain risk management.
- Technology integration and continuous innovation. Recent product iterations, including advanced LED integration, housing redesigns for mechanical and thermal stability, and series consolidation for unified application coverage, indicate that competitive differentiation will continue to emerge from engineering refinement rather than market expansion alone. Monitoring product evolution pathways and vendor R&D focus areas can inform partnership selection, specification updates, and forward-looking capital planning.
For investors, manufacturers, engineering integrators, and nuclear operators, the strategic question is no longer whether specialized illumination matters, but how to structure procurement, partnership, and innovation strategies around a market that increasingly rewards verifiable performance, regulatory fluency, and lifecycle reliability. Organizations that treat lighting as an integrated safety and operational system, rather than a discrete equipment purchase, will be better positioned to manage compliance exposure, reduce operational risk, and capture value in a steadily expanding market environment.
What the Full Study Delivers
This overview establishes the strategic context, but the complete Worldwide Nuclear Grade LED Lighting Market research provides the granular intelligence required to translate industry awareness into executable decision-making. The study maps historical revenue progression and forward-looking forecasts across the full 2020 to 2032 horizon, offering a structured view of growth momentum and market timing. It dissects segmentation dynamics across lighting intensity classifications, application domains, and regional demand architectures, enabling stakeholders to identify where procurement emphasis, engineering focus, and commercial opportunity are most concentrated.
Beyond market sizing, the research delivers detailed competitive profiling, including company-specific capabilities, product architecture strategies, testing and certification positions, and recent development activity that signals evolving technological priorities. It integrates regulatory and technical dynamics, clarifying how seismic qualification standards, radiation testing protocols, emergency illumination mandates, material engineering requirements, and quality assurance frameworks shape product eligibility and market access. This combination of market structure, competitive intelligence, and regulatory context equips executives with a comprehensive reference point for evaluating vendor landscapes, planning specification updates, assessing partnership opportunities, and aligning capital allocation with the operational realities of nuclear environments.
The full report is designed to support scenario planning, specification optimization, and strategic positioning across the 2026 to 2032 forecast window. By connecting macro growth trajectories with micro-level technical and competitive detail, it enables organizations to move from general market awareness to targeted, actionable intelligence.
Accessing the Complete Intelligence
The nuclear grade LED lighting market is entering a phase where technical precision, regulatory alignment, and strategic procurement discipline will separate long-term winners from reactive participants. The 2026 decision environment demands more than high-level market awareness. It requires verified data, structured segmentation insight, and competitive context that can inform specification, sourcing, and investment choices with confidence.
To secure the complete dataset, detailed segmentation breakdowns, full competitive profiles, and forward-looking scenario analysis, access the full Worldwide Nuclear Grade LED Lighting Market research report. The comprehensive study provides the depth and structure necessary to translate industry trajectory into concrete corporate strategy.
For detailed analysis of this topic, please visit the official page: Worldwide Nuclear Grade LED Lighting Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com