

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
PW Consulting Forecast: Melt Pump Market to Expand at a 5.8% CAGR from 2026–2032
By pmarketresearch, 2026-06-30
Melt Pump Market Outlook 2026: Strategic Imperatives for Resilient Growth
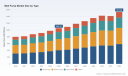
PW Consulting’s latest Melt Pump Market report (base year 2025) frames the sector at a pivotal inflection point for 2026 decision-makers. After recovering from a measured post-pandemic rebound (the market expanded from roughly USD 800 Million in 2020 to about USD 1,054.2 Million in 2025), our forecast analysis projects continued expansion through 2032, with a mid-single-digit compound annual growth rate of 5.8% across the 2026–2032 horizon. That trajectory, and the forces driving it, create immediate strategic choices for OEMs, processors, investors and procurement teams. This release highlights the report’s high-value takeaways and the practical actions leaders should prioritize in 2026; detailed segment-level tables, vendor scorecards and downloadable models are intentionally reserved for the full report to preserve competitive advantage and encourage direct subscription.
Melt Pump Market
Why this matters in 2026: Decisions that determine market share
-
Capital allocation: With the melt pump market on a steady growth path, capital budgeting for 2026 must balance modernization of extrusion lines against tighter ROI horizons and higher upfront costs for precision equipment.
Melt Pump Market -
Supplier strategy: Market concentration data show a landscape where the top three players hold a modest share and the top five capture roughly 60% of market influence. For buyers, this means a mix of global OEM strength and regional competitive pressure—creating room for both strategic partnerships and tactical sourcing.
Melt Pump Market -
Product roadmap and R&D: Advances in low NPSHr designs, low-shear profiles and higher-pressure capability are the differentiators that will matter to processors handling recycled and bio-based polymers in 2026.
-
Sustainability and compliance: Stricter environmental regulations in mature markets are already shaping melt pump requirements—pressure stability, reduced scrap and compatibility with higher recycled content are procurement must-haves.
-
Aftermarket and service models: The expanding installed base through 2032 makes aftermarket services, predictive maintenance and consumable replacement a durable revenue and margin pool.
What the report delivers: actionable, practitioner-focused analysis
-
Executive synthesis: Market sizing, macro drivers and a concise strategic checklist for 2026 investment and procurement decisions.
-
Top-line market model: Time-series market size from 2020 through 2032 (base year 2025), with scenario runs under conservative, base and accelerated demand assumptions and a clear sensitivity analysis around price, throughput and material mix.
-
Demand- and supply-side dynamics: Detail on cost drivers (material and labour), freight and logistics impacts, and regulatory tailwinds shaping product specs and customer requirements.
-
Technology benchmarking: Functional performance matrices for pressure, shear, thermal management and sensor integration, plus a technology adoption timeline that aligns with processor needs for recycled and bio-polymers.
-
Competitive intelligence: Qualitative and quantitative vendor profiles, value-chain maps, go-to-market coverage and pragmatic supplier selection frameworks (TCO, risk-adjusted scorecards).
-
Commercial playbooks: Procurement templates, spare-parts inventory policies and aftermarket service pricing strategies to protect margin while improving uptime.
-
M&A and partnership lens: Target capability maps and deal archetypes for entrants seeking scale, access to regional channels, or intellectual property in precision melt technology.
-
Tools and annexes: Downloadable models, interview transcripts, primary survey data and a glossary for cross-functional teams.
Competitive landscape — who to watch and why
The Melt Pump sector combines established global engineering leaders with nimble regional manufacturers. Our qualitative assessment identifies distinct positioning strategies and near-term implications:
-
Engineering incumbents: Firms such as Nordson Corporation and Maag Pump Systems retain technology leadership through focused product families that emphasize stabilization, low-shear flow and high-pressure capability. Their recent product upgrades and demonstrations underscore a strategy of performance differentiation for demanding extrusion and compounding lines.
-
Systems integrators and extruder specialists: Coperion, Kobe Steel (Kobelco) and others leverage broader extrusion portfolios (twin-screw solutions, pelletizing systems) to drive melt pump adoption as part of integrated line solutions—an attractive route for purchasers seeking single-vendor responsibility for throughput guarantees.
-
Precision and niche providers: European precision houses (e.g., WITTE) and North American engineering brands position around specialized applications—filament extrusion, high-viscosity polymers and controlled metering—where tolerances and material stability command premium pricing.
-
Regional value players: A cadre of manufacturers in Asia (mid-sized and local champions) compete aggressively on price and fast local support. Their presence affects lead times, part costs and aftermarket economics, especially for cost-sensitive processors and converters.
-
Service and aftermarket specialists: Independent service providers and divisions within larger industrial groups are growing the aftermarket, aftermarket sensor upgrades and retrofit offerings—creating an adjacent margin pool that matters for 2026 unit economics.
Taken together, the market shows moderate concentration: our analysis places the three largest firms at a material but not dominant share of the market and the five largest players at roughly 60% control—enough to influence standards and price points, yet leaving substantial opportunity for focused challengers. For executives, these dynamics argue for differentiated positioning (technology, service or cost leadership) rather than attempt to outspend incumbents on scale alone.
Key market dynamics and their 2026 implications
-
Labour & automation: Increasing adoption of automated extruder lines reduces direct labour needs but raises the bar for control systems and pump integration. Buyers should prioritize suppliers with robust control interoperability and remote diagnostics.
-
Material costs and circularity: Precision melt pumps often require higher initial capex, particularly when processing recycled feeds. Capital planning must include lifecycle cost models that capture throughput loss, scrap rates and rework avoided by more stable melt delivery.
-
Regulatory pressure: New environmental mandates in mature markets are tightening acceptable scrap rates and dictating higher process stability. This elevates melt pump specifications from “nice-to-have” to procurement criteria with compliance risk attached.
-
Freight and supply chain volatility: Rising shipping costs for precision-engineered components are accelerating onshore or nearshore sourcing strategies for spare parts and service inventory.
-
Sustainability-driven product demand: Consumer-packaging trends demanding higher recycled content create differentiated demand pockets for melt pumps capable of maintaining throughput with variable input quality—an R&D priority in 2026.
A pragmatic strategic playbook for 2026
-
Adopt a TCO procurement framework: Evaluate suppliers not only on unit price but on uptime guarantees, spare-parts availability, service SLA and retrofit capability for recycled materials.
-
Pursue modular investments: Prioritize melt pump upgrades that are modular and retrofittable to protect existing capex while enabling incremental performance gains.
-
Dual-source critical components: Mitigate freight and geographic risk by combining global OEMs for performance-critical units with vetted regional manufacturers for spares and quick-turn needs.
-
Invest in sensorized pumps and analytics: Push for predictive maintenance pilots in 2026 to convert uptime improvements into quantifiable savings—ideal candidates for capex-to-OPEX shifts or managed-services pilots.
-
Align R&D to recycled feedstocks: Re-prioritize development roadmaps to include low-shear options and thermal control strategies tuned for variability in recycled polymers.
-
Consider targeted M&A and partnerships: Buyers seeking to accelerate capability should evaluate tuck-ins that add service networks, aftermarket parts platforms or complementary extrusion technologies.
Methodology and confidence
The body of work behind the report integrates primary interviews with OEMs, processors and service providers, proprietary shipment and vendor revenue reconciliation, and bottom-up demand modeling calibrated to observable extrusion capacity. Historical series (2020–2025) and the base year 2025 feed into a scenario-driven forecast for 2026–2032, underpinned by a 5.8% CAGR in the base case. Each forecast node includes sensitivity bands and documented assumptions for pricing, utilization and regulatory impact. As noted, detailed tables, segment-level splits and vendor scorecards are excluded from this overview to preserve the commercial fidelity of the full dataset.
Next steps — how to use this analysis in 2026 planning
-
Procurement leaders should request the full report’s supplier scorecards to redesign supplier panels and renegotiate SLAs with an emphasis on lifecycle value.
-
R&D and product teams should use our technology comparisons to prioritize low-NPSHr, low-shear pump designs and integration with Industry 4.0 telemetry in their 2026 roadmaps.
-
Corporate strategists and corporate development teams should leverage the M&A archetypes in the full study to identify bolt-on acquisition targets that accelerate aftermarket or regional service capabilities.
PW Consulting’s Melt Pump Market report is built to be a decision-support tool for 2026: it translates market growth, supplier dynamics and technological change into practical, prioritized actions. To access the full dataset, segment-level revenue tables, vendor scorecards and the downloadable forecasting model, please follow the link in our press kit. The summary here is designed to demonstrate the report’s depth while reserving the granular intelligence that will inform your next procurement cycle or investment due diligence.
For detailed analysis of this topic, please visit the official page: Melt Pump Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Reverse Osmosis Membranes Market to Rise from USD 7.9 Million in 2025 to USD 12.57 Million by 2032, Driven by 6.9% CAGR
By pmarketresearch, 2026-06-30
Reverse Osmosis Membranes Market 2026: Strategic Imperatives from PW Consulting’s New Industry Report
Executive preview
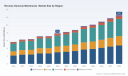
PW Consulting’s latest market study on Reverse Osmosis (RO) Membranes synthesizes five years of historical data (2020–2025) and provides a robust 2026–2032 forecast. The global market, measured in USD Million, expanded from approximately 5.7 in 2020 to 7.9 in 2025 and is projected to reach roughly 12.6 by 2032 at a compound annual growth rate (CAGR) of 6.9% over the forecast window. This growth context underpins a range of strategic decisions that water technology providers, system integrators, investors, and public utility planners must make in 2026. The following preview highlights how our analysis converts macro trajectory and industry dynamics into actionable choices—while reserving our full segmentation tables and granular financials for the complete report.
Reverse Osmosis Membranes Market
Why this market matters for 2026 strategic planning
-
Structural growth with pockets of acceleration: While the market shows steady compound growth, pockets of accelerated opportunity are emerging where regulatory pressure, industrial water reuse mandates, and desalination investments converge. These pockets are likely to outpace average growth and become focal points for capital deployment.
Reverse Osmosis Membranes Market -
Consolidation and concentration: Market concentration is notable—our analysis indicates that the top three suppliers control a majority of market share, and the top five extend that dominance significantly. For new entrants and niche specialists, this structure imposes strategic requirements around differentiation, channel partnerships, and scale economies.
Reverse Osmosis Membranes Market -
Technology and product evolution: Advances in thin-film composite and nanocomposite chemistries, element design (high-flux, low-fouling), and intelligent membrane monitoring are reshaping value propositions—shifting buyer emphasis from lowest-first-cost to lifecycle cost, water recovery, and regulatory compliance.
Data-driven decision levers
Three data-informed levers should drive boardroom debates in 2026:
-
Where to prioritize R&D and product roadmaps: Our historical-to-forecast trajectory demonstrates the commercial payoff of investing in salt-rejection efficiency, boron removal, and elements optimized for zero-liquid-discharge (ZLD) systems. Product programs that reduce energy intensity or enable higher recovery rates deliver measurable downstream benefits for large desalination and industrial reuse projects.
-
Supply-chain hedging and vertical integration: The 2025 period of raw-material price volatility (notably in high-grade polyester and polypropylene nonwovens) materially impacted manufacturing margins. Firms should evaluate hedging, dual-sourcing, and regional manufacturing footprints to mitigate cost oscillations.
-
Regulatory-driven demand capture: Enforceable contaminant limits and point-of-use standards are creating near-term procurement cycles in municipal and point-of-entry markets. Teams that align certification roadmaps and compliance support with sales strategies will capture outsized share as utilities accelerate upgrades.
Report practicalities: what the PW Consulting study delivers
Beyond headline forecasts, the full PW Consulting report is structured to support immediate operational decisions. Key deliverables include:
-
Actionable demand models: A bottom-up model calibrated to historical shipments and validated against company releases and procurement announcements—designed for scenario testing (base, downside, accelerated regulatory adoption).
-
Commercial playbooks: Go-to-market blueprints for suppliers targeting desalination, wastewater reuse, municipal utilities and industrial process water, including partner archetypes, channel economics and margin heat maps.
-
CapEx and manufacturing guidance: Benchmarks for unit economics across production scales, break-even analysis for greenfield lines, and a checklist for localization strategies in priority geographies.
-
Regulatory and standards tracker: A compendium of enacted and emerging regulations affecting membrane adoption—paired with recommended compliance timelines and certification priorities for manufacturers and system integrators.
-
Competitive matrix and M&A scan: Vendor positioning across technology, scale, and channel coverage, plus a readiness assessment for consolidation scenarios and potential alliance targets.
Competitive landscape: who to watch and why
The competitive field combines long-established global incumbents, specialty technology firms, and regional manufacturing leaders. Strategic takeaways from our company-level analysis:
-
DuPont Water Solutions (Wilmington, DE): A technology stalwart focused on product breadth across seawater, brackish and ZLD applications. Recent expansion of low-salt-rejection elements signals an intent to capture the high-value segment of minimal-liquid-discharge projects.
-
Toray Industries (Tokyo): Toray continues to invest in next-generation seawater desalination elements emphasizing salt and boron rejection—an investment that maps directly to large desalination EPCs and utility partners pursuing enhanced water quality targets.
-
LG Chem (Seoul): With its nanocomposite membrane portfolio and regional manufacturing partnerships, LG Chem is executing a hybrid strategy—technology differentiation plus localized production to serve fast-growing regional desalination markets.
-
SUEZ Water Technologies & Solutions (Paris): SUEZ couples high-flux membrane products with digital asset platforms for performance management—positioning itself for aftermarket and long-term service revenues.
-
Nitto Denko / Hydranautics (Osaka): Emphasizing energy-efficient removal of organics and drinking water applications, the firm is leveraging product introductions to expand into water treatment segments where regulatory detection limits are tightening.
-
Koch Separation Solutions (KSS) and AquaMem (United States): These suppliers focus on industrial and municipal spiral-wound and tubular designs and represent pragmatic partners for integration-sensitive projects.
-
Vontron (China) and Toyobo (Japan): Regional champions with automated production and high-performance offerings—relevant for companies evaluating cost-competitive sourcing or strategic joint ventures in Asia and adjacent markets.
Our report includes an objective performance matrix and a scenario-based view of how these vendors compete on technology, cost-to-serve, aftermarket services, and geographic reach.
Regulatory and market headwinds/ tailwinds
-
PFAS and contaminant regulation: Anticipated national-level rules (e.g., forthcoming PFAS limits in the U.S.) will accelerate demand for membrane-based solutions in municipal systems. Utilities facing enforceable maximum contaminant levels are likely to prioritize RO in treatment trains where activated carbon or ion exchange are insufficient.
-
Standards update: Revisions to installation and performance standards (including point-of-use certifications) increase the technical bar for manufacturers and installers—creating a competitive advantage for firms that invest in certified, turnkey solutions and third-party validation.
-
Incentives and localized policy: Targeted tax credits and installation incentives—illustrated by recent state-level measures—can materially alter project economics in underserved regions. Firms should maintain an active policy-monitoring capability to identify short-cycle procurement windows.
-
Raw material volatility: 2025 price swings for nonwoven supports underscore the need for input-cost monitoring, contractual flexibility, and potential backward integration for manufacturers with scale ambitions.
Strategic recommendations for 2026 (what boards and executive teams should do now)
Translate the market opportunity and risks into an executable roadmap with these prioritized actions:
-
Immediate (0–12 months):
-
Stress-test product portfolios for regulatory scenarios. Allocate fast-track funding to certify at-risk SKUs for updated point-of-use standards and contaminant removal requirements.
-
Secure critical supply lines and negotiate dual-sourcing contracts for nonwoven substrates and specialty polymers. Reprice product portfolios to reflect input-cost pass-throughs where contractually feasible.
-
Identify one pilot partnership with a large utility or industrial user to demonstrate lifecycle savings (energy, recovery, O&M) under new contaminant standards.
-
-
Near-term (12–36 months):
-
Invest in localized manufacturing capacity in priority regions where regional incentives and logistics economics favor onshore production. Consider brownfield upgrades before greenfield builds to shorten lead times.
-
Expand aftermarket and digital service offerings focused on predictive fouling management and performance guarantees—these services increase recurring revenue and stickiness with large buyers.
-
Pursue targeted M&A or JVs that fill technology gaps (e.g., boron removal, anti-fouling coatings) or provide immediate access to municipal sales channels.
-
-
Longer-term (3–7 years):
-
Shift R&D portfolios toward materials that deliver both energy and recovery gains while lowering life-cycle cost. Evaluate investments in hybrid membranes and integrated systems that enable higher-margin downstream services.
-
Build policy intelligence functions to influence standards and incentive programs; early involvement in standards development yields commercial advantages.
-
Develop flexible manufacturing modules that allow rapid capacity scaling to capture both steady baseline growth and episodic procurement spikes driven by regulation or large desalination awards.
-
Next steps and how PW Consulting supports execution
PW Consulting’s full Reverse Osmosis Membranes Market report provides the complete set of segmentation tables, regional demand forecasts, application-specific drivers, and vendor scorecards necessary to operationalize the recommendations above. In addition to the downloadable study, we offer tailored advisory packages—ranging from a two-week “market entry blueprint” to quarter-long capability-building engagements—that translate model outputs into executable business cases for capital allocation, partnership selection, and product roadmaps.
Closing note
The RO membrane market presents both predictable, steady expansion and high-variance pockets driven by regulation, regional policy, and technological differentiation. With global revenues approaching USD 8 Million in the base year and a mid-single-digit CAGR through 2032, 2026 is a pivotal year: companies that combine disciplined supply-chain resilience, targeted product investments, and alignment to new compliance cycles will define the competitive landscape for the remainder of the decade. For a comprehensive dataset, scenario models, and vendor-level strategic playbooks, access the full PW Consulting report and engage our advisory team to convert insight into market leadership.
For detailed analysis of this topic, please visit the official page: Reverse Osmosis Membranes Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: UV Lasers Market Poised to Expand at 8.7% CAGR as Demand from Semiconductor and Medical Sectors Surges
By pmarketresearch, 2026-06-30
UV Lasers Market 2026: Strategic Signals for Executive Decision-Making
Executive snapshot
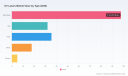
As a strategic advisor at PW Consulting, I present a high-level briefing of our latest UV Lasers Market study (base year 2025). The market has expanded from approximately USD 137.0 Million in 2020 to USD 188.0 Million in 2025 and is forecast to accelerate through the coming decade, reaching roughly USD 338.0 Million by 2032. This trajectory represents a compound annual growth rate of about 8.7% across the forecast horizon. For 2026 planning cycles, these macro dynamics convert into discrete strategic imperatives for product roadmap prioritization, capacity investment, channel strategy, and regulatory compliance.
UV Lasers Market
Why this matters for 2026 strategy
- Predictable growth envelope: Sustained mid-single-digit to high-single-digit CAGR gives boards the confidence to underwrite multi-year R&D programs targeted at UV-specific applications (deep UV lithography, micromachining, precision marking) while preserving optionality for faster pivots.
- Increasing technical differentiation: Breakthroughs in ultrafast pulses, wavelength stabilization, and compact deep-UV modules are shifting competition from commodity pricing to system performance, uptime, and application-specific integration.
- Regulatory and safety inflection: New standards and sectoral regulations are raising the bar for compliant deployment—turning what was once a cost center (safety, certification) into a market-access prerequisite and a source of competitive advantage.
What the market evolution tells us
The UV lasers market is maturing. The historical period (2020–2025) shows steady organic expansion driven by increased adoption in semiconductor microfabrication, precision medical devices, industrial marking, and advanced display processing. Looking forward to 2032, the forecast indicates both deeper penetration into existing applications and emergence of higher-value use cases—driven by ultrafast pulse capabilities and novel wavelength modules. These shifts favor suppliers that can offer end-to-end repeatability, minimal thermal load on substrates, and validated integrations for regulated industries.
UV Lasers Market
Practical, near-term actions for 2026
- Prioritize modular product architectures: OEMs and systems integrators should accelerate modularization—enabling faster wavelength swaps, plug-and-play safety enclosures, and serviceable power modules that reduce downtime and total cost of ownership.
- Embed compliance into design: Product development must incorporate regulatory testing and certification roadmaps (e.g., aerospace and medical standards). Early alignment reduces time-to-market friction and can command pricing premiums in safety-critical segments.
- De-risk supply chains: With demand rising, buyers should map critical subcomponents (nonlinear crystals, UV-grade fibers, diode pumps), identify single-source risks, and establish dual-sourcing or vertical partnerships before capacity shortages drive spot price volatility.
- Shift go-to-market toward solutions: Vendors should bundle lasers with validated process recipes, fixtures, and software analytics to move up the value chain—from component supplier to process partner.
- Invest selectively in photonics IP and service ecosystems: For strategics and financial sponsors, targeted M&A in laser control electronics, ultrafast pulse shaping, or specialized optics offers disproportionate leverage on product roadmaps.
Report highlights — what’s inside (practical, operational content)
Our full study is structured to support fast, board-level and operational decision-making. Key elements include:
UV Lasers Market
- Market sizing and trajectory models: A transparent, auditable topline model covering historical (2020–2025) and forecast (2026–2032) performance, with scenario variants for conservative, base, and accelerated adoption cases.
- Technology readiness and TRL mapping: Comparative assessment of major UV technologies (solid-state, fiber, excimer, diode-pumped solutions, ultrafast vs. nanosecond regimes) against performance, cost, and manufacturability metrics. This is presented as decision matrices and go/no-go thresholds for product roadmaps.
- Commercial playbooks: Channel strategies, pricing archetypes, MQL-to-deal conversion benchmarks, and service revenue levers for suppliers seeking to capture aftermarket and license revenues.
- Regulatory and standards compendium: Practical checklists and test protocols required for aerospace, medical, and industrial deployments—linking standards to certification steps and expected timelines.
- Supply chain heatmaps and sourcing playbooks: Component concentration analyses, supplier scorecards, and recommended strategies for redundancy and nearshoring where warranted.
- Financial scenarios and investment cases: Capex/Opex modeling templates, NPV sensitivity runs, and break-even timelines for common investment archetypes (capacity expansion, new wavelength lines, service network rollouts).
- Actionable use-case dossiers: End-user process validation guides for semiconductor, medical, marking, and other prioritized segments—complete with expected yield improvements, cycle-time impact estimates, and key integration risks.
Because this publication follows a “trailer” design, the full segmented revenue tables, geographic and application splits, and the granular unit economics are available exclusively in the paid report and through our client portal.
Competitive landscape — who’s shaping the next wave
The market structure is moderately concentrated: the top three suppliers capture approximately two-thirds of market revenues, while the top five approach three-quarters of the market—indicating strong incumbents with meaningful scale advantages. Competitive dynamics are now defined less by raw output and more by system-level performance, service availability, and validated application expertise.
- Coherent Corp. — A leader in high-energy deep-UV systems tailored to semiconductor lithography and display processing. Recent launches demonstrate a push toward wavelength-stabilized, high-power platforms that aim to reduce variability in critical process windows.
- TRUMPF — Focused on precision short-pulse UV sources for marking and sensitive substrates; their architecture emphasizes gentle, air-cooled operations suited for high-throughput production lines.
- IPG Photonics — Investing in ultrafast and deep-UV fiber solutions with a clear slant toward reliability and uptime—critical for micro-machining and inspection markets. Their showings at recent industry events signal readiness to scale module-level offerings.
- Han’s Laser — Maintaining strong presence in industrial marking and engraving with broad product accessibility, including handheld solutions. Their trade-show activity underlines continued focus on intelligent, factory-ready systems.
- Lumentum — Concentrating on nanosecond Q-switched platforms for micromachining and high-stability industrial applications; recent product showcases underline throughput and micro-processing performance improvements.
- Amplitude Laser, MKS (Spectra-Physics), DPSS/Laserax — These firms advance specialized niches—ultrafast femtosecond offerings, high-speed marking, and certified workstations respectively—each providing potential partnership or acquisition targets based on corporate strategy.
Recent industry developments to watch (implications for 2026)
- IPG Photonics and Lumentum showcased new high-precision deep UV and ultrafast platforms at SPIE Photonics West 2026—signaling accelerated commercialization of higher-power, application-ready modules. Buyers should expect availability of more compact, higher-throughput units in 2026–2027.
- Coherent’s March 2026 launch of a wavelength-stabilized deep UV system highlights vendor competition at the lithography and display processing frontier. This raises the bar for suppliers addressing sub-micron process windows.
- Han’s Laser and other assembly-line-focused vendors are positioning smarter, more connected marking systems at major trade shows—indicating a shift toward integrated factory deployments where laser performance is coupled with process analytics.
- Standards activity (e.g., aerospace wiring marking requirements and safer Class 1 workstation certifications) is increasing the compliance burden—but also creating opportunities for “compliant-by-design” products that simplify customer procurement and audit trails.
Risk map and mitigation priorities
- Technology obsolescence risk: Shorten development cycles via modular platforms and incremental upgrades rather than monolithic single-version releases.
- Supply concentration: Source critical optics and pump diodes from multiple qualified suppliers; consider component stockpiles for planned ramp phases.
- Regulatory delay: Build certification timelines into go-to-market plans; pursue joint validation pilots with anchor customers to accelerate approvals.
- Customer adoption lag: Offer pilot-as-a-service programs to demonstrate value and reduce procurement friction.
How PW Consulting helps
Our report is designed to be immediately actionable for CFOs, CTOs, VP Product, and corporate development teams. We combine quantitative market models, legal/regulatory mapping, competitive benchmarking, and executable commercial playbooks. For organizations preparing capital budgets or strategic roadmaps for 2026, the study provides tailored scenario outputs and a suite of templates that compress decision cycles from months to weeks.
Next step — where to go for full intelligence
This briefing intentionally presents the strategic contours and executable implications while omitting detailed subsegment tables and proprietary financial matrices. For the full dataset—region and application splits, wavelength and technology revenue breakdowns, unit economics, and downloadable modeling files—please visit our report landing page. Engaging with the full report will equip your leadership team with the granular inputs required to finalize 2026 capital allocations, product launch sequencing, and M&A screening criteria.
For tailored briefings, model walkthroughs, or scenario workshops focused on your role in the UV lasers ecosystem, PW Consulting offers executive workshops and bespoke modeling services to turn this market intelligence into immediate competitive advantage.
For detailed analysis of this topic, please visit the official page: UV Lasers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Predicts 3D Weaving Fabrics Market to Hit USD 266.5 Million by 2032
By pmarketresearch, 2026-06-30
3D Weaving Fabrics Market 2026 Strategic Outlook — PW Consulting Intelligence Brief
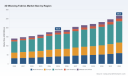
As manufacturers, OEMs, and investors prepare strategic plans for 2026, the PW Consulting 3D Weaving Fabrics Market report offers a focused, executable intelligence package to guide high-stakes decisions. Grounded in a 2020–2025 historical dataset and an explicit 2026–2032 forecast horizon, the study quantifies a steady expansion trajectory (5.55% CAGR across the forecast window) and traces the structural forces shaping demand, supply, technology adoption, and regulatory risk. The market reached approximately USD 183.8 Million in our base year (2025) and is projected to grow to roughly USD 266.5 Million by 2032 — a profile consistent with a maturing, innovation-led materials subsector that is becoming mission-critical across mobility, protective, and performance applications.
3D Weaving Fabrics Market
Why this report matters for 2026 decision cycles
- Capital allocation: validates near- and medium-term ROI expectations for capacity expansion, machine investment, and automation projects against a credible CAGR and scenario set.
- Supply chain strategy: informs raw material contracting (notably carbon fiber and engineered polymers), geographic sourcing, and inventory hedging in light of regulatory and export-control dynamics.
- Product and technology roadmaps: helps prioritize R&D bets (near-net shaping, integrated reinforcements, hybrid knit-weave hybrids) by mapping technology readiness to addressable end markets.
- M&A and partnerships: identifies strategic windows for bolt-on acquisitions and co-development agreements where market concentration and capability gaps align with corporate objectives.
What PW Consulting’s 3D Weaving Fabrics Market report contains
- Full historical time series (2020–2025) and a granular forecast model (2026–2032) — inclusive of base-case, upside, and downside scenarios.
- Demand-side segmentation by geography, fabric architecture, and end-use application, with trend narratives and market sizing at the aggregate level. (Note: the press summary intentionally omits granular segment-level figures to preserve the report’s data value.)
- Comprehensive supply-side mapping: manufacturers, machine vendors, converter networks, and component suppliers, with capacity maps and utilization stress tests.
- Technology assessment and TRL-style positioning for 3D weaving variants, spacers, and hybrid constructions, including manufacturability and scale-up risk matrices.
- Raw-material and price sensitivity analysis, supplier risk indices, and contract negotiation playbooks for carbon fiber and specialty polymer inputs.
- Regulatory, standards, and trade policy impact assessment — with country-level implementation scenarios and compliance mitigation strategies.
- Competitive benchmarking: revenue-agnostic capability profiles, commercialization roadmaps, and potential M&A candidate scoring.
- Executive 90/180/365-day action plans tailored to buyers, suppliers, and investors.
Data-driven strategic takeaways for 2026
Growth will be steady rather than meteoric. The mid-single-digit CAGR we model reflects expanding use of 3D woven architectures where performance and integration advantages justify premium pricing — notably in structural composites, protective systems, and integrated apparel. That said, growth will be uneven by application and region as OEM adoption, regulatory shifts, and raw-material dynamics reorient supplier economics.
3D Weaving Fabrics Market
- Demand katalysts: system-level benefits (weight reduction, through-thickness reinforcement, fewer secondary bonding steps) are accelerating adoption in composites-heavy segments. Expect sustained traction in automotive lightweighting, performance sports equipment, and industrial protective gear, with new use-cases emerging around multifunctional wearables and protective apparel.
- Supply and concentration: market concentration remains modest — our concentration metrics point to a fragmented supplier base with room for consolidation. This creates arbitrage for strategic acquirers and risks for firms that rely on a narrow supplier set.
- Raw-material posture: carbon-fiber pricing has shown relative stability into 2025–2026 at key grades, but supply and lead-time volatility persists for specialty formulations. Buyers should adopt staged volume commitments and explore material substitution pathways where technical requirements permit.
- Regulatory and trade friction: recent policy moves — such as India’s expanded certification requirements for weaving equipment and updates to the U.S. Commerce Control List classifying multidirectional weaving machines — materially affect where capital can be deployed, what equipment can be imported, and how IP-protected machine architectures are traded. These constraints argue for diversified manufacturing footprints, local partnership arrangements, and proactive compliance planning.
Competitive landscape: reading the players and their strategic plays
The ecosystem is populated by specialized innovators, regional champions, and converters who combine design know-how with composite systems integration. Key strategic archetypes observed include pure-play technology licensors, vertically integrated producers, converter-specialists, and machine vendors enabling on-site capability expansion.
3D Weaving Fabrics Market
- Technology-first developers — firms like the Belgium-based developer known for its 3D weaving technology are positioned as technology originators targeting composites and technical-application niches. For alliances, these players are attractive R&D and OEM partners.
- Performance-material specialists — manufacturers from East Asia producing engineered 3D carbon, fiberglass, and UHMWPE constructions address ballistic, industrial, and hybrid-composite markets. Their strengths are cost-competitive scale and engineered fiber expertise; their strategic moves typically emphasize vertical integration and export-led growth.
- Converter and composite systems players — industry converters focused on carbon-fibre 3D textiles serve aerospace, wind, marine, and automotive customers. These firms compete on end-to-end qualification capability and supply security rather than raw price alone.
- Innovative knitted/woven hybrid players — companies introducing knitted 3D solutions (including spacer and seamless functional platforms) are pushing into apparel and protective gear, leveraging textile design to embed functionality (reinforcements, pockets, thermal control) without heavy secondary assembly.
- Regional production specialists — midsized firms with adjacent capabilities (spacer fabrics, woven composites) serve local OEM clusters. They are preferred partners for localized programs and rapid prototyping.
Recent industry moves provide a window into strategic direction. Notable examples include the commercial introduction of a 3D weaving platform enabling seamless performance apparel with integrated reinforcements, trade-show-led product demonstrations of film-infused near-net shapes and thermal protection systems, and machine vendors showcasing 3D weaving capability at regional technical textile shows. These signals emphasize two persistent themes: (1) manufacturers are prioritizing manufacturable integration (near-net shaping, in-line joining) and (2) visibility at technical venues is being used to accelerate OEM qualification cycles.
Regulatory and operational risk matrix
- Machine and technology export controls: the classification of multidirectional, multidimensional weaving machines under expanded export control regimes increases the complexity of cross-border equipment procurement and licensed manufacturing relationships. This elevates the value of domestic machine capability and local partnerships in sensitive jurisdictions.
- Standards and certification: new certification regimes for weaving and embroidery machinery in select markets introduce lead-time and documentation burdens for equipment OEMs and end users — companies will need to front-load compliance tasks into 2026 CAPEX planning.
- Input volatility: while average selling prices for chosen carbon-fibre grades have been stable, supply concentration for high-modulus and specialty grades can create tight windows for qualification-linked sourcing; strategic stocks or multi-sourcing agreements mitigate production risk.
Practical 90/180/365-day playbook for executives
- Next 90 days — perform a rapid supply-security audit (raw materials + machine vendors), initiate compliance reviews for anticipated export or import constraints, and launch two pilot co-development tests with candidate 3D weaving partners to validate performance claims and lead times.
- Next 180 days — commit to at least one scaling path: either secure long-lead time equipment with staged commissioning, or finalize a localized contract manufacturing agreement. Begin formal due diligence on acquisition targets that close capability gaps (converter capacity, machine know-how, or regional presence).
- Next 365 days — operationalize a productization pipeline for 3D-woven-enabled offerings (from design to qualification), lock multi-year strategic supply contracts with tiered pricing, and roll out a blended sourcing strategy that hedges both material and regulatory risk.
How PW Consulting’s report unlocks value
This report is designed as an execution toolkit: not only does it provide verified historical and forecasted market sizing (2020–2032) and a clear CAGR for planning, it maps the practical levers that move margin and time-to-market. For corporate strategists, procurement leads, and private-equity teams, the intelligence enables confident allocation of capital and prioritization of integration vs. partnership models — while preserving flexibility around equipment strategy and IP exposure.
Next steps
PW Consulting’s full report contains the proprietary segment-level breakdowns, detailed company capability matrices, supplier scorecards, and interactive forecasting models that executives need to finalize 2026 plans. The summary above intentionally omits those granular figures to preserve the actionable intelligence contained in the full deliverable. For access to the complete dataset, scenario workbooks, and bespoke advisory engagements tailored to your portfolio or operations, please visit our report page or contact PW Consulting’s advisory desk to arrange a briefing and data license.
For detailed analysis of this topic, please visit the official page: 3D Weaving Fabrics Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Effects Processors & Pedals Market Poised for 5.8% CAGR in 2026–2032 Forecast
By pmarketresearch, 2026-06-30
Effects Processors and Pedals Market 2026: Strategic Imperatives from PW Consulting’s New Industry Brief
As organizations plan investments and competitive moves for 2026, the effects processors and pedals market presents a balance of steady expansion and concentrated competition that rewards clarity of strategy. PW Consulting’s latest market research—anchored on a base year of 2025—maps the sector’s trajectory with a data-driven lens: the global market expanded from approximately USD 1,214 million in 2020 to USD 1,730 million in 2025, and is forecast to reach roughly USD 2,518 million by 2032, a compound annual growth rate of 5.8% over the forecast window. These headline dynamics, combined with an industry concentration where the top three and top five firms control material shares of the market, create defined opportunities and tactical constraints for manufacturers, retailers, and investors entering 2026.
Effects Processors and Pedals Market
Why this brief matters for 2026 decision-makers
Leadership teams must translate macro growth into executable plans: where to invest R&D, which channels to prioritize, how to price and position products, and when to pursue M&A. Our report is structured to do just that: it goes beyond topline figures to provide practical playbooks for product portfolio management, channel optimization, supply chain resilience, and partnership strategies—without compromising proprietary subsegment modeling that we reserve for subscribers. In short, the brief is a strategic compass that links market-size trends and concentration dynamics to concrete actions leaders can take this year.
Effects Processors and Pedals Market
Key market signals shaping 2026 strategy
- Reliable growth trajectory: The market’s steady climb (from 2020 through 2025 and into the projected 2026–2032 window) reduces the risk of demand volatility, enabling multi-year investment plans in product development and brand-building.
- Consolidation with room for differentiation: Market concentration metrics indicate that a handful of players command significant share, creating scale advantages in distribution and marketing—but also leaving niches open for specialized, premium, or highly innovative entrants.
- Technology bifurcation: Digital modeling and multi-effects platforms continue to gain technical credibility and user adoption, while analog and boutique pedals retain cultural cachet among segments of professional users and collectors. Product strategies must reconcile these dual currents.
- Channel and monetization evolution: Direct-to-consumer digital channels, subscription-enabled software ecosystems, and bundled hardware–software offerings are shifting value capture away from traditional retail-only models.
What PW Consulting’s report delivers (practical, operational, and confidential)
Our industry brief is designed for operators and investors who need to move from insight to action. It includes:
Effects Processors and Pedals Market
- Five actionable growth scenarios through 2032—each with trigger points and tactical recommendations for product mix, pricing, and channel investments.
- Go-to-market playbooks for three archetypal companies: scale incumbents, challenger brands, and boutique specialists—detailing SKU rationalization, tiered pricing, and partnership matrices.
- A supply-chain risk register tied to component-level sensitivity (DSP chips, analog parts, enclosure supply) and mitigation options, including strategic sourcing and inventory hedging frameworks.
- M&A and corporate development frameworks: target screening criteria, valuation sensitivity to margin accretion from software bundles, and integration checklists for fast post-deal synergies.
- Retail and distribution optimisation guidance: balancing route-to-market between specialist retailers, pro audio distributors, and direct digital channels to maximize margin and lifetime value.
- Product development prioritization: a decision matrix for investing in modeling algorithms, boutique analog circuits, modular designs, and software ecosystems depending on customer segment economics.
Competitive landscape: what leading firms are doing—and what it means for 2026
The sector’s competitive field ranges from global mass-market incumbents to specialty boutique innovators. Core firm profiles in our analysis—spanning legacy electronics brands and new-model DSP specialists—reveal distinct strategic postures.
- Boss Corporation (Hamamatsu, Japan; boss.info) — Strength: deep brand equity and a broad product footprint that bridges mass-market pedals and pro-level offerings. Strategic implication: leverage brand to expand premium lines while using scale to defend mid-market volumes.
- Electro-Harmonix (New York, USA; ehx.com) — Strength: iconic, enduring analog designs with strong secondary market recognition. Strategic implication: capitalize on heritage with limited-edition runs and curated reissues while selectively investing in hybrid analog–digital features.
- Line 6 (Mission Viejo, CA; line6.com) — Strength: advanced modeling platforms and multi-effects ecosystems. Strategic implication: push software and online services to create recurring revenue and promote deeper integration with DAWs and live-performance workflows.
- TC Electronic (Copenhagen, Denmark; tcelectronic.com) — Strength: studio and live-focused product lines. Strategic implication: double down on pro-audio partnerships and certification programs for touring professionals and rental houses.
- Strymon Engineering (Austin, TX; strymon.net) — Strength: high-end digital processors and premium user experience. Strategic implication: defend price premium through continuous DSP innovation and boutique channel partnerships.
- Kemper GmbH (Koblenz, Germany; kemper-amps.com) — Strength: profiler technology and pro multi-effects. Strategic implication: explore vertical integrations with amp makers and live-sound platforms to extend recurring revenue opportunities.
- Digitech, MXR, Ibanez, Zoom, Korg, Neural DSP, EarthQuaker Devices — Each brand occupies a slice of the market: mass-market multi-effects, classic boutique pedals, advanced modeling, and software-first processors. Strategic implication: competitive differentiation will increasingly come from platform ecosystems, software services, and brand storytelling rather than hardware features alone.
Strategic plays for 2026
Based on the report’s integrated analysis, PW Consulting recommends that executives prioritize three strategic plays depending on their position:
- For scale incumbents: Optimize the product ladder—use tiered SKUs with shared hardware platforms to reduce cost-to-serve, then invest in software bundles and subscription modules that increase wallet share and customer stickiness.
- For challengers and innovators: Focus on high-impact differentiation—unique DSP algorithms, modular hardware, or software-first user experiences. Use targeted limited runs and community-driven marketing to build loyalty without requiring heavy distribution investments.
- For boutique players: Protect margin through scarcity and craftsmanship—limited editions, collaborations with artists, and a strong secondary-market narrative. Lean on direct channels and selective distributor partnerships to preserve brand mystique.
Operational moves to implement in the next 12 months
- Reassess SKU profitability and retire low-velocity SKUs—free up R&D and marketing bandwidth for high-opportunity products.
- Initiate cross-functional pilots that pair hardware releases with software services (tone libraries, artist presets, cloud backups) to test subscription uptake.
- Negotiate strategic supply agreements for key DSP components and diversify contract manufacturers to mitigate single-source risk.
- Develop an M&A watchlist focused on complementary tech (modeling IP, DSP startups) or channel assets (regional distributors with strong pro-audio ties).
- Deploy data-driven marketing to convert hobbyist buyers into brand advocates through education, digital content, and targeted community programs.
Why the headline numbers matter—and what we deliberately withhold
Headline market statistics—such as the market’s recorded growth from about USD 1,214 million in 2020 to USD 1,730 million in 2025 and its projected rise to USD 2,518 million by 2032 at a 5.8% CAGR—set the investment backdrop. They make clear that the sector is expanding but not exploding, favoring disciplined, scalable initiatives over high-risk, capital-intensive gambles.
That said, in accordance with PW Consulting’s publication strategy, detailed subsegment-level financials and granular regional/application percentages are reserved for the full report and interactive datasets. This “preview” is crafted to demonstrate methodological rigor and to equip leaders with immediate, actionable direction while guiding stakeholders to the full source for transaction-level modeling and custom scenario outputs.
Next steps: translating insight into boardroom action
- Executive teams should schedule a strategy workshop in Q1 2026 to align product, channel, and M&A priorities against the scenarios in our brief.
- Investors and corporate development teams should request the full dataset to evaluate acquisition targets and to run sensitivity analyses on margin expansion through software monetization.
- R&D leaders should use our product prioritization matrix to allocate engineering cycles to the highest ROI projects across digital modeling, analog craftsmanship, and hybrid platforms.
PW Consulting’s Effects Processors and Pedals Market report is built to be an operational tool for boardrooms and executive teams preparing for 2026. For access to the complete dataset, subsegment forecasts, and bespoke scenario modeling that support tactical execution, visit the report page or contact our team for a tailored briefing.
For detailed analysis of this topic, please visit the official page: Effects Processors and Pedals Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecasts Covid-19 Vaccine Market to Soar to USD 284 Billion by 2032
By pmarketresearch, 2026-06-30
PW Consulting: Strategic Brief — Covid-19 Vaccine Market Outlook and What Executives Must Do in 2026
Executive snapshot
PW Consulting’s latest Covid-19 Vaccine Market report frames a pivotal moment for industry leaders and life‑science investors preparing decisions in 2026. After a dramatic market emergence in 2020, the global market baseline in our 2025 assessment stood at approximately USD 160 Billion. Our modeling projects a steady recovery and expansion at a compound annual growth rate of 8.75% through 2032, reaching roughly USD 284 Billion by the end of the forecast horizon. The market remains concentrated — the top three manufacturers account for two‑thirds of supply and the top five near four‑fifths — but competitive dynamics are being reshaped by product updates, regulatory guidance, and evolving payer behavior.
Covid-19 Vaccine Market
Why this report matters for 2026 decision-making
- Timing: 2026 will be the first full operational year after widespread adoption of the 2025–2026 vaccine formulations and new regulatory guidance; decisions made now about capacity, portfolio and channels will lock in access and margin profiles for several years.
- Risk navigation: Variant uncertainty continues to drive demand volatility. Our scenarios quantify the range of outcomes from limited, seasonal booster programs to episodic surge immunization campaigns — enabling boards to stress‑test capital allocation and commercial plans.
- Concentration & partnership opportunity: With a high market concentration among leading mRNA and protein manufacturers, strategic non‑traditional entrants (contract manufacturers, regional producers, and specialized subunit players) can define niches via regional supply agreements, differentiated formulations, and service‑led value propositions.
What the report delivers — practical, transaction‑ready intelligence
The PW Consulting Covid-19 Vaccine Market report is built for operators and investors who need executable insights rather than academic summaries. Key practical deliverables include:
Covid-19 Vaccine Market
- Market sizing and scenario forecasts (base year 2025, historical 2020–2025, forecast 2026–2032) that quantify upside and downside demand curves under alternative epidemiologic and policy scenarios.
- Regulatory pathway mapping and decision calendars for 2026–2028, isolating the windows when approvals, authorizations, and guideline revisions are most likely to influence procurement cycles.
- Supply‑chain stress tests: capacity heat maps for fill‑finish, cold‑chain logistics, and raw material bottlenecks, together with mitigation strategies and contracting templates to accelerate onboarding.
- Commercial playbooks: pricing sensitivity models, channel optimization frameworks (public tender vs. retail/private purchase), and payer negotiation guides tailored to regionally differentiated reimbursement environments.
- M&A and partnership scorecards: identification of technically attractive targets (manufacturing, IP, or distribution), valuation ranges under multiple integration scenarios, and a short list of advisable diligence checkpoints.
- Operational checklists for manufacturers and CDMOs covering technology transfer, scale‑up phasing, regulatory dossier alignment, and post‑launch surveillance obligations.
Competitive landscape — who matters and why
The market’s competitive architecture combines legacy pharmaceutical incumbents and specialized vaccine innovators. Key players profiled in the report include:
Covid-19 Vaccine Market
- Pfizer‑BioNTech (New York, USA): A global leader with a market‑leading mRNA product family and established distribution networks. Continues to refine seasonal formulations and leverage broad WHO prequalification and global channel reach to defend volume and premium pricing.
- Moderna (Cambridge, USA): An mRNA powerhouse that has secured approvals for updated 2025–2026 formulations targeting dominant lineages. Its platform agility and pipeline strategy make it a primary competitor in the older adult and high‑risk segments.
- Novavax (Gaithersburg, USA): A protein subunit specialist whose 2025–2026 formulation has achieved regulatory traction for prioritized populations. Novavax represents a differentiated technological option, particularly where cold‑chain constraints or vaccine hesitancy favor non‑mRNA choices.
- Serum Institute of India (Pune, India) and Bharat Biotech (Hyderabad, India): Large‑scale regional manufacturers with WHO prequalification and cost‑competitive production footprints — critical partners for global supply security and tiered pricing strategies.
- HIPRA HUMAN HEALTH (Amer, Spain): A European manufacturer offering alternative formulations and regional manufacturing capabilities that can be pivotal for European and adjacent markets seeking diversified suppliers.
Our competitive analysis is forward‑looking: it not only catalogs product portfolios and approvals, but maps credible near‑term moves — alliance themes, capacity expansions, and likely tender strategies — that could materially alter share dynamics in 2026.
Regulatory and demand dynamics shaping 2026
- Variant‑driven formulation guidance: Recent regulatory recommendations have explicitly steered the 2025–2026 vaccine formula toward lineage‑matching approaches. These guidance signals compress development timelines and favor manufacturers with rapid antigen update capabilities and robust surveillance linkages.
- Targeted approvals and prioritized groups: Several regulatory authorities have granted approvals focused on older adults and high‑risk populations for 2025–2026 formulations, while extending pediatric authorization in defined circumstances. Expect procurement practices that prioritize these cohorts early in seasonal campaigns.
- Retail availability and payer interplay: Vaccines remain purchasable in retail markets in several jurisdictions, creating hybrid public‑private demand channels. Payers and retailers will become active negotiation partners for supplemental dosing programs and workplace immunization offerings.
- Supply reliability as a commercial lever: Governments and large buyers will increasingly prefer suppliers who can commit to durable, geographically distributed capacity and transparent lot‑release timelines. Contract terms will reflect this preference with tighter service level metrics and financial remedies for shortfalls.
Strategic imperatives for 2026 — recommended actions
Executives and investors must convert foresight into concrete actions. PW Consulting recommends the following prioritized moves for 2026:
- Embed variant scenario planning into core commercial forecasts. Maintain three live demand scenarios (baseline seasonal, episodic surges, and high‑vaccine‑coverage drives) and tie approval/legal milestones to contractual release triggers.
- Secure flexible manufacturing capacity via a mix of owned and contracted arrangements. Prioritize modular fill‑finish facilities and short‑term reserved capacity clauses to manage seasonal peaks without oversized fixed costs.
- Diversify technology exposure within portfolios. If a single technology dominates your current exposure, consider selective investments or licensing agreements in complementary platforms (e.g., protein subunit or inactivated vaccines) to manage market segmentation and access constraints.
- Negotiate outcomes‑based procurement where feasible. Offer risk‑sharing models that link price or volumes to epidemiologic triggers, which can unlock larger tenders while sharing downside between buyer and supplier.
- Invest in supply‑chain transparency and lot‑tracking capabilities. Buyers will demand traceability and rapid recall mechanisms; suppliers who can demonstrate end‑to‑end visibility will gain preferential access to public tenders.
- Prepare M&A and partnership playbooks now. Use 2026 as a consolidation window: target assets that bring localized manufacturing, regulatory registrations, or niche product differentiation rather than scale alone.
- Strengthen payer and retail channel strategies. With ongoing retail availability in major markets, build dedicated commercial models for pharmacy chains, workplace programs, and private pay segments to protect margin and share.
Risk matrix — what keeps us up at night
In 2026 management teams should focus on three high‑impact risks:
- Rapid antigenic drift that materially reduces vaccine effectiveness and forces off‑cycle reformulations.
- Procurement volatility from geopolitical stockpiling or rapid reallocation of supply to emergency hotspots.
- Price compression as competition between platform technologies and regional producers intensifies, squeezing margins for incumbent suppliers.
How PW Consulting’s report helps you act
Our report synthesizes the market’s macro trajectory with the tactical intelligence teams need to de‑risk 2026 plans: actionable checklists for procurement, commercial contracts and manufacturing, a prioritized target list for M&A and alliances, and downloadable templates you can use in negotiations immediately. It also includes interactive scenario models and an exposé of supplier concentration metrics to support board‑level discussions.
Next steps — where to get the full analysis
This release is intended as a strategic preview. To access the granular segmentation, regional demand breakdowns, company financial benchmarks and the full set of scenario model files, please visit the PW Consulting report landing page. The complete package contains the proprietary datasets and step‑by‑step implementation tools that senior commercial and operational teams will use to finalize 2026 budgets and contracting strategies.
Final note
2026 will not be a repeat of 2020 — it will be a year defined by strategic execution against a mature but still dynamic vaccine market. Organizations that pair scenario‑based foresight with decisive investments in flexible capacity, diversified technology exposure, and payer‑aligned commercial structures will convert market growth into sustainable advantage. PW Consulting’s Covid-19 Vaccine Market report is designed to be the playbook for that conversion.
For detailed analysis of this topic, please visit the official page: Covid-19 Vaccine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Blepharitis Market Hits USD 517 Million in 2025, Poised for 5.1% CAGR to Reach USD 730 Million by 2032
By pmarketresearch, 2026-06-30
PW Consulting: Blepharitis Market 2026 — Strategic Imperatives from Our Latest Industry Deep Dive
Executive snapshot
PW Consulting today releases a comprehensive industry briefing derived from our new Blepharitis Market report (base year: 2025; historical coverage: 2020–2025; forecast: 2026–2032). The global market has expanded steadily from roughly USD 405 million in 2020 to an estimated USD 517 million in 2025 and is projected to continue growing at a compound annual growth rate (CAGR) of about 5.1% through 2032, with market sizing extending toward the high single‑hundreds of millions by the end of the forecast window. For executives planning 2026 investments, product launches, or restructuring, this report translates macro momentum into actionable decisions while preserving the granular segmentation that underpins confident capital allocation.
Blepharitis Market
Why this matters for 2026 decisions
-
Clinical and commercial inflection: Therapeutic innovation and improved clinical recognition are converging to convert episodic symptom management into sustained care pathways. That transition changes the revenue model for manufacturers and the utilization model for payers and providers.
Blepharitis Market -
Payer dynamics are pivotal: Coverage and reimbursement strategy now drive adoption curves as much as clinical efficacy. The commercialization playbook that worked in an environment of symptomatic management no longer suffices for disease‑directed therapies with durable treatment claims.
Blepharitis Market -
Manufacturing and supply resilience influence margin levers: Scale economics and supplier risk are no longer back‑office concerns; they are primary strategic variables that determine the feasibility of volume‑driven launches.
-
Moderate market concentration leaves room for differentiated entrants: Our concentration analysis shows that the leading players capture a substantial share of the market, but not an insurmountable majority—creating opportunities for well‑targeted clinical or commercial differentiation.
What the report delivers — practical, transaction‑grade insight
This is not a catalogue of static numbers. PW Consulting’s Blepharitis Market report is structured as a decision toolkit for 2026 and beyond. Key deliverables include:
-
Robust market sizing and high‑granularity forecasts by therapeutic approach, presentation type, and distribution channel—built from primary interviews, claims analytics, and unit‑flow modeling.
-
Commercialization playbooks tailored to launch phase (early adoption → payer scale → international rollout), including DTC / HCP balance, sample economics, and specialty distribution options.
-
Payer access and reimbursement mapping that identifies friction points (e.g., prior authorization, step edits) and models the net price waterfall under alternative contracting scenarios.
-
Regulatory and IP roadmaps with win/loss implications for market exclusivity, biosimilar/generic entry timing, and international regulatory timelines.
-
Manufacturing & supply chain stress tests that quantify input cost sensitivity, capacity ramp requirements, and contingency cost of goods under different demand scenarios.
-
Scenario modeling and decision trees for M&A and licensing — highlighting which asset profiles (novel mechanism, durable IP, predictable payer economics) warrant premium valuation.
Competitive landscape — where incumbents and challengers are positioned
The competitive topology in blepharitis is shifting from a fragmented symptomatic market to one with clear innovators and pragmatic incumbents. Our analysis focuses on established ocular care companies and biotechnology challengers that have prioritized therapeutic differentiation, payer strategy, or manufacturing scale.
-
Tarsus Pharmaceuticals : First‑mover therapeutic differentiation in targeted demodex treatment has yielded rapid commercial traction and broad payer engagement. Tarsus’s strategy—accelerating direct‑to‑consumer awareness, expanding clinical development, and pursuing international registrations—creates a playbook other specialty developers are now emulating. The company’s sustained emphasis on payer contracting and patient access is a key case study in converting clinical novelty into durable revenue streams.
-
Allergan (AbbVie) : With established ophthalmic anti‑inflammatory and immunomodulatory assets, Allergan’s portfolio approach targets long‑term symptom control and chronic management pathways. Their commercial capability and established payer relationships make them a default partner or acquirer for late‑stage adjunctive technologies and diagnostics.
-
Novartis : Positioning established dry‑eye therapeutics within blepharitis care pathways highlights the strategic value of cross‑indication assets. Novartis’s footprint in specialty ophthalmology positions it to capture value where dry‑eye and blepharitis intersect.
-
Bausch Health , Santen , and Akorn : Each company represents a strategic archetype—targeted ocular care with differentiated formulations (Bausch), regional specialty leadership (Santen), and generic/supply continuity (Akorn). Collectively, they underscore the ongoing demand for both branded innovation and affordable, reliable symptom management solutions.
Market dynamics and risk vectors
Several forces will disproportionately influence 2026 outcomes:
-
Payer economics and net pricing: The net value equation—rebates, formulary positioning, and utilization management—will determine commercial scale more than list price alone. Negotiated discounts and contracting structures are now first‑order considerations for launch planning.
-
Access logistics and durable adherence: Prior authorization protocols, initial approval durations, and real‑world persistence patterns create discontinuities between prescriptions written and clinical outcomes achieved.
-
Regulatory and IP protection: Extended exclusivity windows for novel therapeutics offer a runway for return on investment, but international regulatory timelines and approval pathways remain heterogeneous—requiring bespoke strategy for each geography.
-
Supply and margin pressure: Scaling volumes materially affects margins and manufacturing risk. Firms that proactively secure supply chains and flex capacity will protect profitability as demand scales.
-
Competitive erosion and generics: The pathway from clinical success to commoditization is shortened in crowded therapeutic categories; differentiation beyond efficacy—such as delivery modality, diagnostics, or integrated services—will slow commoditization.
Strategic recommendations for 2026
For executives needing a concise action plan, our report synthesizes the above into prioritized moves that can be implemented within 6–12 months.
-
Manufacturers (novel therapeutics): Align launch investments to payer segmentation data: prioritize contracting and real‑world evidence generation ahead of full commercial roll‑out. Invest in patient support programs that shorten the time from prescription to sustained use.
-
Incumbent branded players: Leverage portfolio breadth to bundle therapeutic and supportive care offerings; explore co‑promotion and diagnostics partnerships to defend share as specialized entrants scale.
-
Generic suppliers and contract manufacturers: Use demand visibility to secure long‑lead raw materials and to optimize fill/finish capacity—margin resilience will be driven by cost predictability.
-
Private equity and strategic investors: Prioritize assets with clear payer economics and durable intellectual property or those that unlock meaningful cost synergies via manufacturing or distribution integration.
-
Healthcare providers and payers: Reconcile short‑term formulary savings with long‑term disease management outcomes; create streamlined prior authorization pathways for therapies with demonstrated cost‑offset potential.
Why PW Consulting — and what we are deliberately not disclosing in this release
Our analysis combines primary payer interviews, longitudinal claims analysis, proprietary unit‑flow modeling, and a detailed commercial benchmarking dataset to produce transaction‑grade advice. In keeping with our “trailer” approach—designed to provide strategic clarity while preserving the transactional value of granular intelligence—we have presented high‑confidence macro indicators and qualitative strategic insight here while withholding the detailed regional, type‑level, and treatment‑split tables that drive bespoke commercial strategies.
If you are evaluating entry, expansion, or divestiture in 2026, the difference between a good decision and a great one will be determined by that granularity: patient‑level utilization curves, payer net‑price waterfalls by channel, and time‑to‑full‑coverage models for specific geographies. These datasets and the accompanying scenario models are available in the full report and through PW Consulting’s advisory engagements.
Next steps
For companies, investors, and policy stakeholders preparing for 2026, the Blepharitis Market report is a practical roadmap: it identifies where to invest, where to defend, and where to wait for clarity. To access the full dataset, segmentation tables, and bespoke advisory options, please visit our report page or contact PW Consulting’s industry practice lead for a briefing tailored to your strategic objectives.
For detailed analysis of this topic, please visit the official page: Blepharitis Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecasts Cocoa Market to Rise from USD 215.0 Million in 2025 to USD 344.8 Million by 2032, Expanding at a 5.4% CAGR (2026–2032)
By pmarketresearch, 2026-06-30
Cocoa Market 2026 Outlook — Strategic Intelligence for Executive Decision‑Making
PW Consulting’s latest Cocoa Market report (base year 2025; historical window 2020–2025; forecast period 2026–2032) delivers a purpose-built intelligence package for senior executives, investors, and supply‑chain leaders who must make high‑stakes commercial and sustainability decisions in 2026. The market is recovering from near‑term volatility: our topline model shows a recovery from an estimated USD million 163.15 in 2020 to USD million 215.0 in 2025, with the market projected to reach approximately USD million 344.8 by 2032 under a median scenario (CAGR 2026–2032: 5.4%).
Cocoa Market
Why 2026 is an inflection year
-
Regulatory timing: The provisional postponement of the EU Deforestation Regulation (EUDR) enforcement for large operators until 30 December 2026 creates a narrow but critical window for supply‑chain remediation and compliance ramp‑up. Firms that treat this as an extra runway rather than an excuse for delay will gain durable advantage.
Cocoa Market -
Macro supply dynamics: Improved West African harvests and a stronger 2024/25 season (ICCO estimate: ~4.73 million tonnes) materially reshaped price expectations in early 2026, with cocoa bean prices easing as supply prospects improved. That change re‑orders commercial tradeoffs between stockholding, working capital, and procurement cadence.
Cocoa Market -
Policy fragmentation: Trade frictions are non‑negligible — recent tariff actions (notably retaliatory measures affecting some producing origins) compel re‑pricing of origin risk and force re‑evaluation of sourcing lanes and customs exposure.
-
Industrial response: Leading processors and traders are accelerating capex and innovation — from large warehouse builds to renewable energy investments in origin and logistics — shifting cost curves and enabling new commercial models (e.g., origin‑integrated services, forward warehousing, and sustainability‑linked contracting).
What PW Consulting’s Cocoa Market report gives you — operationally focused
This is a strategic “hands‑on” study. We purposely present market structure and dynamics at a level that supports immediate action while reserving proprietary granular splits to the full product. Highlights include:
-
Executive dashboards and KPIs for 2026 planning — market size by year (2020–2025 observed; 2026–2032 forecast), headline CAGR scenarios, and sensitivity ranges tailored to price, production, and policy shocks.
-
Scenario playbooks — three evidence‑based scenarios (base, upside, downside) with decision triggers and contingency plans for procurement, inventory, and hedging in volatile price windows.
-
Compliance and traceability playbook — step‑by‑step remediation routes to meet EUDR expectations, including supplier engagement protocols, audit roadmaps, and costed options (internal trace systems vs. third‑party verification programs).
-
Supplier risk mapping and origin stress tests — a prioritized taxonomy of origin, logistics, and political risks with recommended mitigation levers (sourcing diversification thresholds, contract structuring, and origin partnerships).
-
Commercial playbooks — pricing elasticities, cost‑to‑serve models for different channels, and an M&A screening matrix that flags targets and rationales for consolidation or vertical integration given current concentration dynamics.
-
Innovation and product strategy frameworks — how to evaluate non‑cocoa alternatives and premium cocoa positioning given changing raw material economics and consumer sustainability expectations.
Market structure takeaways and strategic implications
Two macro features stand out. First, the market is growing and re‑rating: after the 2020–2025 volatility the mid‑term outlook—captured by a 5.4% CAGR in our base forecast—supports continued investment in capacity, logistics, and product innovation. Second, the competitive map remains fragmented; the top three and top five players together account for a minority share of total capacity, leaving space for regional champions, agile grinders, and differentiated specialty players to expand.
Implications for executives:
-
Growth matters, but so does positioning: a market that grows at mid‑single digits still rewards firms that control margin drivers (origin premiums, processing yields, value‑added derivatives) rather than those chasing volume alone.
-
Fragmentation opens M&A and partnership windows, particularly for firms that can deliver traceability, low‑carbon claims, or cost reductions through logistics scale.
-
Regulatory and trade uncertainty means that commercial flexibility (contracting windows, optionality in logistics) is as valuable as scale.
Competitive landscape: what the leading players are doing now
The report profiles the operational strategies and strategic moves of the principal global actors — from multinational grinders and ingredient manufacturers to origin‑specialist traders. A synthesis of observed behavior and lessons for 2026 follows:
-
Barry Callebaut (Zurich, Switzerland) — continues to play at the intersection of product innovation and supply‑chain scale. Recent moves include launches of non‑cocoa ingredient ranges to broaden formulation options and a major warehouse partnership in Asia to secure logistics capacity. Strategic lesson: pairing customer‑facing innovation with upstream logistics investments strengthens both moat and margin optionality.
-
Cargill (Minneapolis, USA) — investing heavily in decarbonization and origin‑level infrastructure (biomass boilers, solar power, electrified logistics). The focus is on reducing operating risk and meeting increasingly strict sustainability criteria demanded by large food manufacturers. Strategic lesson: operational resilience and lower scope‑2/3 footprints are becoming competitive differentiators.
-
ofi (Olam Food Ingredients, Singapore) — doubling down on traceable sourcing and integrated origin processing to offer assured supply chains to corporate buyers. Strategic lesson: origin control and transparency are direct responses to both EUDR timing and buyer demand.
-
Ecom Agroindustrial (Switzerland) , Sucden (France) , Touton (France) , Guan Chong (Malaysia) , and Cémoi (France) — collectively illustrate different routes to scale: horizontal trading networks, regional grinding hubs, specialty premium positioning, and origin partnerships. Strategic lesson: there is no single playbook; the right route depends on end‑market focus (mass vs. premium), capital access, and supply‑chain control.
Recent company and industry developments (illustrative):
-
May 2026 — Barry Callebaut introduced new non‑cocoa ingredient lines at a major confectionery expo, signaling product diversification strategies among manufacturers.
-
September 2025 — large warehousing investments in Asia by a leading processor in partnership with a global shipping operator demonstrate the premium placed on logistics control.
-
July 2025 — major processors announced origin‑level renewable energy and electrification projects, highlighting a shift to operational decarbonization as a cost and compliance posture.
Recommended 2026 priorities for corporate leaders
Our consulting engagements with buyers, processors, and investors in H1–H2 2026 converge on a short list of high‑impact actions:
-
Accelerate EUDR readiness programs now — treat the postponement as transitional grace, not a deferral. Prioritize supplier mapping, legal review of contractual indemnities, and an evidence‑based verification path for high‑risk supply lanes.
-
Re‑test procurement scenarios in light of softer early‑2026 prices and the ICCO production backdrop. Update hedging and inventory policy to balance carry costs against supply security and margin opportunities.
-
Invest selectively in logistics and storage optionality — capacity near demand centers and secure warehousing at origin reduce exposure to spot volatility and provide tactical arbitrage opportunities.
-
Embed sustainability into commercial deals — buyers that can offer multi‑year contracts with verified premiums will secure priority allocation in origin seasons where buyers are capacity constrained.
-
Evaluate adjacencies: pilot non‑cocoa ingredient formulations and premium cocoa lines in parallel. Use consumer sensory and cost modelling to decide scale‑up timing vs. opportunistic sourcing.
-
Pursue targeted consolidations or strategic partnerships that address capability gaps (traceability, processing yield, distribution) rather than pursuing scale for scale’s sake.
How to use the report in your 2026 planning cycle
Our report is structured for immediate operationalization within the annual planning calendar:
-
Quarterly procurement playbooks and negotiation scripts aligned to each scenario.
-
Board‑level briefing notes that summarize trigger points for capex or M&A decisions.
-
Integrated risk dashboards that tie exposure to EUDR, tariffs, and origin supply shocks to P&L and balance sheet sensitivities.
Conclusion — the strategic edge for 2026
The cocoa market in 2026 is resolutely more predictable on some fronts and more uncertain on others: production recovery and easing prices reduce short‑term supply stress, while regulatory timing, trade policy, and sustainability demands raise the cost of being late. Firms that combine commercially disciplined procurement, targeted investments in logistics and low‑carbon operations, and fast compliance execution will translate the market’s 5.4% mid‑term growth into durable competitive advantage.
PW Consulting’s Cocoa Market report synthesizes the quantitative forecast, scenario toolkits, and pragmatic playbooks that senior teams need to convert insight into action. Consistent with our “trailer” approach, this release highlights the strategic frames, methods, and implications while preserving the report’s proprietary granular regional, type, and application splits — and company‑level benchmarks — for the full product.
To access the full set of data tables, regional and application breakdowns, company bench‑marks, and executable templates for 2026 planning, please download the complete report from PW Consulting’s Cocoa practice page.
For detailed analysis of this topic, please visit the official page: Cocoa Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com