

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Forecasts Cocoa Market to Rise from USD 215.0 Million in 2025 to USD 344.8 Million by 2032, Expanding at a 5.4% CAGR (2026–2032)

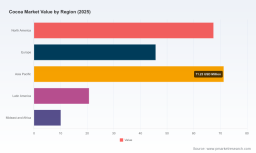
Cocoa Market 2026 Outlook — Strategic Intelligence for Executive Decision‑Making
PW Consulting’s latest Cocoa Market report (base year 2025; historical window 2020–2025; forecast period 2026–2032) delivers a purpose-built intelligence package for senior executives, investors, and supply‑chain leaders who must make high‑stakes commercial and sustainability decisions in 2026. The market is recovering from near‑term volatility: our topline model shows a recovery from an estimated USD million 163.15 in 2020 to USD million 215.0 in 2025, with the market projected to reach approximately USD million 344.8 by 2032 under a median scenario (CAGR 2026–2032: 5.4%).
Cocoa Market
Why 2026 is an inflection year
-
Regulatory timing: The provisional postponement of the EU Deforestation Regulation (EUDR) enforcement for large operators until 30 December 2026 creates a narrow but critical window for supply‑chain remediation and compliance ramp‑up. Firms that treat this as an extra runway rather than an excuse for delay will gain durable advantage.
Cocoa Market -
Macro supply dynamics: Improved West African harvests and a stronger 2024/25 season (ICCO estimate: ~4.73 million tonnes) materially reshaped price expectations in early 2026, with cocoa bean prices easing as supply prospects improved. That change re‑orders commercial tradeoffs between stockholding, working capital, and procurement cadence.
Cocoa Market -
Policy fragmentation: Trade frictions are non‑negligible — recent tariff actions (notably retaliatory measures affecting some producing origins) compel re‑pricing of origin risk and force re‑evaluation of sourcing lanes and customs exposure.
-
Industrial response: Leading processors and traders are accelerating capex and innovation — from large warehouse builds to renewable energy investments in origin and logistics — shifting cost curves and enabling new commercial models (e.g., origin‑integrated services, forward warehousing, and sustainability‑linked contracting).
What PW Consulting’s Cocoa Market report gives you — operationally focused
This is a strategic “hands‑on” study. We purposely present market structure and dynamics at a level that supports immediate action while reserving proprietary granular splits to the full product. Highlights include:
-
Executive dashboards and KPIs for 2026 planning — market size by year (2020–2025 observed; 2026–2032 forecast), headline CAGR scenarios, and sensitivity ranges tailored to price, production, and policy shocks.
-
Scenario playbooks — three evidence‑based scenarios (base, upside, downside) with decision triggers and contingency plans for procurement, inventory, and hedging in volatile price windows.
-
Compliance and traceability playbook — step‑by‑step remediation routes to meet EUDR expectations, including supplier engagement protocols, audit roadmaps, and costed options (internal trace systems vs. third‑party verification programs).
-
Supplier risk mapping and origin stress tests — a prioritized taxonomy of origin, logistics, and political risks with recommended mitigation levers (sourcing diversification thresholds, contract structuring, and origin partnerships).
-
Commercial playbooks — pricing elasticities, cost‑to‑serve models for different channels, and an M&A screening matrix that flags targets and rationales for consolidation or vertical integration given current concentration dynamics.
-
Innovation and product strategy frameworks — how to evaluate non‑cocoa alternatives and premium cocoa positioning given changing raw material economics and consumer sustainability expectations.
Market structure takeaways and strategic implications
Two macro features stand out. First, the market is growing and re‑rating: after the 2020–2025 volatility the mid‑term outlook—captured by a 5.4% CAGR in our base forecast—supports continued investment in capacity, logistics, and product innovation. Second, the competitive map remains fragmented; the top three and top five players together account for a minority share of total capacity, leaving space for regional champions, agile grinders, and differentiated specialty players to expand.
Implications for executives:
-
Growth matters, but so does positioning: a market that grows at mid‑single digits still rewards firms that control margin drivers (origin premiums, processing yields, value‑added derivatives) rather than those chasing volume alone.
-
Fragmentation opens M&A and partnership windows, particularly for firms that can deliver traceability, low‑carbon claims, or cost reductions through logistics scale.
-
Regulatory and trade uncertainty means that commercial flexibility (contracting windows, optionality in logistics) is as valuable as scale.
Competitive landscape: what the leading players are doing now
The report profiles the operational strategies and strategic moves of the principal global actors — from multinational grinders and ingredient manufacturers to origin‑specialist traders. A synthesis of observed behavior and lessons for 2026 follows:
-
Barry Callebaut (Zurich, Switzerland) — continues to play at the intersection of product innovation and supply‑chain scale. Recent moves include launches of non‑cocoa ingredient ranges to broaden formulation options and a major warehouse partnership in Asia to secure logistics capacity. Strategic lesson: pairing customer‑facing innovation with upstream logistics investments strengthens both moat and margin optionality.
-
Cargill (Minneapolis, USA) — investing heavily in decarbonization and origin‑level infrastructure (biomass boilers, solar power, electrified logistics). The focus is on reducing operating risk and meeting increasingly strict sustainability criteria demanded by large food manufacturers. Strategic lesson: operational resilience and lower scope‑2/3 footprints are becoming competitive differentiators.
-
ofi (Olam Food Ingredients, Singapore) — doubling down on traceable sourcing and integrated origin processing to offer assured supply chains to corporate buyers. Strategic lesson: origin control and transparency are direct responses to both EUDR timing and buyer demand.
-
Ecom Agroindustrial (Switzerland) , Sucden (France) , Touton (France) , Guan Chong (Malaysia) , and Cémoi (France) — collectively illustrate different routes to scale: horizontal trading networks, regional grinding hubs, specialty premium positioning, and origin partnerships. Strategic lesson: there is no single playbook; the right route depends on end‑market focus (mass vs. premium), capital access, and supply‑chain control.
Recent company and industry developments (illustrative):
-
May 2026 — Barry Callebaut introduced new non‑cocoa ingredient lines at a major confectionery expo, signaling product diversification strategies among manufacturers.
-
September 2025 — large warehousing investments in Asia by a leading processor in partnership with a global shipping operator demonstrate the premium placed on logistics control.
-
July 2025 — major processors announced origin‑level renewable energy and electrification projects, highlighting a shift to operational decarbonization as a cost and compliance posture.
Recommended 2026 priorities for corporate leaders
Our consulting engagements with buyers, processors, and investors in H1–H2 2026 converge on a short list of high‑impact actions:
-
Accelerate EUDR readiness programs now — treat the postponement as transitional grace, not a deferral. Prioritize supplier mapping, legal review of contractual indemnities, and an evidence‑based verification path for high‑risk supply lanes.
-
Re‑test procurement scenarios in light of softer early‑2026 prices and the ICCO production backdrop. Update hedging and inventory policy to balance carry costs against supply security and margin opportunities.
-
Invest selectively in logistics and storage optionality — capacity near demand centers and secure warehousing at origin reduce exposure to spot volatility and provide tactical arbitrage opportunities.
-
Embed sustainability into commercial deals — buyers that can offer multi‑year contracts with verified premiums will secure priority allocation in origin seasons where buyers are capacity constrained.
-
Evaluate adjacencies: pilot non‑cocoa ingredient formulations and premium cocoa lines in parallel. Use consumer sensory and cost modelling to decide scale‑up timing vs. opportunistic sourcing.
-
Pursue targeted consolidations or strategic partnerships that address capability gaps (traceability, processing yield, distribution) rather than pursuing scale for scale’s sake.
How to use the report in your 2026 planning cycle
Our report is structured for immediate operationalization within the annual planning calendar:
-
Quarterly procurement playbooks and negotiation scripts aligned to each scenario.
-
Board‑level briefing notes that summarize trigger points for capex or M&A decisions.
-
Integrated risk dashboards that tie exposure to EUDR, tariffs, and origin supply shocks to P&L and balance sheet sensitivities.
Conclusion — the strategic edge for 2026
The cocoa market in 2026 is resolutely more predictable on some fronts and more uncertain on others: production recovery and easing prices reduce short‑term supply stress, while regulatory timing, trade policy, and sustainability demands raise the cost of being late. Firms that combine commercially disciplined procurement, targeted investments in logistics and low‑carbon operations, and fast compliance execution will translate the market’s 5.4% mid‑term growth into durable competitive advantage.
PW Consulting’s Cocoa Market report synthesizes the quantitative forecast, scenario toolkits, and pragmatic playbooks that senior teams need to convert insight into action. Consistent with our “trailer” approach, this release highlights the strategic frames, methods, and implications while preserving the report’s proprietary granular regional, type, and application splits — and company‑level benchmarks — for the full product.
To access the full set of data tables, regional and application breakdowns, company bench‑marks, and executable templates for 2026 planning, please download the complete report from PW Consulting’s Cocoa practice page.
For detailed analysis of this topic, please visit the official page: Cocoa Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com