

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Forecast: Melt Pump Market to Expand at a 5.8% CAGR from 2026–2032

Melt Pump Market Outlook 2026: Strategic Imperatives for Resilient Growth
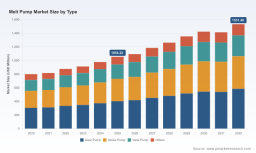
PW Consulting’s latest Melt Pump Market report (base year 2025) frames the sector at a pivotal inflection point for 2026 decision-makers. After recovering from a measured post-pandemic rebound (the market expanded from roughly USD 800 Million in 2020 to about USD 1,054.2 Million in 2025), our forecast analysis projects continued expansion through 2032, with a mid-single-digit compound annual growth rate of 5.8% across the 2026–2032 horizon. That trajectory, and the forces driving it, create immediate strategic choices for OEMs, processors, investors and procurement teams. This release highlights the report’s high-value takeaways and the practical actions leaders should prioritize in 2026; detailed segment-level tables, vendor scorecards and downloadable models are intentionally reserved for the full report to preserve competitive advantage and encourage direct subscription.
Melt Pump Market
Why this matters in 2026: Decisions that determine market share
-
Capital allocation: With the melt pump market on a steady growth path, capital budgeting for 2026 must balance modernization of extrusion lines against tighter ROI horizons and higher upfront costs for precision equipment.
Melt Pump Market -
Supplier strategy: Market concentration data show a landscape where the top three players hold a modest share and the top five capture roughly 60% of market influence. For buyers, this means a mix of global OEM strength and regional competitive pressure—creating room for both strategic partnerships and tactical sourcing.
Melt Pump Market -
Product roadmap and R&D: Advances in low NPSHr designs, low-shear profiles and higher-pressure capability are the differentiators that will matter to processors handling recycled and bio-based polymers in 2026.
-
Sustainability and compliance: Stricter environmental regulations in mature markets are already shaping melt pump requirements—pressure stability, reduced scrap and compatibility with higher recycled content are procurement must-haves.
-
Aftermarket and service models: The expanding installed base through 2032 makes aftermarket services, predictive maintenance and consumable replacement a durable revenue and margin pool.
What the report delivers: actionable, practitioner-focused analysis
-
Executive synthesis: Market sizing, macro drivers and a concise strategic checklist for 2026 investment and procurement decisions.
-
Top-line market model: Time-series market size from 2020 through 2032 (base year 2025), with scenario runs under conservative, base and accelerated demand assumptions and a clear sensitivity analysis around price, throughput and material mix.
-
Demand- and supply-side dynamics: Detail on cost drivers (material and labour), freight and logistics impacts, and regulatory tailwinds shaping product specs and customer requirements.
-
Technology benchmarking: Functional performance matrices for pressure, shear, thermal management and sensor integration, plus a technology adoption timeline that aligns with processor needs for recycled and bio-polymers.
-
Competitive intelligence: Qualitative and quantitative vendor profiles, value-chain maps, go-to-market coverage and pragmatic supplier selection frameworks (TCO, risk-adjusted scorecards).
-
Commercial playbooks: Procurement templates, spare-parts inventory policies and aftermarket service pricing strategies to protect margin while improving uptime.
-
M&A and partnership lens: Target capability maps and deal archetypes for entrants seeking scale, access to regional channels, or intellectual property in precision melt technology.
-
Tools and annexes: Downloadable models, interview transcripts, primary survey data and a glossary for cross-functional teams.
Competitive landscape — who to watch and why
The Melt Pump sector combines established global engineering leaders with nimble regional manufacturers. Our qualitative assessment identifies distinct positioning strategies and near-term implications:
-
Engineering incumbents: Firms such as Nordson Corporation and Maag Pump Systems retain technology leadership through focused product families that emphasize stabilization, low-shear flow and high-pressure capability. Their recent product upgrades and demonstrations underscore a strategy of performance differentiation for demanding extrusion and compounding lines.
-
Systems integrators and extruder specialists: Coperion, Kobe Steel (Kobelco) and others leverage broader extrusion portfolios (twin-screw solutions, pelletizing systems) to drive melt pump adoption as part of integrated line solutions—an attractive route for purchasers seeking single-vendor responsibility for throughput guarantees.
-
Precision and niche providers: European precision houses (e.g., WITTE) and North American engineering brands position around specialized applications—filament extrusion, high-viscosity polymers and controlled metering—where tolerances and material stability command premium pricing.
-
Regional value players: A cadre of manufacturers in Asia (mid-sized and local champions) compete aggressively on price and fast local support. Their presence affects lead times, part costs and aftermarket economics, especially for cost-sensitive processors and converters.
-
Service and aftermarket specialists: Independent service providers and divisions within larger industrial groups are growing the aftermarket, aftermarket sensor upgrades and retrofit offerings—creating an adjacent margin pool that matters for 2026 unit economics.
Taken together, the market shows moderate concentration: our analysis places the three largest firms at a material but not dominant share of the market and the five largest players at roughly 60% control—enough to influence standards and price points, yet leaving substantial opportunity for focused challengers. For executives, these dynamics argue for differentiated positioning (technology, service or cost leadership) rather than attempt to outspend incumbents on scale alone.
Key market dynamics and their 2026 implications
-
Labour & automation: Increasing adoption of automated extruder lines reduces direct labour needs but raises the bar for control systems and pump integration. Buyers should prioritize suppliers with robust control interoperability and remote diagnostics.
-
Material costs and circularity: Precision melt pumps often require higher initial capex, particularly when processing recycled feeds. Capital planning must include lifecycle cost models that capture throughput loss, scrap rates and rework avoided by more stable melt delivery.
-
Regulatory pressure: New environmental mandates in mature markets are tightening acceptable scrap rates and dictating higher process stability. This elevates melt pump specifications from “nice-to-have” to procurement criteria with compliance risk attached.
-
Freight and supply chain volatility: Rising shipping costs for precision-engineered components are accelerating onshore or nearshore sourcing strategies for spare parts and service inventory.
-
Sustainability-driven product demand: Consumer-packaging trends demanding higher recycled content create differentiated demand pockets for melt pumps capable of maintaining throughput with variable input quality—an R&D priority in 2026.
A pragmatic strategic playbook for 2026
-
Adopt a TCO procurement framework: Evaluate suppliers not only on unit price but on uptime guarantees, spare-parts availability, service SLA and retrofit capability for recycled materials.
-
Pursue modular investments: Prioritize melt pump upgrades that are modular and retrofittable to protect existing capex while enabling incremental performance gains.
-
Dual-source critical components: Mitigate freight and geographic risk by combining global OEMs for performance-critical units with vetted regional manufacturers for spares and quick-turn needs.
-
Invest in sensorized pumps and analytics: Push for predictive maintenance pilots in 2026 to convert uptime improvements into quantifiable savings—ideal candidates for capex-to-OPEX shifts or managed-services pilots.
-
Align R&D to recycled feedstocks: Re-prioritize development roadmaps to include low-shear options and thermal control strategies tuned for variability in recycled polymers.
-
Consider targeted M&A and partnerships: Buyers seeking to accelerate capability should evaluate tuck-ins that add service networks, aftermarket parts platforms or complementary extrusion technologies.
Methodology and confidence
The body of work behind the report integrates primary interviews with OEMs, processors and service providers, proprietary shipment and vendor revenue reconciliation, and bottom-up demand modeling calibrated to observable extrusion capacity. Historical series (2020–2025) and the base year 2025 feed into a scenario-driven forecast for 2026–2032, underpinned by a 5.8% CAGR in the base case. Each forecast node includes sensitivity bands and documented assumptions for pricing, utilization and regulatory impact. As noted, detailed tables, segment-level splits and vendor scorecards are excluded from this overview to preserve the commercial fidelity of the full dataset.
Next steps — how to use this analysis in 2026 planning
-
Procurement leaders should request the full report’s supplier scorecards to redesign supplier panels and renegotiate SLAs with an emphasis on lifecycle value.
-
R&D and product teams should use our technology comparisons to prioritize low-NPSHr, low-shear pump designs and integration with Industry 4.0 telemetry in their 2026 roadmaps.
-
Corporate strategists and corporate development teams should leverage the M&A archetypes in the full study to identify bolt-on acquisition targets that accelerate aftermarket or regional service capabilities.
PW Consulting’s Melt Pump Market report is built to be a decision-support tool for 2026: it translates market growth, supplier dynamics and technological change into practical, prioritized actions. To access the full dataset, segment-level revenue tables, vendor scorecards and the downloadable forecasting model, please follow the link in our press kit. The summary here is designed to demonstrate the report’s depth while reserving the granular intelligence that will inform your next procurement cycle or investment due diligence.
For detailed analysis of this topic, please visit the official page: Melt Pump Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com