

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Predicts 3D Weaving Fabrics Market to Hit USD 266.5 Million by 2032

3D Weaving Fabrics Market 2026 Strategic Outlook — PW Consulting Intelligence Brief
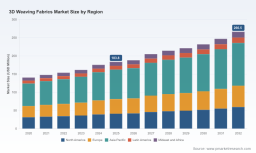
As manufacturers, OEMs, and investors prepare strategic plans for 2026, the PW Consulting 3D Weaving Fabrics Market report offers a focused, executable intelligence package to guide high-stakes decisions. Grounded in a 2020–2025 historical dataset and an explicit 2026–2032 forecast horizon, the study quantifies a steady expansion trajectory (5.55% CAGR across the forecast window) and traces the structural forces shaping demand, supply, technology adoption, and regulatory risk. The market reached approximately USD 183.8 Million in our base year (2025) and is projected to grow to roughly USD 266.5 Million by 2032 — a profile consistent with a maturing, innovation-led materials subsector that is becoming mission-critical across mobility, protective, and performance applications.
3D Weaving Fabrics Market
Why this report matters for 2026 decision cycles
- Capital allocation: validates near- and medium-term ROI expectations for capacity expansion, machine investment, and automation projects against a credible CAGR and scenario set.
- Supply chain strategy: informs raw material contracting (notably carbon fiber and engineered polymers), geographic sourcing, and inventory hedging in light of regulatory and export-control dynamics.
- Product and technology roadmaps: helps prioritize R&D bets (near-net shaping, integrated reinforcements, hybrid knit-weave hybrids) by mapping technology readiness to addressable end markets.
- M&A and partnerships: identifies strategic windows for bolt-on acquisitions and co-development agreements where market concentration and capability gaps align with corporate objectives.
What PW Consulting’s 3D Weaving Fabrics Market report contains
- Full historical time series (2020–2025) and a granular forecast model (2026–2032) — inclusive of base-case, upside, and downside scenarios.
- Demand-side segmentation by geography, fabric architecture, and end-use application, with trend narratives and market sizing at the aggregate level. (Note: the press summary intentionally omits granular segment-level figures to preserve the report’s data value.)
- Comprehensive supply-side mapping: manufacturers, machine vendors, converter networks, and component suppliers, with capacity maps and utilization stress tests.
- Technology assessment and TRL-style positioning for 3D weaving variants, spacers, and hybrid constructions, including manufacturability and scale-up risk matrices.
- Raw-material and price sensitivity analysis, supplier risk indices, and contract negotiation playbooks for carbon fiber and specialty polymer inputs.
- Regulatory, standards, and trade policy impact assessment — with country-level implementation scenarios and compliance mitigation strategies.
- Competitive benchmarking: revenue-agnostic capability profiles, commercialization roadmaps, and potential M&A candidate scoring.
- Executive 90/180/365-day action plans tailored to buyers, suppliers, and investors.
Data-driven strategic takeaways for 2026
Growth will be steady rather than meteoric. The mid-single-digit CAGR we model reflects expanding use of 3D woven architectures where performance and integration advantages justify premium pricing — notably in structural composites, protective systems, and integrated apparel. That said, growth will be uneven by application and region as OEM adoption, regulatory shifts, and raw-material dynamics reorient supplier economics.
3D Weaving Fabrics Market
- Demand katalysts: system-level benefits (weight reduction, through-thickness reinforcement, fewer secondary bonding steps) are accelerating adoption in composites-heavy segments. Expect sustained traction in automotive lightweighting, performance sports equipment, and industrial protective gear, with new use-cases emerging around multifunctional wearables and protective apparel.
- Supply and concentration: market concentration remains modest — our concentration metrics point to a fragmented supplier base with room for consolidation. This creates arbitrage for strategic acquirers and risks for firms that rely on a narrow supplier set.
- Raw-material posture: carbon-fiber pricing has shown relative stability into 2025–2026 at key grades, but supply and lead-time volatility persists for specialty formulations. Buyers should adopt staged volume commitments and explore material substitution pathways where technical requirements permit.
- Regulatory and trade friction: recent policy moves — such as India’s expanded certification requirements for weaving equipment and updates to the U.S. Commerce Control List classifying multidirectional weaving machines — materially affect where capital can be deployed, what equipment can be imported, and how IP-protected machine architectures are traded. These constraints argue for diversified manufacturing footprints, local partnership arrangements, and proactive compliance planning.
Competitive landscape: reading the players and their strategic plays
The ecosystem is populated by specialized innovators, regional champions, and converters who combine design know-how with composite systems integration. Key strategic archetypes observed include pure-play technology licensors, vertically integrated producers, converter-specialists, and machine vendors enabling on-site capability expansion.
3D Weaving Fabrics Market
- Technology-first developers — firms like the Belgium-based developer known for its 3D weaving technology are positioned as technology originators targeting composites and technical-application niches. For alliances, these players are attractive R&D and OEM partners.
- Performance-material specialists — manufacturers from East Asia producing engineered 3D carbon, fiberglass, and UHMWPE constructions address ballistic, industrial, and hybrid-composite markets. Their strengths are cost-competitive scale and engineered fiber expertise; their strategic moves typically emphasize vertical integration and export-led growth.
- Converter and composite systems players — industry converters focused on carbon-fibre 3D textiles serve aerospace, wind, marine, and automotive customers. These firms compete on end-to-end qualification capability and supply security rather than raw price alone.
- Innovative knitted/woven hybrid players — companies introducing knitted 3D solutions (including spacer and seamless functional platforms) are pushing into apparel and protective gear, leveraging textile design to embed functionality (reinforcements, pockets, thermal control) without heavy secondary assembly.
- Regional production specialists — midsized firms with adjacent capabilities (spacer fabrics, woven composites) serve local OEM clusters. They are preferred partners for localized programs and rapid prototyping.
Recent industry moves provide a window into strategic direction. Notable examples include the commercial introduction of a 3D weaving platform enabling seamless performance apparel with integrated reinforcements, trade-show-led product demonstrations of film-infused near-net shapes and thermal protection systems, and machine vendors showcasing 3D weaving capability at regional technical textile shows. These signals emphasize two persistent themes: (1) manufacturers are prioritizing manufacturable integration (near-net shaping, in-line joining) and (2) visibility at technical venues is being used to accelerate OEM qualification cycles.
Regulatory and operational risk matrix
- Machine and technology export controls: the classification of multidirectional, multidimensional weaving machines under expanded export control regimes increases the complexity of cross-border equipment procurement and licensed manufacturing relationships. This elevates the value of domestic machine capability and local partnerships in sensitive jurisdictions.
- Standards and certification: new certification regimes for weaving and embroidery machinery in select markets introduce lead-time and documentation burdens for equipment OEMs and end users — companies will need to front-load compliance tasks into 2026 CAPEX planning.
- Input volatility: while average selling prices for chosen carbon-fibre grades have been stable, supply concentration for high-modulus and specialty grades can create tight windows for qualification-linked sourcing; strategic stocks or multi-sourcing agreements mitigate production risk.
Practical 90/180/365-day playbook for executives
- Next 90 days — perform a rapid supply-security audit (raw materials + machine vendors), initiate compliance reviews for anticipated export or import constraints, and launch two pilot co-development tests with candidate 3D weaving partners to validate performance claims and lead times.
- Next 180 days — commit to at least one scaling path: either secure long-lead time equipment with staged commissioning, or finalize a localized contract manufacturing agreement. Begin formal due diligence on acquisition targets that close capability gaps (converter capacity, machine know-how, or regional presence).
- Next 365 days — operationalize a productization pipeline for 3D-woven-enabled offerings (from design to qualification), lock multi-year strategic supply contracts with tiered pricing, and roll out a blended sourcing strategy that hedges both material and regulatory risk.
How PW Consulting’s report unlocks value
This report is designed as an execution toolkit: not only does it provide verified historical and forecasted market sizing (2020–2032) and a clear CAGR for planning, it maps the practical levers that move margin and time-to-market. For corporate strategists, procurement leads, and private-equity teams, the intelligence enables confident allocation of capital and prioritization of integration vs. partnership models — while preserving flexibility around equipment strategy and IP exposure.
Next steps
PW Consulting’s full report contains the proprietary segment-level breakdowns, detailed company capability matrices, supplier scorecards, and interactive forecasting models that executives need to finalize 2026 plans. The summary above intentionally omits those granular figures to preserve the actionable intelligence contained in the full deliverable. For access to the complete dataset, scenario workbooks, and bespoke advisory engagements tailored to your portfolio or operations, please visit our report page or contact PW Consulting’s advisory desk to arrange a briefing and data license.
For detailed analysis of this topic, please visit the official page: 3D Weaving Fabrics Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com