

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Global Blepharitis Market Hits USD 517 Million in 2025, Poised for 5.1% CAGR to Reach USD 730 Million by 2032

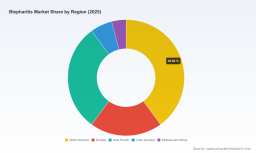
PW Consulting: Blepharitis Market 2026 — Strategic Imperatives from Our Latest Industry Deep Dive
Executive snapshot
PW Consulting today releases a comprehensive industry briefing derived from our new Blepharitis Market report (base year: 2025; historical coverage: 2020–2025; forecast: 2026–2032). The global market has expanded steadily from roughly USD 405 million in 2020 to an estimated USD 517 million in 2025 and is projected to continue growing at a compound annual growth rate (CAGR) of about 5.1% through 2032, with market sizing extending toward the high single‑hundreds of millions by the end of the forecast window. For executives planning 2026 investments, product launches, or restructuring, this report translates macro momentum into actionable decisions while preserving the granular segmentation that underpins confident capital allocation.
Blepharitis Market
Why this matters for 2026 decisions
-
Clinical and commercial inflection: Therapeutic innovation and improved clinical recognition are converging to convert episodic symptom management into sustained care pathways. That transition changes the revenue model for manufacturers and the utilization model for payers and providers.
Blepharitis Market -
Payer dynamics are pivotal: Coverage and reimbursement strategy now drive adoption curves as much as clinical efficacy. The commercialization playbook that worked in an environment of symptomatic management no longer suffices for disease‑directed therapies with durable treatment claims.
Blepharitis Market -
Manufacturing and supply resilience influence margin levers: Scale economics and supplier risk are no longer back‑office concerns; they are primary strategic variables that determine the feasibility of volume‑driven launches.
-
Moderate market concentration leaves room for differentiated entrants: Our concentration analysis shows that the leading players capture a substantial share of the market, but not an insurmountable majority—creating opportunities for well‑targeted clinical or commercial differentiation.
What the report delivers — practical, transaction‑grade insight
This is not a catalogue of static numbers. PW Consulting’s Blepharitis Market report is structured as a decision toolkit for 2026 and beyond. Key deliverables include:
-
Robust market sizing and high‑granularity forecasts by therapeutic approach, presentation type, and distribution channel—built from primary interviews, claims analytics, and unit‑flow modeling.
-
Commercialization playbooks tailored to launch phase (early adoption → payer scale → international rollout), including DTC / HCP balance, sample economics, and specialty distribution options.
-
Payer access and reimbursement mapping that identifies friction points (e.g., prior authorization, step edits) and models the net price waterfall under alternative contracting scenarios.
-
Regulatory and IP roadmaps with win/loss implications for market exclusivity, biosimilar/generic entry timing, and international regulatory timelines.
-
Manufacturing & supply chain stress tests that quantify input cost sensitivity, capacity ramp requirements, and contingency cost of goods under different demand scenarios.
-
Scenario modeling and decision trees for M&A and licensing — highlighting which asset profiles (novel mechanism, durable IP, predictable payer economics) warrant premium valuation.
Competitive landscape — where incumbents and challengers are positioned
The competitive topology in blepharitis is shifting from a fragmented symptomatic market to one with clear innovators and pragmatic incumbents. Our analysis focuses on established ocular care companies and biotechnology challengers that have prioritized therapeutic differentiation, payer strategy, or manufacturing scale.
-
Tarsus Pharmaceuticals : First‑mover therapeutic differentiation in targeted demodex treatment has yielded rapid commercial traction and broad payer engagement. Tarsus’s strategy—accelerating direct‑to‑consumer awareness, expanding clinical development, and pursuing international registrations—creates a playbook other specialty developers are now emulating. The company’s sustained emphasis on payer contracting and patient access is a key case study in converting clinical novelty into durable revenue streams.
-
Allergan (AbbVie) : With established ophthalmic anti‑inflammatory and immunomodulatory assets, Allergan’s portfolio approach targets long‑term symptom control and chronic management pathways. Their commercial capability and established payer relationships make them a default partner or acquirer for late‑stage adjunctive technologies and diagnostics.
-
Novartis : Positioning established dry‑eye therapeutics within blepharitis care pathways highlights the strategic value of cross‑indication assets. Novartis’s footprint in specialty ophthalmology positions it to capture value where dry‑eye and blepharitis intersect.
-
Bausch Health , Santen , and Akorn : Each company represents a strategic archetype—targeted ocular care with differentiated formulations (Bausch), regional specialty leadership (Santen), and generic/supply continuity (Akorn). Collectively, they underscore the ongoing demand for both branded innovation and affordable, reliable symptom management solutions.
Market dynamics and risk vectors
Several forces will disproportionately influence 2026 outcomes:
-
Payer economics and net pricing: The net value equation—rebates, formulary positioning, and utilization management—will determine commercial scale more than list price alone. Negotiated discounts and contracting structures are now first‑order considerations for launch planning.
-
Access logistics and durable adherence: Prior authorization protocols, initial approval durations, and real‑world persistence patterns create discontinuities between prescriptions written and clinical outcomes achieved.
-
Regulatory and IP protection: Extended exclusivity windows for novel therapeutics offer a runway for return on investment, but international regulatory timelines and approval pathways remain heterogeneous—requiring bespoke strategy for each geography.
-
Supply and margin pressure: Scaling volumes materially affects margins and manufacturing risk. Firms that proactively secure supply chains and flex capacity will protect profitability as demand scales.
-
Competitive erosion and generics: The pathway from clinical success to commoditization is shortened in crowded therapeutic categories; differentiation beyond efficacy—such as delivery modality, diagnostics, or integrated services—will slow commoditization.
Strategic recommendations for 2026
For executives needing a concise action plan, our report synthesizes the above into prioritized moves that can be implemented within 6–12 months.
-
Manufacturers (novel therapeutics): Align launch investments to payer segmentation data: prioritize contracting and real‑world evidence generation ahead of full commercial roll‑out. Invest in patient support programs that shorten the time from prescription to sustained use.
-
Incumbent branded players: Leverage portfolio breadth to bundle therapeutic and supportive care offerings; explore co‑promotion and diagnostics partnerships to defend share as specialized entrants scale.
-
Generic suppliers and contract manufacturers: Use demand visibility to secure long‑lead raw materials and to optimize fill/finish capacity—margin resilience will be driven by cost predictability.
-
Private equity and strategic investors: Prioritize assets with clear payer economics and durable intellectual property or those that unlock meaningful cost synergies via manufacturing or distribution integration.
-
Healthcare providers and payers: Reconcile short‑term formulary savings with long‑term disease management outcomes; create streamlined prior authorization pathways for therapies with demonstrated cost‑offset potential.
Why PW Consulting — and what we are deliberately not disclosing in this release
Our analysis combines primary payer interviews, longitudinal claims analysis, proprietary unit‑flow modeling, and a detailed commercial benchmarking dataset to produce transaction‑grade advice. In keeping with our “trailer” approach—designed to provide strategic clarity while preserving the transactional value of granular intelligence—we have presented high‑confidence macro indicators and qualitative strategic insight here while withholding the detailed regional, type‑level, and treatment‑split tables that drive bespoke commercial strategies.
If you are evaluating entry, expansion, or divestiture in 2026, the difference between a good decision and a great one will be determined by that granularity: patient‑level utilization curves, payer net‑price waterfalls by channel, and time‑to‑full‑coverage models for specific geographies. These datasets and the accompanying scenario models are available in the full report and through PW Consulting’s advisory engagements.
Next steps
For companies, investors, and policy stakeholders preparing for 2026, the Blepharitis Market report is a practical roadmap: it identifies where to invest, where to defend, and where to wait for clarity. To access the full dataset, segmentation tables, and bespoke advisory options, please visit our report page or contact PW Consulting’s industry practice lead for a briefing tailored to your strategic objectives.
For detailed analysis of this topic, please visit the official page: Blepharitis Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com