

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
PW Consulting: Leucoxene Market Poised for 5.4% CAGR, Surging to USD 310.82 Million by 2032
By pmarketresearch, 2026-07-02
Leucoxene Market 2026: Strategic Imperatives from PW Consulting’s New Market Intelligence Brief
As demand for higher-grade titanium feedstocks tightens and buyers search for supply resilience, PW Consulting’s latest Leucoxene Market report delivers the practical intelligence executives need to make confident 2026 decisions. Anchored in a comprehensive base-year review (2020–2025) and a detailed forecast through 2032, the study combines granular supply-side mapping, price scenario analysis and commercial playbooks—while purposefully reserving proprietary segment-level datapoints to encourage direct engagement with the full report.
Leucoxene Market
Executive Snapshot: Why Leucoxene Matters in 2026
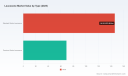
Leucoxene sits at the intersection of metallurgical feedstock markets and specialty pigments. Our analysis finds the global leucoxene market to have grown steadily through the 2020–2025 base period, reaching an estimated market value of approximately USD 215.1 million in 2025. The market is forecast to expand at a steady compound annual growth rate (CAGR) of roughly 5.4% over the 2026–2032 horizon, reaching an estimated market size in excess of USD 300 million by 2032. This trajectory reflects durable end‑use demand and ongoing substitution dynamics among titanium feedstocks—drivers that will shape sourcing, pricing and project economics in 2026 and beyond.
Leucoxene Market
What This Means for 2026 Decision-Makers
-
Buyers (TiO₂ producers, welding consumables, titanium metal makers): Expect tighter quality differentials and episodic price volatility driven by feedstock quality mix and regional logistics. Procurement teams should prioritize flexible contracts with volume bands, quality-adjusted pricing clauses and access to alternative sources. Tactical reserve purchases and staged offtake agreements will de-risk feedstock continuity in the near term.
Leucoxene Market -
Producers and project developers: Greenfield and brownfield investments need to embed near-term price scenarios, capex sensitivity and ESG compliance costs into FID (final investment decision) triggers. Our modelling shows that relatively small shifts in feedstock quality or operating performance can materially affect project IRRs—underscoring the value of staged commissioning and contingency planning.
-
Investors and M&A teams: The market displays meaningful concentration among the leading players—top-three producers account for a majority share while the top-five capture a substantial portion of supply—creating opportunities for bolt-on consolidation, tolling agreements and strategic offtakes. However, expected regulatory scrutiny and supply chain due diligence mean that valuation premia should reflect both operational and ESG execution risk.
What the Report Delivers: Practical, Transaction-Ready Intelligence
PW Consulting designed this brief as an operational toolkit rather than a purely academic study. Key deliverables included in the full report are:
-
Validated market sizing and forward-looking demand scenarios —three-price-path forecasts linked to demand shocks, substitution rates and downstream capacity ramps.
-
Supply-chain heatmaps and vulnerability scoring —detailed node-level analysis of mineral sands origins, processing points, port logistics and single-point-of-failure risks.
-
Price sensitivity and margin modeling (spread decks) —interactive models showing how feedstock quality mixes influence downstream cost curves for pigment and metal producers.
-
Commercial templates and contract playbooks —practical clauses for quality acceptance, force majeure, demurrage and quality escrow tailored to leucoxene trade flows.
-
Project viability checklists and ESG due-diligence frameworks —including local permitting timelines, community engagement risk matrices and certification pathways for responsible mining standards.
-
Target screening for M&A and off-take partnerships —an anonymized short-list of acquisition and partnership targets with estimated integration synergies and downside scenarios.
These components are combined into an executive playbook that supports rapid decision cycles in 2026—whether the mandate is to secure feedstock, accelerate a project, or evaluate an acquisition.
Competitive Landscape: Strategic Profiles and Implications
The leucoxene supply chain is anchored by vertically integrated mineral-sands operators and select processors/distributors. Our report analyzes leading firms—highlighting strategic positioning, operational capabilities and near-term levers they may employ.
-
Iwatani Corporation (Japan) : Through its subsidiary operations in Western Australia, Iwatani controls high-value, primary leucoxene deposits that are differentiated by grade consistency. This gives it leverage in premium markets and targeting high-margin niche end-uses. Strategic takeaway: expect selective offtake and direct partnerships with pigment and specialty weld consumable makers.
-
The Kerala Minerals & Metals Limited (India) : As a state-backed supplier with integrated beach-sands separation operations, KMML is a stable regional supplier with strategic importance for South Asian manufacturers. Strategic takeaway: regional security of supply considerations will factor into long-term sourcing decisions.
-
Eramet (France) — Grande Côte Operations : Eramet’s marketing push around high-TiO₂ leucoxene (circa ~90% TiO₂) and attainment of recognized responsible mining performance levels underscore its dual commercial and ESG positioning. Strategic takeaway: premium product marketing and ESG credentials can command price and contracting advantages in quality-sensitive market segments.
-
Iluka Resources (Australia) : A major mineral sands producer, Iluka’s recent production reviews point to the market effects of variable feedstock quality. Strategic takeaway: buyers must hedge not just quantity risk but quality variability that can propagate through pigment and metal manufacturing costs.
-
Tronox Holdings Plc (United States) : As an integrated TiO₂ producer, Tronox’s vertical integration provides downstream demand security and internal balancing of feedstock quality. Strategic takeaway: integrated players can internalize price shifts, but they remain vulnerable to supply concentration at certain nodes.
-
Astron Limited, Kenmare Resources, Arima Minerals Processing, Mineral Global Trading : These regional developers, processors and traders play critical roles in bridging resource-rich locales with global demand centers. Strategic takeaway: nimble project developers and traders will be important arbitrageurs and partners for buyers seeking to diversify supply.
Market Dynamics & Emerging Risk Signals
-
Price environment: Benchmark reporting indicates bulk ilmenite and leucoxene pricing at roughly USD 400/ton f.o.b. Australia in 2025. While leucoxene commands premiums in grade-sensitive applications, the broader market follows the balance of ilmenite, rutile and slag supply trends—creating periodic re‑rating opportunities.
-
Supply concentration: The market exhibits concentrated supply: the top three and five producers capture a meaningful share of global availability. For buyers and new entrants, this creates both counterparty concentration risk and attractive arbitrage opportunities where smaller players can undercut or outcompete based on niche attributes.
-
ESG and certification: Responsible mining credentials are becoming commercially material. Recent certifications and public reporting by large producers are increasingly being embedded into purchase specifications and financing covenants.
-
Geopolitical flows: Geographic production footprints and cross-border concentrate flows affect availability. For example, production and trade flows from major producing countries continue to shape sourcing patterns for Asian and European consumers—a structural consideration for securing long-term supply.
Recommended 90‑Day Playbook for 2026
-
Immediate (0–30 days): Conduct a quality‑profile audit of current feedstock contracts; renegotiate acceptance tolerances and incorporate short-term flexibility clauses.
-
Near-term (30–90 days): Execute a dual-track sourcing strategy: secure a core anchor offtake with a high-credit, high‑quality supplier while piloting alternative suppliers and spot purchases to test logistics and quality assurance processes. Deploy PW Consulting’s spread models to stress-test margins under three price-path scenarios.
-
Strategic (90+ days): Assess acquisition or JV opportunities among regional developers and processors identified in our target short-list. Build ESG-compliance roadmaps for any potential transaction to accelerate financing and commercialization.
How to Use This Brief—and Where to Find the Full Intelligence
This press brief is designed as a decision-trigger: it summarizes the strategic levers and immediate actions that will matter in 2026 while intentionally withholding certain proprietary segmentation tables, supplier-by-supplier volumes and the full interactive financial models. Those proprietary deliverables are included in the complete PW Consulting Leucoxene Market report and accompanying data pack—resources that procurement, strategy and M&A teams should consult before committing to significant contractual or capital decisions.
For organizations preparing to bid, negotiate or invest in the leucoxene value chain in 2026, the full report provides:
-
Supplier scorecards and contact-ready outreach templates;
-
Downloadable Excel models with scenario toggles for price, quality and logistics;
-
Anonymized M&A target matrices and integration checklists;
-
Detailed ESG compliance pathways and certification comparators.
PW Consulting stands ready to support tailored engagements—ranging from rapid procurement due diligence to multi‑month transaction advisory—built around the levers and playbooks outlined above. To access the full report and the proprietary datasets that underpin our 2026 strategic recommendations, please visit the PW Consulting report hub.
For detailed analysis of this topic, please visit the official page: Leucoxene Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: HSMT SerDes Chip Market Set to Jump from USD 3,200 Million in 2025 to USD 7,764.6 Million by 2032 on 13.5% CAGR
By pmarketresearch, 2026-07-02
HSMT SerDes Chip Market — Strategic Playbook for 2026
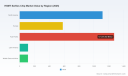
PW Consulting’s new HSMT SerDes Chip Market report provides a timely, decision-ready framework for CIOs, product leaders, supply-chain strategists and investors navigating a market that has more than doubled in size since 2020. Our analysis shows the global HSMT SerDes market expanding from USD 1,720 million in 2020 to USD 3,200 million in the 2025 base year, with a continued trajectory that reaches approximately USD 7,765 million by 2032 under a 13.5% CAGR (2026–2032). For executives planning resource allocation and go-to-market moves in 2026, the implications are clear: the window to solidify platform positions, secure resilient supply chains and capture premium mobility and data-transmission segments is now.
HSMT SerDes Chip Market
Why this report matters for 2026 decision cycles
- Actionable foresight, not forecasts alone. Beyond headline growth, the report decodes the business levers that will determine winners in 2026 — from protocol strategy and PAM4 adoption to tiered sourcing and qualification cycles for automotive-grade silicon.
- Tactical timing for procurement and product roadmap teams. Lead-time dynamics and capacity expansions in 2026 materially affect component allocation for automotive Tier-1s and hyperscale data-center OEMs; our timeline guidance converts market growth into concrete buy/qualify windows.
- Risk-to-reward mapping for investment and M&A. The HSMT SerDes market shows higher concentration among the top manufacturers, underscoring how selective acquisitions or strategic JV stakes can accelerate route-to-market while reducing integration risk.
High-level market dynamics you can trust
- Structural growth driven by automotive and high-bandwidth display needs. Demand for in-vehicle lossless video and sensor aggregation is a primary growth engine. Coupled with expansion in telecommunications and edge networking, this is what sustains a 13.5% compound annual growth through the forecast period.
- Market concentration signals strategic choke points. The competitive landscape demonstrates a relatively concentrated supplier base among top vendors — a dynamic that enables leading suppliers to influence pricing, protocol adoption rates and qualification roadmaps.
- Regulatory and geopolitical tailwinds for localized ecosystems. HSMT’s status as a recommended standard by the China Automotive Standardization Administration, combined with continued U.S. export controls and tariff structures, is accelerating domestic ecosystem development in China and influencing vendor selection and cross-border sourcing decisions.
What the report delivers — practical, executable outputs
PW Consulting’s report is designed for rapid translation into 2026 strategy. It includes:
HSMT SerDes Chip Market
- Market model and sensitivity scenarios that translate macro growth into addressable opportunity by customer class and protocol strategy (full data tables and model inputs are included in the full report).
- Supplier benchmark dossiers with capability matrices, qualification readiness, and commercialization timelines for primary vendors.
- Procurement playbooks: component qualification checklists, sample lead-time hedging strategies and a supplier scorecard adaptable to different risk appetites.
- Regulatory impact analysis: scenario planning for trade-control regimes and standardization milestones that affect certification and market access.
- Go-to-market frameworks for OEMs and Tier-1s: feature-pricing maps, differentiation opportunities around dual-protocol support, PAM4 implementation, and software-enabled value capture.
Competitive landscape — incumbent moves and fast followers
The report profiles the active vendor ecosystem, illustrating how product roadmaps and partnerships are shaping 2026 battlegrounds. Notable themes include rapid productization among Chinese vendors, dual-protocol strategies, and early moves toward higher-rate link products for cockpit and ADAS applications.
HSMT SerDes Chip Market
- Norelsys (China) — Positioned as a leader in automotive HSMT SerDes chipsets, with mass-produced 12G/12.8Gbps products targeting camera and display applications. Norelsys’ broad HSMT portfolio and production maturity make it a key reference for OEM qualification timelines.
- Rsemi (Nanjing Rsemi Technology, China) — Recently showcased a 32Gbps display SerDes (Auto China 2026 debut), signaling a push into high-bandwidth cockpit architectures and revealing where next-generation requirements will concentrate.
- Nanochip (China) — Early mover with 6.4G HSMT solutions positioned as a benchmark for in-vehicle link performance; useful for benchmark and legacy-replacement strategies.
- Ruifa Technology (China) — Demonstrated breadth at major industry exhibitions with mass-produced variants across a broad rate spectrum, underscoring domestic supply-chain depth.
- Velinktech (Venlinktech Microelectronics, China) — Noteworthy for dual-protocol offerings (MIPI A-PHY and HSMT) and a launched PAM4 12.8Gb/s product in mass production with a leading OEM — a model for commercial adoption pathways.
- Naxin Micro & Shouchuan Micro (China) — Represent the wave of firms delivering automotive-grade HSMT implementations that leverage domestic manufacturing and supply-chain integration.
Recent product and commercial milestones (selected)
- Early 2025–2026 product debuts and mass-production announcements have validated the technical feasibility and manufacturability of HSMT SerDes at multiple bandwidth points, reducing technical uncertainty for OEM adoption.
- Automotive OEM engagements and initial model integrations demonstrate that qualification cycles are compressing for established vendors who can deliver automotive-grade quality and supply assurances.
- Exhibitions and partnerships in 2025–2026 have accelerated ecosystem validation, making 2026 a critical junction for vendors and customers to commit to specific protocol roadmaps.
Supply chain, cost and regulatory implications for 2026
Executives must balance multiple, sometimes opposing forces in 2026:
- Lead-time improvements vs. persistent tightness. While industry reports show lead-time improvements for relevant mature nodes (moving into a 16–26 week range amid capacity expansions), adequate inventory strategies remain essential during peak qualification and ramp phases.
- Pricing pressure from adjacent demand. Memory and analog component pricing pressures — driven by AI-related demand spillover — can elevate BOM costs for SerDes solutions and compress OEM margins unless mitigated via long-term procurement or design consolidation.
- Geopolitical risk. Ongoing export controls and tariffs encourage localization in certain markets while elevating transaction costs for cross-border suppliers — a strategic consideration for global OEMs that must balance compliance with performance and cost.
Strategic recommendations for 2026 (prioritized, executable)
- Adopt a dual-path protocol strategy. For OEMs serving multiple geographies, prioritize suppliers that can support both HSMT and alternative standards (e.g., dual-protocol silicon) to minimize regional lock-in and maintain optionality.
- Fast-track qualification with tiered commitments. Use staged volume commitments tied to performance milestones to secure capacity from leading vendors while preserving flexibility to pivot as protocol adoption clarifies.
- Hedge critical BOM components. Negotiate medium-term purchase agreements for analog and memory items and maintain strategic buffer inventories to avoid margin erosion from short-term price spikes.
- Pursue targeted partnerships and minority investments. Use commercial alliances or minority equity in strategically positioned suppliers to accelerate roadmap access and de-risk supply without full integration overhead.
- Embed regulatory scenario planning into product roadmaps. Map alternative sourcing and certification playbooks for the most probable trade-control scenarios and align R&D timelines to the slowest majority path for multiregion launches.
What we deliberately withhold — why you need the full report
In line with PW Consulting’s “trailer” approach, this release highlights the strategic contours and actionable priorities emerging from our analysis but intentionally omits granular subsegment tables, region-by-application revenue splits and model-level company shares. Those datasets — including our detailed market-model workbook, segmented demand curves and supplier-specific revenue scenarios — are proprietary and available through the full report package. These detailed cells are the decision-grade inputs your procurement, product and M&A teams will use to build 90–180 day execution plans.
Next steps for executive teams
- Download the full report to access the interactive market model and supplier dossiers for qualification scheduling and sourcing optimization.
- Request a tailored briefing with PW Consulting to align your 2026 procurement calendar, product milestones and potential investment targets to the scenarios most relevant to your business footprint.
- Leverage our supplier scorecard template to run rapid, comparable assessments across your incumbent and potential HSMT SerDes partners.
PW Consulting’s HSMT SerDes Chip Market report translates growth forecasts (from USD 1,720 million in 2020 to USD 3,200 million in 2025 and toward USD 7,765 million by 2032 at a 13.5% CAGR) into executable 2026 actions. If your 2026 planning cycle includes decisions on product architecture, supply-chain commitments, or strategic investment in SerDes technology, this report is designed to be the playbook that turns market momentum into competitive advantage.
For detailed analysis of this topic, please visit the official page: HSMT SerDes Chip Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Semiconductor Part Refurbishment Repairs Market to Reach USD 8.23 Billion by 2032 on 7.85% CAGR, Asia Pacific Holds USD 2.45 Billion Share
By pmarketresearch, 2026-07-02
Semiconductor Part Refurbishment & Repairs: Strategic Imperatives for 2026 — PW Consulting Market Brief
PW Consulting’s new market study on the Semiconductor Part Refurbishment & Repairs market synthesizes multi-year historical tracking and a robust forward-looking model to give senior leaders the actionable intelligence they need to navigate supply-chain stress, regulatory friction, and accelerating fab investment. This briefing frames the report’s strategic value for decisions to be made in 2026 while intentionally preserving the granular segment tables and proprietary assumptions for subscribers.
Semiconductor Part Refurbishment Repairs Market
Executive summary
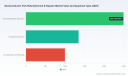
After tracking the market through a detailed 2020–2025 historical calibration, our baseline shows the global Semiconductor Part Refurbishment & Repairs market at approximately USD 4.85 billion in the base year (2025). Under a set of conservative-to-base assumptions, the market is projected to grow at a compound annual growth rate (CAGR) of 7.85% over the 2026–2032 forecast horizon, reaching roughly USD 8.23 billion by 2032. This trajectory is driven by three structural forces: continued fab expansion and capital intensity, constrained new-part availability and extended lead times, and an industry-wide cost optimization push that increases the attractiveness of refurbishment and parts-reuse strategies.
Semiconductor Part Refurbishment Repairs Market
Why this report matters for 2026 corporate decisions
- Strategic procurement and inventory planning: The combination of extended lead times and periodic price uplifts in core semiconductor components means organizations must reassess inventory policies and total landed-cost models. Our analysis links repair/refurbishment economics directly to procurement KPIs and TCO thresholds most relevant in 2026.
- CapEx vs. Opex trade-offs: As fabs scale and diversify, decisions about investing in in-house refurbishment capability versus outsourcing will hinge on utilization scenarios. We provide a financial framework and scenario outputs that show the breakpoints where in‑house capability becomes accretive.
- Regulatory and geopolitical decisioning: With evolving export controls and new tariff structures effective in early 2026, maintenance and repair strategies are being recast — particularly where cross-border transfers, licensing, and domestic exceptions apply. The report maps the practical contours of these rules and their operational impacts.
- M&A and partnership targeting: The market’s moderate concentration profile and specialized service footprints create distinct windows for bolt-on acquisitions and strategic partnerships. Our competitive lens surfaces acquisition targets and illustrative valuation multiples (available in the full report) aligned to 2026 exit and growth plans.
Market trajectory and what the numbers tell us
Using a data-led approach that triangulates supplier financials, end-user fab buildouts, and observed replacement/repair cycles, the report establishes a clear mid-term growth path: from roughly USD 4.50 billion in 2024 to USD 4.85 billion in 2025, then continuing toward an estimated USD 5.23 billion in 2026 and into the high single-digit billions by the early 2030s. The 7.85% CAGR reflects recurring service demand for legacy and current-generation tools, rising refurbishment economics as a response to supply constraints, and steady aftermarket penetration within new fab projects.
Semiconductor Part Refurbishment Repairs Market
Report contents — practical and operational deliverables
Designed for operating executives, procurement leads, and corporate development teams, the full report contains:
- Detailed market-sizing and 2026–2032 forecast models (with sensitivity scenarios and downloadable spreadsheet templates).
- Service- and equipment-level playbooks that translate market demand into operational KPIs: lead-time-to-repair, mean-time-to-return, warranty exposure, and parts obsolescence curves.
- Regulatory impact matrix that maps recent policy changes to practical operating responses (including how certain tariff exclusions apply to repair activities in the United States).
- A prioritized list of opportunities for cost reduction, near-term revenue capture, and margin expansion for aftermarket service providers.
- Deal-sourcing guidance and a shortlist of target profiles for M&A and strategic JV activity, with integration risk checklists.
Competitive landscape — what incumbents and specialists bring to the table
The aftermarket for semiconductor parts is populated by a mix of highly specialized repair houses, regional distributors with service offerings, and engineering-focused refurbishers. PW Consulting’s competitive analysis spotlights capabilities and strategic postures of market participants to help acquirers and partners align to 2026 objectives:
- IES Semiconductor Parts (Bristol, UK) — A specialist in repair and testing for a broad range of manufacturing parts. Their emphasis on extending legacy equipment life and offering warranty-backed services makes them attractive to fabs preserving long-lived tool assets, especially in markets where OEM obsolescence is accelerating.
- PSI Semicon Services (Livonia, MI, USA) — A full-service provider whose breadth across robotics, controllers, power systems, and vacuum components positions them as a one-stop shop for North American fabs seeking to rationalize supplier count while maintaining legacy support.
- SemiGroup (Dallas, TX, USA) — Focused on refurbishing to OEM-grade specifications with installation and maintenance support. Their model is aligned to customers that require turnkey refurbish-install-warranty solutions to minimize downtime risk.
- Capitol Area Technology (Austin, TX, USA) — Combining distribution and repair, CAT offers transactional flexibility that appeals to smaller fabs and contractors balancing capital constraints with uptime requirements.
- Ichor Systems (Fremont, CA, USA) — Noted for engineering-led refurbishments of processing equipment with deep tool integration capability; they serve customers that need design engineering tied to refurbishment for performance restoration.
- Semiconductor Support Services Co. (SSSco) (Austin, TX, USA) — Provides repairs, upgrades, and parts across major OEM tool families, an advantage where multi‑vendor homogeneity is low and cross-platform expertise reduces mean time to recovery.
- Conation Technologies (USA) — A niche provider focused on equipment from specific test and inspection OEMs, useful for fabs where inspection tool uptime is mission-critical.
Collectively, the competitive field shows a mix of complementary strengths: engineering depth, warranty-backed offerings, regional service networks, and logistics capabilities. For corporate strategy teams, the question is not whether to interact with these providers, but how to structure relationships (preferred-supplier, JV, or full acquisition) to lock in capacity and expertise as fabs scale in 2026.
Market dynamics and external shocks shaping 2026 strategies
- Price volatility: Recent supplier price actions (industry reports in early 2026 indicate increases in semi component pricing of 15–35% in some lines) create a renewed ROI case for refurbishment and parts reuse versus sourcing new components.
- Lead-time pressures: Select device categories have trended toward protracted delivery windows (observed trending into the high tens of weeks for some SKUs), reinforcing the strategic value of repair networks and validated refurbished inventories.
- Regulatory shifts: The U.S. Section 232 proclamation effective January 2026 introduces tariffs on certain advanced semiconductors, but crucially includes carve-outs for repair, replacement, and R&D performed domestically — a structural tailwind for U.S.-based refurbishers and for onshore maintenance strategies.
- Geopolitical controls: Export controls and licensing requirements remain a central operational complexity for cross-border maintenance activities. The report provides a decision matrix that ties asset-class risk to licensing pathways.
- Fab investment: With projected global fab spending exceeding USD 1.5 trillion across a multi-year window, sustained capex supports long-term demand for aftermarket services and creates opportunities to embed refurbishment options into factory build contracts.
- Notable developments: Recent facility and investment moves — for example, the launch of a new eco-focused refurbishment facility in Singapore (early 2025) and the wave of U.S. fab project announcements since the CHIPS Act — are changing the geography of aftermarket services and the economics of material recovery.
Opportunities, risks, and recommended 2026 actions
For corporate leaders, the practical decision agenda for 2026 should include the following prioritized actions:
- Recalculate spare-parts policy thresholds using the report’s scenario module — adjust reorder points to reflect new lead-time distributions and price volatility shocks.
- Establish or expand “shop-in-shop” refurbishment capacity where utilization and mix justify fixed-cost investment; otherwise, consolidate outsourcing with 2–3 strategic partners under long-term SLAs that include capacity guarantees and performance penalties.
- Leverage regulatory carve-outs: structure certain maintenance and R&D activities domestically to mitigate tariff exposure and expedite licensing for controlled repairs.
- Pursue selective M&A to acquire engineering capabilities or regional footprint quickly — target profiles include niche engineering refurbishers, warranty-capable installers, and parts-diagnostic specialists.
- Integrate sustainability KPIs into refurbishment contracts to capture material-recovery and circular‑economy benefits that increasingly matter to customers and regulators.
Conclusion & next steps
Our analysis confirms that the Semiconductor Part Refurbishment & Repairs market is neither marginal nor purely tactical — it is a strategic lever for resilience, cost control, and competitive differentiation in 2026 and beyond. With market size rising from the mid‑single billions in the mid‑2020s to the high single‑digit billions by the early 2030s at a 7.85% CAGR, organizations that treat aftermarket strategy as a core pillar of supply‑chain and asset management will materially outperform peers on uptime and cost metrics.
To access the full dataset, segmented forecasts, scenario spreadsheets, and the detailed company benchmarking that informed these conclusions, please visit the PW Consulting report page. The full report contains the granular tables, regional and service splits, and the proprietary sensitivity tests that strategic teams will need to operationalize action plans for 2026.
For detailed analysis of this topic, please visit the official page: Semiconductor Part Refurbishment Repairs Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Packaged Baked Goods Market Set to Reach USD 907.6 Billion by 2032, Growing at a 5.15% CAGR
By pmarketresearch, 2026-07-02
Packaged Baked Goods Market 2026 Preview: Strategic Imperatives for Growth, Resilience and Portfolio Reinvention
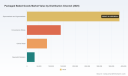
As the packaged baked goods industry enters a pivotal phase in 2026, PW Consulting’s latest market research report delivers the practical intelligence executives need to translate macro momentum into defensible growth. Our analysis aggregates historical performance (2020–2025), calibrates a near-term baseline (base year 2025) and provides a scenario-driven forecast through 2032. The headline: the global market expanded materially during the first half of the decade, reaching roughly USD 638.6 billion in 2025, and—at a compound annual growth rate (CAGR) of 5.15% over the 2026–2032 forecast horizon—is projected to approach the USD 908 billion mark by 2032. This trajectory hides important inflection points; the right strategic responses in 2026 will disproportionately determine which firms capture the upside.
Packaged Baked Goods Market
Why 2026 Is a Strategic Inflection Point
-
Operational cost re-basing. Trade policy shifts and packaging regulation have reshuffled input-cost dynamics. Tariff changes enacted in 2025 are already increasing bakery input costs by industry-average estimates, forcing price, sourcing, and margin decisions in 2026.
Packaged Baked Goods Market -
Labeling and sustainability front-loading. Proposed front-of-package nutrition rules and expanded Extended Producer Responsibility (EPR) regulations put product formulation, claims, and packaging strategies on accelerated timelines—creating both compliance risk and marketing opportunity.
Packaged Baked Goods Market -
Consumer polarization. Demand is fragmenting between premium, health-oriented formats and value/comfort-oriented staples. Winning firms will align portfolio architecture, trade promotions and channel mix for two-speed consumption patterns rather than one-size-fits-all SKUs.
-
Industry structure remains fragmented. Concentration metrics indicate the sector is not dominated by a few players—the top three firms account for roughly 15% of market value while the top five are under 20%. That fragmentation sustains acquisition pipelines and local-market consolidation opportunities for firms with scale advantages.
What the PW Consulting Report Delivers (Practical, Executable Tools)
-
Executive playbook for 2026: prioritized actions across pricing, raw-material hedging, and SKU rationalization tied to defined financial targets and timing gates.
-
Scenario financial models: three forward-looking scenarios (Baseline, Accelerated Premiumization, Margin-Compression) with P&L, working-capital and cash-flow sensitivities for 2026–2028—designed to be dropped into corporate planning systems.
-
Procurement and input-cost playbook: supplier segmentation, hedging options, and a practical toolkit to mitigate volatility in wheat, oils and packaging inputs (including benchmarking against observed 2025 price ranges and forward signals).
-
Regulatory compliance map: region-agnostic implications of front-of-package labeling proposals and EPR policies; recommended labeling and reformulation timelines to avoid distribution interruptions or channel delistings.
-
Channel acceleration guides: tailored GTM tactics for modern retail, convenience and digital platforms with KPI playbooks for assortment, promotion cadence and private-label counterstrategies.
-
M&A and partnership pipeline: screening criteria and prioritized target archetypes (capabilities, geography, and margin profile) supported by valuation multiples observed across recent transactions.
-
Innovation sprint templates: three rapid-test menus (clean label, functional, and indulgent formats) complete with expected product development timelines, CAPEX cadence and go-to-market playbooks for controlled rollouts.
-
Risk & recall readiness: an operational checklist informed by recent industry incidents and recall case studies—designed to shorten response time and reduce reputational impact.
Competitive Landscape — Strategic Themes from Leading Players
Global and regional leaders present different blueprints for growth. Large multinationals leverage distribution breadth and brand equity to defend volume, while regional champions excel in agility, fresh supply chains and local innovation. Key strategic takeaways from our company-level analysis include:
-
Global scale players (e.g., Grupo Bimbo, Mondelēz, Nestlé) are prioritizing supply-chain resilience, digital shelf analytics and cross-border platform plays to monetize premium snacking and convenience formats. Their advantage is the ability to invest in automation and long-term procurement contracts that blunt short-term commodity swings.
-
North American legacy brands (e.g., Flowers Foods, General Mills, Hostess Brands) are doubling down on fresh-pack formats, health-oriented line extensions and retailer partnerships for category captains’ promotions. Product innovation in the ‘better-for-you’ segment is an explicit hedge against slowing traditional bread and snack volumes.
-
Regionally-focused specialists (e.g., Yamazaki in Asia, Warburtons and Associated British Foods in the UK, Britannia in India, Aryzta in Europe) are using local R&D and cold-chain advantages to win on taste and day-one freshness—areas where global brands are more challenged to compete.
-
Ingredient and frozen-product suppliers (e.g., Rich Products, McKee Foods) are shifting upstream, offering co-manufacturing and ingredient systems that reduce customers’ working capital and accelerate retailer listing timelines.
Recent company activity underscores the diversity of corporate strategies: product-line expansions into low-carb and organic formats, corporate commitments to natural colorants, selective retail launches for frozen-ready formats, and—on the flip side—operational setbacks including facility-level recalls and allergy alerts that highlight supply-chain vulnerability.
Macro Dynamics and Risk Vectors to Watch in 2026
-
Raw-materials pressure. Soft-wheat flour pricing and transaction-level spreads observed in 2025 underline the need for active procurement strategies. Firms should stress-test 2026 budgets for +/-10% swings in core commodities and establish multi-tier supplier frameworks for key inputs.
-
Regulatory acceleration. Proposed front-of-package nutrition rules and expanding EPR laws create material go-to-market dependencies. Manufacturers must sequence reformulation, claim substantiation and packaging redesign to meet 3–4 year compliance timelines while preserving shelf appeal.
-
Trade and tariff headwinds. Recent tariff adjustments on select agricultural and packaging inputs have translated into mid-single-digit percentage increases in input costs for many manufacturers—necessitating a fresh look at landed cost, near-shoring and cross-border sourcing strategies in 2026 planning cycles.
-
Reputation and safety. High-profile recalls and allergy alerts in recent years underscore the importance of traceability investments and standardized recall protocols as an element of commercial continuity and retailer confidence.
Concrete Strategic Moves for 2026
-
Prioritize SKU rationalization with margin-first rules: identify the top-decile SKUs by profitability and reallocate incremental marketing spend to those while piloting a rapid-test program for premium/health variants.
-
Lock flexible procurement. Diversify supplier tiers and secure optionality in wheat and packaging contracts; layer short-term spot with partial forward positions to smooth cost volatility while preserving upside participation.
-
Accelerate compliance-ready packaging. Invest in modular packaging platforms to adapt to EPR and front-of-pack rules without full-line overhauls; use small-batch testing to minimize time-to-retail.
-
Targeted M&A for capability gaps. Pursue tuck-ins that deliver either premium brand equity, cold-chain reach, or co-manufacturing capacity—assets that can be integrated within 12 months to unlock synergies.
-
Embed recall readiness in commercial contracts. Make supplier quality performance KPIs a commercial gating factor and secure contractual remedies to reduce downstream brand risk.
How PW Consulting’s Report Helps Executives in 2026
This report is designed as a working tool—not just an industry narrative. Clients receive downloadable financial models, a regulator-readiness timetable, SKU-level decision templates and a prioritized list of capability investments mapped to expected ROI horizons. We deliberately withhold detailed regional-product carve-outs from this preview to preserve the integrity of proprietary segment models; the full, interactive datasets and market-split matrices—essential for granular portfolio and channel decisions—are available on the report access page.
Next Steps
For executive teams preparing 2026 budgets or three-year strategic plans, the report functions as a catalyst: convert the scenarios into a prioritized operating plan, stress-test procurement and pricing levers, and sequence investments in packaging and safety technologies to minimize regulatory and reputational risk. To access the complete dataset, segmentation matrices, and the scenario-ready Excel models referenced herein, please visit the PW Consulting report access page.
For detailed analysis of this topic, please visit the official page: Packaged Baked Goods Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Low Alpha Spherical Alumina Market Poised for Rapid Growth at a 14.02% CAGR Through 2032, Led by Asia Pacific
By pmarketresearch, 2026-07-02
Low Alpha Spherical Alumina Market — 2026 Strategic Outlook
Executive summary
As semiconductor packaging and thermal management demands accelerate into 2026, low alpha spherical alumina has moved from a niche specialty material into a strategic procurement and R&D priority for semiconductor OEMs, advanced packaging houses, and materials formulators. PW Consulting’s newest market study — covering historical performance from 2020–2025 and a forward-looking forecast through 2032 — models a robust compound annual growth rate of approximately 14.0% and projects the market to grow markedly from its 2025 baseline. The market structure is highly concentrated (top-3 providers account for over eight in ten dollars of revenue, and top-5 capture more than nine in ten), creating both stability and strategic risk for buyers and new entrants.
Low Alpha Spherical Alumina Market
Why 2026 is a strategic inflection
-
Node scaling, memory stacking (HBM evolutions), and the broader shift to heterogeneous integration are forcing customers to re-evaluate filler and encapsulant chemistries to avoid radiation-induced soft errors — a technical domain where low alpha spherical alumina plays a decisive role.
Low Alpha Spherical Alumina Market -
Supply-side consolidation and elevated concentration ratios mean buyers face limited sourcing elasticity. Where historical demand shocks were absorbed via regional substitution, 2026’s tightening of qualifying cycles and quality expectations lengthens qualification lead times and elevates supplier leverage.
Low Alpha Spherical Alumina Market -
Raw-material and policy forces remain material to near-term margin dynamics: precipitation feedstocks and alumina intermediates have shown price volatility and regional differentials, while tariff regimes continue to create location-specific premiums that downstream strategists must price into sourcing decisions.
Market trajectory and what it means for strategic planning
Our forecast (2026–2032) constructs demand scenarios anchored to the strong historical growth observed through 2025 and an expected multi-year expansion driven by packaging, TIMs, and high-frequency substrates. Practically, executives should plan for a near-term environment where capacity ramp timelines, qualification cycles, and raw-material swings dominate supplier selection and product roadmap choices.
Key implications for 2026 decision cycles:
-
Prioritize multi-sourcing strategies early in the qualification pipeline to compress lead-time risk and avoid single-point exposure to concentrated suppliers.
-
Embed low-alpha performance targets and testing protocols into design-for-reliability workstreams; waiting for late-stage supplier qualification will materially delay time-to-market.
-
Revisit total-cost-of-ownership (TCO) frameworks to include tariff-affected premiums, logistics complexity, and qualification amortization rather than relying on unit price alone.
Competitive landscape — what we observe in supplier positioning
The competitive map of low alpha spherical alumina combines established high-purity specialty producers with regional scale players that have made rapid technical progress. The report’s supplier analysis synthesizes publicly disclosed R&D and commercial milestones, plant capabilities, qualification timelines, and go-to-market plays.
-
Long-standing specialty manufacturers with proprietary synthesis routes (e.g., vaporized-metal or fusion-based processes) are leveraging their high-purity heritage to target ultra-low-alpha grades needed for cutting-edge memory and packaging. Their strength lies in process control, documented low U/Th footprints, and long-term reliability data — assets that are costly and time-consuming to replicate.
-
Large materials groups and engineered-mineral producers are competing on scale, formulation support, and integrated supply chains aimed at TIMs, power modules, and EV battery thermals. These players translate controlled particle engineering and broad customer relationships into faster commercial rollout for thermal management applications.
-
Regional new entrants, particularly from China, are closing the qualification gap through multi-batch sampling and local co-development with advanced packaging customers. Their advantage is speed-to-volume and localized logistics; their risk exposure centers on consistency at scale and long-term purity assurance.
Recent public moves typify these trends: one incumbent specialty firm has accelerated R&D focused on next-generation HBM memory families to mitigate soft-error risk; another has confirmed commercial production of low-alpha grades for thermal conductive molding compounds and set multi-year revenue ambitions tied to advanced substrate demand. Collectively, these developments indicate both supplier willingness to invest in qualification cycles and the emergence of segmented go-to-market strategies — proprietary ultra-low alpha for critical packaging vs. engineered formulations for thermal applications.
Supply chain dynamics and raw-material sensitivity
Materials executives must manage two linked dimensions: feedstock and process energy. Precipitated intermediates (e.g., aluminum hydroxide) and regional alumina supply balances feed directly into cost curves for spherical alumina. Recent market intelligence points to notable price adjustments in certain markets during early 2026, influenced by downstream demand cycles and energy cost swings at precipitation facilities. Concurrently, trade policy effects (notably aluminum import measures) have generated location-specific premiums, which can materially alter landed costs for higher-purity inputs.
Consequently, manufacturers and buyers should adopt three practical supply-side actions in 2026:
-
Implement rolling two-to-three-year sourcing scenarios that layer spot, contract, and hedged feedstock positions to blunt single-point price shocks.
-
Quantify qualification cost and time explicitly in any supplier TCO model; for many advanced packages the cost of delayed qualification exceeds raw material cost differentials.
-
Stress-test capacity roadmaps against energy and bauxite/alumina availability scenarios — localized disruptions can cascade rapidly into specialty alumina backlogs.
What PW Consulting’s report delivers — practical, purchase-ready intelligence
The full report goes beyond high-level forecasting to equip procurement, product, and corporate strategy teams with actionable deliverables that are essential in 2026 planning cycles:
-
Supplier scorecards: technical capabilities, qualification footprint, capacity roadmap, and risk indicators calibrated to customer qualification timelines.
-
Techno-economic models: build vs. buy decision matrices, capex-to-throughput benchmarks, and sensitivity runs that incorporate feedstock and tariff scenarios.
-
Scenario playbooks: four discrete demand-supply trajectories (base, upstream-constrained, accelerated-HBM-adoption, and substitution-risk) with recommended commercial and operational responses for each.
-
Operational templates: qualification roadmaps, sample-flow timelines, and joint-development term sheets designed to shorten approval cycles without sacrificing reliability.
-
Risk register and mitigation matrix: covering geopolitics, single-source exposure, raw-material volatility, and regulatory change — with prioritized action items for 90/180/365 day horizons.
In keeping with our “trailer” approach, we outline these capabilities here at a strategic level; the full report contains the granular segment-level breakdowns, company benchmarking tables, and model inputs that buyers and investors require to execute with confidence.
How executives should use this report in 2026 decision-making
-
Procurement leaders: use the supplier scorecards and TCO models to re-baseline 12–36 month supply plans and to justify accelerated multi-sourcing investments.
-
R&D and packaging teams: integrate the qualification templates into product roadmaps and gate reviews; demand-side lead indicators in our scenarios identify when to accelerate material co-development.
-
Corporate strategy and M&A teams: the concentration metrics and supply-side capacity maps in the report are designed to highlight strategic bolt-on targets, partnership opportunities, and potential choke points worth remediation.
Concluding perspective
Low alpha spherical alumina is no longer a marginal inputs debate — it is a foundational materials decision that affects yield, reliability, and time-to-market for many of the highest-growth semiconductor and power electronics applications. Our forecast and supplier intelligence indicate a market at once expansive and concentrated: growth creates opportunity, but the concentration of supply and the cost/qualification dynamics create distinct strategic risk that must be actively managed in 2026.
PW Consulting’s report is intended as the operational playbook for executives who need to convert market growth into durable competitive advantage. For the detailed segment tables, supplier rankings, and model inputs necessary to validate sourcing, investment, or partnership decisions, please consult the full report and our interactive data tools on the PW Consulting portal.
For detailed analysis of this topic, please visit the official page: Low Alpha Spherical Alumina Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Semiconductor TMAH Developer Market Reaches USD 1,155.4 Million in 2025 — Asia Pacific Commands USD 820.8 Million as Market Eyes 8.01% CAGR Through 2032
By pmarketresearch, 2026-07-02
Semiconductor TMAH Developer Market: Strategic Bulletin for 2026 Decision-Makers
PW Consulting today publishes its latest Semiconductor TMAH Developer Market report — a decision-focused briefing for executives, procurement leads, and technology strategists planning for 2026 and beyond. The market for tetramethylammonium hydroxide (TMAH) developer chemistries has entered a phase of renewed structural change. On a headline level, PW Consulting’s model uses 2025 as the base year and projects a sustained compound annual growth rate (CAGR) of 8.01% across the 2026–2032 forecast window, with global market value rising from USD 1,155.4 Million in 2025 to an expected USD 1,981.45 Million by 2032. These macro dynamics create a narrow window in 2026 for strategic moves that will set companies up for supply resilience, margin expansion, and technology leadership.
Semiconductor TMAH Developer Market
Why TMAH Developers Matter to 2026 Strategy
TMAH-based developers are not a commodity in the classic sense; they are a tightly specified, high-purity input whose performance maps directly to lithographic yield and process stability. Demand growth is driven by a combination of advanced-node IC production, increasing throughput in display fabs, and the rising complexity of wet-process steps in advanced packaging. At the same time, regulation, waste handling requirements, and the emergence of circular processing are changing the economics of procurement and capital allocation.
Semiconductor TMAH Developer Market
- Purity and process compatibility are strategic levers — minor supplier quality differences translate into measurable yield and tool uptime impacts across high-mix, low-tolerance fabs.
- Environmental and regulatory pressure are shifting TMAH from a simple consumable to a component of the fab’s sustainability agenda; recycling and wastewater treatment materially affect total ownership cost.
- Supply-chain shifts — including tariff actions and near-shoring incentives enacted in 2025 — are altering supplier selection and site-investment calculus for 2026 procurement contracts.
Market Structure and Competitive Implications
Concentration metrics in the report show a market that is moderately concentrated: the combined share of the top three suppliers and of the top five suppliers indicate that a small set of established players retains negotiating power while a second tier is expanding capacity. Practically, this means commercial strategies must be tailored: leaders should negotiate multi-year, performance-linked agreements with incumbents while building multiple qualified second-source suppliers as backups.
Semiconductor TMAH Developer Market
Operationally important production characteristics — such as chlorine-free manufacturing in sealed, integrated facilities connected to TMAC refineries — are no longer optional for suppliers serving advanced fabs. Buyers will favor suppliers with documented end-to-end purity controls and low-impurity supply chains due to the high cost of contamination events. Recent capacity investments by regional players and expansions in China and other APAC hubs are intensifying competition for qualified, electronic-grade volumes.
Key Supply-Chain and Regulatory Signals for 2026
- Recycling as a material strategy: Leading foundries are piloting and deploying technologies to recycle electronic-grade TMAH waste streams. A prominent example aims for a significant recycle share by 2030, materially reducing new liquid purchases and changing long-term demand curves for producers and buyers alike.
- Tariffs and near-shoring: New tariff measures implemented in early 2025 have already pushed a subset of buyers toward supply diversification and consideration of near-shored purification assets. Expect procurement RFPs in 2026 to include local-content and auditability clauses.
- Wastewater complexity: TMAH waste streams pose treatment challenges that affect effluent handling costs and compliance risk; concentrations found in semiconductor effluent require specialist treatment. Capex and OPEX for handling hazardous wet waste should be incorporated into sourcing decisions.
Competitive Landscape — Who Matters and Why
PW Consulting’s corporate profiles and supplier scorecards examine the capabilities of both legacy chemical houses and specialized developers. Below is a high-level synthesis of vendor positioning, focusing on strategic strengths and risks rather than transaction-level pricing.
- Sachem, Inc. (United States) — A long-established supplier with multi-region manufacturing and a track record of supporting advanced fabs. Strengths include trusted product lines for developer applications and geographically distributed production footprint.
- Tokuyama Corporation (Japan) — Known for its positive-type developer series and extensive shipping bases to service key semiconductor clusters in Asia, offering strong logistics support for tight fab schedules.
- Moses Lake Industries (MLI, United States) — Emphasizes ultra-pure, chlorine-free sealed processes integrated with TMAC feedstock, which appeals to customers with the strictest purity requirements.
- Chang Chun Group (Taiwan) — A large regional manufacturer with integrated supply capabilities; historically important as a raw-material source for electronic-grade TMAH used in downstream developer formulations.
- Tokyo Ohka Kogyo (TOK), Tama Chemicals, Kanto Chemical — Japanese suppliers with strong technical service offerings and incremental capacity investments aimed at advanced nodes.
- Dravyaom (India), Fujifilm Electronic Materials, Merck KGaA — A mix of regional challengers and global materials houses providing differentiated service models, from low-cost regional supply to high-margin, metal-ion free developers.
Each vendor profile in the full report includes production footprints, qualification cycles, quality control practices, and an assessment of their likely strategic moves through 2028. The report’s supplier matrix grades firms on purity controls, recycling readiness, logistics resilience, and commercial flexibility.
Recent Developments that Reframe 2026 Decisions
- Foundry-led recycling pilots have advanced to commercial deployment, signaling a potential structural reduction in new-volume purchases that buyers and suppliers must incorporate into 2026 contracts and capacity planning.
- Capacity expansions completed in 2025 by several regional producers are changing short-term availability and price negotiation dynamics; buyers should re-evaluate qualification timelines and onboarding windows.
- Technical updates from developer formulators are improving pattern resolution and process latitude, which can shift supplier selection criteria from purely cost-based to performance-optimized sourcing.
What the PW Consulting Report Delivers (Practical, Operational Contents)
This release is deliberately a prescriptive preview. The full report contains the operational detail that procurement and technology teams will use in 2026: multi-scenario demand forecasts, region-to-region supply maps, supplier scorecards with audit checklists, contract templates keyed to recycling outcomes, margin and total cost of ownership (TCO) models that include wastewater treatment and recycle economics, and a timeline for supplier qualification and capacity lock-ins. To preserve commercial exclusivity for subscribers, we do not reproduce the granular regional and application splits here; those tables and vendor-specific volume forecasts are available in the full report on the PW Consulting site.
90-Day Playbook for 2026 Executives
- Immediate supplier audit: Run rapid audits of primary and secondary suppliers against purity controls, chlorine-free production processes, and documentation for TMAC feedstock traceability.
- Negotiate recycle-linked contracts: Insert contractual flexibility allowing for recycled-content credits and shared investment in closed-loop processing pilots to reduce TCO.
- Evaluate near-shore purification: For firms exposed to tariff or logistics risk, fast-track feasibility studies for regional purification or toll-purification partnerships.
- Invest in wastewater strategy: Build or source specialized treatment capability; include effluent-treatment OPEX in supplier TCO comparisons.
- Qualify two-tier suppliers: Maintain incumbent long-term partners for core volumes while accelerating qualification of a diversified second tier for elasticity in surge or disruption scenarios.
Risk Calibration: What Could Upset the Outlook
- Faster-than-anticipated adoption of closed-loop recycling by major fabs could depress new-volume demand and force supplier rationalization faster than planned.
- Geopolitical or trade actions can re-route supply flows and create short-term scarcity, particularly for high-purity digitally certified volumes.
- Technical discontinuities in lithography, resist chemistry, or developer formulations can suddenly change specification sets, increasing qualification costs or favoring suppliers with rapid reformulation capabilities.
Conclusion — Strategic Opportunity for 2026
For executives evaluating capital allocation, supplier strategy, or R&D partnerships in 2026, the TMAH developer market presents both a risk and a lever. Growth and modernization of fabs support a robust market trajectory through 2032, but the interplay of recycling, regulation, and supplier consolidation requires nuanced, operationally-led decisions this year. PW Consulting’s Semiconductor TMAH Developer Market report is designed to translate these dynamics into executable choices — from procurement clauses and supplier investments to pilot partnerships for recycling and local purification. For access to the full data tables, vendor scorecards, scenario models, and the downloadable 90-day implementation templates, please visit the PW Consulting report page.
For detailed analysis of this topic, please visit the official page: Semiconductor TMAH Developer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Ultra Fine PCC Market to grow at 6.98% CAGR — from USD 215.0 Million in 2025 to USD 344.8 Million by 2032, led by Asia Pacific (USD 69.9M) and North America (USD 68.78M)
By pmarketresearch, 2026-07-02
Ultra Fine Precipitated Calcium Carbonate (PCC) Market: Strategic Briefing for 2026 Decision-Makers
PW Consulting’s latest market intelligence on the Ultra Fine Precipitated Calcium Carbonate (PCC) market provides an evidence-based playbook for commercial, operations, and M&A leaders preparing for 2026 and beyond. Built on a rigorous historical review (2020–2025) and forward-looking forecasts to 2032, the study harmonizes macro trajectories with in-market execution levers. At a compound annual growth rate (CAGR) of 6.98% across the forecast window (2026–2032), the market exhibits durable expansion driven by downstream demand dynamics, regulatory shifts, and raw-material price volatility.
Ultra Fine Precipitated Calcium Carbonate Pcc Market
Why this briefing matters for 2026
-
Timing: 2026 is a pivot year — supply chain reconfigurations post-pandemic, tighter environmental regulation cycles, and renewed investment into specialty grades converge to reshape competitive advantage. Leaders who align capital deployment, product portfolio, and go-to-market to this inflection will capture disproportionate value.
Ultra Fine Precipitated Calcium Carbonate Pcc Market -
Actionability: Our analysis translates market growth forecasts and scenario stress tests into prioritized initiatives — from capacity planning and product differentiation to contract and pricing strategies tailored to ultrafine PCC production.
Ultra Fine Precipitated Calcium Carbonate Pcc Market -
Risk-to-reward clarity: The report quantifies downside scenarios (price spikes, regulatory tightening, trade disruptions) and maps mitigation pathways — enabling boards and commodity managers to set tolerances and contingency budgets anchored to measurable triggers.
Headline market context (what the numbers say)
Across the base-year lens of 2025 and the forecast to 2032, the PCC market advances steadily. The historical review (2020–2025) captures the immediate recovery and rebalancing after pandemic-related shocks, while our forecast uses a 6.98% CAGR to project performance through 2032. These macro dynamics reflect both sustained demand in traditional end uses and the incremental adoption of ultrafine grades into higher-performance applications.
Importantly, market concentration metrics indicate a fragmented competitive landscape: the top three and top five suppliers account for under one-third of market value, underscoring the presence of numerous regional and specialist players. For incumbents and private equity alike, fragmentation suggests consolidation opportunities and the possibility to build scale through targeted M&A or portfolio roll-ups.
What the full PW Consulting report delivers
-
Comprehensive market modelling — a reconciled historical series (2020–2025) and scenario-based forecasts to 2032 with demand drivers disaggregated by customer use cases, product characteristics, and supply-side constraints.
-
Profitability and margin sensitivity analyses — realistic battleground models showing how raw-material price moves, energy costs, and regulatory compliance expenditures alter unit economics across common process routes.
-
Practical go-to-market guidance — customer segmentation for commercial prioritization, pricing playbooks for contractual negotiations, and channel strategies for specialty-grade adoption.
-
Operational and capital planning tools — capacity utilization thresholds, ramp-up timelines, and brownfield vs. greenfield decision frameworks tied to quartiles of expected payback periods.
-
Compliance and sustainability roadmaps — a matrix of emerging regulatory obligations and cost-impact estimates, plus low-regret investments to de-risk production footprints.
-
Deal origination support — target lists, valuation benchmarks, and integration checklists for buyers looking to consolidate or diversify within ultrafine PCC.
Competitive landscape — read between the lines
The ultrafine PCC sector is marked by a mixture of specialized players and diversified chemical producers. Key participants profiled in our research include established European specialty firms, integrated Asian producers, and regional innovators focused on bespoke ultrafine grades. Notable names in the intelligence set are Calcite GmbH (Germany), 20 Microns Nano Minerals Limited (India), Guangdong Qiangda New Materials Technology Co., Ltd. (China), Fujian Sanmu Nano Calcium Carbonate Co., Ltd. (China), and EZ Chemicals Inc. (China).
Our competitive analysis emphasizes capability vectors more than static market shares: particle-size distribution engineering, surface-coating expertise, downstream application formulation support (especially for plastics and high-performance sealants), and localized logistics networks. These capabilities, rather than raw production scale alone, are the main determinants of margin premium in ultrafine segments.
Recent product innovation signals confirm this trend. For example, a late-2025 SKU launch from one regionally important manufacturer introduced an ultrafine PCC grade tailored for high-performance sealants, emphasizing reinforcement, rheology modification, surface finish, and durability. Such introductions illustrate how formulation-led differentiation can unlock adoption in adjacent premium applications.
Market dynamics and operational headwinds
-
Raw-material and energy pressure: A recent North American calcium carbonate price index move in mid-2026 highlights near-term input cost volatility and the risk it poses to margin stability. Procurement teams must adopt dynamic sourcing and hedging practices to preserve profitability during price transients.
-
Regulatory tightening: Stricter chemical safety frameworks and revised exposure limits in major jurisdictions are elevating compliance costs and accelerating the retirement of legacy, highly emission-intensive processes. Manufacturers should expect capital outlays to meet updated worker-safety and environmental standards.
-
Environmental and permitting constraints: Mining-related controls on dust and water discharge are constraining brownfield expansions in some mature production hubs, pushing strategic investment toward process intensification, recycling, and geographically diversified capacity.
-
Geopolitical and trade volatility: Currency swings, tariffs, and trade-policy unpredictability create a layer of uncertainty for cross-border supply chains and pricing strategies. Scenario planning that pairs local hedges with flexible logistics will be critical.
Strategic implications and recommended 2026 actions
-
Prioritize product-led differentiation: Investing in R&D to tune particle characteristics and surface treatments delivers higher take rates into premium downstream segments (e.g., specialty plastics and sealants). Allocate a portion of R&D budget to rapid prototyping and co-development partnerships with key formulators.
-
Rebalance sourcing and contract structures: Move away from single-source, fixed-price raw material exposures. Layered contracting (short-term spot, medium-term indexed, and strategic long-term supply) helps manage both upside and downside pricing shocks.
-
Operational resilience through modular capacity: Given permitting and environmental headwinds, modular and debottlenecking investments often yield faster time-to-market and lower regulatory friction than large-scale greenfield projects.
-
Commercial segmentation and pricing: Use customer-level margin analytics to prioritize accounts for premium offerings, and adopt value-based pricing where ultrafine PCC demonstrably reduces downstream processing costs or enhances product performance.
-
M&A and partnership playbook: Targeted acquisitions of regional specialists can buy formulation know-how and customer access. Conversely, joint ventures in logistics or feedstock sourcing can de-risk volatility without full ownership exposure.
What the report intentionally withholds (and why)
In keeping with our “trailer” approach, this briefing offers the strategic outline, implications, and practical next steps that senior leaders need to act in 2026. We intentionally do not disclose the granular segmented revenue lines, region-by-application percentages, or detailed price-by-product matrices in this release. Those proprietary elements — including our source-data reconciliations and the granular demand-by-use-case tables — are available in the full report and interactive dashboard where readers can drill into the exact splits, unit-cost schedules, and scenario outputs required for transaction diligence or CAPEX sign-off.
How PW Consulting supports execution
Beyond delivering research, PW Consulting offers hands-on execution support aligned to the playbook above: procurement optimization sprints; technical due diligence for M&A; implementation of pilot-scale product development with formulators; and regulatory compliance gap assessments. Each engagement is structured to convert market insights into measurable KPIs — from improved EBITDA margin per ton to reduced time-to-market for specialty grades.
Next steps — for strategists, operators, and investors
-
Executives: Use the market scenarios and sensitivity models in the full report to stress-test your 2026 capital and procurement plans.
-
Commercial teams: Prioritize high-opportunity accounts for co-development and trial volumes, leveraging our suggested value-pricing frameworks.
-
Investors and M&A advisors: Request the proprietary target list and valuation multiples to evaluate consolidation targets or bolt-on acquisitions.
For a full breakdown of our modeling assumptions, the complete set of segment-level forecasts, and PW Consulting’s interactive scenario workbook, access the full Ultra Fine Precipitated Calcium Carbonate (PCC) Market report and dashboards on our site. The detailed data and proprietary tools are designed to convert the insights summarized here into executable plans that protect margin and accelerate growth in 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Ultra Fine Precipitated Calcium Carbonate Pcc Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecast: Normal Dodecyl Mercaptan Market to Rise from USD 205.85 Million (2025) to USD 280.13 Million by 2032 at 4.5% CAGR — Asia Pacific Leads with USD 103.48M
By pmarketresearch, 2026-07-02
Normal Dodecyl Mercaptan Market: Strategic Imperatives for 2026 Decision-Makers
As PW Consulting’s Senior Strategic Advisor and Head Industry Analyst, I present a forward-looking synthesis of the Normal Dodecyl Mercaptan (NDM) market drawn from our newly published market study. This briefing highlights the strategic intelligence that corporate leaders, procurement heads, and M&A teams should prioritize as they set budgets and allocate capital in 2026. The intent is to convey the report’s analytical depth and practical value while reserving the granular tables and segmented forecasts for the full report—available on our site.
Normal Dodecyl Mercaptan Market
Market snapshot: what executives need to know
NDM is a small but structurally important specialty chemical: a chain transfer agent in polymerization, an intermediate for antioxidant and additive synthesis, and an occasional flotation reagent in mining applications. Our assessment uses 2025 as the base year, reviews the 2020–2025 historical period, and projects the market across 2026–2032. Key macro takeaways: the market exhibited steady recovery and expansion through the early 2020s, reaching a mid‑hundreds million USD scale by 2025, and is projected to grow at a compound annual growth rate (CAGR) of approximately 4.5% through 2032—reaching a projected market size that materially changes the risk and opportunity calculus for suppliers and consumers alike.
Normal Dodecyl Mercaptan Market
Two quantitative facts deserve immediate attention: (1) the NDM market is meaningfully larger in 2025 than in 2020, reflecting demand growth across polymer and specialty-chemical value chains; and (2) with the 2026–2032 CAGR at roughly 4.5%, the market’s trajectory supports multi-year commitments for capacity, logistics, and regulatory investment rather than short‑term, tactical sourcing alone.
Normal Dodecyl Mercaptan Market
Why this matters for 2026 strategic decisions
- Procurement and contract design: A moderate but steady growth path argues for mid-term offtake and pricing arrangements—three-to-five year structures that balance supplier investment certainty with buyer flexibility. Tactical spot buying will remain useful for managing short-term volatility, but enterprise buyers should layer in indexed and volume‑protected contracts to secure technical grades and continuity.
- Capacity and footprint planning: Given the market’s scale and the product’s EHS footprint, greenfield capacity decisions must factor in permitting and community acceptance timelines as much as economics. For incumbent producers and potential entrants, targeted brownfield expansions and tolling partnerships may present quicker routes to capture upside.
- M&A and partnership activity: The market concentration profile—high concentration among the top suppliers—creates selective openings. Players looking to expand into specialty thiols or to secure backward integration for polymer additives will find potential partners among established producers and regional specialists explored in our competitive analysis.
- Risk management: Feedstock sensitivity and EHS regulation (particularly odor and transportation controls) make integrated supply-line risk assessments essential. Procurement teams should stress-test sourcing strategies against hydrocarbon and sulfur commodity swings and shifting transport/handling rules.
Segment and demand dynamics (what the report covers)
The full study maps demand across regional markets, product-purity tiers, and end-use applications, and outlines the manufacturing routes and upstream feedstock exposures that drive cost volatility. It includes detailed scenario analyses that capture the effects of feedstock price swings (dodecene/propylenic intermediates, hydrogen sulfide) and regulatory tightening on manufacturing, storage and logistics. While we purposely withhold the detailed segment-level tables in this summary, readers should note the report’s practical modules:
- Market sizing with historical series and a 2026–2032 forecast horizon, reported in USD (Million).
- Unit economics and cost‑curve modeling for representative production routes, including bromide‑based syntheses and alternative organosulfur processes.
- Supply-chain vulnerability assessments that quantify exposure to feedstock price drivers and transportation constraints.
- Regulatory and EH&S impact matrices—operational levers to reduce community friction and avoid costly operational pauses.
Competitive landscape: focused, consolidated, and strategic
NDM supply is concentrated. Our concentration analysis shows a market where the top three producers control a substantial share of capacity, and the top five comprise a dominant portion of commercial availability. This structure influences pricing power, contracting behaviors, and how quickly supply can scale to meet shifts in demand.
The study profiles established global producers alongside capable regional manufacturers and specialty suppliers. Highlights include:
- Chevron Phillips Chemical Company (The Woodlands, TX): Integrated petrochemical and specialty streams position this incumbent as a reliable source for industrial‑scale chain transfer agents and additive intermediates. Their global trading and logistics footprint supports multinational supply chains.
- Arkema (Colombes, France): A global supplier with strong application expertise in styrenics and acrylic polymerization, Arkema combines formulation support with global distribution, which matters for polymer producers seeking technical partnerships.
- Chinese and Indian manufacturers: Several China- and India‑based firms—ranging from ISO‑certified industrial producers to R&D‑driven specialty houses—offer competitive cost positions and regional responsiveness. These players are important supply alternatives, especially for market participants prioritizing price and lead‑time efficiencies.
- European and Japanese specialty producers: Select small‑to‑mid sized companies provide differentiated grades and local support where EHS compliance and odor‑management capabilities are decisive.
For buyers, supplier selection should weigh not only price and capacity, but also EHS handling competence, backward integration (feedstock control), and the ability to meet specific polymerization or additive specifications. For producers, near‑term opportunities lie in service differentiation (e.g., handling, odor mitigation, grade stability) and targeted upstream integration to moderate feedstock exposure.
Recent industry developments and their implications
Operational and application-level shifts continue to reshape demand patterns. A notable example during the review period was a mining project optimizing its flotation flowsheet to remove NDM as a reagent—an explicit reminder that end‑users refine chemistries based on cost, regulatory and EH&S trade-offs. Such changes can rapidly affect local demand pockets despite stable underlying polymer-driven growth.
On the upstream side, the material’s production pathways—from dodecanol conversion routes to alternative organosulfur syntheses—mean feedstock and energy prices feed directly into producer margins. The industry also faces persistent regulatory scrutiny given the compound’s odor and handling risks, which can add non-trivial compliance costs and influence logistics planning.
Actionable recommendations for 2026
- Adopt a layered procurement strategy: Combine multi-year contracts with indexed clauses, strategic spot purchases, and optionality for capacity flex. This balances cost control with resilience against feedstock swings.
- Pursue strategic partnerships: For firms seeking to expand formulations or secure availability, tolling agreements, joint ventures, or off‑take arrangements with regional specialty players can compress lead times and share EHS responsibilities.
- Stress-test operations for EHS and community risk: Invest in odor mitigation, community engagement protocols, and transport packaging solutions—these are often lower-cost mitigations versus lost production or permit delays.
- Model multiple sourcing scenarios: Use quantitative scenario planning in which feedstock and regulatory variables are stressed; identify the marginal supplier in each scenario and negotiate accordingly.
- Scan for opportunistic M&A: Given the high concentration at the top, selective acquisitions of regional or specialty producers can secure technical competencies and expand margin capture.
What the full report delivers
PW Consulting’s full Normal Dodecyl Mercaptan Market Report provides the granular data, supplier scorecards, and financial models required to operationalize the strategic guidance summarized here. Subscribers gain access to:
- Detailed segment-level forecasts and demand tables (regional, purity grade, application),
- Cost and margin models for alternative production routes,
- Supplier capability matrices and CR‑level analysis,
- Scenario playbooks for procurement, plant investment, and M&A decisions, and
- Practical checklists for EH&S and logistics mitigation.
For executives preparing 2026 budgets, capital allocation committees looking at specialty chemical exposures, or procurement teams negotiating multi-year contracts, the report translates market dynamics into concrete levers. Our analysis balances market-level forecasting—anchored by a 4.5% CAGR outlook—with pragmatic action steps tailored to the concentrated supplier base and the compound’s EHS realities.
Next steps
If your team is evaluating supply‑chain resilience, considering capacity investment, or assessing potential M&A in specialty thiols and polymer additives, PW Consulting’s full report contains the proprietary tables and supplier‑level intelligence needed to de‑risk those decisions. Visit our report page to access the complete dataset, supplier profiles, and scenario models that will inform 2026 planning and beyond.
For detailed analysis of this topic, please visit the official page: Normal Dodecyl Mercaptan Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com