

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Semiconductor TMAH Developer Market Reaches USD 1,155.4 Million in 2025 — Asia Pacific Commands USD 820.8 Million as Market Eyes 8.01% CAGR Through 2032

Semiconductor TMAH Developer Market: Strategic Bulletin for 2026 Decision-Makers
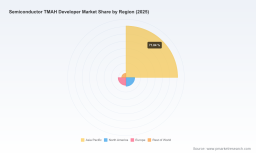
PW Consulting today publishes its latest Semiconductor TMAH Developer Market report — a decision-focused briefing for executives, procurement leads, and technology strategists planning for 2026 and beyond. The market for tetramethylammonium hydroxide (TMAH) developer chemistries has entered a phase of renewed structural change. On a headline level, PW Consulting’s model uses 2025 as the base year and projects a sustained compound annual growth rate (CAGR) of 8.01% across the 2026–2032 forecast window, with global market value rising from USD 1,155.4 Million in 2025 to an expected USD 1,981.45 Million by 2032. These macro dynamics create a narrow window in 2026 for strategic moves that will set companies up for supply resilience, margin expansion, and technology leadership.
Semiconductor TMAH Developer Market
Why TMAH Developers Matter to 2026 Strategy
TMAH-based developers are not a commodity in the classic sense; they are a tightly specified, high-purity input whose performance maps directly to lithographic yield and process stability. Demand growth is driven by a combination of advanced-node IC production, increasing throughput in display fabs, and the rising complexity of wet-process steps in advanced packaging. At the same time, regulation, waste handling requirements, and the emergence of circular processing are changing the economics of procurement and capital allocation.
Semiconductor TMAH Developer Market
- Purity and process compatibility are strategic levers — minor supplier quality differences translate into measurable yield and tool uptime impacts across high-mix, low-tolerance fabs.
- Environmental and regulatory pressure are shifting TMAH from a simple consumable to a component of the fab’s sustainability agenda; recycling and wastewater treatment materially affect total ownership cost.
- Supply-chain shifts — including tariff actions and near-shoring incentives enacted in 2025 — are altering supplier selection and site-investment calculus for 2026 procurement contracts.
Market Structure and Competitive Implications
Concentration metrics in the report show a market that is moderately concentrated: the combined share of the top three suppliers and of the top five suppliers indicate that a small set of established players retains negotiating power while a second tier is expanding capacity. Practically, this means commercial strategies must be tailored: leaders should negotiate multi-year, performance-linked agreements with incumbents while building multiple qualified second-source suppliers as backups.
Semiconductor TMAH Developer Market
Operationally important production characteristics — such as chlorine-free manufacturing in sealed, integrated facilities connected to TMAC refineries — are no longer optional for suppliers serving advanced fabs. Buyers will favor suppliers with documented end-to-end purity controls and low-impurity supply chains due to the high cost of contamination events. Recent capacity investments by regional players and expansions in China and other APAC hubs are intensifying competition for qualified, electronic-grade volumes.
Key Supply-Chain and Regulatory Signals for 2026
- Recycling as a material strategy: Leading foundries are piloting and deploying technologies to recycle electronic-grade TMAH waste streams. A prominent example aims for a significant recycle share by 2030, materially reducing new liquid purchases and changing long-term demand curves for producers and buyers alike.
- Tariffs and near-shoring: New tariff measures implemented in early 2025 have already pushed a subset of buyers toward supply diversification and consideration of near-shored purification assets. Expect procurement RFPs in 2026 to include local-content and auditability clauses.
- Wastewater complexity: TMAH waste streams pose treatment challenges that affect effluent handling costs and compliance risk; concentrations found in semiconductor effluent require specialist treatment. Capex and OPEX for handling hazardous wet waste should be incorporated into sourcing decisions.
Competitive Landscape — Who Matters and Why
PW Consulting’s corporate profiles and supplier scorecards examine the capabilities of both legacy chemical houses and specialized developers. Below is a high-level synthesis of vendor positioning, focusing on strategic strengths and risks rather than transaction-level pricing.
- Sachem, Inc. (United States) — A long-established supplier with multi-region manufacturing and a track record of supporting advanced fabs. Strengths include trusted product lines for developer applications and geographically distributed production footprint.
- Tokuyama Corporation (Japan) — Known for its positive-type developer series and extensive shipping bases to service key semiconductor clusters in Asia, offering strong logistics support for tight fab schedules.
- Moses Lake Industries (MLI, United States) — Emphasizes ultra-pure, chlorine-free sealed processes integrated with TMAC feedstock, which appeals to customers with the strictest purity requirements.
- Chang Chun Group (Taiwan) — A large regional manufacturer with integrated supply capabilities; historically important as a raw-material source for electronic-grade TMAH used in downstream developer formulations.
- Tokyo Ohka Kogyo (TOK), Tama Chemicals, Kanto Chemical — Japanese suppliers with strong technical service offerings and incremental capacity investments aimed at advanced nodes.
- Dravyaom (India), Fujifilm Electronic Materials, Merck KGaA — A mix of regional challengers and global materials houses providing differentiated service models, from low-cost regional supply to high-margin, metal-ion free developers.
Each vendor profile in the full report includes production footprints, qualification cycles, quality control practices, and an assessment of their likely strategic moves through 2028. The report’s supplier matrix grades firms on purity controls, recycling readiness, logistics resilience, and commercial flexibility.
Recent Developments that Reframe 2026 Decisions
- Foundry-led recycling pilots have advanced to commercial deployment, signaling a potential structural reduction in new-volume purchases that buyers and suppliers must incorporate into 2026 contracts and capacity planning.
- Capacity expansions completed in 2025 by several regional producers are changing short-term availability and price negotiation dynamics; buyers should re-evaluate qualification timelines and onboarding windows.
- Technical updates from developer formulators are improving pattern resolution and process latitude, which can shift supplier selection criteria from purely cost-based to performance-optimized sourcing.
What the PW Consulting Report Delivers (Practical, Operational Contents)
This release is deliberately a prescriptive preview. The full report contains the operational detail that procurement and technology teams will use in 2026: multi-scenario demand forecasts, region-to-region supply maps, supplier scorecards with audit checklists, contract templates keyed to recycling outcomes, margin and total cost of ownership (TCO) models that include wastewater treatment and recycle economics, and a timeline for supplier qualification and capacity lock-ins. To preserve commercial exclusivity for subscribers, we do not reproduce the granular regional and application splits here; those tables and vendor-specific volume forecasts are available in the full report on the PW Consulting site.
90-Day Playbook for 2026 Executives
- Immediate supplier audit: Run rapid audits of primary and secondary suppliers against purity controls, chlorine-free production processes, and documentation for TMAC feedstock traceability.
- Negotiate recycle-linked contracts: Insert contractual flexibility allowing for recycled-content credits and shared investment in closed-loop processing pilots to reduce TCO.
- Evaluate near-shore purification: For firms exposed to tariff or logistics risk, fast-track feasibility studies for regional purification or toll-purification partnerships.
- Invest in wastewater strategy: Build or source specialized treatment capability; include effluent-treatment OPEX in supplier TCO comparisons.
- Qualify two-tier suppliers: Maintain incumbent long-term partners for core volumes while accelerating qualification of a diversified second tier for elasticity in surge or disruption scenarios.
Risk Calibration: What Could Upset the Outlook
- Faster-than-anticipated adoption of closed-loop recycling by major fabs could depress new-volume demand and force supplier rationalization faster than planned.
- Geopolitical or trade actions can re-route supply flows and create short-term scarcity, particularly for high-purity digitally certified volumes.
- Technical discontinuities in lithography, resist chemistry, or developer formulations can suddenly change specification sets, increasing qualification costs or favoring suppliers with rapid reformulation capabilities.
Conclusion — Strategic Opportunity for 2026
For executives evaluating capital allocation, supplier strategy, or R&D partnerships in 2026, the TMAH developer market presents both a risk and a lever. Growth and modernization of fabs support a robust market trajectory through 2032, but the interplay of recycling, regulation, and supplier consolidation requires nuanced, operationally-led decisions this year. PW Consulting’s Semiconductor TMAH Developer Market report is designed to translate these dynamics into executable choices — from procurement clauses and supplier investments to pilot partnerships for recycling and local purification. For access to the full data tables, vendor scorecards, scenario models, and the downloadable 90-day implementation templates, please visit the PW Consulting report page.
For detailed analysis of this topic, please visit the official page: Semiconductor TMAH Developer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com