

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Low Alpha Spherical Alumina Market Poised for Rapid Growth at a 14.02% CAGR Through 2032, Led by Asia Pacific

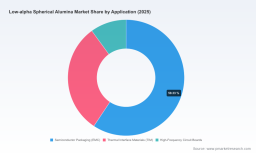
Low Alpha Spherical Alumina Market — 2026 Strategic Outlook
Executive summary
As semiconductor packaging and thermal management demands accelerate into 2026, low alpha spherical alumina has moved from a niche specialty material into a strategic procurement and R&D priority for semiconductor OEMs, advanced packaging houses, and materials formulators. PW Consulting’s newest market study — covering historical performance from 2020–2025 and a forward-looking forecast through 2032 — models a robust compound annual growth rate of approximately 14.0% and projects the market to grow markedly from its 2025 baseline. The market structure is highly concentrated (top-3 providers account for over eight in ten dollars of revenue, and top-5 capture more than nine in ten), creating both stability and strategic risk for buyers and new entrants.
Low Alpha Spherical Alumina Market
Why 2026 is a strategic inflection
-
Node scaling, memory stacking (HBM evolutions), and the broader shift to heterogeneous integration are forcing customers to re-evaluate filler and encapsulant chemistries to avoid radiation-induced soft errors — a technical domain where low alpha spherical alumina plays a decisive role.
Low Alpha Spherical Alumina Market -
Supply-side consolidation and elevated concentration ratios mean buyers face limited sourcing elasticity. Where historical demand shocks were absorbed via regional substitution, 2026’s tightening of qualifying cycles and quality expectations lengthens qualification lead times and elevates supplier leverage.
Low Alpha Spherical Alumina Market -
Raw-material and policy forces remain material to near-term margin dynamics: precipitation feedstocks and alumina intermediates have shown price volatility and regional differentials, while tariff regimes continue to create location-specific premiums that downstream strategists must price into sourcing decisions.
Market trajectory and what it means for strategic planning
Our forecast (2026–2032) constructs demand scenarios anchored to the strong historical growth observed through 2025 and an expected multi-year expansion driven by packaging, TIMs, and high-frequency substrates. Practically, executives should plan for a near-term environment where capacity ramp timelines, qualification cycles, and raw-material swings dominate supplier selection and product roadmap choices.
Key implications for 2026 decision cycles:
-
Prioritize multi-sourcing strategies early in the qualification pipeline to compress lead-time risk and avoid single-point exposure to concentrated suppliers.
-
Embed low-alpha performance targets and testing protocols into design-for-reliability workstreams; waiting for late-stage supplier qualification will materially delay time-to-market.
-
Revisit total-cost-of-ownership (TCO) frameworks to include tariff-affected premiums, logistics complexity, and qualification amortization rather than relying on unit price alone.
Competitive landscape — what we observe in supplier positioning
The competitive map of low alpha spherical alumina combines established high-purity specialty producers with regional scale players that have made rapid technical progress. The report’s supplier analysis synthesizes publicly disclosed R&D and commercial milestones, plant capabilities, qualification timelines, and go-to-market plays.
-
Long-standing specialty manufacturers with proprietary synthesis routes (e.g., vaporized-metal or fusion-based processes) are leveraging their high-purity heritage to target ultra-low-alpha grades needed for cutting-edge memory and packaging. Their strength lies in process control, documented low U/Th footprints, and long-term reliability data — assets that are costly and time-consuming to replicate.
-
Large materials groups and engineered-mineral producers are competing on scale, formulation support, and integrated supply chains aimed at TIMs, power modules, and EV battery thermals. These players translate controlled particle engineering and broad customer relationships into faster commercial rollout for thermal management applications.
-
Regional new entrants, particularly from China, are closing the qualification gap through multi-batch sampling and local co-development with advanced packaging customers. Their advantage is speed-to-volume and localized logistics; their risk exposure centers on consistency at scale and long-term purity assurance.
Recent public moves typify these trends: one incumbent specialty firm has accelerated R&D focused on next-generation HBM memory families to mitigate soft-error risk; another has confirmed commercial production of low-alpha grades for thermal conductive molding compounds and set multi-year revenue ambitions tied to advanced substrate demand. Collectively, these developments indicate both supplier willingness to invest in qualification cycles and the emergence of segmented go-to-market strategies — proprietary ultra-low alpha for critical packaging vs. engineered formulations for thermal applications.
Supply chain dynamics and raw-material sensitivity
Materials executives must manage two linked dimensions: feedstock and process energy. Precipitated intermediates (e.g., aluminum hydroxide) and regional alumina supply balances feed directly into cost curves for spherical alumina. Recent market intelligence points to notable price adjustments in certain markets during early 2026, influenced by downstream demand cycles and energy cost swings at precipitation facilities. Concurrently, trade policy effects (notably aluminum import measures) have generated location-specific premiums, which can materially alter landed costs for higher-purity inputs.
Consequently, manufacturers and buyers should adopt three practical supply-side actions in 2026:
-
Implement rolling two-to-three-year sourcing scenarios that layer spot, contract, and hedged feedstock positions to blunt single-point price shocks.
-
Quantify qualification cost and time explicitly in any supplier TCO model; for many advanced packages the cost of delayed qualification exceeds raw material cost differentials.
-
Stress-test capacity roadmaps against energy and bauxite/alumina availability scenarios — localized disruptions can cascade rapidly into specialty alumina backlogs.
What PW Consulting’s report delivers — practical, purchase-ready intelligence
The full report goes beyond high-level forecasting to equip procurement, product, and corporate strategy teams with actionable deliverables that are essential in 2026 planning cycles:
-
Supplier scorecards: technical capabilities, qualification footprint, capacity roadmap, and risk indicators calibrated to customer qualification timelines.
-
Techno-economic models: build vs. buy decision matrices, capex-to-throughput benchmarks, and sensitivity runs that incorporate feedstock and tariff scenarios.
-
Scenario playbooks: four discrete demand-supply trajectories (base, upstream-constrained, accelerated-HBM-adoption, and substitution-risk) with recommended commercial and operational responses for each.
-
Operational templates: qualification roadmaps, sample-flow timelines, and joint-development term sheets designed to shorten approval cycles without sacrificing reliability.
-
Risk register and mitigation matrix: covering geopolitics, single-source exposure, raw-material volatility, and regulatory change — with prioritized action items for 90/180/365 day horizons.
In keeping with our “trailer” approach, we outline these capabilities here at a strategic level; the full report contains the granular segment-level breakdowns, company benchmarking tables, and model inputs that buyers and investors require to execute with confidence.
How executives should use this report in 2026 decision-making
-
Procurement leaders: use the supplier scorecards and TCO models to re-baseline 12–36 month supply plans and to justify accelerated multi-sourcing investments.
-
R&D and packaging teams: integrate the qualification templates into product roadmaps and gate reviews; demand-side lead indicators in our scenarios identify when to accelerate material co-development.
-
Corporate strategy and M&A teams: the concentration metrics and supply-side capacity maps in the report are designed to highlight strategic bolt-on targets, partnership opportunities, and potential choke points worth remediation.
Concluding perspective
Low alpha spherical alumina is no longer a marginal inputs debate — it is a foundational materials decision that affects yield, reliability, and time-to-market for many of the highest-growth semiconductor and power electronics applications. Our forecast and supplier intelligence indicate a market at once expansive and concentrated: growth creates opportunity, but the concentration of supply and the cost/qualification dynamics create distinct strategic risk that must be actively managed in 2026.
PW Consulting’s report is intended as the operational playbook for executives who need to convert market growth into durable competitive advantage. For the detailed segment tables, supplier rankings, and model inputs necessary to validate sourcing, investment, or partnership decisions, please consult the full report and our interactive data tools on the PW Consulting portal.
For detailed analysis of this topic, please visit the official page: Low Alpha Spherical Alumina Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com