

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Packaged Baked Goods Market Set to Reach USD 907.6 Billion by 2032, Growing at a 5.15% CAGR

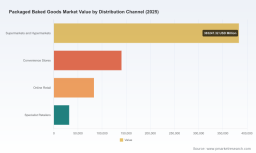
Packaged Baked Goods Market 2026 Preview: Strategic Imperatives for Growth, Resilience and Portfolio Reinvention
As the packaged baked goods industry enters a pivotal phase in 2026, PW Consulting’s latest market research report delivers the practical intelligence executives need to translate macro momentum into defensible growth. Our analysis aggregates historical performance (2020–2025), calibrates a near-term baseline (base year 2025) and provides a scenario-driven forecast through 2032. The headline: the global market expanded materially during the first half of the decade, reaching roughly USD 638.6 billion in 2025, and—at a compound annual growth rate (CAGR) of 5.15% over the 2026–2032 forecast horizon—is projected to approach the USD 908 billion mark by 2032. This trajectory hides important inflection points; the right strategic responses in 2026 will disproportionately determine which firms capture the upside.
Packaged Baked Goods Market
Why 2026 Is a Strategic Inflection Point
-
Operational cost re-basing. Trade policy shifts and packaging regulation have reshuffled input-cost dynamics. Tariff changes enacted in 2025 are already increasing bakery input costs by industry-average estimates, forcing price, sourcing, and margin decisions in 2026.
Packaged Baked Goods Market -
Labeling and sustainability front-loading. Proposed front-of-package nutrition rules and expanded Extended Producer Responsibility (EPR) regulations put product formulation, claims, and packaging strategies on accelerated timelines—creating both compliance risk and marketing opportunity.
Packaged Baked Goods Market -
Consumer polarization. Demand is fragmenting between premium, health-oriented formats and value/comfort-oriented staples. Winning firms will align portfolio architecture, trade promotions and channel mix for two-speed consumption patterns rather than one-size-fits-all SKUs.
-
Industry structure remains fragmented. Concentration metrics indicate the sector is not dominated by a few players—the top three firms account for roughly 15% of market value while the top five are under 20%. That fragmentation sustains acquisition pipelines and local-market consolidation opportunities for firms with scale advantages.
What the PW Consulting Report Delivers (Practical, Executable Tools)
-
Executive playbook for 2026: prioritized actions across pricing, raw-material hedging, and SKU rationalization tied to defined financial targets and timing gates.
-
Scenario financial models: three forward-looking scenarios (Baseline, Accelerated Premiumization, Margin-Compression) with P&L, working-capital and cash-flow sensitivities for 2026–2028—designed to be dropped into corporate planning systems.
-
Procurement and input-cost playbook: supplier segmentation, hedging options, and a practical toolkit to mitigate volatility in wheat, oils and packaging inputs (including benchmarking against observed 2025 price ranges and forward signals).
-
Regulatory compliance map: region-agnostic implications of front-of-package labeling proposals and EPR policies; recommended labeling and reformulation timelines to avoid distribution interruptions or channel delistings.
-
Channel acceleration guides: tailored GTM tactics for modern retail, convenience and digital platforms with KPI playbooks for assortment, promotion cadence and private-label counterstrategies.
-
M&A and partnership pipeline: screening criteria and prioritized target archetypes (capabilities, geography, and margin profile) supported by valuation multiples observed across recent transactions.
-
Innovation sprint templates: three rapid-test menus (clean label, functional, and indulgent formats) complete with expected product development timelines, CAPEX cadence and go-to-market playbooks for controlled rollouts.
-
Risk & recall readiness: an operational checklist informed by recent industry incidents and recall case studies—designed to shorten response time and reduce reputational impact.
Competitive Landscape — Strategic Themes from Leading Players
Global and regional leaders present different blueprints for growth. Large multinationals leverage distribution breadth and brand equity to defend volume, while regional champions excel in agility, fresh supply chains and local innovation. Key strategic takeaways from our company-level analysis include:
-
Global scale players (e.g., Grupo Bimbo, Mondelēz, Nestlé) are prioritizing supply-chain resilience, digital shelf analytics and cross-border platform plays to monetize premium snacking and convenience formats. Their advantage is the ability to invest in automation and long-term procurement contracts that blunt short-term commodity swings.
-
North American legacy brands (e.g., Flowers Foods, General Mills, Hostess Brands) are doubling down on fresh-pack formats, health-oriented line extensions and retailer partnerships for category captains’ promotions. Product innovation in the ‘better-for-you’ segment is an explicit hedge against slowing traditional bread and snack volumes.
-
Regionally-focused specialists (e.g., Yamazaki in Asia, Warburtons and Associated British Foods in the UK, Britannia in India, Aryzta in Europe) are using local R&D and cold-chain advantages to win on taste and day-one freshness—areas where global brands are more challenged to compete.
-
Ingredient and frozen-product suppliers (e.g., Rich Products, McKee Foods) are shifting upstream, offering co-manufacturing and ingredient systems that reduce customers’ working capital and accelerate retailer listing timelines.
Recent company activity underscores the diversity of corporate strategies: product-line expansions into low-carb and organic formats, corporate commitments to natural colorants, selective retail launches for frozen-ready formats, and—on the flip side—operational setbacks including facility-level recalls and allergy alerts that highlight supply-chain vulnerability.
Macro Dynamics and Risk Vectors to Watch in 2026
-
Raw-materials pressure. Soft-wheat flour pricing and transaction-level spreads observed in 2025 underline the need for active procurement strategies. Firms should stress-test 2026 budgets for +/-10% swings in core commodities and establish multi-tier supplier frameworks for key inputs.
-
Regulatory acceleration. Proposed front-of-package nutrition rules and expanding EPR laws create material go-to-market dependencies. Manufacturers must sequence reformulation, claim substantiation and packaging redesign to meet 3–4 year compliance timelines while preserving shelf appeal.
-
Trade and tariff headwinds. Recent tariff adjustments on select agricultural and packaging inputs have translated into mid-single-digit percentage increases in input costs for many manufacturers—necessitating a fresh look at landed cost, near-shoring and cross-border sourcing strategies in 2026 planning cycles.
-
Reputation and safety. High-profile recalls and allergy alerts in recent years underscore the importance of traceability investments and standardized recall protocols as an element of commercial continuity and retailer confidence.
Concrete Strategic Moves for 2026
-
Prioritize SKU rationalization with margin-first rules: identify the top-decile SKUs by profitability and reallocate incremental marketing spend to those while piloting a rapid-test program for premium/health variants.
-
Lock flexible procurement. Diversify supplier tiers and secure optionality in wheat and packaging contracts; layer short-term spot with partial forward positions to smooth cost volatility while preserving upside participation.
-
Accelerate compliance-ready packaging. Invest in modular packaging platforms to adapt to EPR and front-of-pack rules without full-line overhauls; use small-batch testing to minimize time-to-retail.
-
Targeted M&A for capability gaps. Pursue tuck-ins that deliver either premium brand equity, cold-chain reach, or co-manufacturing capacity—assets that can be integrated within 12 months to unlock synergies.
-
Embed recall readiness in commercial contracts. Make supplier quality performance KPIs a commercial gating factor and secure contractual remedies to reduce downstream brand risk.
How PW Consulting’s Report Helps Executives in 2026
This report is designed as a working tool—not just an industry narrative. Clients receive downloadable financial models, a regulator-readiness timetable, SKU-level decision templates and a prioritized list of capability investments mapped to expected ROI horizons. We deliberately withhold detailed regional-product carve-outs from this preview to preserve the integrity of proprietary segment models; the full, interactive datasets and market-split matrices—essential for granular portfolio and channel decisions—are available on the report access page.
Next Steps
For executive teams preparing 2026 budgets or three-year strategic plans, the report functions as a catalyst: convert the scenarios into a prioritized operating plan, stress-test procurement and pricing levers, and sequence investments in packaging and safety technologies to minimize regulatory and reputational risk. To access the complete dataset, segmentation matrices, and the scenario-ready Excel models referenced herein, please visit the PW Consulting report access page.
For detailed analysis of this topic, please visit the official page: Packaged Baked Goods Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com