

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: HSMT SerDes Chip Market Set to Jump from USD 3,200 Million in 2025 to USD 7,764.6 Million by 2032 on 13.5% CAGR

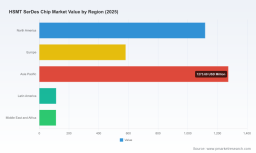
HSMT SerDes Chip Market — Strategic Playbook for 2026
PW Consulting’s new HSMT SerDes Chip Market report provides a timely, decision-ready framework for CIOs, product leaders, supply-chain strategists and investors navigating a market that has more than doubled in size since 2020. Our analysis shows the global HSMT SerDes market expanding from USD 1,720 million in 2020 to USD 3,200 million in the 2025 base year, with a continued trajectory that reaches approximately USD 7,765 million by 2032 under a 13.5% CAGR (2026–2032). For executives planning resource allocation and go-to-market moves in 2026, the implications are clear: the window to solidify platform positions, secure resilient supply chains and capture premium mobility and data-transmission segments is now.
HSMT SerDes Chip Market
Why this report matters for 2026 decision cycles
- Actionable foresight, not forecasts alone. Beyond headline growth, the report decodes the business levers that will determine winners in 2026 — from protocol strategy and PAM4 adoption to tiered sourcing and qualification cycles for automotive-grade silicon.
- Tactical timing for procurement and product roadmap teams. Lead-time dynamics and capacity expansions in 2026 materially affect component allocation for automotive Tier-1s and hyperscale data-center OEMs; our timeline guidance converts market growth into concrete buy/qualify windows.
- Risk-to-reward mapping for investment and M&A. The HSMT SerDes market shows higher concentration among the top manufacturers, underscoring how selective acquisitions or strategic JV stakes can accelerate route-to-market while reducing integration risk.
High-level market dynamics you can trust
- Structural growth driven by automotive and high-bandwidth display needs. Demand for in-vehicle lossless video and sensor aggregation is a primary growth engine. Coupled with expansion in telecommunications and edge networking, this is what sustains a 13.5% compound annual growth through the forecast period.
- Market concentration signals strategic choke points. The competitive landscape demonstrates a relatively concentrated supplier base among top vendors — a dynamic that enables leading suppliers to influence pricing, protocol adoption rates and qualification roadmaps.
- Regulatory and geopolitical tailwinds for localized ecosystems. HSMT’s status as a recommended standard by the China Automotive Standardization Administration, combined with continued U.S. export controls and tariff structures, is accelerating domestic ecosystem development in China and influencing vendor selection and cross-border sourcing decisions.
What the report delivers — practical, executable outputs
PW Consulting’s report is designed for rapid translation into 2026 strategy. It includes:
HSMT SerDes Chip Market
- Market model and sensitivity scenarios that translate macro growth into addressable opportunity by customer class and protocol strategy (full data tables and model inputs are included in the full report).
- Supplier benchmark dossiers with capability matrices, qualification readiness, and commercialization timelines for primary vendors.
- Procurement playbooks: component qualification checklists, sample lead-time hedging strategies and a supplier scorecard adaptable to different risk appetites.
- Regulatory impact analysis: scenario planning for trade-control regimes and standardization milestones that affect certification and market access.
- Go-to-market frameworks for OEMs and Tier-1s: feature-pricing maps, differentiation opportunities around dual-protocol support, PAM4 implementation, and software-enabled value capture.
Competitive landscape — incumbent moves and fast followers
The report profiles the active vendor ecosystem, illustrating how product roadmaps and partnerships are shaping 2026 battlegrounds. Notable themes include rapid productization among Chinese vendors, dual-protocol strategies, and early moves toward higher-rate link products for cockpit and ADAS applications.
HSMT SerDes Chip Market
- Norelsys (China) — Positioned as a leader in automotive HSMT SerDes chipsets, with mass-produced 12G/12.8Gbps products targeting camera and display applications. Norelsys’ broad HSMT portfolio and production maturity make it a key reference for OEM qualification timelines.
- Rsemi (Nanjing Rsemi Technology, China) — Recently showcased a 32Gbps display SerDes (Auto China 2026 debut), signaling a push into high-bandwidth cockpit architectures and revealing where next-generation requirements will concentrate.
- Nanochip (China) — Early mover with 6.4G HSMT solutions positioned as a benchmark for in-vehicle link performance; useful for benchmark and legacy-replacement strategies.
- Ruifa Technology (China) — Demonstrated breadth at major industry exhibitions with mass-produced variants across a broad rate spectrum, underscoring domestic supply-chain depth.
- Velinktech (Venlinktech Microelectronics, China) — Noteworthy for dual-protocol offerings (MIPI A-PHY and HSMT) and a launched PAM4 12.8Gb/s product in mass production with a leading OEM — a model for commercial adoption pathways.
- Naxin Micro & Shouchuan Micro (China) — Represent the wave of firms delivering automotive-grade HSMT implementations that leverage domestic manufacturing and supply-chain integration.
Recent product and commercial milestones (selected)
- Early 2025–2026 product debuts and mass-production announcements have validated the technical feasibility and manufacturability of HSMT SerDes at multiple bandwidth points, reducing technical uncertainty for OEM adoption.
- Automotive OEM engagements and initial model integrations demonstrate that qualification cycles are compressing for established vendors who can deliver automotive-grade quality and supply assurances.
- Exhibitions and partnerships in 2025–2026 have accelerated ecosystem validation, making 2026 a critical junction for vendors and customers to commit to specific protocol roadmaps.
Supply chain, cost and regulatory implications for 2026
Executives must balance multiple, sometimes opposing forces in 2026:
- Lead-time improvements vs. persistent tightness. While industry reports show lead-time improvements for relevant mature nodes (moving into a 16–26 week range amid capacity expansions), adequate inventory strategies remain essential during peak qualification and ramp phases.
- Pricing pressure from adjacent demand. Memory and analog component pricing pressures — driven by AI-related demand spillover — can elevate BOM costs for SerDes solutions and compress OEM margins unless mitigated via long-term procurement or design consolidation.
- Geopolitical risk. Ongoing export controls and tariffs encourage localization in certain markets while elevating transaction costs for cross-border suppliers — a strategic consideration for global OEMs that must balance compliance with performance and cost.
Strategic recommendations for 2026 (prioritized, executable)
- Adopt a dual-path protocol strategy. For OEMs serving multiple geographies, prioritize suppliers that can support both HSMT and alternative standards (e.g., dual-protocol silicon) to minimize regional lock-in and maintain optionality.
- Fast-track qualification with tiered commitments. Use staged volume commitments tied to performance milestones to secure capacity from leading vendors while preserving flexibility to pivot as protocol adoption clarifies.
- Hedge critical BOM components. Negotiate medium-term purchase agreements for analog and memory items and maintain strategic buffer inventories to avoid margin erosion from short-term price spikes.
- Pursue targeted partnerships and minority investments. Use commercial alliances or minority equity in strategically positioned suppliers to accelerate roadmap access and de-risk supply without full integration overhead.
- Embed regulatory scenario planning into product roadmaps. Map alternative sourcing and certification playbooks for the most probable trade-control scenarios and align R&D timelines to the slowest majority path for multiregion launches.
What we deliberately withhold — why you need the full report
In line with PW Consulting’s “trailer” approach, this release highlights the strategic contours and actionable priorities emerging from our analysis but intentionally omits granular subsegment tables, region-by-application revenue splits and model-level company shares. Those datasets — including our detailed market-model workbook, segmented demand curves and supplier-specific revenue scenarios — are proprietary and available through the full report package. These detailed cells are the decision-grade inputs your procurement, product and M&A teams will use to build 90–180 day execution plans.
Next steps for executive teams
- Download the full report to access the interactive market model and supplier dossiers for qualification scheduling and sourcing optimization.
- Request a tailored briefing with PW Consulting to align your 2026 procurement calendar, product milestones and potential investment targets to the scenarios most relevant to your business footprint.
- Leverage our supplier scorecard template to run rapid, comparable assessments across your incumbent and potential HSMT SerDes partners.
PW Consulting’s HSMT SerDes Chip Market report translates growth forecasts (from USD 1,720 million in 2020 to USD 3,200 million in 2025 and toward USD 7,765 million by 2032 at a 13.5% CAGR) into executable 2026 actions. If your 2026 planning cycle includes decisions on product architecture, supply-chain commitments, or strategic investment in SerDes technology, this report is designed to be the playbook that turns market momentum into competitive advantage.
For detailed analysis of this topic, please visit the official page: HSMT SerDes Chip Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com