

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
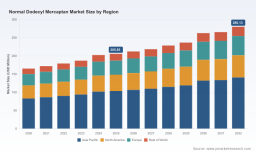
PW Consulting Forecast: Normal Dodecyl Mercaptan Market to Rise from USD 205.85 Million (2025) to USD 280.13 Million by 2032 at 4.5% CAGR — Asia Pacific Leads with USD 103.48M

Normal Dodecyl Mercaptan Market: Strategic Imperatives for 2026 Decision-Makers
As PW Consulting’s Senior Strategic Advisor and Head Industry Analyst, I present a forward-looking synthesis of the Normal Dodecyl Mercaptan (NDM) market drawn from our newly published market study. This briefing highlights the strategic intelligence that corporate leaders, procurement heads, and M&A teams should prioritize as they set budgets and allocate capital in 2026. The intent is to convey the report’s analytical depth and practical value while reserving the granular tables and segmented forecasts for the full report—available on our site.
Normal Dodecyl Mercaptan Market
Market snapshot: what executives need to know
NDM is a small but structurally important specialty chemical: a chain transfer agent in polymerization, an intermediate for antioxidant and additive synthesis, and an occasional flotation reagent in mining applications. Our assessment uses 2025 as the base year, reviews the 2020–2025 historical period, and projects the market across 2026–2032. Key macro takeaways: the market exhibited steady recovery and expansion through the early 2020s, reaching a mid‑hundreds million USD scale by 2025, and is projected to grow at a compound annual growth rate (CAGR) of approximately 4.5% through 2032—reaching a projected market size that materially changes the risk and opportunity calculus for suppliers and consumers alike.
Normal Dodecyl Mercaptan Market
Two quantitative facts deserve immediate attention: (1) the NDM market is meaningfully larger in 2025 than in 2020, reflecting demand growth across polymer and specialty-chemical value chains; and (2) with the 2026–2032 CAGR at roughly 4.5%, the market’s trajectory supports multi-year commitments for capacity, logistics, and regulatory investment rather than short‑term, tactical sourcing alone.
Normal Dodecyl Mercaptan Market
Why this matters for 2026 strategic decisions
- Procurement and contract design: A moderate but steady growth path argues for mid-term offtake and pricing arrangements—three-to-five year structures that balance supplier investment certainty with buyer flexibility. Tactical spot buying will remain useful for managing short-term volatility, but enterprise buyers should layer in indexed and volume‑protected contracts to secure technical grades and continuity.
- Capacity and footprint planning: Given the market’s scale and the product’s EHS footprint, greenfield capacity decisions must factor in permitting and community acceptance timelines as much as economics. For incumbent producers and potential entrants, targeted brownfield expansions and tolling partnerships may present quicker routes to capture upside.
- M&A and partnership activity: The market concentration profile—high concentration among the top suppliers—creates selective openings. Players looking to expand into specialty thiols or to secure backward integration for polymer additives will find potential partners among established producers and regional specialists explored in our competitive analysis.
- Risk management: Feedstock sensitivity and EHS regulation (particularly odor and transportation controls) make integrated supply-line risk assessments essential. Procurement teams should stress-test sourcing strategies against hydrocarbon and sulfur commodity swings and shifting transport/handling rules.
Segment and demand dynamics (what the report covers)
The full study maps demand across regional markets, product-purity tiers, and end-use applications, and outlines the manufacturing routes and upstream feedstock exposures that drive cost volatility. It includes detailed scenario analyses that capture the effects of feedstock price swings (dodecene/propylenic intermediates, hydrogen sulfide) and regulatory tightening on manufacturing, storage and logistics. While we purposely withhold the detailed segment-level tables in this summary, readers should note the report’s practical modules:
- Market sizing with historical series and a 2026–2032 forecast horizon, reported in USD (Million).
- Unit economics and cost‑curve modeling for representative production routes, including bromide‑based syntheses and alternative organosulfur processes.
- Supply-chain vulnerability assessments that quantify exposure to feedstock price drivers and transportation constraints.
- Regulatory and EH&S impact matrices—operational levers to reduce community friction and avoid costly operational pauses.
Competitive landscape: focused, consolidated, and strategic
NDM supply is concentrated. Our concentration analysis shows a market where the top three producers control a substantial share of capacity, and the top five comprise a dominant portion of commercial availability. This structure influences pricing power, contracting behaviors, and how quickly supply can scale to meet shifts in demand.
The study profiles established global producers alongside capable regional manufacturers and specialty suppliers. Highlights include:
- Chevron Phillips Chemical Company (The Woodlands, TX): Integrated petrochemical and specialty streams position this incumbent as a reliable source for industrial‑scale chain transfer agents and additive intermediates. Their global trading and logistics footprint supports multinational supply chains.
- Arkema (Colombes, France): A global supplier with strong application expertise in styrenics and acrylic polymerization, Arkema combines formulation support with global distribution, which matters for polymer producers seeking technical partnerships.
- Chinese and Indian manufacturers: Several China- and India‑based firms—ranging from ISO‑certified industrial producers to R&D‑driven specialty houses—offer competitive cost positions and regional responsiveness. These players are important supply alternatives, especially for market participants prioritizing price and lead‑time efficiencies.
- European and Japanese specialty producers: Select small‑to‑mid sized companies provide differentiated grades and local support where EHS compliance and odor‑management capabilities are decisive.
For buyers, supplier selection should weigh not only price and capacity, but also EHS handling competence, backward integration (feedstock control), and the ability to meet specific polymerization or additive specifications. For producers, near‑term opportunities lie in service differentiation (e.g., handling, odor mitigation, grade stability) and targeted upstream integration to moderate feedstock exposure.
Recent industry developments and their implications
Operational and application-level shifts continue to reshape demand patterns. A notable example during the review period was a mining project optimizing its flotation flowsheet to remove NDM as a reagent—an explicit reminder that end‑users refine chemistries based on cost, regulatory and EH&S trade-offs. Such changes can rapidly affect local demand pockets despite stable underlying polymer-driven growth.
On the upstream side, the material’s production pathways—from dodecanol conversion routes to alternative organosulfur syntheses—mean feedstock and energy prices feed directly into producer margins. The industry also faces persistent regulatory scrutiny given the compound’s odor and handling risks, which can add non-trivial compliance costs and influence logistics planning.
Actionable recommendations for 2026
- Adopt a layered procurement strategy: Combine multi-year contracts with indexed clauses, strategic spot purchases, and optionality for capacity flex. This balances cost control with resilience against feedstock swings.
- Pursue strategic partnerships: For firms seeking to expand formulations or secure availability, tolling agreements, joint ventures, or off‑take arrangements with regional specialty players can compress lead times and share EHS responsibilities.
- Stress-test operations for EHS and community risk: Invest in odor mitigation, community engagement protocols, and transport packaging solutions—these are often lower-cost mitigations versus lost production or permit delays.
- Model multiple sourcing scenarios: Use quantitative scenario planning in which feedstock and regulatory variables are stressed; identify the marginal supplier in each scenario and negotiate accordingly.
- Scan for opportunistic M&A: Given the high concentration at the top, selective acquisitions of regional or specialty producers can secure technical competencies and expand margin capture.
What the full report delivers
PW Consulting’s full Normal Dodecyl Mercaptan Market Report provides the granular data, supplier scorecards, and financial models required to operationalize the strategic guidance summarized here. Subscribers gain access to:
- Detailed segment-level forecasts and demand tables (regional, purity grade, application),
- Cost and margin models for alternative production routes,
- Supplier capability matrices and CR‑level analysis,
- Scenario playbooks for procurement, plant investment, and M&A decisions, and
- Practical checklists for EH&S and logistics mitigation.
For executives preparing 2026 budgets, capital allocation committees looking at specialty chemical exposures, or procurement teams negotiating multi-year contracts, the report translates market dynamics into concrete levers. Our analysis balances market-level forecasting—anchored by a 4.5% CAGR outlook—with pragmatic action steps tailored to the concentrated supplier base and the compound’s EHS realities.
Next steps
If your team is evaluating supply‑chain resilience, considering capacity investment, or assessing potential M&A in specialty thiols and polymer additives, PW Consulting’s full report contains the proprietary tables and supplier‑level intelligence needed to de‑risk those decisions. Visit our report page to access the complete dataset, supplier profiles, and scenario models that will inform 2026 planning and beyond.
For detailed analysis of this topic, please visit the official page: Normal Dodecyl Mercaptan Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com