

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Semiconductor Part Refurbishment Repairs Market to Reach USD 8.23 Billion by 2032 on 7.85% CAGR, Asia Pacific Holds USD 2.45 Billion Share

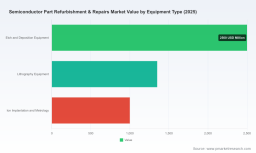
Semiconductor Part Refurbishment & Repairs: Strategic Imperatives for 2026 — PW Consulting Market Brief
PW Consulting’s new market study on the Semiconductor Part Refurbishment & Repairs market synthesizes multi-year historical tracking and a robust forward-looking model to give senior leaders the actionable intelligence they need to navigate supply-chain stress, regulatory friction, and accelerating fab investment. This briefing frames the report’s strategic value for decisions to be made in 2026 while intentionally preserving the granular segment tables and proprietary assumptions for subscribers.
Semiconductor Part Refurbishment Repairs Market
Executive summary
After tracking the market through a detailed 2020–2025 historical calibration, our baseline shows the global Semiconductor Part Refurbishment & Repairs market at approximately USD 4.85 billion in the base year (2025). Under a set of conservative-to-base assumptions, the market is projected to grow at a compound annual growth rate (CAGR) of 7.85% over the 2026–2032 forecast horizon, reaching roughly USD 8.23 billion by 2032. This trajectory is driven by three structural forces: continued fab expansion and capital intensity, constrained new-part availability and extended lead times, and an industry-wide cost optimization push that increases the attractiveness of refurbishment and parts-reuse strategies.
Semiconductor Part Refurbishment Repairs Market
Why this report matters for 2026 corporate decisions
- Strategic procurement and inventory planning: The combination of extended lead times and periodic price uplifts in core semiconductor components means organizations must reassess inventory policies and total landed-cost models. Our analysis links repair/refurbishment economics directly to procurement KPIs and TCO thresholds most relevant in 2026.
- CapEx vs. Opex trade-offs: As fabs scale and diversify, decisions about investing in in-house refurbishment capability versus outsourcing will hinge on utilization scenarios. We provide a financial framework and scenario outputs that show the breakpoints where in‑house capability becomes accretive.
- Regulatory and geopolitical decisioning: With evolving export controls and new tariff structures effective in early 2026, maintenance and repair strategies are being recast — particularly where cross-border transfers, licensing, and domestic exceptions apply. The report maps the practical contours of these rules and their operational impacts.
- M&A and partnership targeting: The market’s moderate concentration profile and specialized service footprints create distinct windows for bolt-on acquisitions and strategic partnerships. Our competitive lens surfaces acquisition targets and illustrative valuation multiples (available in the full report) aligned to 2026 exit and growth plans.
Market trajectory and what the numbers tell us
Using a data-led approach that triangulates supplier financials, end-user fab buildouts, and observed replacement/repair cycles, the report establishes a clear mid-term growth path: from roughly USD 4.50 billion in 2024 to USD 4.85 billion in 2025, then continuing toward an estimated USD 5.23 billion in 2026 and into the high single-digit billions by the early 2030s. The 7.85% CAGR reflects recurring service demand for legacy and current-generation tools, rising refurbishment economics as a response to supply constraints, and steady aftermarket penetration within new fab projects.
Semiconductor Part Refurbishment Repairs Market
Report contents — practical and operational deliverables
Designed for operating executives, procurement leads, and corporate development teams, the full report contains:
- Detailed market-sizing and 2026–2032 forecast models (with sensitivity scenarios and downloadable spreadsheet templates).
- Service- and equipment-level playbooks that translate market demand into operational KPIs: lead-time-to-repair, mean-time-to-return, warranty exposure, and parts obsolescence curves.
- Regulatory impact matrix that maps recent policy changes to practical operating responses (including how certain tariff exclusions apply to repair activities in the United States).
- A prioritized list of opportunities for cost reduction, near-term revenue capture, and margin expansion for aftermarket service providers.
- Deal-sourcing guidance and a shortlist of target profiles for M&A and strategic JV activity, with integration risk checklists.
Competitive landscape — what incumbents and specialists bring to the table
The aftermarket for semiconductor parts is populated by a mix of highly specialized repair houses, regional distributors with service offerings, and engineering-focused refurbishers. PW Consulting’s competitive analysis spotlights capabilities and strategic postures of market participants to help acquirers and partners align to 2026 objectives:
- IES Semiconductor Parts (Bristol, UK) — A specialist in repair and testing for a broad range of manufacturing parts. Their emphasis on extending legacy equipment life and offering warranty-backed services makes them attractive to fabs preserving long-lived tool assets, especially in markets where OEM obsolescence is accelerating.
- PSI Semicon Services (Livonia, MI, USA) — A full-service provider whose breadth across robotics, controllers, power systems, and vacuum components positions them as a one-stop shop for North American fabs seeking to rationalize supplier count while maintaining legacy support.
- SemiGroup (Dallas, TX, USA) — Focused on refurbishing to OEM-grade specifications with installation and maintenance support. Their model is aligned to customers that require turnkey refurbish-install-warranty solutions to minimize downtime risk.
- Capitol Area Technology (Austin, TX, USA) — Combining distribution and repair, CAT offers transactional flexibility that appeals to smaller fabs and contractors balancing capital constraints with uptime requirements.
- Ichor Systems (Fremont, CA, USA) — Noted for engineering-led refurbishments of processing equipment with deep tool integration capability; they serve customers that need design engineering tied to refurbishment for performance restoration.
- Semiconductor Support Services Co. (SSSco) (Austin, TX, USA) — Provides repairs, upgrades, and parts across major OEM tool families, an advantage where multi‑vendor homogeneity is low and cross-platform expertise reduces mean time to recovery.
- Conation Technologies (USA) — A niche provider focused on equipment from specific test and inspection OEMs, useful for fabs where inspection tool uptime is mission-critical.
Collectively, the competitive field shows a mix of complementary strengths: engineering depth, warranty-backed offerings, regional service networks, and logistics capabilities. For corporate strategy teams, the question is not whether to interact with these providers, but how to structure relationships (preferred-supplier, JV, or full acquisition) to lock in capacity and expertise as fabs scale in 2026.
Market dynamics and external shocks shaping 2026 strategies
- Price volatility: Recent supplier price actions (industry reports in early 2026 indicate increases in semi component pricing of 15–35% in some lines) create a renewed ROI case for refurbishment and parts reuse versus sourcing new components.
- Lead-time pressures: Select device categories have trended toward protracted delivery windows (observed trending into the high tens of weeks for some SKUs), reinforcing the strategic value of repair networks and validated refurbished inventories.
- Regulatory shifts: The U.S. Section 232 proclamation effective January 2026 introduces tariffs on certain advanced semiconductors, but crucially includes carve-outs for repair, replacement, and R&D performed domestically — a structural tailwind for U.S.-based refurbishers and for onshore maintenance strategies.
- Geopolitical controls: Export controls and licensing requirements remain a central operational complexity for cross-border maintenance activities. The report provides a decision matrix that ties asset-class risk to licensing pathways.
- Fab investment: With projected global fab spending exceeding USD 1.5 trillion across a multi-year window, sustained capex supports long-term demand for aftermarket services and creates opportunities to embed refurbishment options into factory build contracts.
- Notable developments: Recent facility and investment moves — for example, the launch of a new eco-focused refurbishment facility in Singapore (early 2025) and the wave of U.S. fab project announcements since the CHIPS Act — are changing the geography of aftermarket services and the economics of material recovery.
Opportunities, risks, and recommended 2026 actions
For corporate leaders, the practical decision agenda for 2026 should include the following prioritized actions:
- Recalculate spare-parts policy thresholds using the report’s scenario module — adjust reorder points to reflect new lead-time distributions and price volatility shocks.
- Establish or expand “shop-in-shop” refurbishment capacity where utilization and mix justify fixed-cost investment; otherwise, consolidate outsourcing with 2–3 strategic partners under long-term SLAs that include capacity guarantees and performance penalties.
- Leverage regulatory carve-outs: structure certain maintenance and R&D activities domestically to mitigate tariff exposure and expedite licensing for controlled repairs.
- Pursue selective M&A to acquire engineering capabilities or regional footprint quickly — target profiles include niche engineering refurbishers, warranty-capable installers, and parts-diagnostic specialists.
- Integrate sustainability KPIs into refurbishment contracts to capture material-recovery and circular‑economy benefits that increasingly matter to customers and regulators.
Conclusion & next steps
Our analysis confirms that the Semiconductor Part Refurbishment & Repairs market is neither marginal nor purely tactical — it is a strategic lever for resilience, cost control, and competitive differentiation in 2026 and beyond. With market size rising from the mid‑single billions in the mid‑2020s to the high single‑digit billions by the early 2030s at a 7.85% CAGR, organizations that treat aftermarket strategy as a core pillar of supply‑chain and asset management will materially outperform peers on uptime and cost metrics.
To access the full dataset, segmented forecasts, scenario spreadsheets, and the detailed company benchmarking that informed these conclusions, please visit the PW Consulting report page. The full report contains the granular tables, regional and service splits, and the proprietary sensitivity tests that strategic teams will need to operationalize action plans for 2026.
For detailed analysis of this topic, please visit the official page: Semiconductor Part Refurbishment Repairs Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com