

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
PW Consulting: Low Salted Sodium Hypochlorite Market Poised for 5.29% CAGR Through 2032
By pmarketresearch, 2026-07-06
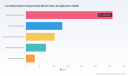
Low Salted Sodium Hypochlorite Market — Strategic Briefing for 2026
Executive summary
The Low Salted Sodium Hypochlorite market is transitioning from a niche specialty product into a predictable, margin-supporting commodity for water-treatment and industrial disinfectant users. Our new PW Consulting report (base year 2025; historical window 2020–2025; forecast 2026–2032) quantifies this transition and translates it into practical decision levers for executives preparing budgets, procurement strategies, and technical pilots in 2026.
Low Salted Sodium Hypochlorite Market
At the macro level, the global market expanded from roughly USD 502 million in 2020 to USD 648.5 million in 2025, and our model projects an expansion to approximately USD 930.3 million by 2032 — implying a compound annual growth rate of 5.29% across the forecast window. That steady growth, together with a mid-level market concentration profile, makes the segment strategically attractive for suppliers seeking scale and for buyers looking to lock in predictable supply and performance gains.
Low Salted Sodium Hypochlorite Market
Why this matters for 2026 corporate decisions
-
Budgeting and procurement: The market’s steady CAGR gives procurement teams a defensible planning envelope for 2026–2028 purchasing and inventory policies. Organizations that move from ad hoc buying to contract structures tied to product-grade performance (rather than only price per liter) can expect improved uptime and lower total cost of ownership.
Low Salted Sodium Hypochlorite Market -
Operational optimization: Recent field validations indicate high-strength, low-salt formulations can materially reduce dosing volumes, degradation losses, and equipment wear. For water utilities and industrial users, 2026 is the window to plan pilot-to-scale substitutions that can free operational budget for capital maintenance or compliance work.
-
Regulatory and stewardship alignment: Certification and product-stewardship documentation are becoming procurement gatekeepers. Buyers and suppliers that align product specifications with recognized standards will shorten validation cycles and accelerate adoption.
What the report delivers — practical content for immediate action
-
Validated market sizing and trajectory: rolling historical estimates (2020–2025) and a scenario-driven forecast (2026–2032) in USD Million, enabling CFOs to stress-test investment cases under conservative, base, and upside demand scenarios.
-
Use-case ROI worksheets: templated analyses for municipal, industrial cooling, food & beverage, and healthcare segments that translate product performance (dosing, shelf life, impurity profile) into OPEX and CAPEX impacts.
-
Procurement playbooks: contract clauses, specification checklists, and tender language that emphasize verified purity, handling requirements, and shelf-life testing rather than headline pricing alone.
-
Supplier scorecards and risk heatmaps: a repeatable framework to evaluate supply concentration, logistics risk, and stewardship readiness — designed for procurement and risk committees to operationalize in 60–90 days.
-
Pilot design templates and KPIs: pragmatic trial designs that replicate field tests demonstrating dosing reduction and stability, including sampling protocols, acceptance criteria, and statistical thresholds for go/no-go decisions.
-
Regulatory alignment checklist: mapping of major certifications and their procurement implications for public utilities and regulated industries, plus recommended interactions with local regulators during specification updates.
Competitive landscape — what buyers and strategists need to know
The market combines several long-established chlor-alkali players and specialized producers. Top producers differentiate on a few clear vectors: concentration (wt% NaOCl), impurity control (chlorate, perchlorate, heavy metals, bromates), filtration and certification (e.g., NSF/ANSI, JWWA), and geographic manufacturing footprint. The market concentration metrics point to a competitive environment where the top suppliers provide nearly half of available volume — sufficient to shape product specifications, but still offering opportunities for regional and technical challengers.
-
Kuehne Company (NJ, USA) — a private chlor-alkali producer that markets concentrated, low-salt formulations under branded product positioning emphasizing long-term stability in municipal applications. Their value proposition focuses on reliability and proven field tenure.
-
HASA Inc. (Valencia, CA, USA) — a leading supplier of premium low-salt hypochlorite, including high-strength variants. Recent independent trial data show substantial dosing reductions and operational benefits versus conventional strengths, making HASA a reference point for performance-based procurement pilots.
-
Olin Corporation (Clayton, MO, USA) — an integrated chlor-alkali incumbent offering high-concentration, low-impurity products alongside a public-facing stewardship manual. That manual signals an industry shift: suppliers are investing in documentation and handling guidance that shorten buyer qualification cycles.
-
Shin-Etsu Chemical (Tokyo) and Kaneka Corporation (Osaka) — established Japanese producers whose low-impurity grades meet stringent domestic water chemistry certifications and appeal to public utilities and food-grade users where specification purity is non-negotiable.
Collectively, these suppliers illustrate two strategic truths: senior buyers will increasingly base supplier selection on validated, field-proven performance and documented stewardship; and suppliers that bundle technical support, certification, and logistics reliability will command the premium portion of the market.
Recent developments that reshaped the 2025–2026 decision agenda
-
Performance validation: A mid-2025 trial conducted at a wastewater treatment facility demonstrated substantially lower usage volumes and improved consistency for a 15.5 wt% high strength low-salt product versus a conventional 12.5 wt% baseline. The practical consequences were lower operating volumes, reduced chemical handling, and measurable operational savings.
-
Formalized stewardship: An incumbent supplier issued an updated product stewardship manual in 2025 that details production capabilities, purity improvements, and handling specifications for super-concentrated low-salt grades. The document reduces buyer onboarding friction and creates a template for industry best practice.
-
On-site generation alternatives: Parallel to blended and concentrated supply strategies, on-site hypochlorite generation systems are maturing and becoming a valid substitute in some use-cases. These systems materially change logistics and procurement trade-offs by eliminating bulk transport and reducing storage risk.
Strategic implications and recommended 2026 actions
-
Run three targeted pilots in 2026: one municipal water utility, one industrial cooling application, and one food-processing site. Use the report’s pilot templates and KPI sets to capture dosing, degradation, equipment impact, and total delivered cost over a 12–18 month window.
-
Revise procurement specifications: Move from density/active-titer-only contracts to performance-and-stewardship contracts that include impurity limits, shelf-life guarantees, and documented handling guidance. Include supplier-provided trial data as contractual proof points.
-
Assess on-site generation as a strategic option: For sites with predictable, high, and continuous demand, build a 5-year TCO comparison that includes capital amortization, energy, labor, and avoided transport risk versus contracted supply.
-
Prepare supply-security playbooks: Given a moderately concentrated supplier base, identify secondary suppliers and logistical redundancies now, and incorporate these requirements into 2026 procurement RFPs.
-
Invest in specification harmonization: For multi-site organizations, centralize chemical specifications and validation protocols to achieve consistency in safety, regulatory compliance, and dosing performance.
Methodology and data reliability
The underlying market model uses a bottom-up build combining historical shipment data (2020–2025), supplier-reported capacities, and end-user dosing surveys validated with field trials and third-party certifications. Forecast scenarios (2026–2032) incorporate demand elasticity for higher-strength grades, potential substitution from on-site generation, and regulatory adoption curves. All financials are expressed in USD Million with a base year of 2025 and a consolidated CAGR of 5.29% for the forecast window.
How to use this briefing — and where to find the rest
This is a strategic briefing designed to accelerate executive alignment in 2026. If you are evaluating pilots, revising procurement language, or considering supplier collaborations, the full PW Consulting report contains the segment-level tables, supplier scorecards, scenario spreadsheets, and the detailed ROI models that operational teams will need to execute.
We intentionally withhold the granular regional and application split tables in this summary to preserve the integrity of the model and to ensure downstream conversations are anchored to validated purchase access. Access to the complete dataset, editable financial models, and supplier diligence files is available through our report portal and advisory engagements.
For procurement leaders, operations VPs, and strategy teams preparing 2026 roadmaps: the decisions you make now on specification design, pilot funding, and supplier governance will determine whether your organization captures the operational savings and reliability gains that low-salt hypochlorite can deliver — or whether those gains are captured by peers and competitors instead.
For detailed analysis of this topic, please visit the official page: Low Salted Sodium Hypochlorite Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: ESRD market to surge from $152.3B in 2025 to $305.4B by 2032 at a 10.45% CAGR — Dialysis alone tops $133.6B in 2025
By pmarketresearch, 2026-07-06
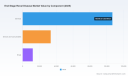
End Stage Renal Disease Market: Strategic Imperatives for 2026 Decision‑Making
PW Consulting’s new End Stage Renal Disease (ESRD) Market Research Report is designed as the decision support tool C‑suite teams, corporate development groups, and health systems will rely on when shaping 2026 investment and commercialization plans. Our base‑year analysis (2025) anchors a forward view across 2026–2032 that demonstrates a pronounced acceleration: the global ESRD market expands from USD 152,306.45 Million in 2025 to USD 305,407.41 Million by 2032, reflecting a compound annual growth rate (CAGR) of 10.45% across the forecast window. This briefing highlights the strategic value of the report for executive decision cycles while intentionally withholding core sub‑segment level tables — the detailed, slice‑by‑slice intelligence is available in the full report.
End Stage Renal Disease Market
Why this report matters for 2026
-
Timing. 2026 marks a tactical inflection for ESRD markets: newer modalities, device platforms and a shifting reimbursement backdrop are converging. Companies must reconcile short‑term access and margin pressures with long‑term product and service investments.
End Stage Renal Disease Market -
Scale and velocity. Our top‑line projections reveal a market roughly doubling over the forecast horizon, driven by technology adoption, expanded access, and new care models. This creates both opportunity (new revenue pools) and risk (accelerated obsolescence for legacy systems).
End Stage Renal Disease Market -
Decision focus. The report translates macro growth into actionable choices: which modalities to prioritize, where to double down on clinical evidence generation, and how to align commercial models with payers that are increasingly demanding outcomes and cost‑efficiency.
What is inside — practical, executable content
-
Robust market model: a bottom‑up forecast (2026–2032) with scenario sensitivity to volume, pricing, and reimbursement shocks. Note: the headline model and aggregated market totals are summarized herein; detailed subsegment breakouts are reserved for the full report to preserve competitive integrity.
-
Five strategic scenarios: our base case is complemented by conservative and accelerated adoption pathways that quantify revenue, unit demand, and margin implications under varying clinical and regulatory assumptions.
-
Regulatory & payer playbook: a pragmatic guide to navigating the current reimbursement environment, including scenario templates for contract negotiations tied to outcomes‑based arrangements.
-
Commercialization & go‑to‑market frameworks: country‑level market entry checklists, prioritization matrices for modality and channel (in‑center vs. home vs. acute), and digital adoption roadmaps.
-
Competitive intelligence and sourcing maps: capability heatmaps for incumbent and emerging players, supplier dependency analyses, and M&A target shortlists ranked by strategic fit and integration complexity.
-
Operational readiness tools: supply chain resilience playbooks, clinical rollout templates for new device launches, and cybersecurity readiness checklists for dialysis platforms with connected components.
Market dynamics: what is changing and what it means
The ESRD market's growth is not monolithic — it is the aggregate result of evolving care pathways, technology advances, and policy changes. Key dynamics that the report examines in depth include:
-
Modal shift and decentralization: home dialysis and hybrid delivery models are gaining traction. Device makers and service providers who can offer simplified, connected platforms will capture a greater share of incremental growth.
-
Technology convergence: next‑generation dialysis platforms emphasize usability, cybersecurity, and connectivity. Regulatory clearances for updated software and enterprise capabilities (e.g., recent FDA clearances for modernized systems) create windows for commercial differentiation.
-
Value‑based care pressure: payers are increasingly focused on total cost of care and patient outcomes. Expect procurement processes to reward demonstrated reductions in hospitalization, infection rates, and overall cost per patient episode.
-
Reimbursement headwinds and tailwinds: the CY 2026 ESRD Prospective Payment System (PPS) final rule nudges base reimbursement upward and maintains labor‑share and wage‑index protections that materially affect facility economics. Operators and vendors must update financial models and contracting approaches in response.
Competitive landscape — who to watch and how to think about competition
The market remains concentrated among a handful of vertically integrated players, with CR3 and CR5 metrics indicating material market share captured by the largest groups. Our competitive analysis synthesizes product portfolios, service footprints, and strategic trajectories for incumbents and challengers. Highlights:
-
Fresenius Medical Care: maintains leadership through a combined product and clinic model. Its platform strategy — combining high‑volume hemodiafiltration systems, clinic networks, and value‑based care offerings — creates a compelling integrated proposition. The planned U.S. commercialization of its high‑volume HDF platform in 2026 is a strategic accelerant that will influence competitor roadmaps.
-
Baxter and other device specialists: firms focused on peritoneal dialysis, consumables and home modalities are staking claims in adjacent growth pockets. Their agility in product iterations and supply agreements makes them strategic partners for payers and providers pursuing home‑first strategies.
-
Large service operators (e.g., DaVita): scale in outpatient center networks and care management services enables negotiating leverage with suppliers and payers. Their investments in home programs and care coordination are key strategic indicators to monitor.
-
Innovative platform disruptors (e.g., Outset Medical, Quanta): newer all‑in‑one and compact systems, especially those receiving regulatory clearances and bolstered cybersecurity features, alter the economics of deployment across acute, chronic, and home settings.
-
Specialist suppliers (Nipro, B. Braun, Asahi Kasei, Toray, JMS, Nikkiso, Medtronic): these companies underpin the device and consumable supply chain; their product innovations, manufacturing footprints, and distribution partnerships determine margin resilience and the pace of clinical adoption.
For each company profiled in the report, we provide a strategic scorecard: product roadmap alignment, clinical evidence generation, channel and service capabilities, and M&A/partnership optionality. Recent public developments — including major annual disclosures, product clearances, and payer rules — are synthesized into implications for competitive positioning and tactical moves for 2026.
Strategic priorities for market entrants and incumbents in 2026
-
Prioritize modular product strategies. Design platforms that can be upgraded via software and consumables to extend device lifecycles and capture recurring revenue.
-
Invest in clinical evidence early. Demonstrating reductions in hospitalization and total cost of care is vital for securing preferred network status and higher‑value contracting.
-
Build payer engagement playbooks. Use the report’s reimbursement templates to model the financial impact of alternative payment arrangements and to construct outcome‑linked proposals.
-
Secure supply‑chain optionality. Dual‑sourcing critical consumables and creating near‑term inventory strategies will reduce exposure to geopolitical and production disruptions.
-
Emphasize cybersecurity and interoperability. As dialysis platforms become connected, enterprise‑level security and data‑integration capabilities will be procurement differentiators.
-
Adopt an M&A and partnership lens. With meaningful concentration at the top of the market, strategic bolt‑on acquisitions and ecosystem partnerships can accelerate access to care networks and product portfolios.
How PW Consulting’s report will change your 2026 playbook
This report is constructed as a practical execution manual, not an academic exercise. Alongside the headline market trajectory, it contains:
-
Actionable financial models you can plug into internal planning systems to test product launches, pricing strategies, and contract outcomes against the market forecast.
-
Negotiation templates and risk‑adjusted ROI calculators for outcomes‑based contracting.
-
A prioritized set of M&A and partnership candidates mapped to capability gaps common among device makers, service operators and payers.
-
Field‑tested clinical rollout and training plans to compress time‑to‑adoption and limit early‑stage clinical variability.
Next steps and how to access the full intelligence
The material in this press briefing showcases the depth and strategic orientation of PW Consulting’s ESRD market research while deliberately reserving the core sub‑segment data tables and tactical scorecards for the full report. For commercial teams preparing 2026 budgets, corporate development teams evaluating M&A targets, and health systems negotiating payer contracts, the full report provides the granular segmentation, channel forecasts, and validated unit price curves necessary to finalize decisions.
Contact PW Consulting to schedule a briefing, obtain the full dataset, or request a tailored workshop that maps our findings to your business model and 2026 operating plan. Our analysts are prepared to run custom scenario analyses and to support rapid integration of the report’s outputs into board‑level decision materials.
PW Consulting: translating market scale into executable strategy for the rapidly evolving ESRD landscape.
For detailed analysis of this topic, please visit the official page: End Stage Renal Disease Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecast: Audit Management Software Market to Reach USD 5,887.06 Million by 2032, Growing at an 11.2% CAGR
By pmarketresearch, 2026-07-06
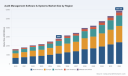
Audit Management Software Systems Market 2026: Strategic Intelligence for Executive Decision-Making
PW Consulting today releases its authoritative market research brief on the Audit Management Software Systems market, designed as a strategic playbook for enterprise leaders, IT and GRC executives, and procurement teams planning for 2026 and beyond. The report synthesizes proprietary modeling with primary interviews and offers an operationally focused roadmap — revealing the competitive dynamics, regulatory inflections, and technology levers that will matter most to organizations seeking to modernize audit, compliance, and controls programs.
Audit Management Software Systems Market
Why this report matters in 2026
-
Rapid market expansion: The audit management software market has accelerated from a COVID-impacted baseline to a robust growth trajectory, surpassing the multi-billion dollar mark in the mid-2020s and continuing on a steep growth path through 2032. PW Consulting’s forecast models show compound annual growth of 11.2% across the forecast window, reflecting sustained demand for automation, analytics, and integrated GRC capabilities.
Audit Management Software Systems Market -
Strategic inflection point for buyers: As organizations move beyond point solutions, the 2026 purchasing cycle is defined by three strategic priorities — risk-informed automation, governed AI adoption, and seamless integration with finance, ERM and privacy tooling. Decisions made this year will determine whether organizations capture efficiency gains and risk reduction or face costly rework and compliance exposure as regulation tightens.
Audit Management Software Systems Market -
Regulatory and labor pressure: With jurisdictional changes such as the phased enforcement of AI governance rules and a proliferation of privacy laws, enterprises must select platforms that combine demonstrable governance controls with scalable integrations. Concurrently, rising labor costs and auditor shortages are pushing buyers to prioritize solutions that materially reduce manual evidence collection and repetitive testing.
Market dynamics at a glance
-
Scale and velocity — The market’s macro trajectory underscores a transition from discrete audit tooling to unified platforms that embed controls, risk, and compliance workflows. The sizeable year-over-year increases we tracked during 2020–2025 culminate in a strong base year for 2025, setting the stage for the forecast period (2026–2032) where demand is expected to more than double from early-decade levels by the end of the horizon.
-
Consolidation with choice — Market concentration metrics indicate a mixed landscape: the top three vendors account for an appreciable share of vendor revenue, while the top five widen that share further, signaling continued consolidation alongside a healthy cohort of specialist challengers. This structure creates opportunities for both enterprise incumbents and nimble newcomers to capture adjacent use-cases.
-
Cloud-first acceleration — Subscription delivery models and cloud-native architectures are rapidly becoming default procurement preferences due to cost predictability and ease of integration. Our analysis demonstrates that cloud platforms are unlocking faster time-to-value for audit teams, particularly when paired with pre-built connectors and analytics libraries.
What the PW Consulting report contains — practical tools for 2026 decisions
This report is deliberately operational. Beyond market sizing and high-level forecasts, PW Consulting delivers a suite of decision-ready assets that procurement and GRC leaders can deploy immediately:
-
Executive playbook: A step-by-step framework for aligning audit technology investments with enterprise risk appetite, including prioritization matrices and business case templates for CFO/CAO sponsorship.
-
Vendor shortlists and fit-mapping: A methodology to map vendor capabilities to common enterprise archetypes (finance-led audit, distributed field audits, regulated services firms), with scenario-based recommendations for first-, second-, and third-wave purchases.
-
Integration and deployment blueprints: Technical checklists for API readiness, data lineage requirements, and end-to-end implementation timelines that reduce deployment risk and accelerate adoption.
-
AI governance and controls framework: Practical controls and test plans for the safe adoption of embedded AI/ML features — aligning product selection with regulatory obligations and change-management realities.
-
ROI and TCO calculators: Configurable models that quantify labor savings from automation, reduction in audit cycle times, and comparative total cost of ownership for cloud vs. on-premises deployments.
-
RFP templates and scoring rubrics: Ready-to-use documentation to shorten procurement cycles and ensure responses are evaluated against security, data residency, and modern GRC requirements.
-
Use case playbooks and case studies: Real-world examples showing how organizations recaptured audit capacity, improved issue remediation timelines, and created audit-ready evidence streams.
Competitive landscape — positioning and practical implications
The audit management market is diverse — a mix of specialist platforms, integrated GRC suites, and enterprise ERP vendors expanding into audit. PW Consulting’s vendor profiles combine product capability assessment with go-to-market posture and implementation risk. Key observations include:
-
AuditBoard (Optro) — Positioning: A connected risk platform focused on unified GRC workflows. Strategic implication: Strong fit for organizations seeking consolidated audit, risk, and compliance workflows with growing AI-enabled capabilities. Recommended action: Evaluate for organizations prioritizing breadth of workflow connectivity and a modern UX.
-
Workiva — Positioning: Cloud-based integrated reporting and audit solutions with governed AI targeted at finance and sustainability reporting. Strategic implication: Suited for enterprises where audit ties closely to reporting cycles and regulatory disclosures. Recommended action: Consider when advanced reporting and data lineage for financial or ESG disclosures are primary requirements.
-
Diligent — Positioning: Platform integrating governance, risk, compliance, and audit with AI-enhanced tooling. Strategic implication: Attractive for boards and governance teams seeking a single-pane oversight approach. Recommended action: Assess for organizations wanting to centralize board reporting, compliance, and audit workflows.
-
Wolters Kluwer (TeamMate) — Positioning: End-to-end internal audit management covering planning, execution, reporting, and issue tracking. Strategic implication: Battle-tested in audit shops with standardized methodologies. Recommended action: Consider where depth of audit execution features and established methodologies are non-negotiable.
-
MetricStream — Positioning: GRC platform emphasizing risk-based auditing and compliance orchestration. Strategic implication: Strong where enterprise risk management is tightly integrated into audit planning. Recommended action: Evaluate for risk-centric audit programs that need consolidated risk and control testing capabilities.
-
Onspring — Positioning: No-code GRC platform with flexible automation and real-time analytics. Strategic implication: Rapid configuration and low-code extensibility make it appealing for teams facing fast-changing processes. Recommended action: Pilot for organizations prioritizing speed-to-value and in-house configuration capacity; consider its expanding AI suite for automating routine tasks.
-
SAP — Positioning: Audit Management as part of a broader ERP and finance ecosystem. Strategic implication: Best fit for enterprises already committed to SAP who need audit functions tightly integrated with transactional systems. Recommended action: Favor when deep ERP integration is a strategic requirement and there is existing SAP footprint.
Recent activity shaping vendor selection and risk
-
Partnerships and ecosystem play: Major moves by established information providers to expand AI-enabled audit tooling are changing integration expectations. Strategic buyers should interrogate partner networks, data provenance, and automation boundaries when selecting a vendor.
-
Product acceleration among specialists: Several vendors launched embedded AI capabilities and privacy-focused modules in late 2024–2025 and early 2026, which materially alter shortlists for organizations seeking automation beyond workflow orchestration.
-
New benchmarking data: Industry reports and state-of-practice publications published in early 2026 highlight AI’s dual role as an enabler and a compliance risk — an argument for mature AI governance provisions in procurement contracts.
Regulatory and operational headwinds to plan for
-
AI governance policies: With full enforcement timelines for AI governance taking hold in key jurisdictions, vendor due diligence must include model risk management, documentation of training and validation procedures, and contractual assurances around explainability for high-risk audit features.
-
Privacy and data residency: Rapid expansion of subnational privacy laws in the U.S. and evolving cross-border data rules need to be addressed through data mapping, robust audit trails, and platform-level privacy modules.
-
Workforce pressures: Auditor shortages and rising labor costs make automation a business imperative; buyers should focus on solutions that provide measurable reduction in manual effort and clear metrics for productivity gains.
-
Cloud economics: Subscription models and SaaS delivery lower the upfront cost barrier but require attention on lifecycle costs, exit clauses, and migration planning in RFPs to avoid vendor lock-in or unexpected TCO spikes.
How to use this report to inform your 2026 roadmap
-
Shortlist with intent: Use the report’s scenario mapping to create a two-tier procurement plan — a near-term tactical buy for rapid automation and a strategic platform decision aligned to multi-year operating models.
-
Build AI governance into procurement criteria: Demand vendors demonstrate governance controls, audit trails for automated judgments, and evidence of third-party validation where AI influences material audit outcomes.
-
Prioritize integrations that reduce manual evidence handling: Focus on platforms offering native connectors to key transactional systems and automated data normalization to accelerate auditor productivity gains.
-
Cost-out transition risk: Leverage the included TCO models to quantify transition, training, and ongoing subscription costs versus projected labor and cycle-time benefits.
Accessing the full intelligence
This release is a strategic preview designed to help executives evaluate the urgency and directionality of investments in audit management technologies for 2026. The full PW Consulting Audit Management Software Systems Market report contains the complete dataset, segmentation tables, vendor scorecards, and downloadable procurement assets referenced here. To obtain the complete report with detailed regional and deployment segmentations, proprietary vendor benchmarking, and the full financial model used in our forecast, please visit our research distribution page.
Contact PW Consulting for bespoke briefings, tailored vendor shortlists, and implementation advisory services to translate insight into measurable outcomes this procurement cycle.
For detailed analysis of this topic, please visit the official page: Audit Management Software Systems Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Fully Closed Ventilator Breathing Circuit Market to expand at 5.22% CAGR (2026–2032), rising from USD 1,185.9 Million in 2025 to USD 1,693.3 Million by 2032 as North America Leads with USD 421.9 Million
By pmarketresearch, 2026-07-06
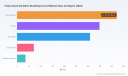
Fully Closed Ventilator Breathing Circuit Market — Strategic Outlook for 2026 Decision-Makers
Executive snapshot
PW Consulting’s new market study on Fully Closed Ventilator Breathing Circuits crystallizes the commercial and clinical dynamics that will shape vendor and buyer strategies in 2026 and beyond. At a macro level, the market reached USD 1,185.86 Million in our base year (2025) and is projected to increase to about USD 1,278.06 Million in 2026, growing at a compound annual growth rate (CAGR) of 5.22% across the 2026–2032 forecast period, with a 2032 projection near USD 1,693.25 Million. Those headline numbers mask markedly different strategic implications for incumbents, challenger brands, distribution partners, and hospital procurement organizations — which is precisely the focus of this report.
Fully Closed Ventilator Breathing Circuit Market
Why 2026 is an inflection point
-
Clinical and operational priorities are converging. Pressure to reduce ventilator-associated complications, combined with demand for longer closed-circuit use in critical care and expanding non-invasive ventilation options, puts closed breathing circuits at the intersection of infection prevention, staff efficiency, and cost control.
Fully Closed Ventilator Breathing Circuit Market -
Technology differentiation is materializing. Innovations such as permeable membrane humidification and vapour-permeable heated circuits reduce condensate and the need for interim water-trap management, which in turn reduces circuit breaks and procedural interruptions. These are no longer incremental features — they alter total-cost-of-care calculations.
Fully Closed Ventilator Breathing Circuit Market -
Channel and care-delivery shifts are accelerating. Growth in ambulatory surgical centers and home-based ventilation expands addressable use cases, while high-acuity hospitals continue to demand validated, integrated solutions compatible with flagship ventilators.
-
Regulatory and reimbursement nuance is increasing. Compliance to device standards (including ISO connectors and relevant U.S. CFR classifications) and evolving reimbursement coding logic influence procurement decisions and product design prioritization.
What this report delivers — practical intelligence for 2026 action
This study is structured as a decision-ready toolkit, designed to be executed against in-year budgets and multi-year roadmaps. Key deliverables include:
-
Robust market sizing and demand scenarios calibrated to a 2026–2032 forecast horizon, with sensitivity analyses that translate macro assumptions into revenue and capacity requirements.
-
Commercial models and buyer-supplier comparators: procurement scorecards, supplier risk heatmaps, and negotiation playbooks tailored to hospitals, ASC groups, and homecare service providers.
-
Technology assessment dashboards that rank humidification and heating approaches by clinical efficacy, regulatory complexity, manufacturing cost, and scale-up risk.
-
Go-to-market playbooks for different strategic positions: incumbent OEMs, low-cost regional manufacturers, and pure-play consumables vendors — each with channel mix, pricing levers, and promotional tactics.
-
Regulatory & clinical evidence roadmaps that sequence 510(k) strategies, ISO compliance, and targeted clinical studies (e.g., VAP reduction, circuit longevity) to support product adoption and purchasing justification.
-
M&A and partnership scouting lists, with operational due diligence templates and integration risk checklists for buyers pursuing consolidation or capability acquisition.
Competitive landscape — strategic takeaways
The competitive topology is a mix of large medical-device OEMs with integrated ventilation franchises, specialist breathing-circuit manufacturers, and an emerging class of cost-competitive suppliers from Asia. Feature- and evidence-led differentiation sits at the top of the agenda for market leaders, while price and supply-security dominate for many buyers.
-
Fisher & Paykel Healthcare (Auckland) continues to set feature expectations with permeable-membrane humidification systems that purposefully minimize condensate and support prolonged closed-system use. Recent regulatory milestones in 2025 underscore their strategy of pairing respiratory delivery hardware with validated accessories to protect circuit integrity.
-
Regional manufacturers such as Plasti-med (Turkey), Unimax Medical Systems (Taiwan), Shenzhen Besdata (China), GaleMed (Taiwan), Cathwide, and Besmed are advancing competitive positions through targeted technology variants (e.g., embedded heated wires, closed-suction compatibility) and lower-cost, high-volume manufacturing footprints. These suppliers are credible partners for high-volume disposable programs and for OEMs seeking contract manufacturing alternatives.
-
Established global OEMs — Armstrong Medical (UK), Teleflex (US), ICU Medical, Dräger (Germany), Medtronic (Ireland), and Hamilton Medical (Switzerland) — leverage brand, distribution reach, and ventilator integration to defend traditional hospital spend. Their strategic playbooks emphasize integrated system-vendor relationships, lifecycle services, and clinically backed consumables bundles.
-
Competitive pressure is fostering hybrid strategies: premium feature sets for high-acuity wards, and cost-optimized disposables for high-volume channels. Expect continued partnership activity between ventilator OEMs and breathing circuit specialists, and selective downstream consolidation where supply reliability and scale matter.
Regulatory, reimbursement and clinical context
Device classification and standards remain a gating factor for product design and market entry. Closed ventilator breathing circuits, depending on configuration, fall into existing breathing circuit and ventilator accessary classifications and are subject to connector and performance standards (including ISO requirements). In the U.S., coding and billing nuance (for example, the treatment of breathing-circuit items under HCPCS guidance) alters how hospitals bundle costs and how suppliers justify pricing.
Clinically, closed suction systems and circuit integrity are core components of ventilator-associated pneumonia prevention bundles. Vendors that can demonstrate reduced circuit breaks, lower condensate management burden, and measurable improvements in workflow and infection metrics will have a stronger commercial narrative in procurement dialogs.
2026 playbook — five prioritized moves
-
Prioritize condensate-reducing technologies that demonstrably lower staff interventions. Invest in clinical validation that links device features to workflow time-savings and infection metrics — those studies accelerate procurement approvals.
-
Bolster supply resilience through dual-sourcing and regional manufacturing partnerships. High-volume disposable demand makes operational continuity a primary commercial defense.
-
Segment product lines by channel economics. Offer modular portfolios: feature-rich options for ICU/high-acuity settings and streamlined, cost-optimized disposables for ambulatory and home-care channels.
-
Prepare regulatory dossiers and reimbursement evidence early. Anticipate interoperability testing and ISO connector audits; align submission timelines with product launch roadmaps.
-
Use targeted M&A or JV activity to fill capability gaps quickly — whether that is heated-wire expertise, closed-suction IP, or regional manufacturing scale. A focused bolt-on can shorten time-to-market versus organic development.
How PW Consulting’s research accelerates your 2026 agenda
Clients who use this report gain access to a layered set of assets: a financial model you can drop into board-level strategic planning, supplier scorecards that feed procurement RFPs, clinical evidence templates to support internal business cases, and a deal-ready shortlist of acquisition targets that have been pre-screened on technical and commercial criteria. The study combines primary interviews with purchasing managers and clinicians, factory-level supply-chain assessments, and a proprietary demand forecasting engine that translates macro adoption drivers into product-type requirements and capacity needs.
Closing — the decision-making edge
For organizations making allocation decisions in 2026 — whether investing in product R&D, negotiating multi-year supply agreements, or assessing acquisition targets — the fully closed ventilator breathing circuit market presents both structural growth and execution risk. The market’s steady expansion, as reflected in our base-year and forecast figures, rewards initiatives that tie product performance to measurable clinical and operational outcomes, and that secure manufacturing resilience without sacrificing innovation.
PW Consulting’s full report provides the granular, actionable intelligence necessary to move from strategic intent to executable plans. For the detailed segment-level breakdowns, company dossiers, pricing benchmarks, and downloadable models that underpin these conclusions, access the full report at PW Consulting’s market studies portal.
For detailed analysis of this topic, please visit the official page: Fully Closed Ventilator Breathing Circuit Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecasts 13.5% CAGR as Aerial Inspections Market Surges to USD 35.18 Billion by 2032
By pmarketresearch, 2026-07-06
Aerial Inspections Service Market: Strategic Intelligence for 2026 Decision-Makers
PW Consulting's new Aerial Inspections Service Market report (base year 2025) translates a fast-maturing segment of the aerial robotics and remote sensing economy into boardroom-ready guidance for 2026. The report maps a clear growth trajectory — from a multi‑billion-dollar industry in 2025 through sustained double‑digit expansion across the 2026–2032 forecast window (compound annual growth rate: 13.5%) — and converts that macro momentum into pragmatic, low‑risk strategic options for operators, asset owners, investors, and technology suppliers.
Aerial Inspections Service Market
Why this intelligence matters for 2026
As companies plan capital allocation and capability buildouts for 2026, they face three simultaneous dynamics: accelerating adoption of UAV and remote-sensing workflows, shifting regulatory guardrails (notably around BVLOS and critical‑infrastructure restrictions), and intensifying competition among technology-enabled service providers. Our report crystallizes these forces into actionable choices: where to invest, which partners to prioritize, and how to protect service continuity as regulation and labor markets evolve.
Aerial Inspections Service Market
What the report delivers (practical, execution-oriented)
- Market sizing and trajectory: a consolidated market model covering historical performance (2020–2025) and a detailed forecast period (2026–2032) with scenario sensitivity and key growth levers segmented by inspection method, application, and region.
- Regulatory and operational risk matrix: an assessment of existing certification regimes (e.g., FAA Part 107), recent enforcement trends, and likely outcomes from pending BVLOS and critical‑infrastructure rulemakings — with decision triggers and mitigation playbooks for 2026 procurement cycles.
- Competitive playbooks: comparative capability maps and vendor selection criteria that prioritize data management, AI analytics, and field execution scalability over ribbon‑cutting technology demos.
- Go‑to‑market and commercial models: recommended pricing architectures, cost‑savings quantification (including validated industrial inspection cost reductions and time efficiency metrics), contracting templates, and sample ROI calculators tailored to utilities, energy, infrastructure, and industrial asset owners.
- Technology maturity and integration roadmaps: stepwise adoption paths for UAV hardware, multispectral sensors, LiDAR, satellite augmentation, and analytics platforms — linked to internal change management, pilot programs, and supplier enablement plans.
- Case studies and implementation checklists: offshore wind, solar farms, pipeline and LNG terminal inspections and infrastructure asset programs, highlighting common pitfalls, timelines, and resource plans for scalable rollouts.
- Data annex and methodology: transparent model assumptions, primary interview summaries, and a machine‑readable dataset supporting the headline market model (annual series from 2020 through 2032).
Market shape and strategic implications
The aerial inspections market is no longer an experimental niche; it is a mainstream operational lever for large asset owners. With a high‑growth baseline and strong efficiency claims — our synthesis of primary and secondary data confirms inspection time reductions of roughly three quarters and operating‑cost savings that can approach the low‑to‑mid tens of percentage points higher compared with traditional, manual access techniques — decision windows in 2026 will favor organizations that convert pilot programs into enterprise standards.
Aerial Inspections Service Market
At the same time, concentration metrics indicate a fragmented supplier landscape: established specialist providers and platform players coexist with regional integrators and new entrants. The market’s top three and top five suppliers together represent a modest share of total value, underscoring an opportunity for consolidation, strategic partnerships, and differentiated vertical specialization.
Competitive landscape: who to watch and why
- Cyberhawk (Edinburgh, UK): A global leader in drone‑based asset inspection with a mature aerial data management platform (iHawk) and a track record of large energy and industrial contracts. Cyberhawk’s extended contract wins in 2025 signal continued demand for vendor partners that combine field execution with enterprise data workflows.
- DroneDeploy (San Francisco, CA): A platform provider focused on reality capture and enterprise mapping. Recent 2026 product releases and expanded enterprise agreements underline the attractiveness of software‑first approaches that accelerate project standardization across construction and infrastructure portfolios.
- SkySpecs (Ann Arbor, MI): Specialized in wind‑turbine autonomy and blade analytics, SkySpecs exemplifies the value of depth‑focused offerings that pair proprietary autonomy with industry‑specific analytics and lifecycle services.
- Terra Drone Corporation (Tokyo, Japan): A broad service provider with global reach and a growing footprint across defense, infrastructure, and offshore sectors — an example of geographic and vertical diversification as a growth route.
- Raptor Maps (USA): A data‑centric player in utility‑scale solar and large utility inspections; illustrates how domain specialization (solar analytics) creates defensible value based on outcome metrics.
- SAM (Surveying And Mapping, LLC) and Measure (Washington, DC): National providers with strong LiDAR and GIS integration capabilities, catering to infrastructure and municipal asset managers requiring integrated geospatial deliverables.
- AERIUM Analytics: A specialized analytics firm emphasizing tailored industrial and energy use cases, illustrative of the growing mid‑market demand for high‑accuracy, insight‑ready datasets.
Recent corporate activity reinforces two practical themes: platform consolidation and enterprise standardization. For example, DroneDeploy’s 2026 partnership expansion with a major construction contractor and its April product release demonstrate the commercial value of faster data workflows and multi‑model support. Similarly, Cyberhawk’s 2025 contract extensions in the Middle East underline the importance of proven operational experience in regulated and high‑stakes environments. New divisions and entrants focused on offshore and subsea inspections further indicate a widening addressable market footprint.
Regulatory and labor dynamics that will decide winners in 2026
- Regulatory evolution: FAA Part 107 continues to be the baseline for commercial drone operations, but enforcement intensity and programs for expedited violation resolution are rising. Proposed rulemaking around BVLOS and critical infrastructure will materially influence program design and capital planning in 2026 — both enabling scale and imposing new compliance costs. Our report includes a regulatory scenario toolbox that maps likely rule outcomes to operational responses and timelines.
- Labor and cost structure: Unit labor pricing for typical residential and building inspections remains in a defined range, and specialized thermal or complex industrial inspections command premium rates reflecting pilot skill and equipment. Procurement teams must move beyond headline hourly rates and evaluate total cost of inspection (including access, downtime, repeat visits, and data integration effort).
- Operational economics: Independent benchmarks show drone‑based industrial inspections can cut operational costs by 30–70% and inspection time by approximately 75–85% versus legacy manual methods. These efficiency gains are central to crafting compelling business cases — but they must be validated against asset class, inspection frequency, and data processing commitments.
Actionable strategies for 2026
- Prioritize data platforms over single‑fleet purchases: The marginal value in 2026 lies in integrated data ingestion, automated analytics, and seamless export to asset management systems. Contracts should mandate open APIs, exportable metadata standards, and agreed SLAs for detection and reporting.
- Run BVLOS‑ready pilot programs now: With BVLOS regulatory change probable within the near term, early pilots that emulate BVLOS workflows and safety cases will accelerate the transition to scaled operations when permissions arrive.
- Negotiate outcome‑based contracts: Shift from time‑and‑materials to outcome or availability models for repeatable inspection programs. Outcome pricing aligns incentives and captures a portion of the demonstrated operational savings.
- Build vendor redundancy for critical assets: Given the market’s fragmentation and regulatory uncertainty, procure a primary platform partner plus at least one certified regional integrator to de‑risk continuity in complex geographies.
- Integrate inspection data into maintenance planning: Move from periodic inspections to condition‑based maintenance models enabled by analytics, which reduces downtime and optimizes CAPEX cycles.
- Consider M&A and partnerships: For incumbent service providers and systems integrators, acquiring analytic capability or striking exclusive enterprise partnerships can be a rapid path to scale and differentiated IP.
How to use the report in your 2026 planning cycle
Use the report as a decision accelerator: align procurement cycles to the report’s regulatory timelines, test the three recommended commercial models in pilot contracts, and use the scenario tool to stress‑test your capital and staffing plans under conservative and aggressive adoption pathways. The dataset accompanying the report enables quick integration into financial models and board materials.
Conclusion — take the next step
The aerial inspections market is transitioning from tactical pilot projects to strategic capability. For 2026, the critical choices are less about whether to adopt aerial inspections than how to structure adoption for resilience, data ownership, and repeatable value capture. PW Consulting’s Aerial Inspections Service Market report provides the evidence base, operational playbooks, and vendor comparison tools that procurement, operations, and strategy teams need to make those choices defensibly.
To access the full dataset, vendor profiles, and implementation playbooks — including the complete segmentation tables and proprietary model outputs withheld here to preserve the “trailer” of strategic findings — please visit our official report page or contact PW Consulting’s industry team for a briefing.
For detailed analysis of this topic, please visit the official page: Aerial Inspections Service Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Refrigerated Food Vending Machine Market Poised to Reach USD 11.45 Billion by 2032
By pmarketresearch, 2026-07-06
Refrigerated Food Vending Machines: Strategic Imperatives for 2026 — PW Consulting Market Preview
As companies prepare strategic moves for 2026, the refrigerated food vending machine sector is presenting a rare confluence of growth opportunity, regulatory pressure and technology-driven disruption. PW Consulting’s latest market research — based on a 2025 baseline and a seven-year outlook to 2032 — shows the market expanding at a compound annual growth rate (CAGR) of roughly 7.5%. The total market, which stood at approximately USD 6.9 billion in 2025, is forecast to cross the USD 11 billion threshold by the end of the forecast window. For executives evaluating product roadmaps, channel investments, or M&A targets this year, these topline dynamics demand choices with both near-term compliance and long-term scalability in mind.
Refrigerated Food Vending Machine Market
Why this report matters for 2026 decision-makers
-
Regulatory inflection points are now hard business constraints — not distant risks. Manufacturers and operators who fail to prioritize refrigerant and energy compliance will face restricted product lifecycles and accelerated retrofit costs.
Refrigerated Food Vending Machine Market -
Technology adoption (cloud telemetry, RFID, AI-driven merchandising, and energy-efficient refrigeration) is shifting value from pure hardware sales toward recurring services, data monetization, and integrated channel solutions.
Refrigerated Food Vending Machine Market -
Market expansion is real but uneven: the overall growth trajectory supports new deployments across retail, transport, workplace and micro-market use cases; however, commercial success will rest on differentiated service ecosystems and cost-to-serve optimization.
Market snapshot — growth with structural nuance
PW Consulting’s sizing and scenario work highlights consistent expansion from the historical period into the forecast horizon. After a strong rebound in the early 2020s, the market reached an estimated USD 6.9 billion in 2025. Under base assumptions, the sector grows at about 7.5% CAGR through 2032, reflecting a blend of replacement demand, new-format retail adoptions, and increased deployment of smart vending solutions. This topline growth masks structural change: product-level differentiation, evolving regulation and new service economics are creating winners and laggards even within high-growth geographies and channels.
Key market dynamics shaping 2026 actions
-
Regulatory acceleration: North American and European regulations are already shaping product design cycles. Notably, the EPA AIM Act measures and complementary EU energy efficiency labeling regimes (with standards aligned to EN 50597) have created binding deadlines for refrigerant use and minimum energy performance. The result is a bifurcated market: compliant new-builds and an expanding aftermarket for retrofits and conversions.
-
Energy and lifecycle costs: Energy efficiency has migrated from sustainability rhetoric to a core cost category for operators. Energy labeling requirements and stricter refrigerant rules are raising the prestige and price of certified, efficient platforms — while tightening the usable lifetime of legacy machines that rely on high-GWP refrigerants.
-
Product intelligence & services shift: Vendors are monetizing telemetry, inventory analytics, and customer engagement software. RFID-enabled fridges, AI-powered merchandising algorithms and touch-interactive interfaces convert hardware into recurring-revenue platforms and differentiate operator economics.
-
Fragmented supply and material pressures: Structural materials such as stainless steel remain dominant for durability and thermal management in FoH (front-of-house) refrigerated solutions; industry data indicates a strong reliance on certain material classes for structural components, which has implications for sourcing and cost volatility.
Technology and product trends to prioritize
-
Refrigerants and thermal design: Transition to low‑GWP refrigerants and sealed, microchannel condensers is not optional. Systems engineered to be refrigerant-agnostic and serviceable will preserve resale value and limit stranded assets.
-
Edge intelligence and remote operations: AI-driven demand forecasting, dynamic price/assortment control and predictive maintenance reduce stockouts and shrink total cost of ownership for operators — critical levers for expanding micro-market footprints.
-
Human-centered interfaces: Touchscreens, frictionless payment and branded UX are driving impulse and repeat use. Data integration across payment, inventory and CRM systems enables new sponsorship and advertising revenue opportunities.
-
Modular hardware platforms: Modular vending architectures that support multiple temperature zones, swappable shelving and standardized service modules accelerate product updates under regulatory change, lowering capex erosion.
Competitive landscape — who’s shaping the market
The industry remains moderately fragmented, with the top three players accounting for just under one-third of market share and the top five holding roughly four-in-ten. This concentration profile indicates room for regional champions and specialist innovators to scale through differentiated propositions.
-
Crane Payment Innovations (formerly Crane Merchandising Systems) — U.S.–based — continues to leverage advanced merchandising platforms and touchscreen-enabled cold food solutions focused on retail and high-traffic environments. Its emphasis on robust refrigeration engineering and merchant media positions it for enterprise retail deployments.
-
AMS Vendors — a specialist in low-temperature combo systems — has built strengths in reliable delivery mechanisms for mixed refrigerated assortments, an asset for operators seeking flexible product mixes without sacrificing throughput.
-
SandenVendo America — a manufacturer concentrating on glass-front and frozen food solutions — is notable for investments in energy-efficient refrigeration suited to commercial foodservice channels.
-
REDYREF — innovating at the intersection of RFID and smart refrigeration — has launched deployed kiosks that illustrate the value of inventory-aware, locked-fridge models for 24/7 meal access. Such deployments show the speed at which RFID and access control are moving from pilots to commercial rollouts.
-
Azkoyen, Seaga, Fuji Electric and TCN Vending — among others — round out the competitive set with regional engineering, price-performance variants and scale manufacturing that target different channel needs and geographies.
Recent industry events (e.g., NAMA Show, Venditalia 2026) underscored two realities: first, a clear migration toward AI-backed smart coolers and micro-market solutions; second, the competitive importance of system-level plays (hardware + software + service) rather than standalone cabinets.
Operational implications for manufacturers and operators
-
Compliance-first product design: Adopt refrigerant transition roadmaps that include retrofit kits, validated low‑GWP systems, and supplier contracts tied to compliance milestones to avoid product obsolescence.
-
Service-centric commercial models: Move up the value stack by packaging maintenance, telemetry and inventory services into subscription contracts that reduce churn and increase lifetime customer value.
-
Channel & partner orchestration: Build distributorship models that blend national accounts with local service partners to manage installation, regulatory permits and first-line repairs.
-
Data & monetization playbook: Deploy data governance and commercial APIs early to unlock insights (assortment performance, location analytics) that can be monetized via advertising or supplier revenue-sharing.
-
Procurement resilience: Hedge material exposure for key structural components and qualify multiple vendors for refrigeration subsystems and controls to limit single-supplier risk.
What PW Consulting’s full report delivers
-
Comprehensive market sizing and scenarios from 2020–2032 with modelled sensitivities to energy prices, regulatory adoption rates and technology diffusion curves.
-
Deep segmentation by product type, application and region, plus bespoke scenario dashboards for portfolio stress‑testing (note: detailed segment tables and regional splits are reserved for the full report).
-
Competitive profiles and M&A screening templates for target prioritization, including validated company intelligence and deal multiples guidance.
-
Practical playbooks — product roadmaps, retrofit decision matrices, lease vs. buy models and service contract templates — tailored to OEMs, operators and large enterprise buyers.
-
Regulatory impact assessment with compliance timelines and cost‑to‑compliance estimates, and a refrigerant transition plan that shows break-even timelines for retrofits versus replacement.
-
Case studies and pilot-readiness checklists for RFID, AI merchandising and micro-market deployments, plus go-to-market strategies for rapid scaling.
Strategic next steps for 2026
-
Immediate: audit installed fleet for refrigerant exposure, energy efficiency label status and retrofit feasibility; prioritize high‑impact sites for compliance investment.
-
Short-term: launch modular pilot programs that validate AI merchandising and telemetry economics in at least two use cases (e.g., transit hub, workplace campus).
-
Medium-term: restructure sales contracts toward service subscriptions with uptime SLAs and data-sharing clauses to capture recurring value.
-
Long-term: assess acquisition targets that fill gaps in service capability, last‑mile logistics or software monetization to accelerate platform outcomes.
Conclusion — positioning for both compliance and growth
2026 will separate organizations that view regulation as a cost center from those that treat it as a catalyst for product differentiation and new revenue streams. The refrigerated vending market is large and growing, but the competitive prize will accrue to firms that combine compliant thermal engineering, modular hardware strategies, and software-driven service models. PW Consulting’s full Refrigerated Food Vending Machine Market report provides the detailed segmentation, risk modelling and executable playbooks executives need to make high‑confidence decisions this year. For teams preparing budgets, sourcing strategies, or M&A pipelines in 2026, the evidence is clear: act now to convert regulatory pressures into strategic advantage.
To access the full dataset, segmentation tables and tactical templates referenced in this preview, contact PW Consulting for the full report and consultancy engagements tailored to your role in the value chain.
For detailed analysis of this topic, please visit the official page: Refrigerated Food Vending Machine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: High-Speed Specialty Cable Market Poised for Robust Expansion — 9.21% CAGR Forecast Through 2032
By pmarketresearch, 2026-07-06
High Speed Specialty Cable Market: Strategic Imperatives for 2026 — PW Consulting Brief
Executive summary
PW Consulting’s latest High Speed Specialty Cable Market report provides a forward-looking strategic compass for corporate decision-makers navigating a dynamic period of technology transition, raw-material volatility, and shifting trade policy. The market that produced roughly USD 5,250 Million in revenue in our base year (2025) is projected to expand at a compound annual growth rate (CAGR) of 9.21% as the industry transitions through 2026 and into the 2026–2032 forecast window. By 2032, our model anticipates the global market approaching approximately USD 9,726.5 Million (USD Million), driven by accelerating data-center bandwidth requirements, continued adoption of active optical and hybrid interconnects, and industrial/critical-infrastructure upgrades.
High Speed Specialty Cable Market
Why this matters for 2026 corporate decisions
- Investment timing: With near-term growth materially above historical averages, capital allocation (capacity expansions, automation, and product platform investments) needs to be synchronized with technology migration curves to avoid stranded assets.
- Procurement risk: Raw-material and trade-policy shocks in 2025–26 require a re-think of sourcing, inventory strategy and contractual terms to protect margins while preserving service levels.
- Competitive positioning: The market is moderately consolidated; top-tier incumbents maintain strong engineering and distribution advantages, but there are accessible niches for fast followers and specialists.
- Commercial strategy: Customers (hyperscalers, telecom carriers, industrial OEMs) are demanding higher-performance, lower-latency interconnects—value capture will favor differentiated systems-level solutions, services and assurance models.
Key market dynamics shaping 2026
Three intersecting forces will define strategic choices next year: demand-side technology transitions, supply-chain and raw-material stress, and trade/regulatory discontinuities.
High Speed Specialty Cable Market
- Technology migration and demand concentration. Data-center networking upgrades, adoption of higher-speed I/O standards, and ongoing fiber densification create asymmetric demand for high-performance cable assemblies and optical interconnects. Buyers are trading up to systems that deliver reliability at scale, expanding addressable revenue but increasing technical complexity for suppliers.
- Raw-material and input-cost pressure. Copper and copper-derived inputs reached unprecedented pressure points in 2025–early 2026. Commodity markets and industry indices are signaling sustained cost inflation for copper wire-and-cable inputs, copper-clad laminates and foil, forcing manufacturers to adjust pricing, reformulate products where possible, and accelerate yield-improvement programs on the factory floor.
- Trade policy and geopolitics. New tariffs and export controls implemented in 2025 altered established sourcing flows for semi-finished and copper-intensive products, and controls on key rare-earths have cascading effects on magnet supply for certain cable systems. These policy changes make geographic diversification and resilient supplier networks a board-level priority.
Competitive landscape — concentration and capability
The industry exhibits moderate concentration characteristics: the three largest players account for a meaningful share of the market and the top five control a materially larger portion. This concentration supports scale-driven R&D and ensures that a set of global incumbents can deliver broad product portfolios and geographic reach, while still leaving room for regional specialists and highly engineered niche players to win on customization and service.
High Speed Specialty Cable Market
At the company level, key competitive archetypes and strategic moves to watch include:
- Large, diversified incumbents (e.g., Amphenol, Prysmian, Nexans). These firms leverage integrated manufacturing, broad channel networks and strong OEM relationships to capture system-level upgrades. Amphenol’s recent performance demonstrates the magnitude of demand in IT/datacom and high-speed interconnect markets; incumbents will continue to invest in platform technologies that serve multi-market needs.
- High-performance fiber and specialty-focused manufacturers (e.g., Sumitomo Electric, Furukawa). These players are concentrating on density, optical performance and reliability—areas that hyperscalers and telecom carriers prize. Continued product launches and high-density innovations are expected to accelerate competition in data-center segments.
- Regional and specialty vendors (e.g., Proterial Cable America, Specialty Cable Corporation, Samtec). These firms compete on rapid product development, micro-distribution designs, and proximity to key customers. Recent product introductions underscore opportunities for specialist providers to win design-ins for niche, high-margin applications.
- Manufacturing and capacity dynamics. Select suppliers are expanding capacity and precision-production capabilities; investments are being directed toward automation and quality control to offset raw-material inflation and raise throughput without proportionate increases in labor costs.
What PW Consulting’s report contains — practical, operational intelligence
Our report is designed as an actionable toolkit for commercial leaders, procurement teams, product and strategy executives. Highlights include:
- Top-line, point-in-time market sizing (2020–2025 historical baseline) and a detailed forecast for 2026–2032 with scenario variants that reflect technology adoption rates and policy shocks.
- Scenario-driven cost and margin modeling that quantifies the impact of raw-material shocks and tariff regimes on product-level profitability and breakeven thresholds.
- Supplier heat maps and vendor capability matrices: engineering pedigree, manufacturing footprint, product roadmaps, and integration readiness—built to support RFP and supplier consolidation decisions.
- Commercial playbooks for pricing, contract design (including indexation and force-majeure clauses), and service-level engineering tailored to hyperscale, carrier and industrial accounts.
- M&A and partnership screening tools that identify pockets of high-margin, defensible niches and acquirable capabilities (IP, specialized manufacturing, or channel access), accompanied by valuation sensitivity models.
- Technology strategy modules: product roadmaps for optical vs. copper-based solutions, migration pathways for customers, and hit-rate models for new connector and cable standards.
- Regulatory and geopolitical risk dashboards tracking tariffs, export controls and critical-material vulnerabilities—integrated with mitigation playbooks for insuring continuity of supply.
To honor the “trailer” principle of this release, we are deliberately summarizing the scope here while withholding segment-level splits and vendor scorecards. The full report contains detailed breakdowns, vendor benchmarking scores, and downloadable modelling assets.
Priority strategic recommendations for 2026
PW Consulting recommends a three-horizon approach to convert market growth into defensible margin expansion and resilience.
- Short term (0–12 months): Stabilize margins and supply.
- Execute supplier stress-tests and reprice contracts with clear indexation clauses to pass-through raw-material movements transparently.
- Establish hedging or strategic inventory programs for critical copper-derived inputs and copper-clad laminates; prioritize supplier dual-sourcing where feasible.
- Pursue targeted capacity buffers for high-demand product families required by data centers and telecom carriers, using short-cycle subcontracting to avoid long-term overcommitment.
- Medium term (12–24 months): Differentiate product and go-to-market.
- Invest selectively in optical and hybrid interconnect architectures that align with customers’ multi-year migration plans; aim for systems that combine product sales with premium service and assurance contracts.
- Develop modular product platforms to reduce SKU proliferation and compress lead times while increasing factory throughput via automation and lean manufacturing.
- Negotiate long-term supply agreements with tier-1 raw-material suppliers, including options for co-investment in critical upstream capacity where strategic.
- Long term (24+ months): Secure structural advantage.
- Pursue tuck-in M&A to acquire specialized manufacturing capabilities or cognitive design assets (e.g., advanced cable modeling, connector engineering) that are otherwise expensive to build organically.
- Position to supply emerging, higher-value applications (defense, aerospace, medical) by investing in qualification and Mil-spec certifications—these segments can provide margin insulation from commodity cycles.
- Build cross-functional scenario-planning capabilities to integrate trade-policy and raw-material volatility into capital planning and product roadmaps.
Investor and board-level implications
For investors, the sector’s mid-to-high single-digit CAGR and the sizable re-rating potential tied to systems-integration and premium service models make selective exposure attractive—but timing and asset quality matter. Boards should insist on stress-tested capex plans that incorporate tariff scenarios, commodity shocks, and customer migration pacing. Equity and debt providers will increasingly value companies that can demonstrate demonstrated supplier resilience and recurring-service revenue streams.
How to use PW Consulting’s research
Our report is built for rapid operationalization: the downloadable modeling workbook can be inserted into capital-planning and procurement workflows, the supplier heat maps inform immediate sourcing decisions, and the M&A screening module accelerates target prioritization. For executives making strategic calls in 2026—pricing, capacity, or M&A—the report functions as a single source of evidence-based guidance calibrated to both upside demand and downside policy risk.
Next steps
To access the full, interactive report—including detailed segment forecasts, vendor scorecards and downloadable modelling assets—visit PW Consulting’s market research portal. The public summary above is intended to present the strategic contours and decision-grade recommendations; the full deliverable contains the granular inputs and proprietary analytics required to execute on the playbook.
For detailed analysis of this topic, please visit the official page: High Speed Specialty Cable Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Bake‑Stable Pastry Fillings Market Set to Grow at a 5.2% CAGR, New Insights Reveal
By pmarketresearch, 2026-07-06
Bake Stable Pastry Fillings Market: Strategic Preview for 2026 Decisions
PW Consulting’s latest Bake Stable Pastry Fillings Market report (base year 2025) furnishes senior leadership teams with an evidence-based roadmap to shape product, procurement, and go‑to‑market choices throughout 2026. The global bake-stable fillings market, measured at USD 1,450 Million in 2025, has experienced uneven but resilient expansion since 2020 and is projected to reach roughly USD 2,068 Million by 2032 under a central scenario (CAGR 5.2% for the 2026–2032 forecast window). These headline figures frame a market large enough to justify targeted investment but structurally diverse enough to reward precise strategic moves.
Bake Stable Pastry Fillings Market
Why this report matters to 2026 corporate agendas
-
Actionable foresight for capital allocation: With a mid-single-digit CAGR through 2032, the category is growth-at-scale rather than hypergrowth. That implies selective capacity expansion, pilot lines, and targeted acquisitions will typically outperform broad-based greenfield builds for most mid-market and regional players.
Bake Stable Pastry Fillings Market -
Risk-calibrated sourcing and pricing strategy: Input-price episodes over the past 24 months — including volatility in cocoa, sugar, and fresh fruit markets — mean procurement playbooks should combine short-term hedges with supplier diversification and SKU rationalization. The report’s sensitivity modeling translates commodity stress tests into margin and pricing levers you can execute in 2026.
Bake Stable Pastry Fillings Market -
Commercial differentiation via formulation and label claims: Clean-label, high-fruit content, plant-based and allergen-aware fillings increasingly drive retail and foodservice assortment decisions. Our competitive benchmarks identify how leading suppliers are positioning ingredient and nutritional claims — and where white space exists for new SKU introductions in 2026.
-
M&A and partnership targets: The market concentration metrics (CR3 ~31.4%, CR5 ~40.8%) show a category that is neither atomized nor tightly consolidated. This structure creates repeated opportunities for bolt-on acquisitions that deliver scale in core geographies, formulation IP, or sales channel access — a pattern we quantify and illustrate with practical screening criteria.
Report practical contents — what you’ll find inside
-
Robust market sizing and forecast framework: Methodology, demand drivers, and sensitivity ranges for 2026–2032 anchored to our 2025 base. The published forecast is supported by scenario variants that stress commodity shocks, regulatory shifts, and consumer preference turnpoints.
-
Segment-level playbooks (kept deliberately high-level in this preview): channel and flavor vectors, practical SKU optimization guides, and route-to-market strategies for retail, foodservice, and industrial baking customers.
-
Raw-material and cost-pressure module: dynamic models that translate cocoa, sugar, and fresh-fruit pricing paths into finished-goods cost impacts; also, a decision matrix for when to reformulate versus when to absorb or pass through costs.
-
Technical & sensory guidance: processing constraints, bake- and freeze‑thaw stability checklists, and recommended trial methodologies to speed product launch cycles while minimizing rework.
-
Go-to-market and commercial tools: prioritized account lists, distributor scorecards, margin waterfall templates, and an ROI calculator for new launch scenarios (including private-label and co-manufacturing options).
-
M&A playbook and valuation heuristics: practical screening criteria, expectations for multiple ranges by asset type, and integration checklists specific to bakery ingredient and filling assets.
-
Supplier and innovation scouting: a short-list of technology and ingredient partners with capabilities in clean-label texturants, thermally stable fruit preparations, and plant-based emulsions — including tactical recommendations for pilot collaborations and joint IP strategies.
Competitive landscape — capabilities, moves, and implications
-
Puratos Group (Groot‑Bijgaarden, Belgium): Puratos’ Vivafil and Topfil lines emphasize bake stability plus clean-label options. Their June 2025 US pilot bakery plant signals a dual strategy — accelerate commercial innovation for large-scale bakers while deepening technical services. For potential partners or acquirers, Puratos is a reference for integrated R&D-to-production models that shorten time-to-shelf.
-
Dawn Foods (Jackson, Michigan, USA): Dawn’s BakeFill, PlusFill and Delifruit Xtra ranges target high-fruit-content and multi-condition stability (freeze-thaw and bake). Dawn’s strength lies in bakery channel relationships and scalable formulations — making them an ideal comparator for companies evaluating margin capture through channel specialization versus product innovation.
-
AGRANA Beteiligungs‑AG (Vienna, Austria): AGRANA’s emphasis on thermostable fruit preparations and all-in-one starch/juice/flavor solutions positions them as a technical leader for manufacturers seeking minimal-slip, oven-stable systems. Their trade‑show launches point toward an offensive on vegan and allergen‑friendly formulations.
-
Bakels Group (Lucerne, Switzerland): Bakels offers ready-to-use fillings, including vegan and home-baking lines. Their diversified portfolio and strong route-to-market for private-label present a compelling model for companies looking to monetize home-baking trends without heavy R&D spend.
-
Andros Chef (Cajarc, France): With clean-label fruit fillings (high fruit content, low/no starch), Andros Chef exemplifies the premium clean-label play. For foodservice and premium retail segments, their approach shows how ingredient sourcing and transparent claims can sustain price premiums.
-
Metarom USA (New Hampshire, USA): Metarom’s strength is customization — flavor systems, bake-stable blends, and technical thought leadership. Their May 2025 technical publication highlights selection criteria (migration, rheology, stability, flavor) that CPG and bakery manufacturers can operationalize when qualifying suppliers.
-
Barry Callebaut (Zurich, Switzerland): Barry Callebaut brings deep chocolate and nut-filling expertise optimized for high-temperature processes. Their capabilities are particularly relevant for manufacturers aiming to keep margins intact when cocoa price cycles normalize.
Supply-chain and input-risk dynamics to monitor in 2026
-
Commodity price cycles remain material to margin management. Recent swings in cocoa and sugar markets, and episodic fresh‑fruit price movements, mean procurement teams should implement rolling stress tests and a layered purchasing strategy (short-term contracts plus selective hedging).
-
Farm-level and retail fruit price dynamics indicate potential near-term easing in supplier costs for fruit preparations, but volatility remains by region and variety. The report’s sensitivity matrices show when a reformulation (e.g., replacing refined sugar with concentrated fruit puree) yields net margin improvement versus when scale and sourcing contracts are the optimal lever.
-
Regulatory and consumer trends favor clean‑label and preservative‑free formulations. That trend is not merely marketing: it changes ingredient stacks, shelf‑life management, and co-manufacturing requirements — and it creates premium niches for suppliers with validated clean-label systems.
How to use the report in boardroom decision-making for 2026
-
Prioritize investments: Use the report’s ROI and break-even models to sequence investments — pilot lines, co-manufacturing agreements, or targeted acquisitions — in that order for most mid-sized players.
-
Align product roadmap with procurement reality: Cross‑reference the report’s commodity scenarios with your contract calendar to decide whether to launch new high-fruit SKUs now or defer until price regimes stabilize.
-
Frame M&A conversations: Apply the provided screening filters to identify assets that deliver immediate scale (sales channels), proprietary formulation IP, or cost synergies (shared raw-material sourcing).
-
Strengthen commercial execution: Deploy the report’s account-prioritization and margin-waterfall tools to convert category growth into sustained margin expansion rather than promotional-driven volume.
Conclusion — a strategic lens for 2026
Our market assessment demonstrates that bake-stable pastry fillings are a strategically attractive segment: stable, large enough to support meaningful returns, and dynamic enough to reward focused innovation. The central forecast (CAGR 5.2% through 2032) supports selective investment in production and formulation capabilities, but commodity and regulatory pressures require surgical procurement, formulation, and channel strategies. PW Consulting’s report synthesizes these trade-offs into executable plans — from technical trial protocols to M&A screening and commercial playbooks — enabling confident, evidence-driven choices in 2026.
Next steps
-
Access the full report to unlock the detailed segmentation, regional and channel splits, financial models, and downloadable toolkits referenced in this preview. The full intelligence package contains the granular data and appendices necessary to operationalize the recommendations summarized here.
-
Contact PW Consulting for a tailored briefing: we can walk your leadership team through the parts of the report most material to your strategy — whether that is product roadmap, procurement policy, or M&A screening.
For detailed analysis of this topic, please visit the official page: Bake Stable Pastry Fillings Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com