

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: ESRD market to surge from $152.3B in 2025 to $305.4B by 2032 at a 10.45% CAGR — Dialysis alone tops $133.6B in 2025

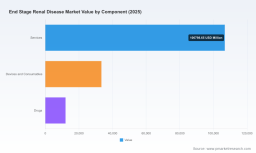
End Stage Renal Disease Market: Strategic Imperatives for 2026 Decision‑Making
PW Consulting’s new End Stage Renal Disease (ESRD) Market Research Report is designed as the decision support tool C‑suite teams, corporate development groups, and health systems will rely on when shaping 2026 investment and commercialization plans. Our base‑year analysis (2025) anchors a forward view across 2026–2032 that demonstrates a pronounced acceleration: the global ESRD market expands from USD 152,306.45 Million in 2025 to USD 305,407.41 Million by 2032, reflecting a compound annual growth rate (CAGR) of 10.45% across the forecast window. This briefing highlights the strategic value of the report for executive decision cycles while intentionally withholding core sub‑segment level tables — the detailed, slice‑by‑slice intelligence is available in the full report.
End Stage Renal Disease Market
Why this report matters for 2026
-
Timing. 2026 marks a tactical inflection for ESRD markets: newer modalities, device platforms and a shifting reimbursement backdrop are converging. Companies must reconcile short‑term access and margin pressures with long‑term product and service investments.
End Stage Renal Disease Market -
Scale and velocity. Our top‑line projections reveal a market roughly doubling over the forecast horizon, driven by technology adoption, expanded access, and new care models. This creates both opportunity (new revenue pools) and risk (accelerated obsolescence for legacy systems).
End Stage Renal Disease Market -
Decision focus. The report translates macro growth into actionable choices: which modalities to prioritize, where to double down on clinical evidence generation, and how to align commercial models with payers that are increasingly demanding outcomes and cost‑efficiency.
What is inside — practical, executable content
-
Robust market model: a bottom‑up forecast (2026–2032) with scenario sensitivity to volume, pricing, and reimbursement shocks. Note: the headline model and aggregated market totals are summarized herein; detailed subsegment breakouts are reserved for the full report to preserve competitive integrity.
-
Five strategic scenarios: our base case is complemented by conservative and accelerated adoption pathways that quantify revenue, unit demand, and margin implications under varying clinical and regulatory assumptions.
-
Regulatory & payer playbook: a pragmatic guide to navigating the current reimbursement environment, including scenario templates for contract negotiations tied to outcomes‑based arrangements.
-
Commercialization & go‑to‑market frameworks: country‑level market entry checklists, prioritization matrices for modality and channel (in‑center vs. home vs. acute), and digital adoption roadmaps.
-
Competitive intelligence and sourcing maps: capability heatmaps for incumbent and emerging players, supplier dependency analyses, and M&A target shortlists ranked by strategic fit and integration complexity.
-
Operational readiness tools: supply chain resilience playbooks, clinical rollout templates for new device launches, and cybersecurity readiness checklists for dialysis platforms with connected components.
Market dynamics: what is changing and what it means
The ESRD market's growth is not monolithic — it is the aggregate result of evolving care pathways, technology advances, and policy changes. Key dynamics that the report examines in depth include:
-
Modal shift and decentralization: home dialysis and hybrid delivery models are gaining traction. Device makers and service providers who can offer simplified, connected platforms will capture a greater share of incremental growth.
-
Technology convergence: next‑generation dialysis platforms emphasize usability, cybersecurity, and connectivity. Regulatory clearances for updated software and enterprise capabilities (e.g., recent FDA clearances for modernized systems) create windows for commercial differentiation.
-
Value‑based care pressure: payers are increasingly focused on total cost of care and patient outcomes. Expect procurement processes to reward demonstrated reductions in hospitalization, infection rates, and overall cost per patient episode.
-
Reimbursement headwinds and tailwinds: the CY 2026 ESRD Prospective Payment System (PPS) final rule nudges base reimbursement upward and maintains labor‑share and wage‑index protections that materially affect facility economics. Operators and vendors must update financial models and contracting approaches in response.
Competitive landscape — who to watch and how to think about competition
The market remains concentrated among a handful of vertically integrated players, with CR3 and CR5 metrics indicating material market share captured by the largest groups. Our competitive analysis synthesizes product portfolios, service footprints, and strategic trajectories for incumbents and challengers. Highlights:
-
Fresenius Medical Care: maintains leadership through a combined product and clinic model. Its platform strategy — combining high‑volume hemodiafiltration systems, clinic networks, and value‑based care offerings — creates a compelling integrated proposition. The planned U.S. commercialization of its high‑volume HDF platform in 2026 is a strategic accelerant that will influence competitor roadmaps.
-
Baxter and other device specialists: firms focused on peritoneal dialysis, consumables and home modalities are staking claims in adjacent growth pockets. Their agility in product iterations and supply agreements makes them strategic partners for payers and providers pursuing home‑first strategies.
-
Large service operators (e.g., DaVita): scale in outpatient center networks and care management services enables negotiating leverage with suppliers and payers. Their investments in home programs and care coordination are key strategic indicators to monitor.
-
Innovative platform disruptors (e.g., Outset Medical, Quanta): newer all‑in‑one and compact systems, especially those receiving regulatory clearances and bolstered cybersecurity features, alter the economics of deployment across acute, chronic, and home settings.
-
Specialist suppliers (Nipro, B. Braun, Asahi Kasei, Toray, JMS, Nikkiso, Medtronic): these companies underpin the device and consumable supply chain; their product innovations, manufacturing footprints, and distribution partnerships determine margin resilience and the pace of clinical adoption.
For each company profiled in the report, we provide a strategic scorecard: product roadmap alignment, clinical evidence generation, channel and service capabilities, and M&A/partnership optionality. Recent public developments — including major annual disclosures, product clearances, and payer rules — are synthesized into implications for competitive positioning and tactical moves for 2026.
Strategic priorities for market entrants and incumbents in 2026
-
Prioritize modular product strategies. Design platforms that can be upgraded via software and consumables to extend device lifecycles and capture recurring revenue.
-
Invest in clinical evidence early. Demonstrating reductions in hospitalization and total cost of care is vital for securing preferred network status and higher‑value contracting.
-
Build payer engagement playbooks. Use the report’s reimbursement templates to model the financial impact of alternative payment arrangements and to construct outcome‑linked proposals.
-
Secure supply‑chain optionality. Dual‑sourcing critical consumables and creating near‑term inventory strategies will reduce exposure to geopolitical and production disruptions.
-
Emphasize cybersecurity and interoperability. As dialysis platforms become connected, enterprise‑level security and data‑integration capabilities will be procurement differentiators.
-
Adopt an M&A and partnership lens. With meaningful concentration at the top of the market, strategic bolt‑on acquisitions and ecosystem partnerships can accelerate access to care networks and product portfolios.
How PW Consulting’s report will change your 2026 playbook
This report is constructed as a practical execution manual, not an academic exercise. Alongside the headline market trajectory, it contains:
-
Actionable financial models you can plug into internal planning systems to test product launches, pricing strategies, and contract outcomes against the market forecast.
-
Negotiation templates and risk‑adjusted ROI calculators for outcomes‑based contracting.
-
A prioritized set of M&A and partnership candidates mapped to capability gaps common among device makers, service operators and payers.
-
Field‑tested clinical rollout and training plans to compress time‑to‑adoption and limit early‑stage clinical variability.
Next steps and how to access the full intelligence
The material in this press briefing showcases the depth and strategic orientation of PW Consulting’s ESRD market research while deliberately reserving the core sub‑segment data tables and tactical scorecards for the full report. For commercial teams preparing 2026 budgets, corporate development teams evaluating M&A targets, and health systems negotiating payer contracts, the full report provides the granular segmentation, channel forecasts, and validated unit price curves necessary to finalize decisions.
Contact PW Consulting to schedule a briefing, obtain the full dataset, or request a tailored workshop that maps our findings to your business model and 2026 operating plan. Our analysts are prepared to run custom scenario analyses and to support rapid integration of the report’s outputs into board‑level decision materials.
PW Consulting: translating market scale into executable strategy for the rapidly evolving ESRD landscape.
For detailed analysis of this topic, please visit the official page: End Stage Renal Disease Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com