

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Refrigerated Food Vending Machine Market Poised to Reach USD 11.45 Billion by 2032

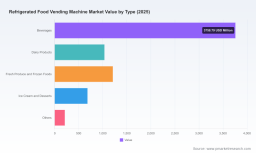
Refrigerated Food Vending Machines: Strategic Imperatives for 2026 — PW Consulting Market Preview
As companies prepare strategic moves for 2026, the refrigerated food vending machine sector is presenting a rare confluence of growth opportunity, regulatory pressure and technology-driven disruption. PW Consulting’s latest market research — based on a 2025 baseline and a seven-year outlook to 2032 — shows the market expanding at a compound annual growth rate (CAGR) of roughly 7.5%. The total market, which stood at approximately USD 6.9 billion in 2025, is forecast to cross the USD 11 billion threshold by the end of the forecast window. For executives evaluating product roadmaps, channel investments, or M&A targets this year, these topline dynamics demand choices with both near-term compliance and long-term scalability in mind.
Refrigerated Food Vending Machine Market
Why this report matters for 2026 decision-makers
-
Regulatory inflection points are now hard business constraints — not distant risks. Manufacturers and operators who fail to prioritize refrigerant and energy compliance will face restricted product lifecycles and accelerated retrofit costs.
Refrigerated Food Vending Machine Market -
Technology adoption (cloud telemetry, RFID, AI-driven merchandising, and energy-efficient refrigeration) is shifting value from pure hardware sales toward recurring services, data monetization, and integrated channel solutions.
Refrigerated Food Vending Machine Market -
Market expansion is real but uneven: the overall growth trajectory supports new deployments across retail, transport, workplace and micro-market use cases; however, commercial success will rest on differentiated service ecosystems and cost-to-serve optimization.
Market snapshot — growth with structural nuance
PW Consulting’s sizing and scenario work highlights consistent expansion from the historical period into the forecast horizon. After a strong rebound in the early 2020s, the market reached an estimated USD 6.9 billion in 2025. Under base assumptions, the sector grows at about 7.5% CAGR through 2032, reflecting a blend of replacement demand, new-format retail adoptions, and increased deployment of smart vending solutions. This topline growth masks structural change: product-level differentiation, evolving regulation and new service economics are creating winners and laggards even within high-growth geographies and channels.
Key market dynamics shaping 2026 actions
-
Regulatory acceleration: North American and European regulations are already shaping product design cycles. Notably, the EPA AIM Act measures and complementary EU energy efficiency labeling regimes (with standards aligned to EN 50597) have created binding deadlines for refrigerant use and minimum energy performance. The result is a bifurcated market: compliant new-builds and an expanding aftermarket for retrofits and conversions.
-
Energy and lifecycle costs: Energy efficiency has migrated from sustainability rhetoric to a core cost category for operators. Energy labeling requirements and stricter refrigerant rules are raising the prestige and price of certified, efficient platforms — while tightening the usable lifetime of legacy machines that rely on high-GWP refrigerants.
-
Product intelligence & services shift: Vendors are monetizing telemetry, inventory analytics, and customer engagement software. RFID-enabled fridges, AI-powered merchandising algorithms and touch-interactive interfaces convert hardware into recurring-revenue platforms and differentiate operator economics.
-
Fragmented supply and material pressures: Structural materials such as stainless steel remain dominant for durability and thermal management in FoH (front-of-house) refrigerated solutions; industry data indicates a strong reliance on certain material classes for structural components, which has implications for sourcing and cost volatility.
Technology and product trends to prioritize
-
Refrigerants and thermal design: Transition to low‑GWP refrigerants and sealed, microchannel condensers is not optional. Systems engineered to be refrigerant-agnostic and serviceable will preserve resale value and limit stranded assets.
-
Edge intelligence and remote operations: AI-driven demand forecasting, dynamic price/assortment control and predictive maintenance reduce stockouts and shrink total cost of ownership for operators — critical levers for expanding micro-market footprints.
-
Human-centered interfaces: Touchscreens, frictionless payment and branded UX are driving impulse and repeat use. Data integration across payment, inventory and CRM systems enables new sponsorship and advertising revenue opportunities.
-
Modular hardware platforms: Modular vending architectures that support multiple temperature zones, swappable shelving and standardized service modules accelerate product updates under regulatory change, lowering capex erosion.
Competitive landscape — who’s shaping the market
The industry remains moderately fragmented, with the top three players accounting for just under one-third of market share and the top five holding roughly four-in-ten. This concentration profile indicates room for regional champions and specialist innovators to scale through differentiated propositions.
-
Crane Payment Innovations (formerly Crane Merchandising Systems) — U.S.–based — continues to leverage advanced merchandising platforms and touchscreen-enabled cold food solutions focused on retail and high-traffic environments. Its emphasis on robust refrigeration engineering and merchant media positions it for enterprise retail deployments.
-
AMS Vendors — a specialist in low-temperature combo systems — has built strengths in reliable delivery mechanisms for mixed refrigerated assortments, an asset for operators seeking flexible product mixes without sacrificing throughput.
-
SandenVendo America — a manufacturer concentrating on glass-front and frozen food solutions — is notable for investments in energy-efficient refrigeration suited to commercial foodservice channels.
-
REDYREF — innovating at the intersection of RFID and smart refrigeration — has launched deployed kiosks that illustrate the value of inventory-aware, locked-fridge models for 24/7 meal access. Such deployments show the speed at which RFID and access control are moving from pilots to commercial rollouts.
-
Azkoyen, Seaga, Fuji Electric and TCN Vending — among others — round out the competitive set with regional engineering, price-performance variants and scale manufacturing that target different channel needs and geographies.
Recent industry events (e.g., NAMA Show, Venditalia 2026) underscored two realities: first, a clear migration toward AI-backed smart coolers and micro-market solutions; second, the competitive importance of system-level plays (hardware + software + service) rather than standalone cabinets.
Operational implications for manufacturers and operators
-
Compliance-first product design: Adopt refrigerant transition roadmaps that include retrofit kits, validated low‑GWP systems, and supplier contracts tied to compliance milestones to avoid product obsolescence.
-
Service-centric commercial models: Move up the value stack by packaging maintenance, telemetry and inventory services into subscription contracts that reduce churn and increase lifetime customer value.
-
Channel & partner orchestration: Build distributorship models that blend national accounts with local service partners to manage installation, regulatory permits and first-line repairs.
-
Data & monetization playbook: Deploy data governance and commercial APIs early to unlock insights (assortment performance, location analytics) that can be monetized via advertising or supplier revenue-sharing.
-
Procurement resilience: Hedge material exposure for key structural components and qualify multiple vendors for refrigeration subsystems and controls to limit single-supplier risk.
What PW Consulting’s full report delivers
-
Comprehensive market sizing and scenarios from 2020–2032 with modelled sensitivities to energy prices, regulatory adoption rates and technology diffusion curves.
-
Deep segmentation by product type, application and region, plus bespoke scenario dashboards for portfolio stress‑testing (note: detailed segment tables and regional splits are reserved for the full report).
-
Competitive profiles and M&A screening templates for target prioritization, including validated company intelligence and deal multiples guidance.
-
Practical playbooks — product roadmaps, retrofit decision matrices, lease vs. buy models and service contract templates — tailored to OEMs, operators and large enterprise buyers.
-
Regulatory impact assessment with compliance timelines and cost‑to‑compliance estimates, and a refrigerant transition plan that shows break-even timelines for retrofits versus replacement.
-
Case studies and pilot-readiness checklists for RFID, AI merchandising and micro-market deployments, plus go-to-market strategies for rapid scaling.
Strategic next steps for 2026
-
Immediate: audit installed fleet for refrigerant exposure, energy efficiency label status and retrofit feasibility; prioritize high‑impact sites for compliance investment.
-
Short-term: launch modular pilot programs that validate AI merchandising and telemetry economics in at least two use cases (e.g., transit hub, workplace campus).
-
Medium-term: restructure sales contracts toward service subscriptions with uptime SLAs and data-sharing clauses to capture recurring value.
-
Long-term: assess acquisition targets that fill gaps in service capability, last‑mile logistics or software monetization to accelerate platform outcomes.
Conclusion — positioning for both compliance and growth
2026 will separate organizations that view regulation as a cost center from those that treat it as a catalyst for product differentiation and new revenue streams. The refrigerated vending market is large and growing, but the competitive prize will accrue to firms that combine compliant thermal engineering, modular hardware strategies, and software-driven service models. PW Consulting’s full Refrigerated Food Vending Machine Market report provides the detailed segmentation, risk modelling and executable playbooks executives need to make high‑confidence decisions this year. For teams preparing budgets, sourcing strategies, or M&A pipelines in 2026, the evidence is clear: act now to convert regulatory pressures into strategic advantage.
To access the full dataset, segmentation tables and tactical templates referenced in this preview, contact PW Consulting for the full report and consultancy engagements tailored to your role in the value chain.
For detailed analysis of this topic, please visit the official page: Refrigerated Food Vending Machine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com