

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: High-Speed Specialty Cable Market Poised for Robust Expansion — 9.21% CAGR Forecast Through 2032

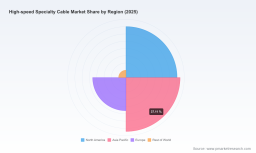
High Speed Specialty Cable Market: Strategic Imperatives for 2026 — PW Consulting Brief
Executive summary
PW Consulting’s latest High Speed Specialty Cable Market report provides a forward-looking strategic compass for corporate decision-makers navigating a dynamic period of technology transition, raw-material volatility, and shifting trade policy. The market that produced roughly USD 5,250 Million in revenue in our base year (2025) is projected to expand at a compound annual growth rate (CAGR) of 9.21% as the industry transitions through 2026 and into the 2026–2032 forecast window. By 2032, our model anticipates the global market approaching approximately USD 9,726.5 Million (USD Million), driven by accelerating data-center bandwidth requirements, continued adoption of active optical and hybrid interconnects, and industrial/critical-infrastructure upgrades.
High Speed Specialty Cable Market
Why this matters for 2026 corporate decisions
- Investment timing: With near-term growth materially above historical averages, capital allocation (capacity expansions, automation, and product platform investments) needs to be synchronized with technology migration curves to avoid stranded assets.
- Procurement risk: Raw-material and trade-policy shocks in 2025–26 require a re-think of sourcing, inventory strategy and contractual terms to protect margins while preserving service levels.
- Competitive positioning: The market is moderately consolidated; top-tier incumbents maintain strong engineering and distribution advantages, but there are accessible niches for fast followers and specialists.
- Commercial strategy: Customers (hyperscalers, telecom carriers, industrial OEMs) are demanding higher-performance, lower-latency interconnects—value capture will favor differentiated systems-level solutions, services and assurance models.
Key market dynamics shaping 2026
Three intersecting forces will define strategic choices next year: demand-side technology transitions, supply-chain and raw-material stress, and trade/regulatory discontinuities.
High Speed Specialty Cable Market
- Technology migration and demand concentration. Data-center networking upgrades, adoption of higher-speed I/O standards, and ongoing fiber densification create asymmetric demand for high-performance cable assemblies and optical interconnects. Buyers are trading up to systems that deliver reliability at scale, expanding addressable revenue but increasing technical complexity for suppliers.
- Raw-material and input-cost pressure. Copper and copper-derived inputs reached unprecedented pressure points in 2025–early 2026. Commodity markets and industry indices are signaling sustained cost inflation for copper wire-and-cable inputs, copper-clad laminates and foil, forcing manufacturers to adjust pricing, reformulate products where possible, and accelerate yield-improvement programs on the factory floor.
- Trade policy and geopolitics. New tariffs and export controls implemented in 2025 altered established sourcing flows for semi-finished and copper-intensive products, and controls on key rare-earths have cascading effects on magnet supply for certain cable systems. These policy changes make geographic diversification and resilient supplier networks a board-level priority.
Competitive landscape — concentration and capability
The industry exhibits moderate concentration characteristics: the three largest players account for a meaningful share of the market and the top five control a materially larger portion. This concentration supports scale-driven R&D and ensures that a set of global incumbents can deliver broad product portfolios and geographic reach, while still leaving room for regional specialists and highly engineered niche players to win on customization and service.
High Speed Specialty Cable Market
At the company level, key competitive archetypes and strategic moves to watch include:
- Large, diversified incumbents (e.g., Amphenol, Prysmian, Nexans). These firms leverage integrated manufacturing, broad channel networks and strong OEM relationships to capture system-level upgrades. Amphenol’s recent performance demonstrates the magnitude of demand in IT/datacom and high-speed interconnect markets; incumbents will continue to invest in platform technologies that serve multi-market needs.
- High-performance fiber and specialty-focused manufacturers (e.g., Sumitomo Electric, Furukawa). These players are concentrating on density, optical performance and reliability—areas that hyperscalers and telecom carriers prize. Continued product launches and high-density innovations are expected to accelerate competition in data-center segments.
- Regional and specialty vendors (e.g., Proterial Cable America, Specialty Cable Corporation, Samtec). These firms compete on rapid product development, micro-distribution designs, and proximity to key customers. Recent product introductions underscore opportunities for specialist providers to win design-ins for niche, high-margin applications.
- Manufacturing and capacity dynamics. Select suppliers are expanding capacity and precision-production capabilities; investments are being directed toward automation and quality control to offset raw-material inflation and raise throughput without proportionate increases in labor costs.
What PW Consulting’s report contains — practical, operational intelligence
Our report is designed as an actionable toolkit for commercial leaders, procurement teams, product and strategy executives. Highlights include:
- Top-line, point-in-time market sizing (2020–2025 historical baseline) and a detailed forecast for 2026–2032 with scenario variants that reflect technology adoption rates and policy shocks.
- Scenario-driven cost and margin modeling that quantifies the impact of raw-material shocks and tariff regimes on product-level profitability and breakeven thresholds.
- Supplier heat maps and vendor capability matrices: engineering pedigree, manufacturing footprint, product roadmaps, and integration readiness—built to support RFP and supplier consolidation decisions.
- Commercial playbooks for pricing, contract design (including indexation and force-majeure clauses), and service-level engineering tailored to hyperscale, carrier and industrial accounts.
- M&A and partnership screening tools that identify pockets of high-margin, defensible niches and acquirable capabilities (IP, specialized manufacturing, or channel access), accompanied by valuation sensitivity models.
- Technology strategy modules: product roadmaps for optical vs. copper-based solutions, migration pathways for customers, and hit-rate models for new connector and cable standards.
- Regulatory and geopolitical risk dashboards tracking tariffs, export controls and critical-material vulnerabilities—integrated with mitigation playbooks for insuring continuity of supply.
To honor the “trailer” principle of this release, we are deliberately summarizing the scope here while withholding segment-level splits and vendor scorecards. The full report contains detailed breakdowns, vendor benchmarking scores, and downloadable modelling assets.
Priority strategic recommendations for 2026
PW Consulting recommends a three-horizon approach to convert market growth into defensible margin expansion and resilience.
- Short term (0–12 months): Stabilize margins and supply.
- Execute supplier stress-tests and reprice contracts with clear indexation clauses to pass-through raw-material movements transparently.
- Establish hedging or strategic inventory programs for critical copper-derived inputs and copper-clad laminates; prioritize supplier dual-sourcing where feasible.
- Pursue targeted capacity buffers for high-demand product families required by data centers and telecom carriers, using short-cycle subcontracting to avoid long-term overcommitment.
- Medium term (12–24 months): Differentiate product and go-to-market.
- Invest selectively in optical and hybrid interconnect architectures that align with customers’ multi-year migration plans; aim for systems that combine product sales with premium service and assurance contracts.
- Develop modular product platforms to reduce SKU proliferation and compress lead times while increasing factory throughput via automation and lean manufacturing.
- Negotiate long-term supply agreements with tier-1 raw-material suppliers, including options for co-investment in critical upstream capacity where strategic.
- Long term (24+ months): Secure structural advantage.
- Pursue tuck-in M&A to acquire specialized manufacturing capabilities or cognitive design assets (e.g., advanced cable modeling, connector engineering) that are otherwise expensive to build organically.
- Position to supply emerging, higher-value applications (defense, aerospace, medical) by investing in qualification and Mil-spec certifications—these segments can provide margin insulation from commodity cycles.
- Build cross-functional scenario-planning capabilities to integrate trade-policy and raw-material volatility into capital planning and product roadmaps.
Investor and board-level implications
For investors, the sector’s mid-to-high single-digit CAGR and the sizable re-rating potential tied to systems-integration and premium service models make selective exposure attractive—but timing and asset quality matter. Boards should insist on stress-tested capex plans that incorporate tariff scenarios, commodity shocks, and customer migration pacing. Equity and debt providers will increasingly value companies that can demonstrate demonstrated supplier resilience and recurring-service revenue streams.
How to use PW Consulting’s research
Our report is built for rapid operationalization: the downloadable modeling workbook can be inserted into capital-planning and procurement workflows, the supplier heat maps inform immediate sourcing decisions, and the M&A screening module accelerates target prioritization. For executives making strategic calls in 2026—pricing, capacity, or M&A—the report functions as a single source of evidence-based guidance calibrated to both upside demand and downside policy risk.
Next steps
To access the full, interactive report—including detailed segment forecasts, vendor scorecards and downloadable modelling assets—visit PW Consulting’s market research portal. The public summary above is intended to present the strategic contours and decision-grade recommendations; the full deliverable contains the granular inputs and proprietary analytics required to execute on the playbook.
For detailed analysis of this topic, please visit the official page: High Speed Specialty Cable Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com