

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Low Salted Sodium Hypochlorite Market Poised for 5.29% CAGR Through 2032

Low Salted Sodium Hypochlorite Market — Strategic Briefing for 2026
Executive summary
The Low Salted Sodium Hypochlorite market is transitioning from a niche specialty product into a predictable, margin-supporting commodity for water-treatment and industrial disinfectant users. Our new PW Consulting report (base year 2025; historical window 2020–2025; forecast 2026–2032) quantifies this transition and translates it into practical decision levers for executives preparing budgets, procurement strategies, and technical pilots in 2026.
Low Salted Sodium Hypochlorite Market
At the macro level, the global market expanded from roughly USD 502 million in 2020 to USD 648.5 million in 2025, and our model projects an expansion to approximately USD 930.3 million by 2032 — implying a compound annual growth rate of 5.29% across the forecast window. That steady growth, together with a mid-level market concentration profile, makes the segment strategically attractive for suppliers seeking scale and for buyers looking to lock in predictable supply and performance gains.
Low Salted Sodium Hypochlorite Market
Why this matters for 2026 corporate decisions
-
Budgeting and procurement: The market’s steady CAGR gives procurement teams a defensible planning envelope for 2026–2028 purchasing and inventory policies. Organizations that move from ad hoc buying to contract structures tied to product-grade performance (rather than only price per liter) can expect improved uptime and lower total cost of ownership.
Low Salted Sodium Hypochlorite Market -
Operational optimization: Recent field validations indicate high-strength, low-salt formulations can materially reduce dosing volumes, degradation losses, and equipment wear. For water utilities and industrial users, 2026 is the window to plan pilot-to-scale substitutions that can free operational budget for capital maintenance or compliance work.
-
Regulatory and stewardship alignment: Certification and product-stewardship documentation are becoming procurement gatekeepers. Buyers and suppliers that align product specifications with recognized standards will shorten validation cycles and accelerate adoption.
What the report delivers — practical content for immediate action
-
Validated market sizing and trajectory: rolling historical estimates (2020–2025) and a scenario-driven forecast (2026–2032) in USD Million, enabling CFOs to stress-test investment cases under conservative, base, and upside demand scenarios.
-
Use-case ROI worksheets: templated analyses for municipal, industrial cooling, food & beverage, and healthcare segments that translate product performance (dosing, shelf life, impurity profile) into OPEX and CAPEX impacts.
-
Procurement playbooks: contract clauses, specification checklists, and tender language that emphasize verified purity, handling requirements, and shelf-life testing rather than headline pricing alone.
-
Supplier scorecards and risk heatmaps: a repeatable framework to evaluate supply concentration, logistics risk, and stewardship readiness — designed for procurement and risk committees to operationalize in 60–90 days.
-
Pilot design templates and KPIs: pragmatic trial designs that replicate field tests demonstrating dosing reduction and stability, including sampling protocols, acceptance criteria, and statistical thresholds for go/no-go decisions.
-
Regulatory alignment checklist: mapping of major certifications and their procurement implications for public utilities and regulated industries, plus recommended interactions with local regulators during specification updates.
Competitive landscape — what buyers and strategists need to know
The market combines several long-established chlor-alkali players and specialized producers. Top producers differentiate on a few clear vectors: concentration (wt% NaOCl), impurity control (chlorate, perchlorate, heavy metals, bromates), filtration and certification (e.g., NSF/ANSI, JWWA), and geographic manufacturing footprint. The market concentration metrics point to a competitive environment where the top suppliers provide nearly half of available volume — sufficient to shape product specifications, but still offering opportunities for regional and technical challengers.
-
Kuehne Company (NJ, USA) — a private chlor-alkali producer that markets concentrated, low-salt formulations under branded product positioning emphasizing long-term stability in municipal applications. Their value proposition focuses on reliability and proven field tenure.
-
HASA Inc. (Valencia, CA, USA) — a leading supplier of premium low-salt hypochlorite, including high-strength variants. Recent independent trial data show substantial dosing reductions and operational benefits versus conventional strengths, making HASA a reference point for performance-based procurement pilots.
-
Olin Corporation (Clayton, MO, USA) — an integrated chlor-alkali incumbent offering high-concentration, low-impurity products alongside a public-facing stewardship manual. That manual signals an industry shift: suppliers are investing in documentation and handling guidance that shorten buyer qualification cycles.
-
Shin-Etsu Chemical (Tokyo) and Kaneka Corporation (Osaka) — established Japanese producers whose low-impurity grades meet stringent domestic water chemistry certifications and appeal to public utilities and food-grade users where specification purity is non-negotiable.
Collectively, these suppliers illustrate two strategic truths: senior buyers will increasingly base supplier selection on validated, field-proven performance and documented stewardship; and suppliers that bundle technical support, certification, and logistics reliability will command the premium portion of the market.
Recent developments that reshaped the 2025–2026 decision agenda
-
Performance validation: A mid-2025 trial conducted at a wastewater treatment facility demonstrated substantially lower usage volumes and improved consistency for a 15.5 wt% high strength low-salt product versus a conventional 12.5 wt% baseline. The practical consequences were lower operating volumes, reduced chemical handling, and measurable operational savings.
-
Formalized stewardship: An incumbent supplier issued an updated product stewardship manual in 2025 that details production capabilities, purity improvements, and handling specifications for super-concentrated low-salt grades. The document reduces buyer onboarding friction and creates a template for industry best practice.
-
On-site generation alternatives: Parallel to blended and concentrated supply strategies, on-site hypochlorite generation systems are maturing and becoming a valid substitute in some use-cases. These systems materially change logistics and procurement trade-offs by eliminating bulk transport and reducing storage risk.
Strategic implications and recommended 2026 actions
-
Run three targeted pilots in 2026: one municipal water utility, one industrial cooling application, and one food-processing site. Use the report’s pilot templates and KPI sets to capture dosing, degradation, equipment impact, and total delivered cost over a 12–18 month window.
-
Revise procurement specifications: Move from density/active-titer-only contracts to performance-and-stewardship contracts that include impurity limits, shelf-life guarantees, and documented handling guidance. Include supplier-provided trial data as contractual proof points.
-
Assess on-site generation as a strategic option: For sites with predictable, high, and continuous demand, build a 5-year TCO comparison that includes capital amortization, energy, labor, and avoided transport risk versus contracted supply.
-
Prepare supply-security playbooks: Given a moderately concentrated supplier base, identify secondary suppliers and logistical redundancies now, and incorporate these requirements into 2026 procurement RFPs.
-
Invest in specification harmonization: For multi-site organizations, centralize chemical specifications and validation protocols to achieve consistency in safety, regulatory compliance, and dosing performance.
Methodology and data reliability
The underlying market model uses a bottom-up build combining historical shipment data (2020–2025), supplier-reported capacities, and end-user dosing surveys validated with field trials and third-party certifications. Forecast scenarios (2026–2032) incorporate demand elasticity for higher-strength grades, potential substitution from on-site generation, and regulatory adoption curves. All financials are expressed in USD Million with a base year of 2025 and a consolidated CAGR of 5.29% for the forecast window.
How to use this briefing — and where to find the rest
This is a strategic briefing designed to accelerate executive alignment in 2026. If you are evaluating pilots, revising procurement language, or considering supplier collaborations, the full PW Consulting report contains the segment-level tables, supplier scorecards, scenario spreadsheets, and the detailed ROI models that operational teams will need to execute.
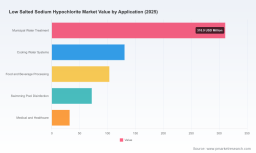
We intentionally withhold the granular regional and application split tables in this summary to preserve the integrity of the model and to ensure downstream conversations are anchored to validated purchase access. Access to the complete dataset, editable financial models, and supplier diligence files is available through our report portal and advisory engagements.
For procurement leaders, operations VPs, and strategy teams preparing 2026 roadmaps: the decisions you make now on specification design, pilot funding, and supplier governance will determine whether your organization captures the operational savings and reliability gains that low-salt hypochlorite can deliver — or whether those gains are captured by peers and competitors instead.
For detailed analysis of this topic, please visit the official page: Low Salted Sodium Hypochlorite Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com