

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Forecasts 13.5% CAGR as Aerial Inspections Market Surges to USD 35.18 Billion by 2032

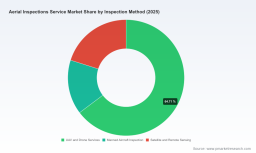
Aerial Inspections Service Market: Strategic Intelligence for 2026 Decision-Makers
PW Consulting's new Aerial Inspections Service Market report (base year 2025) translates a fast-maturing segment of the aerial robotics and remote sensing economy into boardroom-ready guidance for 2026. The report maps a clear growth trajectory — from a multi‑billion-dollar industry in 2025 through sustained double‑digit expansion across the 2026–2032 forecast window (compound annual growth rate: 13.5%) — and converts that macro momentum into pragmatic, low‑risk strategic options for operators, asset owners, investors, and technology suppliers.
Aerial Inspections Service Market
Why this intelligence matters for 2026
As companies plan capital allocation and capability buildouts for 2026, they face three simultaneous dynamics: accelerating adoption of UAV and remote-sensing workflows, shifting regulatory guardrails (notably around BVLOS and critical‑infrastructure restrictions), and intensifying competition among technology-enabled service providers. Our report crystallizes these forces into actionable choices: where to invest, which partners to prioritize, and how to protect service continuity as regulation and labor markets evolve.
Aerial Inspections Service Market
What the report delivers (practical, execution-oriented)
- Market sizing and trajectory: a consolidated market model covering historical performance (2020–2025) and a detailed forecast period (2026–2032) with scenario sensitivity and key growth levers segmented by inspection method, application, and region.
- Regulatory and operational risk matrix: an assessment of existing certification regimes (e.g., FAA Part 107), recent enforcement trends, and likely outcomes from pending BVLOS and critical‑infrastructure rulemakings — with decision triggers and mitigation playbooks for 2026 procurement cycles.
- Competitive playbooks: comparative capability maps and vendor selection criteria that prioritize data management, AI analytics, and field execution scalability over ribbon‑cutting technology demos.
- Go‑to‑market and commercial models: recommended pricing architectures, cost‑savings quantification (including validated industrial inspection cost reductions and time efficiency metrics), contracting templates, and sample ROI calculators tailored to utilities, energy, infrastructure, and industrial asset owners.
- Technology maturity and integration roadmaps: stepwise adoption paths for UAV hardware, multispectral sensors, LiDAR, satellite augmentation, and analytics platforms — linked to internal change management, pilot programs, and supplier enablement plans.
- Case studies and implementation checklists: offshore wind, solar farms, pipeline and LNG terminal inspections and infrastructure asset programs, highlighting common pitfalls, timelines, and resource plans for scalable rollouts.
- Data annex and methodology: transparent model assumptions, primary interview summaries, and a machine‑readable dataset supporting the headline market model (annual series from 2020 through 2032).
Market shape and strategic implications
The aerial inspections market is no longer an experimental niche; it is a mainstream operational lever for large asset owners. With a high‑growth baseline and strong efficiency claims — our synthesis of primary and secondary data confirms inspection time reductions of roughly three quarters and operating‑cost savings that can approach the low‑to‑mid tens of percentage points higher compared with traditional, manual access techniques — decision windows in 2026 will favor organizations that convert pilot programs into enterprise standards.
Aerial Inspections Service Market
At the same time, concentration metrics indicate a fragmented supplier landscape: established specialist providers and platform players coexist with regional integrators and new entrants. The market’s top three and top five suppliers together represent a modest share of total value, underscoring an opportunity for consolidation, strategic partnerships, and differentiated vertical specialization.
Competitive landscape: who to watch and why
- Cyberhawk (Edinburgh, UK): A global leader in drone‑based asset inspection with a mature aerial data management platform (iHawk) and a track record of large energy and industrial contracts. Cyberhawk’s extended contract wins in 2025 signal continued demand for vendor partners that combine field execution with enterprise data workflows.
- DroneDeploy (San Francisco, CA): A platform provider focused on reality capture and enterprise mapping. Recent 2026 product releases and expanded enterprise agreements underline the attractiveness of software‑first approaches that accelerate project standardization across construction and infrastructure portfolios.
- SkySpecs (Ann Arbor, MI): Specialized in wind‑turbine autonomy and blade analytics, SkySpecs exemplifies the value of depth‑focused offerings that pair proprietary autonomy with industry‑specific analytics and lifecycle services.
- Terra Drone Corporation (Tokyo, Japan): A broad service provider with global reach and a growing footprint across defense, infrastructure, and offshore sectors — an example of geographic and vertical diversification as a growth route.
- Raptor Maps (USA): A data‑centric player in utility‑scale solar and large utility inspections; illustrates how domain specialization (solar analytics) creates defensible value based on outcome metrics.
- SAM (Surveying And Mapping, LLC) and Measure (Washington, DC): National providers with strong LiDAR and GIS integration capabilities, catering to infrastructure and municipal asset managers requiring integrated geospatial deliverables.
- AERIUM Analytics: A specialized analytics firm emphasizing tailored industrial and energy use cases, illustrative of the growing mid‑market demand for high‑accuracy, insight‑ready datasets.
Recent corporate activity reinforces two practical themes: platform consolidation and enterprise standardization. For example, DroneDeploy’s 2026 partnership expansion with a major construction contractor and its April product release demonstrate the commercial value of faster data workflows and multi‑model support. Similarly, Cyberhawk’s 2025 contract extensions in the Middle East underline the importance of proven operational experience in regulated and high‑stakes environments. New divisions and entrants focused on offshore and subsea inspections further indicate a widening addressable market footprint.
Regulatory and labor dynamics that will decide winners in 2026
- Regulatory evolution: FAA Part 107 continues to be the baseline for commercial drone operations, but enforcement intensity and programs for expedited violation resolution are rising. Proposed rulemaking around BVLOS and critical infrastructure will materially influence program design and capital planning in 2026 — both enabling scale and imposing new compliance costs. Our report includes a regulatory scenario toolbox that maps likely rule outcomes to operational responses and timelines.
- Labor and cost structure: Unit labor pricing for typical residential and building inspections remains in a defined range, and specialized thermal or complex industrial inspections command premium rates reflecting pilot skill and equipment. Procurement teams must move beyond headline hourly rates and evaluate total cost of inspection (including access, downtime, repeat visits, and data integration effort).
- Operational economics: Independent benchmarks show drone‑based industrial inspections can cut operational costs by 30–70% and inspection time by approximately 75–85% versus legacy manual methods. These efficiency gains are central to crafting compelling business cases — but they must be validated against asset class, inspection frequency, and data processing commitments.
Actionable strategies for 2026
- Prioritize data platforms over single‑fleet purchases: The marginal value in 2026 lies in integrated data ingestion, automated analytics, and seamless export to asset management systems. Contracts should mandate open APIs, exportable metadata standards, and agreed SLAs for detection and reporting.
- Run BVLOS‑ready pilot programs now: With BVLOS regulatory change probable within the near term, early pilots that emulate BVLOS workflows and safety cases will accelerate the transition to scaled operations when permissions arrive.
- Negotiate outcome‑based contracts: Shift from time‑and‑materials to outcome or availability models for repeatable inspection programs. Outcome pricing aligns incentives and captures a portion of the demonstrated operational savings.
- Build vendor redundancy for critical assets: Given the market’s fragmentation and regulatory uncertainty, procure a primary platform partner plus at least one certified regional integrator to de‑risk continuity in complex geographies.
- Integrate inspection data into maintenance planning: Move from periodic inspections to condition‑based maintenance models enabled by analytics, which reduces downtime and optimizes CAPEX cycles.
- Consider M&A and partnerships: For incumbent service providers and systems integrators, acquiring analytic capability or striking exclusive enterprise partnerships can be a rapid path to scale and differentiated IP.
How to use the report in your 2026 planning cycle
Use the report as a decision accelerator: align procurement cycles to the report’s regulatory timelines, test the three recommended commercial models in pilot contracts, and use the scenario tool to stress‑test your capital and staffing plans under conservative and aggressive adoption pathways. The dataset accompanying the report enables quick integration into financial models and board materials.
Conclusion — take the next step
The aerial inspections market is transitioning from tactical pilot projects to strategic capability. For 2026, the critical choices are less about whether to adopt aerial inspections than how to structure adoption for resilience, data ownership, and repeatable value capture. PW Consulting’s Aerial Inspections Service Market report provides the evidence base, operational playbooks, and vendor comparison tools that procurement, operations, and strategy teams need to make those choices defensibly.
To access the full dataset, vendor profiles, and implementation playbooks — including the complete segmentation tables and proprietary model outputs withheld here to preserve the “trailer” of strategic findings — please visit our official report page or contact PW Consulting’s industry team for a briefing.
For detailed analysis of this topic, please visit the official page: Aerial Inspections Service Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com