

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Fully Closed Ventilator Breathing Circuit Market to expand at 5.22% CAGR (2026–2032), rising from USD 1,185.9 Million in 2025 to USD 1,693.3 Million by 2032 as North America Leads with USD 421.9 Million

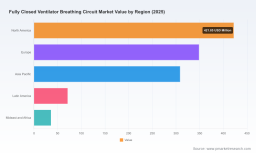
Fully Closed Ventilator Breathing Circuit Market — Strategic Outlook for 2026 Decision-Makers
Executive snapshot
PW Consulting’s new market study on Fully Closed Ventilator Breathing Circuits crystallizes the commercial and clinical dynamics that will shape vendor and buyer strategies in 2026 and beyond. At a macro level, the market reached USD 1,185.86 Million in our base year (2025) and is projected to increase to about USD 1,278.06 Million in 2026, growing at a compound annual growth rate (CAGR) of 5.22% across the 2026–2032 forecast period, with a 2032 projection near USD 1,693.25 Million. Those headline numbers mask markedly different strategic implications for incumbents, challenger brands, distribution partners, and hospital procurement organizations — which is precisely the focus of this report.
Fully Closed Ventilator Breathing Circuit Market
Why 2026 is an inflection point
-
Clinical and operational priorities are converging. Pressure to reduce ventilator-associated complications, combined with demand for longer closed-circuit use in critical care and expanding non-invasive ventilation options, puts closed breathing circuits at the intersection of infection prevention, staff efficiency, and cost control.
Fully Closed Ventilator Breathing Circuit Market -
Technology differentiation is materializing. Innovations such as permeable membrane humidification and vapour-permeable heated circuits reduce condensate and the need for interim water-trap management, which in turn reduces circuit breaks and procedural interruptions. These are no longer incremental features — they alter total-cost-of-care calculations.
Fully Closed Ventilator Breathing Circuit Market -
Channel and care-delivery shifts are accelerating. Growth in ambulatory surgical centers and home-based ventilation expands addressable use cases, while high-acuity hospitals continue to demand validated, integrated solutions compatible with flagship ventilators.
-
Regulatory and reimbursement nuance is increasing. Compliance to device standards (including ISO connectors and relevant U.S. CFR classifications) and evolving reimbursement coding logic influence procurement decisions and product design prioritization.
What this report delivers — practical intelligence for 2026 action
This study is structured as a decision-ready toolkit, designed to be executed against in-year budgets and multi-year roadmaps. Key deliverables include:
-
Robust market sizing and demand scenarios calibrated to a 2026–2032 forecast horizon, with sensitivity analyses that translate macro assumptions into revenue and capacity requirements.
-
Commercial models and buyer-supplier comparators: procurement scorecards, supplier risk heatmaps, and negotiation playbooks tailored to hospitals, ASC groups, and homecare service providers.
-
Technology assessment dashboards that rank humidification and heating approaches by clinical efficacy, regulatory complexity, manufacturing cost, and scale-up risk.
-
Go-to-market playbooks for different strategic positions: incumbent OEMs, low-cost regional manufacturers, and pure-play consumables vendors — each with channel mix, pricing levers, and promotional tactics.
-
Regulatory & clinical evidence roadmaps that sequence 510(k) strategies, ISO compliance, and targeted clinical studies (e.g., VAP reduction, circuit longevity) to support product adoption and purchasing justification.
-
M&A and partnership scouting lists, with operational due diligence templates and integration risk checklists for buyers pursuing consolidation or capability acquisition.
Competitive landscape — strategic takeaways
The competitive topology is a mix of large medical-device OEMs with integrated ventilation franchises, specialist breathing-circuit manufacturers, and an emerging class of cost-competitive suppliers from Asia. Feature- and evidence-led differentiation sits at the top of the agenda for market leaders, while price and supply-security dominate for many buyers.
-
Fisher & Paykel Healthcare (Auckland) continues to set feature expectations with permeable-membrane humidification systems that purposefully minimize condensate and support prolonged closed-system use. Recent regulatory milestones in 2025 underscore their strategy of pairing respiratory delivery hardware with validated accessories to protect circuit integrity.
-
Regional manufacturers such as Plasti-med (Turkey), Unimax Medical Systems (Taiwan), Shenzhen Besdata (China), GaleMed (Taiwan), Cathwide, and Besmed are advancing competitive positions through targeted technology variants (e.g., embedded heated wires, closed-suction compatibility) and lower-cost, high-volume manufacturing footprints. These suppliers are credible partners for high-volume disposable programs and for OEMs seeking contract manufacturing alternatives.
-
Established global OEMs — Armstrong Medical (UK), Teleflex (US), ICU Medical, Dräger (Germany), Medtronic (Ireland), and Hamilton Medical (Switzerland) — leverage brand, distribution reach, and ventilator integration to defend traditional hospital spend. Their strategic playbooks emphasize integrated system-vendor relationships, lifecycle services, and clinically backed consumables bundles.
-
Competitive pressure is fostering hybrid strategies: premium feature sets for high-acuity wards, and cost-optimized disposables for high-volume channels. Expect continued partnership activity between ventilator OEMs and breathing circuit specialists, and selective downstream consolidation where supply reliability and scale matter.
Regulatory, reimbursement and clinical context
Device classification and standards remain a gating factor for product design and market entry. Closed ventilator breathing circuits, depending on configuration, fall into existing breathing circuit and ventilator accessary classifications and are subject to connector and performance standards (including ISO requirements). In the U.S., coding and billing nuance (for example, the treatment of breathing-circuit items under HCPCS guidance) alters how hospitals bundle costs and how suppliers justify pricing.
Clinically, closed suction systems and circuit integrity are core components of ventilator-associated pneumonia prevention bundles. Vendors that can demonstrate reduced circuit breaks, lower condensate management burden, and measurable improvements in workflow and infection metrics will have a stronger commercial narrative in procurement dialogs.
2026 playbook — five prioritized moves
-
Prioritize condensate-reducing technologies that demonstrably lower staff interventions. Invest in clinical validation that links device features to workflow time-savings and infection metrics — those studies accelerate procurement approvals.
-
Bolster supply resilience through dual-sourcing and regional manufacturing partnerships. High-volume disposable demand makes operational continuity a primary commercial defense.
-
Segment product lines by channel economics. Offer modular portfolios: feature-rich options for ICU/high-acuity settings and streamlined, cost-optimized disposables for ambulatory and home-care channels.
-
Prepare regulatory dossiers and reimbursement evidence early. Anticipate interoperability testing and ISO connector audits; align submission timelines with product launch roadmaps.
-
Use targeted M&A or JV activity to fill capability gaps quickly — whether that is heated-wire expertise, closed-suction IP, or regional manufacturing scale. A focused bolt-on can shorten time-to-market versus organic development.
How PW Consulting’s research accelerates your 2026 agenda
Clients who use this report gain access to a layered set of assets: a financial model you can drop into board-level strategic planning, supplier scorecards that feed procurement RFPs, clinical evidence templates to support internal business cases, and a deal-ready shortlist of acquisition targets that have been pre-screened on technical and commercial criteria. The study combines primary interviews with purchasing managers and clinicians, factory-level supply-chain assessments, and a proprietary demand forecasting engine that translates macro adoption drivers into product-type requirements and capacity needs.
Closing — the decision-making edge
For organizations making allocation decisions in 2026 — whether investing in product R&D, negotiating multi-year supply agreements, or assessing acquisition targets — the fully closed ventilator breathing circuit market presents both structural growth and execution risk. The market’s steady expansion, as reflected in our base-year and forecast figures, rewards initiatives that tie product performance to measurable clinical and operational outcomes, and that secure manufacturing resilience without sacrificing innovation.
PW Consulting’s full report provides the granular, actionable intelligence necessary to move from strategic intent to executable plans. For the detailed segment-level breakdowns, company dossiers, pricing benchmarks, and downloadable models that underpin these conclusions, access the full report at PW Consulting’s market studies portal.
For detailed analysis of this topic, please visit the official page: Fully Closed Ventilator Breathing Circuit Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com