

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
PW Consulting: Advanced Insulation Materials Market Poised for a 9.24% CAGR, Fueling Energy-Efficiency Gains
By pmarketresearch, 2026-07-07
Advanced Insulation Materials 2026: A Strategic Brief for Decision-Makers
PW Consulting’s Advanced Insulation Material Market Research (base year 2025) synthesizes the near‑term imperatives that will shape capital allocation, product strategy, and supply‑chain design across the insulation value chain in 2026. This briefing pulls the strategic threads from our full study—market sizing, competitive dynamics, regulatory inflection points, and practical playbooks—so executives can prioritize decisions this year. Consider it a trailer: we reveal the structural trends and action levers but reserve the full, transaction‑grade data and segment cross‑tables for the complete report.
Advanced Insulation Material Market Research
Market snapshot: growth with opportunity and complexity
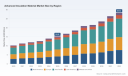
The advanced insulation market has moved from a niche performance play into a mainstream industrial imperative. After steady expansion through the early 2020s, total industry revenues reached approximately USD 15.3 Billion in 2025 and are projected to continue on a multi‑year expansion path. Our forecast shows the market growing at a compound annual growth rate (CAGR) of approximately 9.24% across the 2026–2032 horizon, reaching the high‑twenties (USD Billion) by 2032. This pace reflects simultaneous demand drivers: building energy efficiency mandates, electrification of transport and energy networks, and thermal management needs in industrial and cryogenic applications.
Advanced Insulation Material Market Research
Market concentration remains meaningful but not monopolistic: the top three players together control roughly one third of the market, and the top five account for just under half. That structure creates both scale advantages for incumbent integrated producers and opportunity windows for specialized innovators and regional challengers.
Advanced Insulation Material Market Research
Why this matters for 2026 corporate decisions
- CapEx prioritization: With regulation and product innovation shifting product mixes toward higher‑performance solutions (aerogels, vacuum panels, advanced PCM systems), boards must decide whether to invest in internal capacity expansions, technology licensing, or strategic partnerships. Our analysis quantifies payoff curves for each route under multiple oil/raw‑material and tariff scenarios.
- Supply‑chain resilience: Raw‑material volatility and trade measures mean procurement strategies established in 2020–2021 are insufficient. The report models inventory and sourcing hedges that materially reduce marginal cost exposure while balancing working capital.
- Product roadmap and regulatory compliance: New regulatory thresholds and chemical restrictions are changing acceptable formulations and thermal performance baselines. Companies that accelerate reformulation and certification for public‑sector procurement will capture high‑margin, low‑volume contracts.
- M&A and ecosystem plays: The combination of moderate concentration and technology fragmentation makes 2026 a favorable year for bolt‑on acquisitions and licensing of highly differentiated materials (e.g., aerogel composites, cryogenic blankets) to enter adjacent markets.
Context drivers—what is forcing the change now
- Regulatory tightening: Public procurement and construction standards have raised the bar for thermal performance in 2025–2026, with binding limits that favor materials delivering lower thermal conductivity. At the same time, chemical regulations are phasing out high‑GWP agents in key jurisdictions, forcing rapid reformulation.
- Raw‑material and logistics volatility: Feedstock dynamics have introduced tangible cost shocks and uncertainty. Procurement teams are evaluating regional hedging, long‑term offtakes, and supplier diversification as core mitigation strategies. Concurrently, maritime and logistics cost dynamics have added effective transport surcharges on transoceanic flows that tilt competitiveness for production footprints.
- Trade policy: New countervailing duties and tariffs on certain imported insulation products have rapidly reshaped price competitiveness and created near‑term windows for local producers to capture share.
- Technological differentiation: High‑performance products—particularly aerogels and advanced vacuum systems—are transitioning from specialty use cases into commercial growth segments where performance‑to‑cost ratios are improving thanks to production innovations and scale.
Competitive landscape—how incumbents and specialists are positioning
Our competitive mapping segments players along two dimensions: breadth of product portfolio (multinational chemical majors and building‑materials groups) and technology depth (specialists in aerogels, cryogenics, or tailored polymer systems). This yields three strategic archetypes with different operational implications:
- Integrated chemical champions: Firms with diversified upstream chemical and polymer platforms are using their feedstock access and global channels to defend volume markets and invest in low‑GWP reformulations. Examples include major chemicals groups that continue to expand insulation foam capacity and leverage scale to amortize R&D.
- Building‑materials conglomerates: Large building‑product manufacturers combine thermal and acoustic performance in packaged systems and pursue certification credentials and sustainability badges to win large institutional and public contracts.
- High‑performance specialists: Focused technology companies commercialize premium materials—e.g., aerogel blankets and cryogenic super‑insulation—that command higher margins in energy, subsea, aerospace, and EV battery thermal management.
Across these archetypes, our analysis profiles a representative set of market participants—companies with global scale and those driving niche innovations. Their recent moves are instructive:
- Capacity investments by multinational producers reflect a defensive strategy to secure feedstock integration and maintain supply for core foam products.
- Specialist product launches targeting electric‑vehicle thermal management and subsea energy applications demonstrate how new end‑use demand is opening adjacent revenue pools.
- Third‑party certifications and sustainability credentials are increasingly table stakes for winning institutional construction projects; firms achieving higher sustainability ratings capture premium tenders.
Operational playbook for 2026 (executive checklist)
- Immediate (0–6 months): Run rapid scenario tests on your current product mix against the updated regulatory matrix and tariff landscape; prioritize reformulation of any lines exposed to high‑GWP agent bans. Commence supplier stress tests for critical polyol and blowing‑agent supply.
- Near term (6–18 months): Lock strategic offtake agreements or explore co‑investment with regional manufacturers to bypass punitive import tariffs and elevated trans‑Pacific logistics surcharges. Accelerate certification programs for your highest‑margin products for public‑sector procurement.
- Medium term (18–36 months): Revisit plant footprint decisions—evaluate nearshoring of intermediate inputs, capacity expansions in lower‑cost jurisdictions with favorable trade access, and selective M&A of specialized aerogel or PCM technology firms to secure differentiation.
Risk matrix and sensitivity highlights
The full report includes probabilistic scenario outputs; highlight risks that should be monitored closely in 2026:
- Material price shock: A sustained increase in polyol/monomer feedstocks will compress margins on commodity foams and accelerate demand for higher‑value, lower‑thickness solutions.
- Regulatory acceleration: Faster‑than‑expected rollouts of limits on thermal conductivity or phase‑out of specific blowing agents will re‑rank supplier competitiveness.
- Trade disruptions: Tariff and surcharge regimes can create immediate windows of winners and losers in regional procurement cycles; nimble production redeployment will be rewarded.
What the full PW Consulting report delivers (practical inclusions)
- Dynamic market model with annualized revenue forecasts through 2032 and configurable drivers for price, volume, and substitution effects.
- Supplier scorecards, technology maturity matrices, and unit‑economics benchmarks to support sourcing and product decisions.
- Regulatory impact mapping across major markets and a compliance timeline for formulation and performance standards.
- Three invest/divest/M&A scenarios with recommended deal structures and integration checklists.
- Actionable dashboards and Excel workbooks that buyers, product managers, and corporate strategy teams can adopt to run bespoke sensitivity runs.
These deliverables are designed to move teams from strategic intent to operational execution quickly: the models are transaction‑grade and ready for board or investor review, but—as a conscious editorial choice—we withhold the full segment‑level and region‑application matrices in this public briefing to preserve the competitive value of the datasets contained in the full report.
How leaders are already responding
Market leaders and technology specialists are deploying three common tactics: (1) securing feedstock and logistics resilience via long‑term contracts and regional production pivots; (2) accelerating product certification and sustainability credentials to capture institutional demand; and (3) selectively acquiring or partnering with niche technology providers to shorten time‑to‑market for premium thermal solutions. These tactics are evident across recent product launches, capacity announcements, and certification milestones.
Final guidance for 2026 strategy
2026 will reward firms that treat advanced insulation as a strategic category rather than a cost line item. Boards should expect this category to drive differentiated returns through product premiumization, tighter regulatory‑driven demand, and new industrial use cases (e.g., battery thermal management, cryogenics). The companies best positioned will be those that combine flexible manufacturing footprints, prioritized R&D spend on low‑GWP and low‑conductivity solutions, and an M&A playbook that brings niche performance technologies into scalable channels.
PW Consulting’s Advanced Insulation Material Market Research provides the analytical foundation and execution templates to convert these strategic imperatives into measurable value. To access the full dataset, interactive models, and supplier-by-supplier analysis, visit PW Consulting’s report page for the comprehensive report and advisory packages.
For detailed analysis of this topic, please visit the official page: Advanced Insulation Material Market Research
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Pharma Sustained Release Agent Market to Climb from USD 2,540 Million in 2025 to USD 3,947.12 Million by 2032 at a 6.5% CAGR
By pmarketresearch, 2026-07-07
Pharma Sustained Release Agent Market — Strategic Outlook for 2026 Decision-Making
PW Consulting today publishes an executive-level briefing derived from our forthcoming full market research report on the Pharma Sustained Release Agent market. Built on a base year of 2025 and a detailed historical review covering 2020–2025, our analysis projects the market through 2032. At the aggregate level the market has grown from approximately USD 1,850 Million in 2020 to USD 2,540 Million in 2025, and we model a continuation of that expansion to roughly USD 3,947 Million by 2032 — a compound annual growth rate (CAGR) of 6.5% over the 2026–2032 forecast period. This release summarizes the practical strategic value the full report delivers to executives who must set direction in 2026 while intentionally withholding the granular segment-by-segment tables that subscribers will find in the published product.
Pharma Sustained Release Agent Market
Why this report matters for 2026 strategy
-
Timing and scale: The market’s mid-single-digit CAGR coupled with steady expansion after 2025 creates a planning horizon in which near-term investments (2026–2028) can be sized to capture durable share through 2032. Our forecast provides the topline growth trajectory and the scenario-driven sensitivity that CFOs and strategy teams need to size capex and working capital.
Pharma Sustained Release Agent Market -
Portfolio prioritization: For product and formulation leaders, the report translates aggregate growth into practical prioritization principles — when to invest in hydrophilic matrices versus membrane systems, and which formulation routes justify pilot-to-commercial scale-up in the 2026 window.
Pharma Sustained Release Agent Market -
Sourcing and supply resilience: Procurement teams can use the intelligence to redesign supplier strategies, balancing price volatility and regulatory risk (notably cellulose feedstock and chemical additives) while sizing strategic safety stock and dual-sourcing contracts for 2026.
-
Commercial go-to-market: For sales and BD leaders, the report frames market access timing, channel strategies, and partnering archetypes that have the highest expected return on investment in the near term.
What the full report delivers (operationally usable content)
-
Topline market model (USD Million, base year 2025) with alternative scenarios to stress-test 2026 plans against downside raw-material shocks and accelerated regulatory change.
-
Actionable playbooks for formulation teams: stepwise reformulation checklists, typical development timelines, and cost-impact templates for substituting plasticizers and binders under different regulatory constraints.
-
Supplier scorecards and heatmaps: capability assessments, reliability metrics, and tactical supplier selection frameworks you can slot directly into procurement RFPs.
-
Regulatory heatmap and compliance pathways covering global regimes that materially affect sustained release excipients, enabling legal and regulatory teams to prioritize filings and labeling changes.
-
M&A and partnership playbook: target profiling, acquisition valuation heuristics, integration risk checklists, and three deal archetypes that are most likely to accelerate a buyer’s presence in sustained release formulations.
-
Commercial and pricing dashboards: suggested list- and net-price scenarios, margin sensitivity analyses, and tender-win playbooks for contract manufacturers and ingredient suppliers.
Competitive landscape: who shapes supplier strategy in 2026
The sustained release agent supplier ecosystem is moderately concentrated: the top three global players account for a meaningful portion of the market and the top five increase that concentration materially. This structural dynamic creates both opportunity and constraint for formulators and ingredient buyers.
-
Dow — With a strong presence in established cellulose ethers (Methocel™) and ethylcellulose chemistries, Dow’s recent capacity expansion underscores an emphasis on scale and reliability. For buyers, Dow’s footprint is attractive for high-volume programs that demand continuity of supply; for competitors, capacity investments signal intensified price and service competition in mainstream matrix systems.
-
Ashland — Benecel™ and Aqualon™ portfolios continue to be positioned around hydrophilic matrix and film-coating solutions. Ashland’s recent halal and kosher recertifications highlight the commercial value of broader market access credentials — a practical consideration for companies targeting multi-market launches.
-
Evonik — The Eudragit® franchise offers differentiated functional polymers (pH-dependent and insoluble types) important for enteric, delayed, and sustained-release coatings. Product innovation such as new grades for hot-melt extrusion and taste-masking reflects R&D-led displacement opportunities in niche fast-growing formulation techniques.
-
Colorcon, Shin‑Etsu, JRS Pharma, Lubrizol, BASF, Roquette — Each of these players brings distinct strengths: specialized coating systems, regionally entrenched distribution, multiparticulate platforms, carbomer-based technologies, and starch-derived matrices. The competitive map in our report includes comparative positioning on technology readiness, regulatory footprint, and customer-service metrics critical to sourcing decisions.
Market dynamics and regulatory forces that will shape 2026 choices
-
Raw-material volatility: Our supply-chain analysis traces the downstream impact of a step-change in cellulose feedstock costs that occurred in 2022. A documented single-year increase in pharmaceutical-grade wood pulp disrupted HPMC supply chains and continues to inform contract hedging and vertical-integration considerations.
-
Regulatory tightening: Changes such as REACH limitations on certain plasticizers and California’s product-warning requirements raise both compliance costs and formulation constraints. These dynamics accelerate reformulation timelines and favor suppliers with low-regulatory-risk portfolios.
-
Trade policy and tariffs: Ongoing tariff regimes affecting imported cellulose ethers influence landed cost and are likely to drive nearshoring or alternative sourcing strategies for critical excipients.
-
Innovation vectors: Adoption of hot-melt extrusion, multiparticulate drug delivery, and novel polymer chemistries (including taste-masking grades and MAE-based coatings) is creating pockets of higher-margin growth that reward early technical partnerships and co-development agreements.
Recommended strategic moves for 2026 (high-confidence actions)
-
Lock in multi-year supply agreements for critical cellulose grades while incorporating indexed price collars to mitigate near-term raw-material swings.
-
Accelerate reformulation of sensitive products where plasticizer restrictions or label risks (e.g., Prop 65) are likely to trigger costly recalls or relabeling within a two- to three-year horizon.
-
Prioritize discretely scaled piloting of advanced delivery platforms (hot-melt extrusion or multiparticulate) for assets with favorable life-cycle economics; use stage-gate financial models from the report to decide go/no-go thresholds.
-
Use supplier scorecards and scenario-driven valuation frameworks to triage M&A targets: favor targets that deliver immediate technical differentiation or materially reduce feedstock exposure.
How PW Consulting’s deliverables lower execution risk in 2026
The full report is intentionally structured to be executable: each strategic recommendation is paired with a short implementation checklist, a risk register, and a stakeholder-ownership template. Clients can translate topline forecasts into procurement contracts, R&D roadmaps, and M&A diligence workstreams within weeks rather than quarters.
A note on the preview and next steps
This briefing is a curated preview: we have deliberately withheld the detailed subsegment tables and exact regional and application-level splits to ensure readers engage with the full dataset available in the complete report. Subscribers receive the full financial model (USD Million, 2020–2032), detailed supplier matrices, and reproducible scenario tools. If your 2026 strategic planning requires validated forecasts, supplier risk scoring, or an executable step-by-step playbook — PW Consulting’s full Pharma Sustained Release Agent Market report provides those deliverables.
To discuss bespoke strategic engagements, scenario workshops, or to purchase the full report and underlying model, contact PW Consulting’s Life Sciences practice. Our team will help translate these insights into an operational plan that protects margins, accelerates launches, and mitigates regulatory and supply risks across the 2026 planning cycle.
For detailed analysis of this topic, please visit the official page: Pharma Sustained Release Agent Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Bluetooth Audio IC Market Set to Expand at an 11.85% CAGR Through 2032 as TWS and Dual‑Mode ICs Drive Growth
By pmarketresearch, 2026-07-07
Bluetooth Audio IC Market 2026: Strategic Imperatives from PW Consulting’s Forthcoming Industry Brief
Executive snapshot
PW Consulting’s new Bluetooth Audio IC Market report (base year 2025, forecast 2026–2032) synthesizes market, technology and competitive intelligence into an operational playbook for decision-makers entering 2026. At a macro level, the Bluetooth audio IC market expanded from USD 3,820.5 Million in 2020 to USD 6,720.0 Million in 2025, and our top-line model projects the market to grow to approximately USD 14,717.08 Million by 2032 — implying a compound annual growth rate (CAGR) of 11.85% over the forecast window. Market concentration remains meaningful (CR3 ~58.4%; CR5 ~72.2%), creating both opportunity and entry barriers depending on a firm’s strategic posture.
Bluetooth Audio Ic Market
Why this report matters for 2026 planning
-
Strategic clarity in a technology inflection: 2024–2026 marks the industry’s transition from legacy audio profiles to LE Audio, LC3 codecs and expanded low‑power topologies. Firms that align product roadmaps and supply strategies with these shifts will capture disproportionate value.
Bluetooth Audio Ic Market -
Supply‑chain resilience during geopolitical friction: export controls, tariffs and foundry lead‑time normalization are tangible constraints that must be embedded in sourcing and product timing decisions.
Bluetooth Audio Ic Market -
Competitive positioning: with a moderate-to-high concentration among top vendors, nuanced vendor selection, IP licensing and co‑development strategies are critical for OEMs and fabless entrants.
What the report delivers — practical, transaction‑ready intelligence
This is not a theoretical forecast. The report is structured to be used at the board and product‑line level to make 2026 resource allocation, procurement and M&A decisions. Key deliverables include:
-
A validated top‑down market model that reconciles historical shipments and revenue (2020–2025) with a granular forecast (2026–2032) — including scenario runs for technology adoption and price deflation curves.
-
Technology adoption maps that align Bluetooth core releases (including Bluetooth 5.4 and LE Audio mandates such as LC3) with product life cycles across hearables, speakers, automotive gateways and wearable segments.
-
Supplier and component risk matrices that integrate foundry lead times (post‑shortage normalization in 40nm processes), export control exposure and tariff impacts to quantify supply risk and cost exposure by sourcing strategy.
-
Commercial playbooks for OEMs and chip vendors — including go‑to‑market sequencing, channel structuring, pricing levers and software/service monetization options (e.g., codec licensing, bundled voice/ANC algorithms, and ecosystem integrations such as Matter).
-
Deal support tools: vendor scorecards, an M&A screening framework tuned to Bluetooth IC economics, and LBO/ROI templates for near‑term consolidation opportunities.
Market dynamics: drivers, constraints and inflection points
-
Driver — LE Audio and Low‑Power Codecs: The LC3 codec and LE Audio profile represent the most significant tech driver for the next phase of growth. They enable superior perceived quality at lower bitrates and open functionality (audio sharing, improved hearing aids support) that widens addressable markets.
-
Driver — Consumer hearables and immersive audio: Continued demand for true wireless stereo (TWS) with better ANC, spatial audio and lower latency keeps product cycles short and upgrade rates high for premium segments.
-
Constraint — Geopolitical and regulatory overlay: Export controls on advanced semiconductor manufacturing equipment and trade actions (including recent tariff considerations) are reshaping supplier strategies and may lengthen qualification cycles for cross‑border sourcing.
-
Constraint — Foundry cadence and node economics: While lead times for legacy nodes (e.g., 40nm) have stabilized versus the shortages of 2020–2023, capacity planning and multi‑node sourcing remain essential for cost and time‑to‑market control.
Competitive landscape — what to watch in 2026
The market exhibits a hybrid structure: several large, vertically integrated incumbents maintain substantial share while specialized regional and systems‑level players push on price/performance or unique IP. Our report profiles each strategic player across product roadmaps, channel reach and IP stacks. Highlights:
-
Qualcomm (San Diego): Continues to lead on integrated solutions and value‑added software stacks (e.g., Snapdragon Sound, aptX family, and LE Audio support). Expect continued emphasis on system‑level differentiation — silicon + software + certification pathways.
-
Realtek (Hsinchu): Competes aggressively on cost‑performance for mass segments with SoC families optimized for TWS. Watch their moves on platform integrations and reference designs that accelerate OEM qualification cycles.
-
Airoha Technology (Zhubei): Positioned for premium TWS with low‑latency and AI‑assisted ANC; certifications around LE Audio increase attractiveness to premium hearable OEMs.
-
BES Technic (Shanghai): Focused on high‑fidelity audio and power efficiency specific to TWS and hearables — incremental innovations in ANC and spatial audio are differentiators.
-
Nordic Semiconductor (Trondheim) and Texas Instruments (Dallas): Niche leadership in LE Audio stacks and low‑power SoCs for hearables, wearables and audio gateways; valuable partners for OEMs targeting fast time‑to‑market with new Bluetooth profiles.
-
Espressif (Shanghai) and STMicroelectronics (Geneva): Compete on embedded platforms combining Wi‑Fi/Bluetooth convergence and MCU integration — relevant for IoT and smart speaker implementations.
Recent vendor moves we track (examples): new LE Audio‑capable SoC introductions, sample programs for ultra‑low power chips, and product certifications that shorten OEM adoption cycles. These signals accelerate adoption curves and should be read as leading indicators rather than isolated press items.
Strategic implications and recommended actions for 2026
Our work translates insight into immediate actions. For C‑suite and product leads preparing 2026 plans, PW Consulting recommends the following prioritized steps:
-
Embed LE Audio into the product roadmap now: prioritize LC3 codec plans and software stack readiness in product specifications for any new hearable or gateway launches scheduled in 2026–2027.
-
Adopt a dual‑track sourcing strategy: qualify at least two suppliers across different geographies and node ecosystems to mitigate export control and tariff shocks while preserving price competitiveness.
-
Pursue software and services monetization: move beyond silicon sales — codec licensing, cloud‑enabled audio features and subscription services increase lifetime value and create differentiation.
-
Accelerate collaboration with hyperscalers and standards bodies: interoperability and certification (e.g., Matter integrations, Bluetooth SIG timelines) materially shorten OEM time to market — engage early.
-
Use concentration strategically: small-to-medium players should target white‑space product niches and partner with higher‑tier vendors for co‑development. Large incumbents should consider tuck‑ins to secure IP in ANC/spatial audio or low‑power audio algorithms.
-
Operationalize a regulatory‑aware product calendar: layer compliance and export risk into lead‑time assumptions and inventory policy to avoid late‑stage qualification delays and pricing shocks.
What we intentionally withhold — and why
In keeping with our “trailer” principle, this release highlights the analytical depth, strategic conclusions and operational tools included in PW Consulting’s Bluetooth Audio IC Market report, but it does not reproduce the detailed segmentation tables, regional/application percentage splits or supplier scorecard numerical grids that are central to vendor selection and deal execution. Those datasets are curated, proprietary, and presented in interactive formats (model workbooks, supplier matrices and scenario dashboards) within the paid report to preserve commercial value and prevent misinterpretation outside context.
How to use the full report in 2026 decision cycles
Clients typically use our deliverables in three ways: (1) immediate 90‑day actions (supplier qualification and roadmap adjustments), (2) medium‑term investment planning (capex and R&D prioritization aligned with forecasted price declines and volume ramps), and (3) M&A screening (target lists based on product/technology gaps and market access). The report’s scenario module enables finance and strategy teams to stress‑test plans under different technology adoption and tariff outcomes — making it a practical tool for 2026 budgeting rounds.
Next steps
For procurement leads, product managers and corporate strategists preparing 2026 plans, the full PW Consulting Bluetooth Audio IC Market report contains the operational datasets, vendor playbooks and financial templates needed to translate market momentum into measurable outcomes. To access the interactive models, supplier scorecards and full vendor profiles, please visit PW Consulting’s reports page or contact our industry practice team for a briefing and tailored executive summary.
For detailed analysis of this topic, please visit the official page: Bluetooth Audio Ic Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Fully Closed Ventilator Breathing Circuit Market to Grow at 5.22% CAGR, Reaching USD 1,693.25 Million by 2032
By pmarketresearch, 2026-07-07
Fully Closed Ventilator Breathing Circuit Market — Strategic Imperatives for 2026
PW Consulting’s new market study on Fully Closed Ventilator Breathing Circuits is designed as the operational intelligence playbook that healthcare OEMs, strategic buyers, hospital procurement teams, and investors will use to shape decisions in 2026. Built on a publicly validated forecasting approach and primary interviews across clinical, regulatory and procurement stakeholders, the report translates macro momentum into executable strategic choices. The headline: the market has expanded from roughly USD 940.3 Million in 2020 to an estimated USD 1,185.86 Million in 2025 (base year), and is forecast to grow to approximately USD 1,278.06 Million in 2026 and beyond — a compounded annual growth rate (CAGR) of 5.22% across the 2026–2032 forecast window, reaching roughly USD 1,693.25 Million by 2032.
Fully Closed Ventilator Breathing Circuit Market
Why 2026 is a Pivotal Year
-
Market inflection: After a period of post-pandemic consolidation, 2026 is when product differentiation — not just capacity — will determine winners. Growth is steady and driven by clinical emphasis on infection control, closed-system compatibility with modern ventilators, and technologies that materially reduce condensate and circuit maintenance frequency.
Fully Closed Ventilator Breathing Circuit Market -
Procurement transition: Hospitals and integrated delivery networks are shifting procurement criteria from lowest cost per unit to total cost of ownership (TCO), factoring in reduced circuit breaks, lower device-associated infection rates, and servicing overhead. For manufacturers, this creates an opening for bundled consumable-service models.
Fully Closed Ventilator Breathing Circuit Market -
Regulatory and reimbursement pressure: Continued harmonization around ISO connector standards and guidance within 21 CFR pathways means product interoperability and documented performance will be commercial prerequisites in many markets. Meanwhile reimbursement complexity (e.g., HCPCS billing constraints) is squeezing standalone pricing leverage for breathing circuits, especially where they are tied to higher-frequency servicing codes.
Technology and Clinical Drivers — What Really Moves Adoption
-
Condensate management technologies — permeable membranes, vapour-permeable tubing, and embedded heated-wire approaches — are no longer niche: they materially extend closed-system run-times and reduce water trap changes, directly affecting clinical workflow and device-associated pneumonia risk. Examples of these approaches appear across leading vendors’ portfolios and are central to clinical value propositions.
-
Disposable versus reusable dynamics are being re-evaluated through lifecycle lenses: infection-control priorities and single-patient disposable strategies increase demand for single-use, while sustainability and cost pressures keep reusable autoclave-capable options relevant in specific settings.
-
Closed suction integration: systems that preserve circuit integrity while enabling secretion management are becoming essential in bundled ventilator-care pathways. Clinical guidelines and hospital protocols increasingly list closed suctioning as part of VAP reduction bundles.
Competitive Landscape — Leaders, Challengers and Strategic Positioning
The competitive field is mixed: global ventilator and anesthesia players offer integrated systems and scale; specialised respiratory-supply manufacturers emphasise niche technical differentiation and fast innovation cycles. Market concentration is moderate — the combined share of the top three players is approximately 38.5%, and the top five combine for roughly 52.3% — indicating meaningful room for niche specialists and M&A consolidation.
-
Fisher & Paykel Healthcare (Auckland) — A technology leader in humidification and condensate management with the Evaqua family and permeable membranes. Recent regulatory activity (including multiple 510(k) clearances in 2025) reinforces their product-compatibility play across single- and dual-limb applications and extends their non-invasive ventilation accessory footprint.
-
Armstrong Medical (UK) — Focused on heated circuits with vapour-permeable approaches that reduce water-trap dependency. Their product design philosophy targets long closed-circuit runs, an attractive proposition for high-acuity hospitals looking to reduce circuit handling.
-
Major ventilator OEMs and critical-care suppliers (Dräger, Medtronic, Hamilton Medical, Teleflex, ICU Medical) — Leverage integrated device-channel relationships and established hospital procurement contracts to bundle circuits with ventilator systems or disposables portfolios; their scale supports global distribution but can be slower to iterate niche condensate innovations.
-
Regional and specialised manufacturers (Plasti-med, Unimax, Besdata, GaleMed, Cathwide, Besmed) — Compete through localized manufacturing, cost flexibility, and focused product variants such as closed suction-compatible circuits, spiral embedded heated-wire designs, and short-run customization for neonatal or specialty ventilation.
For market entrants and investors, the strategic calculus is clear: mobility across contract channels and a defensible IP/technology advantage in humidity and condensate management will win premium positioning, while scale and integration enable steady share capture in institutional channels.
Regulatory, Reimbursement and Clinical Context — Framing Risk and Opportunity
-
Regulatory baseline: Breathing circuits fall under established device classifications (including 21 CFR 868.5240 and related accessory classifications) and must meet ISO connector and performance standards (e.g., ISO 5367). Compliance plus clear clinical-use validations materially reduces adoption friction among buying hospitals.
-
Reimbursement nuance: In certain jurisdictions, breathing-circuit codes exist but are constrained when billed alongside frequent servicing codes — a dynamic that erodes unit-level pricing power and elevates the importance of demonstrating TCO advantages tied to clinical outcomes.
-
Clinical imperative: Closed systems that demonstrably reduce ventilator-associated complications align with infection-control bundles and are increasingly used as evidence in procurement RFPs. Clinical evidence and real-world utilization data are decisive in converting pilot projects into enterprise contracts.
What PW Consulting’s Report Delivers — Practical, Executable Intelligence
-
Market forecast model (USD Million) with sensitivity scenarios across 2026–2032, including downside/recovery and adoption inflection permutations.
-
Technology ROI calculators that quantify savings from extended closed-circuit runtime, reduced water-trap changes, and lower VAP incidents — convertible into hospital procurement scorecards.
-
Supplier scorecards and comparative matrices covering product specifications, clinical evidence strength, regulatory status, manufacturing footprint and supply-chain resilience.
-
Regulatory roadmap and ISO/21 CFR conformance checklist for rapid product registration planning and risk mitigation by geography.
-
Commercial playbooks: tender and RFP templates, channel-partner models, and pricing architectures aligned to TCO messaging rather than unit price competition.
-
M&A and partnership shortlists: targeted diligence checklists for bolt-on technology, clinical data asset acquisition, and regional manufacturing scale-ups.
-
Patient-setting adoption maps and go-to-market segmentation that translate macro forecasts into targeted near-term opportunities — from high-acuity hospital ICUs to ambulatory and home-care settings.
Actionable Recommendations for 2026
-
For manufacturers: Prioritise condensate-management IP and interoperability with leading ventilator platforms. Invest now in clinical outcomes studies that convert operational benefits (reduced handling, fewer circuit breaks) into procurement KPIs.
-
For distributors and service providers: Build bundled maintenance and consumables offers that explicitly reduce buyer TCO; create flexible contract terms that scale with usage intensity.
-
For hospital systems and IDNs: Reframe procurement metrics to include clinical impact and lifecycle cost. Pilot closed-circuit technologies in high-acuity units where benefits on device-associated infection and staff time are most measurable.
-
For investors and M&A teams: Target specialised technology vendors with demonstrable condensate-management advantages and strong clinical evidence. Consider roll-up strategies to create a full-stack respiratory-consumables provider with cross-sell synergies.
How to Use This Report in Your 2026 Planning Cycle
This study is structured as an execution tool for 2026 planning cycles. Use the forecast and scenario outputs to size near-term addressable markets for new product launches. Leverage supplier scorecards during RFP reformulation. Deploy the ROI tools in internal business-cases to reprice circuits on a TCO basis. And, for C-suite decision-making, apply the M&A screen to prioritize targets that accelerate time-to-market for differentiated humidification solutions.
Next Steps — Where to Find the Full Intelligence
PW Consulting’s full report contains the granular segment and regional breakdowns, vendor-specific scorecards, and downloadable financial models that procurement teams, corporate strategy groups, and investors will need to finalize 2026 initiatives. This release intentionally highlights the strategic insights and market trajectory without disclosing sensitive segment-level tables — to access the complete dataset, vendor benchmarking and templated playbooks, please visit PW Consulting’s report portal or contact our industry practice.
For detailed analysis of this topic, please visit the official page: Fully Closed Ventilator Breathing Circuit Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Refrigerated Food Vending Machine Market Poised to Expand at a 7.5% CAGR Through 2026–2032
By pmarketresearch, 2026-07-07
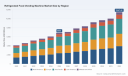
Refrigerated Food Vending Machine Market 2026: Strategic Imperatives from PW Consulting’s Latest Industry Study
PW Consulting’s new Refrigerated Food Vending Machine Market report provides a forward-looking playbook for executives, investors, product teams, and procurement leaders preparing 2026 strategies. The market is no longer a marginal adjunct to vending and foodservice—our analysis shows an established multi‑billion dollar base and sustained expansion into the next decade. The market grew from roughly USD 4.1 billion in 2020 to about USD 6.9 billion in 2025 and is forecast to exceed USD 11.4 billion by 2032, tracking at a compound annual growth rate of approximately 7.5% through the 2026–2032 forecast window. This trajectory reflects accelerating consumer demand for fresh, chilled, and convenience food solutions combined with technology-led differentiation in refrigeration, telemetry, and payment systems.
Refrigerated Food Vending Machine Market
Why this report matters for 2026 decision-making
- Investment prioritization: we translate macro growth into specific strategic options—manufacturing capacity vs. software-as-a-service, retrofit services vs. new unit deployment—to help you optimize CAPEX and OPEX in 2026.
- Regulatory risk management: with major energy and refrigerant regulation already in force in key markets, the report maps compliance timelines and retrofit windows to avoid stranded inventory and supply interruptions.
- Product and technology roadmap alignment: our analysis identifies where to accelerate development (energy efficiency, low‑GWP refrigerants, smart inventory) versus where to maintain a wait‑and‑see posture.
- Commercial go‑to‑market playbooks: practical channel and partnership recommendations tailored to operators, foodservice brands, and location partners (retail, transport, workplaces).
Market dynamics shaping 2026 strategy
Demand-side forces remain robust: consumer preference for high-quality, perishable-ready vending options, micro-market proliferation, and extended operating hours in workplaces and travel hubs are expanding addressable demand. On the supply side, vendors are integrating advanced refrigeration systems, touchscreen merchant interfaces, RFID/IoT-enabled inventory tracking, and AI-driven replenishment—creating new value capture points beyond the physical machine.
Refrigerated Food Vending Machine Market
Two regulatory currents are particularly consequential for 2026 planning. First, North American refrigerant policy has moved decisively: manufacturers can no longer introduce new vending platforms using high‑GWP HFCs beyond regulatory cutoffs, which imposes technology migration deadlines and creates a retrofit demand curve. Second, European energy labeling and minimum efficiency standards are tightening, pushing purchasers to favor energy‑optimized designs and to account for lifecycle operating costs rather than acquisition price alone. Both trends accelerate demand for low‑GWP refrigerants, inverter compressors, and advanced thermal insulation in machines.
Refrigerated Food Vending Machine Market
Raw material and component dynamics should not be underestimated. Structural materials and thermal management components—often built around durable metal frames and engineered insulation—are central to service life and maintenance cost. Procurement strategies that consider long‑lead components and supplier diversification will have a material impact on 2026 availability and margins.
Competitive landscape: what leading suppliers are doing
The competitive field is composed of global OEMs, regional specialists, and emerging smart‑vending startups. Our competitive profiles synthesize technology positioning, channel focus, and strategic intent for each major player to enable rapid vendor shortlists and partnership assessments.
- Crane Payment Innovations (formerly Crane Merchandising Systems): positions itself on advanced merchandising and touchscreen interfaces, offering integrated refrigeration platforms suited to fresh and chilled assortments—appealing to operators that prioritize a full‑service merchandising experience.
- AMS Vendors: focuses on low‑temperature combo machines and guaranteed delivery mechanisms, which suit operators wanting hybrid beverage/food offers with proven delivery reliability.
- SandenVendo America: emphasizes energy‑efficient refrigeration and glass‑front solutions, targeting commercial foodservice and locations where product visibility and energy performance are decisive purchase drivers.
- REDYREF: moving quickly on RFID and smart-fridge kiosks, with recent deployments of RFID‑enabled refrigerated vending fridges for fresh meals—an example of how inventory control and 24/7 meal access can be commercialized in enterprise venues.
- Azkoyen Vending Systems: European design strengths with temperature‑controlled snack and sandwich solutions attractive to retail partners prioritizing food safety and precise temperature profiles.
- Seaga Manufacturing, Fuji Electric, and TCN Vending: collectively represent scale and geographic breadth, offering configurable refrigerated platforms, frozen and chilled options, and regional manufacturing footprints that support rapid rollouts.
Recent industry activity underscores these shifts. RFID‑enabled smart fridges and AI‑enhanced coolers featured prominently at industry events in 2025–2026, and several vendors showcased low‑GWP refrigeration designs and connectivity suites at major trade shows—signals that product portfolios are migrating in predictable directions. For operators and investors, these developments mean that vendor selection should include a two‑year technology roadmap and a retrofit compatibility assessment.
What the PW Consulting report delivers (actionable toolkit)
Beyond high‑level narrative, the report is a hands‑on toolkit for executives who must convert industry trends into executable 2026 plans. Key deliverables include:
- End‑to‑end market sizing and scenario forecasts with demand shocks and sensitivity testing to inform budgeting and investment pacing.
- Technology and product roadmaps that link refrigerant choices, energy ratings, and controls architectures to total cost of ownership models.
- Regulatory compliance matrix and retrofit timelines for primary markets—enabling procurement to sequence orders and avoid non‑compliant batches.
- Supplier capability and risk assessments, including manufacturing lead times, component bottlenecks, and competitive differentiation.
- Go‑to‑market frameworks: channel economics, site selection heuristics, pricing models, and sample commercial contracts for operator partners.
- Deployment playbooks and KPI dashboards—covering pilot design, inventory algorithms, replenishment cadences, lifecycle maintenance schedules, and ROI calculators for varying deployment scenarios.
To preserve the integrity of competitive advantage, the report presents granular segmentation, regional splits, and operator‑level use cases behind a secure paywall—this is the proprietary intelligence that fuels targeted decision making in 2026.
High‑priority strategic recommendations for 2026
- Accelerate compliance-driven platform upgrades: prioritize retrofits and new orders that comply with the latest refrigerant and energy standards to avoid mid‑cycle obsolescence.
- Design for modularity: standardize control and refrigeration modules to support field upgrades and to shorten time‑to‑market for new SKUs or features.
- Invest in telemetry and machine learning: use real‑time inventory and performance data to reduce shrinkage, optimize route planning, and improve fill yields—improving gross margins without increasing footprint.
- Pursue partnership pilots with foodservice brands and property owners: co‑branded micro‑markets and refrigerated kiosks reduce customer acquisition cost and accelerate adoption curves in workplaces and travel hubs.
- Hedge supply chain risk: secure critical components (compressors, controls, insulation panels) through multi‑sourcing or strategic stocking to avoid 2026 lead‑time shocks.
- Embed lifecycle cost in procurement: shift evaluation criteria from unit price to multi‑year operating cost and energy impact to minimize total cost of ownership and regulatory exposure.
How to operationalize this intelligence in your 2026 planning cycle
Translate the report’s findings into your fiscal plan via a four‑step approach:
- Q1: Regulatory & procurement alignment—update supplier contracts, set compliance checkpoints, and re‑price models to include energy and retrofit cost.
- Q2: Product & pilot development—deploy modular prototypes, integrate telemetry stacks, and launch controlled field trials with high‑visibility partners.
- Q3: Commercial scale-up—leverage pilot learnings to finalize SKUs, negotiate volume discounts, and roll out to prioritized channels.
- Q4: Optimization & risk mitigation—consolidate performance data, refine replenishment algorithms, and lock supply agreements for the following year.
Each phase includes decision gates—technical compliance, pilot KPIs (uptime, fill yield, energy consumption), and financial thresholds—that the report defines and benchmarks against market expectations.
Conclusion: positioning for profitable growth in 2026
The refrigerated food vending machine market offers substantial growth, but winning in 2026 requires more than telescoping demand forecasts—success will flow to organizations that marry compliant hardware choices with software‑enabled operational excellence and disciplined procurement. PW Consulting’s report provides the dataset, playbooks, and vendor intelligence to make those tradeoffs confidently. For teams that need the detailed segmentation, regional forecasts, supplier scorecards, and interactive ROI models that underpin our recommendations, the full report and dashboards are available through the PW Consulting release page.
For detailed analysis of this topic, please visit the official page: Refrigerated Food Vending Machine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecasts IoT UTM Market to Surge at 22.15% CAGR, Reaching USD 25.5 Billion by 2032
By pmarketresearch, 2026-07-07
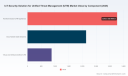
PW Consulting Strategic Brief: IoT Security Solution for Unified Threat Management (UTM) Market — A 2026 Playbook for Decision-Makers
The convergence of pervasive IoT deployments and escalating threat sophistication has pushed Unified Threat Management (UTM) for IoT from a niche network hygiene topic to a board‑level strategic imperative. Our new market study, "IoT Security Solution For Unified Threat Management (UTM) Market," synthesizes five years of historical data and a seven‑year forecast to deliver operational guidance for procurement, architecture, and risk governance teams making investment decisions in 2026.
Iot Security Solution For Unified Threat Management Utm Market
Why this report matters in 2026
-
Market momentum: The IoT UTM market has moved from early consolidation into rapid commercialization. In numeric terms, our base‑year analysis shows the market expanded from USD 4,212.45 million in 2023 to USD 6,285.20 million in 2025, and is forecast to grow to USD 25,501.94 million by 2032. The forecast period (2026–2032) implies a compound annual growth rate (CAGR) of 22.15%, underscoring both opportunity and disruption.
Iot Security Solution For Unified Threat Management Utm Market -
Strategic timing: 2026 is the inflection point for many enterprises — regulators are tightening product and data responsibilities, architectures are shifting toward cloud‑native and service models, and suppliers are layering AI and zero‑trust capabilities into core UTM offerings. Decisions made this year define security posture and procurement exposure across the next hardware and software refresh cycles.
Iot Security Solution For Unified Threat Management Utm Market -
Practical orientation: This report is designed as a practitioner's toolkit for C‑suite and security leaders — not an academic exercise. It maps market trajectories to operational choices that matter to 2026 budget cycles and 3–5 year roadmaps.
What the report delivers: operational, decision‑grade intelligence
-
Robust market sizing and trend diagnostics — an audited historical series (2020–2025) and a detailed seven‑year forecast (2026–2032) that link macro drivers to addressable spend categories.
-
Buyer personas and procurement playbooks — role‑specific checklists for CISOs, procurement directors, and MSP partners that translate risk appetite into procurement language (service levels, patch cadences, indemnities, and escrow provisions).
-
Deployment and migration frameworks — validated blueprints for integrating UTM into heterogeneous IoT estates, covering brownfield segmentation, telemetry collection, SOC ingestion, and automation paths for incident response.
-
Vendor evaluation tools — scorecards that combine technical capability, product roadmaps, delivery model maturity (hardware, virtual, cloud), and commercial flexibility—designed to be used in RFPs and due diligence.
-
Regulatory and compliance mapping — alignment matrices that translate obligations under emerging frameworks (e.g., EU Cyber Resilience Act, EU Data Act, China’s network/data rules, and U.S. Bulk Data controls) into contract clauses and operational controls.
-
Financial models and TCO scenarios — configurable templates that quantify direct costs, service fees, integration effort, and the implied value of managed/co‑managed service options over multi‑year horizons.
-
Risk scenarios and playbooks — prioritized threat scenarios for industrial, healthcare, and critical‑infrastructure IoT use cases, with actionable mitigation sequences and measurable KPIs.
Competitive landscape — who matters and why
The vendor landscape blends established network security vendors, cloud developers, and specialist appliance suppliers. Market concentration is material but not prohibitive: our CR3 sits in the high‑thirties and CR5 is slightly north of the mid‑fifties, indicating a field where a few leaders set broadly accepted technical and commercial norms, while mid‑tier and regional players maintain important niches.
-
Fortinet, Inc. (Sunnyvale, CA — https://www.fortinet.com) continues to leverage integrated NGFW/UTM platforms that emphasize IoT device visibility, segmentation, and scalable threat management for distributed estates.
-
Cisco Systems, Inc. (San Jose, CA — https://www.cisco.com) advances a blended model across Secure Firewall and Meraki lines, integrating device profiling and threat intelligence into a single operational fabric.
-
Check Point Software Technologies Ltd. (Tel Aviv — https://www.checkpoint.com) positions its NGFW and cloud products to emphasize policy enforcement and threat prevention across hybrid deployments.
-
Sophos Ltd. (Abingdon, UK — https://www.sophos.com) focuses on unified management simplicity and continuous update streams for UTM appliances and virtual platforms.
-
WatchGuard Technologies, Inc. (Seattle, WA — https://www.watchguard.com) and SonicWall Inc. (Milpitas, CA — https://www.sonicwall.com) continue to serve channel ecosystems with differentiated appliance portfolios and partner‑centric services.
-
Barracuda Networks, Inc. (Campbell, CA — https://www.barracuda.com) and Juniper Networks, Inc. (Sunnyvale, CA — https://www.juniper.net) prioritize cloud connectivity and AI‑driven management for multi‑site environments.
-
Huawei Technologies Co. Ltd. (Shenzhen — https://www.huawei.com) addresses global telco and large enterprise accounts with integrated UTM features and network stack tightness in its portfolio.
-
Palo Alto Networks, Inc. (Santa Clara, CA — https://www.paloaltonetworks.com) emphasizes device identification, Zero Trust enforcement, and high fidelity telemetry for SOC integration.
Recent vendor moves underscore the pace of innovation and go‑to‑market shifts: product refreshes that embed ZTNA and cyber warranties, new SASE/SASE‑adjacent entries for SME channels, and continuous firmware/software refreshes that bear directly on lifecycle risk. These shifts influence which vendors are suitable for greenfield, brownfield, or heavily regulated environments.
Regulatory and infrastructure dynamics that will shape 2026 choices
-
Regulation: The EU Cyber Resilience Act and the EU Data Act are moving liability and data portability obligations into product lifecycles — procurement must now evaluate supplier update commitments, vulnerability disclosure policies, and contractual liability caps.
-
Cross‑border data constraints: New rules in large markets require careful architecture decisions on telemetry storage and cross‑border transfers; procurement must bake localization and legal assessments into vendor selection.
-
Cost inputs: Rising data center and infrastructure costs are increasing the attractiveness of cloud‑first and managed consumption models for telemetry and analytics, altering comparative TCOs for on‑prem appliances versus SaaS/virtual options.
Actionable recommendations for 2026 decision cycles
-
For CISOs: Prioritize a roadmap that converts asset‑rich IoT environments into enforceable security domains. Insist on vendor commitments for secure-by‑design patch cadences, SBOM availability, and integration with SIEM/SOAR platforms. Treat UTM selection as a control platform, not just a perimeter appliance.
-
For Procurement: Move beyond price and horsepower. Use the report’s vendor scorecards to evaluate supply‑chain resilience, indemnity language aligned to new regulations, and co‑managed service options that reduce in‑house lifecycle burden.
-
For MSPs/MSSPs: Design co‑managed bundles that combine device discovery, segmentation policy templates, and continuous monitoring, creating predictable revenue streams as enterprises outsource operational complexity.
-
For Technology Leaders: Adopt a hybrid architecture play that allows selective offload to cloud analytics while keeping critical enforcement points on premises. Implement identity‑first segmentation and automated micro‑containment for high‑risk device classes.
Risks and scenarios executives should model now
-
Regulatory acceleration: Faster or broader adoption of product‑liability regimes could materially shift vendor economics — build clauses that require regular evidence of OTA update practices and vulnerability management.
-
Lock‑in and migration friction: Avoid hard dependency on single‑vendor telemetry formats; insist on exportable telemetry, documented APIs, and migration playbooks.
-
Supply and cost shocks: Infrastructure and raw material cost escalation can change the balance of appliance vs. service economics; stress‑test TCO models under higher data center costs.
-
Threat evolution: AI‑augmented offensive capabilities and supply‑chain attacks mean that detection and response timelines must compress — evaluate vendors on detection speed and automation depth, not just prevention metrics.
How to use this study as a decisioning instrument
The study is intentionally tactical: each chapter connects market dynamics to executable choices. Use the market forecast to set portfolio allocation envelopes; use the regulatory mapping to adjust contract language; use the vendor scorecards to narrow a long list to a defensible short list; and use the deployment blueprints to accelerate secure rollout with measurable KPIs.
Our "trailer" approach here highlights the strategic contours and operational takeaways that will matter in 2026. For procurement‑grade subsegment economics, country‑level forecasts, granular component breakouts, and the full vendor scorecards (including third‑party validation and channel positioning), refer to the full report available from PW Consulting. The full dataset and appendices contain the granular inputs you will need to finalize RFPs, capital plans, and compliance attestations for the coming planning cycles.
Final note
Enterprises that treat IoT UTM as an architectural program rather than a point purchase will capture disproportionate risk reduction and operational efficiencies across their IoT lifecycles. With the market expanding rapidly and regulation increasing supplier accountability, 2026 is the year to convert market intelligence into procurement discipline, architecture clarity, and measurable security outcomes. PW Consulting’s full report equips teams to do precisely that.
For detailed analysis of this topic, please visit the official page: Iot Security Solution For Unified Threat Management Utm Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: High-Speed Specialty Cable Market to Surge from USD 5,250 Million in 2025 to USD 9,726.51 Million by 2032 at a 9.21% CAGR
By pmarketresearch, 2026-07-07
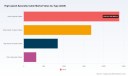
High Speed Specialty Cable Market: Strategic Imperatives for 2026 Decision-Makers
PW Consulting’s newest market study on the High Speed Specialty Cable Market provides the operational intelligence leaders need to convert market momentum into durable advantage in 2026. Built on a transparent market model with historical coverage from 2020–2025 and a forecast window through 2032, the report calibrates a growth baseline at a 9.21% compound annual growth rate (CAGR). On this trajectory the global market—measured in USD Million—expanded from the early‑decade base and reached a 2025 valuation we use as the planning pivot; by 2032 our model projects it approaching the USD Million range that materially reshapes supplier economics and product roadmaps.
High Speed Specialty Cable Market
Why this matters for 2026 planning
- Acceleration of bandwidth-hungry workloads (cloud-native services, AI training and inference, 5G‑era edge densification) is shifting the performance and reliability bar for cable assemblies and interconnects.
- Material and geopolitical volatility is introducing meaningful supply‑chain and cost uncertainty, forcing procurement and product leaders to commit to hedging, redesign, or nearshoring strategies sooner than planned.
- Technology transition windows (optical vs. copper, next‑generation connector standards, high-density micro‑distribution) create asymmetric opportunities for firms that align R&D, manufacturing, and go‑to‑market execution during 2026.
Drivers reshaping demand architecture
The market is being driven by the convergence of three structural forces. First, hyperscale and cloud operators continue to densify racks and interconnects, increasing demand for low-latency, high-throughput cable assemblies optimized for thermal and space constraints. Second, telecom network upgrades and the rollout of multi-layer 5G and private wireless networks are expanding high-frequency cable requirements across access and transport layers. Third, industrial and aerospace applications are demanding higher reliability, smaller form factors, and certification-driven designs for harsh environments.
High Speed Specialty Cable Market
Technology trends that deserve special attention in 2026 planning include the ongoing displacement of some copper functions by active optical solutions in high-throughput environments, continued investments in connector and board‑level signaling (e.g., PCIe generation impacts), and material innovations that balance signal integrity with manufacturability. Product managers should treat these trends as trigger points for portfolio pruning, targeted NPI, and customer co-engineering initiatives.
High Speed Specialty Cable Market
Supply-side stress: costs, materials, and trade policy
Raw material dynamics are a central near-term risk. Copper markets have been unusually volatile: COMEX reference points trended in the low‑single‑digit USD/lb range in early 2026 even as other benchmarks recorded intra‑year spikes. Producer price indices for copper wire and cable have risen sharply year‑over‑year, and specialty inputs such as copper foil and copper-clad laminates experienced double‑digit percentage increases during 2025—raising per‑unit input costs and compressing margin windows for commodity-exposed product lines.
Trade policy and export controls further complicate supplier footprints. Recent tariff measures on semi‑finished and copper‑intensive derivatives in major markets have altered landed-cost math and created incentives for regionalization or tariff engineering. At the same time, export licensing shifts for critical upstream materials—such as rare earths and related components—have introduced second‑order constraints in magnet and connector supply chains. The combined effect is a higher premium on supply‑chain agility, contract flexibility, and multi‑sourcing strategies in 2026 procurement cycles.
Competitive landscape: concentration and who to watch
The High Speed Specialty Cable sector demonstrates moderate concentration: our market concentration indices indicate the top three and top five established players account for a meaningful share of revenue—enough to shape pricing and standards adoption but not to preclude disruptive entrants. That balance creates both predictable competitive pressures and windows for differentiated execution by mid‑tier specialists.
- Amphenol Corporation (Wallingford, CT, USA) – A multi‑domain interconnect and cable player with visible traction in high‑throughput datacom and PCIe‑aligned solutions. Recent corporate reporting highlighted robust organic expansion in IT/datacom, underscoring the firm’s ability to translate specification leadership into commercial growth.
- Prysmian Group (Milan, Italy) – A globally integrated cable manufacturer with depth in fiber and large‑scale network cabling. Its breadth of manufacturing footprint and project execution capabilities makes it a natural partner for infrastructure plays and utility‑scale rollouts.
- Nexans (Paris, France) – Specialist in high‑performance systems for energy and communications; their systems approach to cabling and service offerings positions them for bundled infrastructure deals.
- Sumitomo Electric, LS Cable & System, Furukawa Electric – Asian manufacturers with strengths in advanced fiber, high-frequency cable technology, and regional OEM relationships critical to high‑density data center builds and telecom refresh programs.
- Proterial Cable America, Southwire, Specialty Cable Corporation, Samtec – North American producers and specialists who are differentiating through product innovation (e.g., Category 6A, micro‑distribution fiber), precision manufacturing investments, and service responsiveness—attributes that matter under tariff and logistics pressure.
Recent tactical movements—product launches targeted at high‑density micro‑distribution and Category 6A solutions, capacity expansions for precision wire, and outsized organic growth among certain integrators—point to a market where execution speed and product fit will determine winners in 2026.
Strategic playbook for 2026
Leaders should translate market intelligence into a short list of no‑regret moves. Based on our modeling and scenario work, PW Consulting recommends the following prioritized actions for companies engaged in or adjacent to the high speed specialty cable value chain:
- C-suite / Strategy: Use a 9.21% CAGR baseline while stress‑testing upside and supply‑shock scenarios. Prioritize capital allocation toward capacity that supports optical transitions and high‑value assemblies rather than commodity copper runs.
- Procurement: Implement layered hedging of critical inputs, broaden qualified‑supplier lists across jurisdictions, and build tariff‑aware sourcing strategies (including tariff engineering and nearshore alternatives) into standard RFQs.
- Product & R&D: Accelerate optical and active cable platforms for hyperscale customers; reduce cost‑to‑serve for legacy copper products via design for manufacturability and alternate materials where performance allows.
- Commercial & Operations: Rework lead‑time commitments in SLAs, incorporate escalation clauses tied to input indices, and co‑develop rapid deployment kits with key hyperscalers and carriers to secure long‑lead volume commitments.
- Investors & M&A teams: Target vertical adjacencies that shorten go‑to‑market cycles (e.g., connector houses, optical transceiver specialists) and evaluate bolt‑on acquisitions that provide regional manufacturing or material control to mitigate tariff exposure.
What the PW Consulting report delivers to decision-makers
This release is a strategic preview; the full PW Consulting report is the operational playbook. It includes:
- A robust demand and revenue model with historical (2020–2025) calibration and annual forecasts through 2032, built to support scenario and sensitivity analysis against input cost shocks and adoption curves.
- Segment and application breakdowns, with quantified demand drivers and price‑elasticity assumptions (note: detailed subsegment tables and company‑level revenue splits are available in the full report and supplemental datasets).
- Vendor scorecards and competitive positioning maps that synthesize product portfolios, vertical exposure, manufacturing footprints, and recent strategic moves.
- Supply‑chain stress tests and tariff/regulatory impact assessments that translate macro policy changes into landed‑cost implications and margin scenarios.
- Practical go‑to‑market toolkits for product launches, procurement negotiation templates, and an acquisition target shortlist calibrated for 2026 value creation.
Actionable next step
For 2026 decision cycles, the differentiator will be speed of alignment between strategic intent and operational execution. PW Consulting’s High Speed Specialty Cable Market report equips leaders with the models, diagnostics, and playbooks required to make those tradeoffs under uncertainty. This briefing intentionally omits our full subsegment tables and the granular vendor revenue breakout; those analytics are available within the full report and interactive datasets on our publication page for clients and subscribers.
If your 2026 planning requires scenario-ready financial models, supplier maps, or a tailored vendor due-diligence package, PW Consulting can deploy a short engagement (4–6 weeks) to convert the public analysis into bespoke action plans aligned to your portfolio and geography.
For detailed analysis of this topic, please visit the official page: High Speed Specialty Cable Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Household Solid State Relay Market to Grow at a 7.66% CAGR, Report Says
By pmarketresearch, 2026-07-07
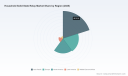
Household Solid State Relay Market — Strategic Outlook 2026: A PW Consulting Briefing
As household electrification and smart-home integration accelerate, solid state relays (SSRs) are moving from niche components into the mainstream of residential power control. PW Consulting’s latest market study — anchored on a 2025 base year and projecting through 2032 — synthesizes technology evolution, supply-chain risk, and commercial positioning into a single, actionable view intended to inform executive decisions in 2026. The market expands from roughly USD 305.12 Million in 2020 to USD 430.32 Million in 2025 and, under our base forecast, reaches approximately USD 721.25 Million by 2032 (USD Million; CAGR 7.66% over the forecast period). This trajectory creates commercially material opportunities — and real operational risks — for OEMs, component suppliers, system integrators, and investors.
Household Solid State Relay Market
Why this matters for 2026 decision-making
-
Demand inflection: Energy-efficiency regulations, quieter consumer preferences, and the integration of solid state switching into smart-home energy management systems are driving structural demand. The compound growth rate we model (7.66% CAGR) reflects both replacement cycles in household appliances and step-change adoption in lighting, HVAC and distributed energy systems.
Household Solid State Relay Market -
Technology differentiation: Innovations in thermal management, zero-cross switching, PhotoMOS and MOSFET-based SSRs are expanding SSR applicability across resistive and inductive household loads. Product lifecycles are shortening as suppliers roll out higher-performance, lower-noise units tuned for residential environments.
Household Solid State Relay Market -
Supply-chain geopolitics: Critical upstream inputs for SSRs — notably materials used in optocouplers and power semiconductors — are geographically concentrated. Recent policy moves and tariff shifts materially increase supplier and sourcing risk for 2026 procurement and R&D plans.
Key industry dynamics to watch in 2026
-
Materials concentration: Low-purity primary gallium production remains highly concentrated, creating a single-point supply vulnerability for components used in optocouplers and power devices.
-
Trade and tariff environment: Escalating tariffs and export controls on semiconductor inputs increase landed cost volatility and complicate cross-border manufacturing strategies.
-
Regulatory momentum: National security-driven proclamations and export control mechanisms are reshaping the calculus for sourcing and localization, especially for firms dependent on advanced semiconductors.
What PW Consulting’s report delivers — practical, board-ready tools
Beyond headline forecasts, our report is expressly designed as an operational playbook for 2026. It includes:
-
Scenario-driven demand models: Three demand pathways (constrained supply, base, and accelerated adoption) with sensitivity analyses that let you stress-test revenue, margin and inventory plans against plausible 2026 shocks.
-
Supplier landscape and scorecards: Qualitative and quantitative assessments of the competitive field, including technology fit, manufacturing footprint, quality certifications, and time-to-volume risk — intended to support sourcing decisions and dual-sourcing roadmaps.
-
Technology deep-dive: Comparative maturity and roadmaps for PhotoMOS, MOSFET-based SSRs, and optocoupler-integrated solutions, with practical implications for thermal design, EMI/EMC, and lifecycle cost.
-
Regulatory & raw-material risk matrix: Regionally calibrated risk heatmaps and mitigations (inventory buffers, contract clauses, MIN/MAX holdings, alternative component pathways) that translate policy headlines into procurement actions.
-
Commercial playbook: Go-to-market recommendations for OEMs and component suppliers — channel strategies, value-based pricing frameworks, and partner ecosystems for smart-home and builder-spec segments.
-
M&A and partnership screening tools: A shortlist methodology, valuation heuristics and integration checklists tailored to the SSR value chain — appropriate for private equity and corporate strategy teams evaluating consolidation or capability acquisition.
Competitive landscape — leader behaviors and strategic positioning
The household SSR market combines long-established automation players, electronic-component specialists, and focused relay manufacturers. Our competitive analysis highlights strategic differentiators and near-term moves for the companies shaping 2026 outcomes.
-
Omron Corporation (Kyoto, Japan) — Omron’s breadth across PCB-mount and panel-mount SSRs, and its emphasis on appliance temperature control and lighting, position it as a key partner for appliance OEMs seeking proven reliability and supply continuity. Recent showcases of AC/DC high-power variants point to a push into higher-load household and renewable integration use cases.
-
Panasonic Corporation (Osaka, Japan) — With PhotoMOS and low-power SSRs optimized for silent operation, Panasonic remains a preferred supplier for consumer-electronics and compact appliance applications where acoustic and reliability metrics matter.
-
Carlo Gavazzi Holding AG (Steinhausen, Switzerland) — As a specialist in DIN-rail and panel-mount units, Carlo Gavazzi targets building automation and HVAC integrators. Its thermal integration and heatsink expertise suit retrofits and new-build control panels where installation and heat-dissipation characteristics matter.
-
Sensata Technologies (Crydom) (Attleboro, USA) — Crydom’s industrial-grade platforms, enhanced thermal performance and isolation improvements make it an attractive candidate where household applications demand higher reliability thresholds or integration with distributed-energy systems.
-
Schneider Electric, Siemens, ABB — These automation and power-distribution incumbents integrate SSRs into broader home and building energy management stacks. Their strength lies in systems-level integration, channel reach, and services — important considerations for strategic partnerships and OEM bundling.
-
TE Connectivity, Vishay, Littelfuse, Celduc, Fujitsu — Component and specialist relay suppliers bring high-cycle endurance, vibration resistance and compact form factors. They are critical from a supply-chain perspective — offering both standard catalog solutions and custom-engineered items for differentiated appliance designs.
Collectively, the market shows moderate concentration: the three-largest suppliers capture a meaningful share while the top five extend that reach further. This dynamic (moderate CR3/CR5 levels) creates windows for both consolidation and niche specialization: larger players pursue system integration and scale; specialists compete on thermal performance, acoustic characteristics, and form-factor innovation.
Recent developments shaping 2026 choices
-
Product innovation: Suppliers continue to refine thermal performance and electrical isolation, with several fourth-generation launches and showcase events in 2025–2026 highlighting incremental but cumulatively important reliability gains.
-
Market engagement: Trade shows and sector exhibitions in early 2026 have already served as staging grounds for new relay architectures aimed at household and semiconductor-enabled implementations.
-
Policy headlines: Export controls and tariff rebalancing announced across 2024–2026 increase urgency for procurement strategies that reduce single-source exposure and prioritize alternate-material pathways.
Strategic playbook — actionable recommendations for 2026
-
Procurement: Implement multi-tiered sourcing with conditional volume commitments and material-pass-through clauses. Prioritize suppliers with diversified footprints and transparent supply chains.
-
R&D and product: Accelerate validation of lower-dependency designs (e.g., alternate optocoupler architectures) and modular SSR platforms that allow last-mile semiconductor substitution without re-certification.
-
Commercial: Distinguish offerings by system-level benefits — energy savings, acoustic performance, and lifecycle reliability — instead of competing purely on unit cost.
-
M&A and partnership: Target bolt-on acquisitions that provide thermal management IP or regional manufacturing presence to mitigate policy and material risk.
-
Regulatory engagement: Develop playbooks for export-control compliance and engage with industry consortia to anticipate changes in critical-material governance.
How executives should use this report in 2026
-
Board presentations: Use scenario outputs to quantify downside exposure and to set capital allocation guardrails for product and manufacturing investments.
-
Procurement negotiations: Leverage supplier scorecards and risk heatmaps to renegotiate lead-times, penalty clauses and safety-stock parameters.
-
Product roadmap planning: Align SSR component strategy with broader electrification initiatives and test alternate technology stacks early in the design cycle to reduce rework cost.
-
Investor diligence: Use our M&A screening and valuation heuristics to assess acquisition targets and perform integration planning with realistic cost and time assumptions.
Final word: why the full report matters
Our briefing provides the high-level, decision-focused perspective that senior teams need. The full PW Consulting Household Solid State Relay Market Report contains the granular intelligence that underpins these recommendations — including segmented demand models, supplier scorecards, and downloadable tools for scenario stress-testing. To access the complete data tables, segmentation breakdowns, and our proprietary supplier rankings — essential inputs for executing the 2026 strategies described here — visit the report landing page.
For detailed analysis of this topic, please visit the official page: Household Solid State Relay Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com