

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Advanced Insulation Materials Market Poised for a 9.24% CAGR, Fueling Energy-Efficiency Gains

Advanced Insulation Materials 2026: A Strategic Brief for Decision-Makers
PW Consulting’s Advanced Insulation Material Market Research (base year 2025) synthesizes the near‑term imperatives that will shape capital allocation, product strategy, and supply‑chain design across the insulation value chain in 2026. This briefing pulls the strategic threads from our full study—market sizing, competitive dynamics, regulatory inflection points, and practical playbooks—so executives can prioritize decisions this year. Consider it a trailer: we reveal the structural trends and action levers but reserve the full, transaction‑grade data and segment cross‑tables for the complete report.
Advanced Insulation Material Market Research
Market snapshot: growth with opportunity and complexity
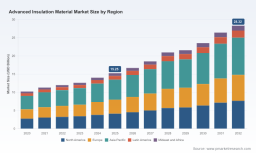
The advanced insulation market has moved from a niche performance play into a mainstream industrial imperative. After steady expansion through the early 2020s, total industry revenues reached approximately USD 15.3 Billion in 2025 and are projected to continue on a multi‑year expansion path. Our forecast shows the market growing at a compound annual growth rate (CAGR) of approximately 9.24% across the 2026–2032 horizon, reaching the high‑twenties (USD Billion) by 2032. This pace reflects simultaneous demand drivers: building energy efficiency mandates, electrification of transport and energy networks, and thermal management needs in industrial and cryogenic applications.
Advanced Insulation Material Market Research
Market concentration remains meaningful but not monopolistic: the top three players together control roughly one third of the market, and the top five account for just under half. That structure creates both scale advantages for incumbent integrated producers and opportunity windows for specialized innovators and regional challengers.
Advanced Insulation Material Market Research
Why this matters for 2026 corporate decisions
- CapEx prioritization: With regulation and product innovation shifting product mixes toward higher‑performance solutions (aerogels, vacuum panels, advanced PCM systems), boards must decide whether to invest in internal capacity expansions, technology licensing, or strategic partnerships. Our analysis quantifies payoff curves for each route under multiple oil/raw‑material and tariff scenarios.
- Supply‑chain resilience: Raw‑material volatility and trade measures mean procurement strategies established in 2020–2021 are insufficient. The report models inventory and sourcing hedges that materially reduce marginal cost exposure while balancing working capital.
- Product roadmap and regulatory compliance: New regulatory thresholds and chemical restrictions are changing acceptable formulations and thermal performance baselines. Companies that accelerate reformulation and certification for public‑sector procurement will capture high‑margin, low‑volume contracts.
- M&A and ecosystem plays: The combination of moderate concentration and technology fragmentation makes 2026 a favorable year for bolt‑on acquisitions and licensing of highly differentiated materials (e.g., aerogel composites, cryogenic blankets) to enter adjacent markets.
Context drivers—what is forcing the change now
- Regulatory tightening: Public procurement and construction standards have raised the bar for thermal performance in 2025–2026, with binding limits that favor materials delivering lower thermal conductivity. At the same time, chemical regulations are phasing out high‑GWP agents in key jurisdictions, forcing rapid reformulation.
- Raw‑material and logistics volatility: Feedstock dynamics have introduced tangible cost shocks and uncertainty. Procurement teams are evaluating regional hedging, long‑term offtakes, and supplier diversification as core mitigation strategies. Concurrently, maritime and logistics cost dynamics have added effective transport surcharges on transoceanic flows that tilt competitiveness for production footprints.
- Trade policy: New countervailing duties and tariffs on certain imported insulation products have rapidly reshaped price competitiveness and created near‑term windows for local producers to capture share.
- Technological differentiation: High‑performance products—particularly aerogels and advanced vacuum systems—are transitioning from specialty use cases into commercial growth segments where performance‑to‑cost ratios are improving thanks to production innovations and scale.
Competitive landscape—how incumbents and specialists are positioning
Our competitive mapping segments players along two dimensions: breadth of product portfolio (multinational chemical majors and building‑materials groups) and technology depth (specialists in aerogels, cryogenics, or tailored polymer systems). This yields three strategic archetypes with different operational implications:
- Integrated chemical champions: Firms with diversified upstream chemical and polymer platforms are using their feedstock access and global channels to defend volume markets and invest in low‑GWP reformulations. Examples include major chemicals groups that continue to expand insulation foam capacity and leverage scale to amortize R&D.
- Building‑materials conglomerates: Large building‑product manufacturers combine thermal and acoustic performance in packaged systems and pursue certification credentials and sustainability badges to win large institutional and public contracts.
- High‑performance specialists: Focused technology companies commercialize premium materials—e.g., aerogel blankets and cryogenic super‑insulation—that command higher margins in energy, subsea, aerospace, and EV battery thermal management.
Across these archetypes, our analysis profiles a representative set of market participants—companies with global scale and those driving niche innovations. Their recent moves are instructive:
- Capacity investments by multinational producers reflect a defensive strategy to secure feedstock integration and maintain supply for core foam products.
- Specialist product launches targeting electric‑vehicle thermal management and subsea energy applications demonstrate how new end‑use demand is opening adjacent revenue pools.
- Third‑party certifications and sustainability credentials are increasingly table stakes for winning institutional construction projects; firms achieving higher sustainability ratings capture premium tenders.
Operational playbook for 2026 (executive checklist)
- Immediate (0–6 months): Run rapid scenario tests on your current product mix against the updated regulatory matrix and tariff landscape; prioritize reformulation of any lines exposed to high‑GWP agent bans. Commence supplier stress tests for critical polyol and blowing‑agent supply.
- Near term (6–18 months): Lock strategic offtake agreements or explore co‑investment with regional manufacturers to bypass punitive import tariffs and elevated trans‑Pacific logistics surcharges. Accelerate certification programs for your highest‑margin products for public‑sector procurement.
- Medium term (18–36 months): Revisit plant footprint decisions—evaluate nearshoring of intermediate inputs, capacity expansions in lower‑cost jurisdictions with favorable trade access, and selective M&A of specialized aerogel or PCM technology firms to secure differentiation.
Risk matrix and sensitivity highlights
The full report includes probabilistic scenario outputs; highlight risks that should be monitored closely in 2026:
- Material price shock: A sustained increase in polyol/monomer feedstocks will compress margins on commodity foams and accelerate demand for higher‑value, lower‑thickness solutions.
- Regulatory acceleration: Faster‑than‑expected rollouts of limits on thermal conductivity or phase‑out of specific blowing agents will re‑rank supplier competitiveness.
- Trade disruptions: Tariff and surcharge regimes can create immediate windows of winners and losers in regional procurement cycles; nimble production redeployment will be rewarded.
What the full PW Consulting report delivers (practical inclusions)
- Dynamic market model with annualized revenue forecasts through 2032 and configurable drivers for price, volume, and substitution effects.
- Supplier scorecards, technology maturity matrices, and unit‑economics benchmarks to support sourcing and product decisions.
- Regulatory impact mapping across major markets and a compliance timeline for formulation and performance standards.
- Three invest/divest/M&A scenarios with recommended deal structures and integration checklists.
- Actionable dashboards and Excel workbooks that buyers, product managers, and corporate strategy teams can adopt to run bespoke sensitivity runs.
These deliverables are designed to move teams from strategic intent to operational execution quickly: the models are transaction‑grade and ready for board or investor review, but—as a conscious editorial choice—we withhold the full segment‑level and region‑application matrices in this public briefing to preserve the competitive value of the datasets contained in the full report.
How leaders are already responding
Market leaders and technology specialists are deploying three common tactics: (1) securing feedstock and logistics resilience via long‑term contracts and regional production pivots; (2) accelerating product certification and sustainability credentials to capture institutional demand; and (3) selectively acquiring or partnering with niche technology providers to shorten time‑to‑market for premium thermal solutions. These tactics are evident across recent product launches, capacity announcements, and certification milestones.
Final guidance for 2026 strategy
2026 will reward firms that treat advanced insulation as a strategic category rather than a cost line item. Boards should expect this category to drive differentiated returns through product premiumization, tighter regulatory‑driven demand, and new industrial use cases (e.g., battery thermal management, cryogenics). The companies best positioned will be those that combine flexible manufacturing footprints, prioritized R&D spend on low‑GWP and low‑conductivity solutions, and an M&A playbook that brings niche performance technologies into scalable channels.
PW Consulting’s Advanced Insulation Material Market Research provides the analytical foundation and execution templates to convert these strategic imperatives into measurable value. To access the full dataset, interactive models, and supplier-by-supplier analysis, visit PW Consulting’s report page for the comprehensive report and advisory packages.
For detailed analysis of this topic, please visit the official page: Advanced Insulation Material Market Research
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com