

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Household Solid State Relay Market to Grow at a 7.66% CAGR, Report Says

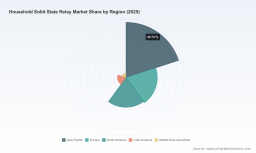
Household Solid State Relay Market — Strategic Outlook 2026: A PW Consulting Briefing
As household electrification and smart-home integration accelerate, solid state relays (SSRs) are moving from niche components into the mainstream of residential power control. PW Consulting’s latest market study — anchored on a 2025 base year and projecting through 2032 — synthesizes technology evolution, supply-chain risk, and commercial positioning into a single, actionable view intended to inform executive decisions in 2026. The market expands from roughly USD 305.12 Million in 2020 to USD 430.32 Million in 2025 and, under our base forecast, reaches approximately USD 721.25 Million by 2032 (USD Million; CAGR 7.66% over the forecast period). This trajectory creates commercially material opportunities — and real operational risks — for OEMs, component suppliers, system integrators, and investors.
Household Solid State Relay Market
Why this matters for 2026 decision-making
-
Demand inflection: Energy-efficiency regulations, quieter consumer preferences, and the integration of solid state switching into smart-home energy management systems are driving structural demand. The compound growth rate we model (7.66% CAGR) reflects both replacement cycles in household appliances and step-change adoption in lighting, HVAC and distributed energy systems.
Household Solid State Relay Market -
Technology differentiation: Innovations in thermal management, zero-cross switching, PhotoMOS and MOSFET-based SSRs are expanding SSR applicability across resistive and inductive household loads. Product lifecycles are shortening as suppliers roll out higher-performance, lower-noise units tuned for residential environments.
Household Solid State Relay Market -
Supply-chain geopolitics: Critical upstream inputs for SSRs — notably materials used in optocouplers and power semiconductors — are geographically concentrated. Recent policy moves and tariff shifts materially increase supplier and sourcing risk for 2026 procurement and R&D plans.
Key industry dynamics to watch in 2026
-
Materials concentration: Low-purity primary gallium production remains highly concentrated, creating a single-point supply vulnerability for components used in optocouplers and power devices.
-
Trade and tariff environment: Escalating tariffs and export controls on semiconductor inputs increase landed cost volatility and complicate cross-border manufacturing strategies.
-
Regulatory momentum: National security-driven proclamations and export control mechanisms are reshaping the calculus for sourcing and localization, especially for firms dependent on advanced semiconductors.
What PW Consulting’s report delivers — practical, board-ready tools
Beyond headline forecasts, our report is expressly designed as an operational playbook for 2026. It includes:
-
Scenario-driven demand models: Three demand pathways (constrained supply, base, and accelerated adoption) with sensitivity analyses that let you stress-test revenue, margin and inventory plans against plausible 2026 shocks.
-
Supplier landscape and scorecards: Qualitative and quantitative assessments of the competitive field, including technology fit, manufacturing footprint, quality certifications, and time-to-volume risk — intended to support sourcing decisions and dual-sourcing roadmaps.
-
Technology deep-dive: Comparative maturity and roadmaps for PhotoMOS, MOSFET-based SSRs, and optocoupler-integrated solutions, with practical implications for thermal design, EMI/EMC, and lifecycle cost.
-
Regulatory & raw-material risk matrix: Regionally calibrated risk heatmaps and mitigations (inventory buffers, contract clauses, MIN/MAX holdings, alternative component pathways) that translate policy headlines into procurement actions.
-
Commercial playbook: Go-to-market recommendations for OEMs and component suppliers — channel strategies, value-based pricing frameworks, and partner ecosystems for smart-home and builder-spec segments.
-
M&A and partnership screening tools: A shortlist methodology, valuation heuristics and integration checklists tailored to the SSR value chain — appropriate for private equity and corporate strategy teams evaluating consolidation or capability acquisition.
Competitive landscape — leader behaviors and strategic positioning
The household SSR market combines long-established automation players, electronic-component specialists, and focused relay manufacturers. Our competitive analysis highlights strategic differentiators and near-term moves for the companies shaping 2026 outcomes.
-
Omron Corporation (Kyoto, Japan) — Omron’s breadth across PCB-mount and panel-mount SSRs, and its emphasis on appliance temperature control and lighting, position it as a key partner for appliance OEMs seeking proven reliability and supply continuity. Recent showcases of AC/DC high-power variants point to a push into higher-load household and renewable integration use cases.
-
Panasonic Corporation (Osaka, Japan) — With PhotoMOS and low-power SSRs optimized for silent operation, Panasonic remains a preferred supplier for consumer-electronics and compact appliance applications where acoustic and reliability metrics matter.
-
Carlo Gavazzi Holding AG (Steinhausen, Switzerland) — As a specialist in DIN-rail and panel-mount units, Carlo Gavazzi targets building automation and HVAC integrators. Its thermal integration and heatsink expertise suit retrofits and new-build control panels where installation and heat-dissipation characteristics matter.
-
Sensata Technologies (Crydom) (Attleboro, USA) — Crydom’s industrial-grade platforms, enhanced thermal performance and isolation improvements make it an attractive candidate where household applications demand higher reliability thresholds or integration with distributed-energy systems.
-
Schneider Electric, Siemens, ABB — These automation and power-distribution incumbents integrate SSRs into broader home and building energy management stacks. Their strength lies in systems-level integration, channel reach, and services — important considerations for strategic partnerships and OEM bundling.
-
TE Connectivity, Vishay, Littelfuse, Celduc, Fujitsu — Component and specialist relay suppliers bring high-cycle endurance, vibration resistance and compact form factors. They are critical from a supply-chain perspective — offering both standard catalog solutions and custom-engineered items for differentiated appliance designs.
Collectively, the market shows moderate concentration: the three-largest suppliers capture a meaningful share while the top five extend that reach further. This dynamic (moderate CR3/CR5 levels) creates windows for both consolidation and niche specialization: larger players pursue system integration and scale; specialists compete on thermal performance, acoustic characteristics, and form-factor innovation.
Recent developments shaping 2026 choices
-
Product innovation: Suppliers continue to refine thermal performance and electrical isolation, with several fourth-generation launches and showcase events in 2025–2026 highlighting incremental but cumulatively important reliability gains.
-
Market engagement: Trade shows and sector exhibitions in early 2026 have already served as staging grounds for new relay architectures aimed at household and semiconductor-enabled implementations.
-
Policy headlines: Export controls and tariff rebalancing announced across 2024–2026 increase urgency for procurement strategies that reduce single-source exposure and prioritize alternate-material pathways.
Strategic playbook — actionable recommendations for 2026
-
Procurement: Implement multi-tiered sourcing with conditional volume commitments and material-pass-through clauses. Prioritize suppliers with diversified footprints and transparent supply chains.
-
R&D and product: Accelerate validation of lower-dependency designs (e.g., alternate optocoupler architectures) and modular SSR platforms that allow last-mile semiconductor substitution without re-certification.
-
Commercial: Distinguish offerings by system-level benefits — energy savings, acoustic performance, and lifecycle reliability — instead of competing purely on unit cost.
-
M&A and partnership: Target bolt-on acquisitions that provide thermal management IP or regional manufacturing presence to mitigate policy and material risk.
-
Regulatory engagement: Develop playbooks for export-control compliance and engage with industry consortia to anticipate changes in critical-material governance.
How executives should use this report in 2026
-
Board presentations: Use scenario outputs to quantify downside exposure and to set capital allocation guardrails for product and manufacturing investments.
-
Procurement negotiations: Leverage supplier scorecards and risk heatmaps to renegotiate lead-times, penalty clauses and safety-stock parameters.
-
Product roadmap planning: Align SSR component strategy with broader electrification initiatives and test alternate technology stacks early in the design cycle to reduce rework cost.
-
Investor diligence: Use our M&A screening and valuation heuristics to assess acquisition targets and perform integration planning with realistic cost and time assumptions.
Final word: why the full report matters
Our briefing provides the high-level, decision-focused perspective that senior teams need. The full PW Consulting Household Solid State Relay Market Report contains the granular intelligence that underpins these recommendations — including segmented demand models, supplier scorecards, and downloadable tools for scenario stress-testing. To access the complete data tables, segmentation breakdowns, and our proprietary supplier rankings — essential inputs for executing the 2026 strategies described here — visit the report landing page.
For detailed analysis of this topic, please visit the official page: Household Solid State Relay Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com