

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
PW Consulting: Blackstrap Molasses Market to Reach USD 18,005.6 Million by 2032, Expanding at a 4.2% CAGR (2026–2032)
By pmarketresearch, 2026-07-07
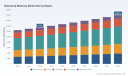
Blackstrap Molasses Market — Strategic Imperatives for 2026: A PW Consulting Report Preview
PW Consulting’s new market intelligence brief on the global Blackstrap Molasses market delivers a decision-grade synthesis for corporate strategy, supply chain planning, and portfolio optimization as firms set priorities for 2026. Anchored in a comprehensive historical review (2020–2025) and an actionable forecast window (2026–2032), the analysis combines hard market-sizing, competitive mapping, and pragmatic playbooks that management teams can deploy immediately.
Blackstrap Molasses Market
Snapshot: Where the market stands
The blackstrap molasses market has demonstrated steady expansion through the mid-2020s. PW’s topline estimate places global market revenue at approximately USD 13,500 Million in the base year (2025), following a clear upward trajectory from prior years. We project the market to reach roughly USD 14,067 Million in 2026 and to grow to about USD 18,006 Million by 2032 — representing a compounded annual growth rate (CAGR) of 4.2% over the 2026–2032 forecast window. These macro dynamics reflect structurally persistent end-market demand across animal nutrition, food formulation, and industrial applications, moderated by commodity-price cycles and policy shifts.
Blackstrap Molasses Market
Why this preview matters for 2026 corporate decision-making
-
Portfolio Prioritization — With modest, predictable growth, companies must choose where to allocate capital between volume-driven feed channels, higher-margin food & specialty segments, and emerging industrial uses such as bioethanol feedstock and sustainable formulations.
Blackstrap Molasses Market -
Supply Chain Resilience — Raw material volatility and logistical constraints mean procurement strategies established in 2026 will materially affect cost structures through the next five years.
-
Regulatory Hedging — Evolving guidance on added sugars and renewable fuel mandates will reshape product positioning and R&D investment priorities.
Key market dynamics shaping 2026
-
Demand diversification: Animal feed continues to be a core volume anchor, while food & beverage formulators and industrial customers are increasingly seeking nutrient-rich, verified-origin molasses to meet clean-label and sustainability commitments.
-
Policy and sustainability tailwinds: U.S. and international regulatory developments are nudging formulators toward natural sweeteners and incentivizing renewable feedstocks for fuels — both add strategic optionality for molasses producers.
-
Price environment: Commodity-price signals matter. In mid-2025 U.S. molasses prices held firm in the high two-hundreds USD per metric ton range, while global cane-molasses export averages in recent reporting hovered near the low two-hundreds USD per ton. Such ranges create margins pressure in low-value channels and opportunity in value-added formats.
-
Production profile: Within the broader molasses universe, blackstrap-grade products command a disproportionate share due to their nutrient concentration and downstream utility — a structural advantage producers can exploit through focused processing and branding.
Competitive landscape — concentrated in name, fragmented in practice
The Blackstrap Molasses market is characterized by a mix of legacy family-owned producers, regional processors, and branded consumer-pack manufacturers. Aggregate concentration metrics indicate that the top three players control a relatively modest portion of the market, with the top five also leaving ample room for mid-sized players and niche specialists. This structure creates a dual path for growth: scale-driven cost leadership and niche-driven margin capture.
-
Zook Molasses Company (Zook Ag Company) — A family-owned bulk supplier positioned strongly in nutrient-rich molasses for feed and horticulture. Its nationwide logistics and organic/non-GMO options make it a natural strategic partner for integrators seeking supply security and traceability.
-
Golden Barrel (Good Food, Inc.) — Retail and bulk supplier emphasizing unsulfured, sugarcane-derived products for baking and health segments. Their brand-led approach highlights opportunities to extract higher retail value from historically industrial commodities.
-
B&G Foods, Inc. — A branded consumer-food player with legacy molasses brands. Recent product-variant launches emphasize organic and unsulfured options, signaling consumer demand towards premiumization and health-oriented claims.
-
M.A. Patout & Son, LTD, LLC — An incumbent raw sugar processor that benefits from integrated sugarcane operations and byproduct synergies, providing a competitive cost base for molasses production.
-
Crosby Molasses Co Ltd. — Producer with footprints across industrial and food manufacturing, recently introducing fortified molasses and enhanced packaging solutions to capture functional-food premiums.
-
Other notable participants — Regional suppliers and bulk specialists such as Indiana Sugars, Buffalo Molasses LLC, and Allied Old English play important roles in local markets and fulfillment for large processors and manufacturing operations.
Recent corporate moves underscore product differentiation and premiumization as clear strategic responses. For example, in 2025 B&G Foods launched organic/unsulfured variants for baking and health uses, and Crosby introduced fortified blackstrap lines with sustainable packaging — both reflect the premiumization trend and the race to capture functional-food dollars.
What the PW Consulting report contains — practical, proprietary, and ready-to-use
Our full market study goes beyond top-line forecasting to give teams operational tools they can use immediately. Highlights include:
-
Granular demand modeling across the 2020–2032 window with scenario alternatives calibrated for policy shifts and commodity cycles.
-
Supply-chain and cost-model templates to stress-test procurement and hedging strategies under price volatility scenarios.
-
Competitive benchmarking with capability maps, channel economics, and an M&A playbook tailored for both strategic buyers and financial sponsors.
-
Go-to-market blueprints for premiumization (consumer retail and functional-food channels) and scale plays (feed and industrial volume markets).
-
Regulatory impact assessment covering nutrition-labeling trends, renewable fuels policy, and sustainability reporting requirements.
-
Commercial KPIs and negotiation levers for pricing, minimum-order quantities, and value-added services (fortification, certification, packaging).
Note: this press preview deliberately refrains from publishing the full regional or application-level splits contained in the report. Those segment-level figures and proprietary model outputs are reserved for the full subscription product and direct clients.
Actionable 2026 strategic moves — prioritized
-
Re-evaluate channel mix: Reallocate CAPEX to channels where premiumization and certification deliver margin uplift rather than pure-volume arms races.
-
Lock-in diverse feedstock contracts: Use multi-year, index-linked agreements to stabilize input costs while preserving upside participation in falling-price scenarios.
-
Invest selectively in fortified and certified SKUs: Small-format, higher-margin product lines (organic, fortified, unsulfured) are proving resilient to commoditization.
-
Optimize logistics footprints: Near-sourcing and inventory strategies that reduce transit exposure will pay off given observed mid-2025 price and logistics tightness.
-
Pursue partnering over acquisition for rapid channel access: Brands and co-packing agreements accelerate entry into premium retail without requiring heavy upfront manufacturing retooling.
-
Embed regulatory monitoring in R&D roadmaps: Anticipate nutrition labeling and renewable fuels directives to convert compliance into product differentiation.
Risks, uncertainty, and scenario planning
-
Price volatility remains the most immediate commercial risk. Even modest upward swings in feedstock costs materially compress margins in low-value channels.
-
Policy reversals or slower-than-expected adoption of renewable fuel mandates would reduce a near-term industrial demand pool for molasses-based feedstocks.
-
Brand liability and quality traceability: As producers chase higher-margin consumer segments, investments in testing, certification, and transparent sourcing will be non-negotiable.
-
Geopolitical and logistics shocks: Regional disruptions in cane-sugar producing geographies can ripple quickly into export availability and freight pricing.
How to use this preview — and where to get the full model
This article outlines the strategic contours PW Consulting believes will matter most in 2026. For executive teams making allocation decisions this year, the following immediate steps are recommended: conduct a rapid-margin diagnostic for all molasses SKUs, run a 12–24 month procurement stress-test under PW’s downside commodity scenario, and prioritize pilot launches for fortified or certified premium SKUs that can be scaled in 9–18 months.
PW Consulting’s full Blackstrap Molasses Market report contains the empirical foundations for those actions, including the proprietary segment-level data, regional breakdowns, and downloadable financial models that are intentionally omitted from this preview to protect client intellectual capital. Subscribers and corporate clients can access the full datasets, scenario models, and supplier scorecards via the PW Consulting report portal.
Final thought
For companies competing in a market that is simultaneously steady and evolving, 2026 is the year to convert observational insights into structural differentiation. Whether the goal is securing low-cost production, unlocking consumer premiums, or entering industrial feedstock markets tied to renewables policy, the decisions taken this year will determine market positions for the better part of the next decade. PW Consulting’s full report equips leaders with the numbers, scenarios, and playbooks to make those decisions with confidence.
For detailed analysis of this topic, please visit the official page: Blackstrap Molasses Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Lithium Battery Ethylene Carbonate Market to Expand at 13.15% CAGR Through 2032 as Asia‑Pacific EV Demand Accelerates
By pmarketresearch, 2026-07-07
PW Consulting Strategic Brief: Lithium Battery Ethylene Carbonate Market — Actionable Intelligence for 2026 Decision-Making
PW Consulting today publishes an executive-level release accompanying our in-depth market study on ethylene carbonate (EC) used in lithium battery electrolytes. Designed as a strategic tool for leadership teams preparing budgets, supply-chain commitments, and technology roadmaps in 2026, this briefing highlights the macro trajectory, competitive posture, and the operational levers that matter — while reserving the proprietary, company- and segment-level tables for subscribers of the full report.
Lithium Batter Ethylene Carbonate Market
Top-line market context
-
Market scale and momentum: The lithium battery ethylene carbonate market has expanded rapidly over the past five years, rising from the low hundreds of millions in revenue in 2020 to USD 660.42 Million in our base year (2025). Our scenario-weighted forecast projects the market continuing to grow through the 2026–2032 horizon at a compound annual growth rate (CAGR) of 13.15%, reaching approximately USD 1.57 Billion by 2032.
Lithium Batter Ethylene Carbonate Market -
Historic acceleration: The market more than doubled over the 2020–2025 period, reflecting the acceleration of electrification in mobility, the scaling of stationary storage projects, and intensified demand for high-purity, battery-grade solvents.
Lithium Batter Ethylene Carbonate Market -
Concentration dynamics: Market share is meaningfully concentrated among leading global and regional producers; our concentration metrics indicate the top three firms control just under half of the market (CR3 ≈ 48.25%), and the top five account for roughly two-thirds (CR5 ≈ 64.12%). That structure creates both pricing power pockets and clear targets for competition and partnership.
Why this report is essential for 2026 strategic planning
-
Supply-demand alignment: Our demand model integrates battery build programs, electrolyte formulation trends, and a plant-level supply-side inventory to identify timing mismatches that can create short-term price spikes or margin compression. Executives can use these signals to prioritize feedstock hedges, capacity investments, or offtake agreements.
-
Cost exposure and sourcing: Ethylene oxide represents a dominant portion of raw material expense in EC manufacture (roughly 65–75%). Fluctuations in ethylene oxide availability and price translate almost directly into EC margin volatility — an operational reality our cost-pass-through templates quantify for 18-month and 36-month horizons.
-
Regional arbitrage and pricing regimes: Material price dispersion has widened in recent quarters — for example, Q4 2025 spot differentials in North America and China were pronounced — a structural feature that influences near-term trading, tolling economics, and the case for localizing capacity.
-
Regulatory and technology risk: Nearly half of manufacturers have shifted to lower-emission EC synthesis routes that leverage CO2-based feedstocks, reflecting regulatory pressure and ESG-aligned procurement. Simultaneously, academic and industrial R&D into EC-lean or EC-free electrolyte chemistries presents a medium-term demand risk that buyers and producers must monitor closely.
Key thematic takeaways (teaser insights)
-
EV battery buildouts remain the primary demand engine. While consumer electronics and utility-scale storage contribute, the pace and design of EV programs determine the shape of near-term demand surges.
-
Global production scale versus battery capture: Global EC production reached roughly 620 kilotons in 2024, and a significant share flows into lithium-ion battery electrolytes. How that production is allocated — between battery and industrial uses — is a leading indicator of market tightness or slack.
-
Price volatility is a strategic lever. The gap between regional price points creates incentives for trade, tolling, and investment that can be exploited by vertically integrated players or agile traders; it also increases the urgency for secure feedstock arrangements among battery makers.
-
Emission-conscious synthesis is becoming a competitive differentiator. Manufacturers adopting CO2-based routes are reducing regulatory exposure and gaining access to sustainability-linked customers, but these routes also require capital and operational redesign.
Competitive landscape — profiles and strategic postures
Our competitive analysis examines active global and regional suppliers, assessing technology readiness, capacity footprints, vertical integration, and strategic moves. Below we summarize the strategic posture of core players mapped in the market.
-
Mitsubishi Chemical Group Corporation (Japan) — A leading producer of high-purity EC focused on battery electrolytes. Recent investments include a new Southeast Asia production facility and strategic asset transfers of electrolyte manufacturing assets in North America and Europe to optimize a global manufacturing network. These moves indicate a deliberate strategy to secure regional supply while improving scale economics.
-
Huntsman International LLC (United States) — A North American leader that has expanded capacity tailored to EV-grade EC. Huntsman’s strengths are its product customization for high-purity applications and its integration with specialty chemical portfolios that can provide formulation advantages for electrolyte producers.
-
Oriental Union Chemical Corporation (OUCC) (Taiwan) — A focused manufacturer with strong proximity to East Asian battery supply chains; its positioning emphasizes reliability for OEMs sourcing in the region.
-
TOAGOSEI CO., LTD. (Japan) — A producer leveraging joint ventures to secure feedstocks and deliver battery-grade quality, benefiting from Japanese quality perceptions and overseas JV scale.
-
BASF SE (Germany) — A diversified global chemical player that supplies EC as part of broader electrolyte solutions; BASF’s strength lies in global reach and R&D capabilities to co-develop formulations with battery manufacturers.
-
Leading Chinese producers — Several vertically integrated Chinese firms (formerly organized under groups such as Shinghwa and others) combine raw material sourcing, EC manufacture, and proximity to battery cell builders, offering a cost-competitive pathway to scale. Our analysis highlights how their vertical integration changes trade flows and contract structures.
-
Specialty suppliers — Niche firms in Japan and Europe emphasize premium, battery-grade (>99.99%) specifications and tailor services such as quality assurance and small-lot supply for R&D and pilot programs.
Collectively, these players demonstrate differentiated strategies: scale and cost competitiveness, regional supply security, premium high-purity specialization, and vertical integration aimed at capture of downstream margin. Recent disclosed moves — such as Mitsubishi’s Southeast Asia plant and asset optimizations, and new capacity announcements from electrolyte players in China — validate our view that the next 18 months will be a window of strategic consolidation and greenfield responses.
What the PW Consulting report delivers (practical contents)
-
Scenario-driven demand model (2026–2032) with sensitivity levers for EV penetration, pack-level EC intensity, and alternative electrolyte adoption.
-
Supplier scorecard and plant-mapped capacity atlas (includes utilization, ramp timing, and feedstock exposure) to prioritize sourcing partners and contingency plans.
-
Raw-material cost pass-through models and recommended hedging templates to quantify margin risk under multiple ethylene oxide scenarios.
-
Regulatory and sustainability pathway mapping that links low-emission synthesis adoption to permitting timelines, capex needs, and buyer preferences.
-
Commercial playbooks for producers and battery manufacturers — including tolling structures, offtake clause language, and transition strategies for EC-lean electrolytes.
-
M&A and partnership shortlists based on strategic fit, with valuation frameworks and integration risk matrices.
Strategic recommendations for 2026 stakeholders
-
Producers: Prioritize flexible capacity (tolling and modular units) to exploit regional price spreads while investing selectively in low-emission routes to access premium customers and reduce regulatory risk.
-
Battery manufacturers/OEMs: Secure multi-year supply contracts with clause structures that balance price stability and access to battery-grade quality; evaluate co-investment in regional capacity where cell programs are large and concentrated.
-
Investors and private equity: Focus diligence on players with feedstock security, proximity to EV supply chains, and the capability to upgrade to lower-emission synthesis economically; look for consolidation targets in mid-size regional suppliers.
-
Policymakers and procurement leads: Use the transition window to incentivize CO2-based synthesis adoption and to support circularity initiatives that reduce raw-material volatility in the long term.
Methodology and data integrity
The PW Consulting study uses a mixed-methods approach. Base year calibration is 2025, with historical coverage from 2020 to 2025 and a forecast window of 2026–2032. Our forecast integrates primary interviews at plant and C-suite levels, trade and customs flows, input-cost modeling (including the ethylene oxide cost bucket), price-series analysis, and publicly disclosed capacity announcements. All monetary values are reported in USD and revenue units are expressed in millions unless otherwise noted. The full report includes model files and scenario toggles for client use.
Accessing full, granular intelligence
This article is a strategic preview highlighting the report’s value. To preserve the commercial integrity of our modeling and to deliver a high-actionable product for subscribers, we have omitted granular regional and application-level breakdowns and company-level volumes from this brief. Those detailed tables, supply maps, and the interactive forecast model are available exclusively in the full PW Consulting Lithium Battery Ethylene Carbonate Market Report. Visit PW Consulting’s research portal or contact our subscription desk to request the complete deliverable and a licensed model walkthrough.
In an environment where price spreads, feedstock exposure, regulatory shifts, and formulation innovation converge, PW Consulting’s market study provides the decision-grade intelligence leaders need to position portfolios, prioritize investments, and construct resilient supply contracts for 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Lithium Batter Ethylene Carbonate Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecasts Airspace Management System Market to Reach USD 2,575.4 Million by 2032, Up from USD 1,450.0 Million in 2025 (8.55% CAGR)
By pmarketresearch, 2026-07-07
Airspace Management System Market 2026: Strategic Imperatives from PW Consulting’s New Industry Report
As PW Consulting’s senior strategic advisor and lead industry analyst, I present a concise briefing on the strategic value our latest Airspace Management System (AMS) Market report delivers to executive decision-makers in 2026. This is a forward-looking, decision-grade synopsis designed to demonstrate the rigor and practical orientation of the full report while preserving the proprietary granular segmentation that drives procurement, M&A, and product strategy choices. For organizations facing the twin pressures of accelerated modernization and expanding airspace use, this briefing highlights where to focus senior attention, which uncertainties to hedge, and how the market trajectory shapes capital and operational choices over the next planning cycle.
Airspace Management System Market
Why 2026 Is a Pivotal Year for AMS Decisions
Regulatory and infrastructure momentum that crystallized between 2023 and 2025 now moves into operational implementation. Several national modernization programs and new spectrum and communications rules have created enforceable timelines and funding windows that will materially affect procurement cycles and integration roadmaps. For C-suite and boardrooms, 2026 is the first year in which near-term tactical choices (procurement timing, partnership selection, vendor lock-in tolerances) will determine competitive optionality for projects delivered through 2028 and beyond.
Airspace Management System Market
- Modernization programs (federal and regional) are shifting from planning to large-scale deployment phases.
- New spectrum rules and IP-based telecommunications transitions are rewriting technical specifications and interoperability baselines.
- Investment windows now require firms to make multi-year commitments where flexibility and upgradeability are primary risk mitigants.
Market Trajectory: Size, Growth and Structure
PW Consulting’s market model shows the global AMS market expanding decisively through the 2026–2032 forecast horizon. After a steady rise from the early-decade base, the market reached a measured size of approximately USD 1,450 Million in the base year 2025. Our forecast indicates a compound annual growth rate (CAGR) of 8.55% over the 2026–2032 period, culminating in a market value exceeding USD 2.5 billion by 2032. The trajectory reflects synchronized upgrades across civil, defense and public-safety domains, accelerated adoption of software-defined capabilities, and growing demand for integrated surveillance and automation systems.
Airspace Management System Market
Market concentration is meaningful but not prohibitive: the three largest providers account for roughly half of the market, and the five largest firms capture about two-thirds. This structure creates a dual dynamic — established suppliers exert pricing and integration influence, while mid-tier and specialist players win on niche innovation and service flexibility.
Key Demand Drivers and Strategic Implications
- Airspace densification and the rise of new entrants (UAS, advanced air mobility, and increased commercial traffic) are increasing demand for layered surveillance and dynamic flow management tools. Enterprises should prioritize systems that support multi-domain integration and are certified for mixed-traffic operations.
- Regulatory harmonization initiatives such as ICAO’s ASBU and regional programs like the EU’s Single European Sky accelerate requirement convergence. Buyers must demand conformity-plus — regulatory compliance today plus a product upgrade path to meet evolving standards.
- Large-scale public investments and modernization programs create procurement windows but also impose technical and contractual constraints. For vendors, this means structuring offerings with adaptable financing and modular deployment. For operators, RFP timing and systems integration strategy will determine total cost of ownership.
- Connectivity transitions (migration from legacy TDM copper to IP/fiber/wireless) and new spectrum allocations for UAS CNPC are shifting where value accrues — to vendors who can deliver resilient, standards-compliant communications and end-to-end cybersecurity assurance.
Technology and Regulation: Catalysts in 2026
Several technical and regulatory catalysts are decisive for near-term strategy:
- National modernization plans are replacing legacy radar and telecommunications infrastructure, creating demand for radar modernization, IP-based telecoms, and cloud-enabled automation platforms.
- Spectrum policies enabling dedicated bands for UAS CNPC, together with RTCA standards, are establishing technical baselines for safe unmanned operations — a major new addressable market for AMS vendors that can deliver integrated CNPC and traffic management capabilities.
- Space-based surveillance services and partnerships between satellite ADS‑B providers and ATM vendors are shifting how flow management and long-range surveillance are provisioned, enabling more flexible network architectures.
- Environmental and capacity mandates embedded in regional initiatives are pushing the sector toward performance-based navigation and trajectory-based operations, which require richer data-sharing ecosystems and automation tools.
Competitive Landscape — Who Matters and Why
The AMS market blends long-established aerospace and defense incumbents with specialized systems integrators and newer data/service players. Our competitive assessment highlights each firm’s differentiating capability, typical procurement role, and strategic moves observed in the 2024–2026 window:
- Thales Group (France): A leader in integrated ATM suites and flow-management, with strengths in combined civil/military deployments and recent contract awards for national modernization programs. Strategic partnerships around data integration amplify its systems play.
- RTX Corporation (United States): Through its Raytheon and Collins Aerospace lines, it offers radar modernization, automation platforms and communications — a core supplier in major national renewals. Recent contract awards tied to large-scale radar replacement underline its role on infrastructure projects.
- Indra Sistemas S.A. (Spain): Known for automation and CNS systems and cloud-native ATC solutions, Indra competes strongly in full modernization projects and is active in global ATC modernization tenders.
- Honeywell International Inc. (United States): Focuses on avionics, flight data processing and integrated ATM solutions; positions itself where airborne and ground-system integration is a procurement priority.
- L3Harris Technologies Inc., Leonardo S.p.A., Saab AB, Frequentis AG, Northrop Grumman, BAE Systems, Leidos, and Aireon: each brings differentiated strengths — from digital/remote towers to space-based surveillance and safety-critical communications. New product launches and partnerships (including space-data integrations) are reshaping competitive adjacencies.
Recent market events — major radar modernization awards, national ATC modernization contracts, cloud-based ATC platform launches, and strategic partnerships to integrate space-based ADS‑B with flow management — confirm an active procurement and alliance environment. These dynamics favor suppliers who combine domain expertise with software and data-platform capabilities.
What the PW Consulting Report Contains (Practical, Actionable Deliverables)
To support 2026 decision-making, the full PW Consulting AMS Market report includes the following execution-oriented modules:
- Proprietary market-sizing model with historical baselines and scenario-modeled forecasts through 2032, calibrated to programmatic funding and deployment timelines.
- Vendor benchmarking with technology scorecards, procurement playbooks, reference architectures, and typical contract models observed in recent national programs.
- Regulatory impact assessment mapping ICAO, regional programs and national initiatives to technical requirements, certification pathways, and procurement windows.
- Integration and TCO frameworks that quantify CAPEX/OPEX tradeoffs for hardware-centric versus software-defined deployment strategies, including upgrade and migration sequencing.
- Risk register and mitigation playbook covering interoperability, cybersecurity, obsolescence and supplier concentration risks, with practical contract clauses and SLA templates.
- Scenario analysis (best case, base case, downside), stress-tested against delayed funding, technology adoption lags, and accelerated UAS traffic scales.
- Strategic recommendations for operators, suppliers and investors — covering partnership models, go-to-market plays, and technology investment priorities.
Note: the public briefing deliberately omits granular regional and application-level revenue splits and supplier share tables. Those core segmentation datasets are central to procurement and investment decisions and are only available in the full report and corresponding datasets.
How Strategic Leaders Should Use This Report in 2026
- CIOs & CTOs: Use the TCO and integration frameworks to design procurement packages that preserve upgrade pathways to software-defined and cloud-native capabilities.
- Heads of Procurement: Leverage the vendor scorecards and contract archetypes to accelerate RFP development while avoiding supplier lock-in pitfalls.
- Corporate Strategy & Development: Deploy the scenario models to size addressable opportunity in adjacent markets (UAS traffic management, space-based surveillance services) and to prioritize M&A targets that close capability gaps.
- Investors and PE: Use concentration metrics and vendor risk assessments to identify consolidation targets and service businesses with defensible margins driven by recurring services and integration complexity.
Closing Advice — Five Immediate Actions for Executives
- Re-run your 2026 procurement calendar against the timelines in the report; postpone or accelerate tenders where funding windows and vendor roadmaps create optionality.
- Prioritize modular architectures with clear upgrade paths to support trajectory-based operations and multi-domain surveillance inputs.
- Negotiate data-rights and integration clauses up-front to preserve the ability to switch or augment data providers (including space-based ADS‑B and cloud services).
- Build partnership scenarios with both large systems integrators and specialist platform providers — competition is shifting from hardware alone to hybrid HW/SW/data offerings.
- Stress-test cyber and resilience assumptions; the move to IP-based backbones and shared data services increases attack surfaces and downstream operational risk.
Access the Full Report
PW Consulting’s AMS Market report is designed as a working tool for executives and operators making material decisions in 2026 and beyond. It contains the complete segmentation, detailed vendor share tables, procurement templates, and the underlying dataset supporting our forecasts. To obtain the full report and data package, including the confidential segmentation matrices and vendor scorecards referenced above, please visit our report portal or contact PW Consulting’s client services team.
In a market defined by rapid technical change and concentrated modernization spending, the right combination of procurement discipline, modular architecture, and strategic vendor selection will determine who captures the next wave of airspace management value. PW Consulting’s analysis maps the path — the full report provides the instruments to execute it.
For detailed analysis of this topic, please visit the official page: Airspace Management System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report: Audit Management Software Systems Market Poised for 11.2% CAGR Through 2032
By pmarketresearch, 2026-07-07
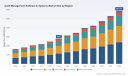
Audit Management Software Systems Market 2026: Strategic Imperatives for Decision-Makers — PW Consulting Insight Brief
As organizations confront accelerating regulatory complexity, mounting auditor shortages, and the rapid maturation of AI-enabled governance tools, the Audit Management Software Systems market is entering a phase of structurally higher demand and strategic re‑positioning. PW Consulting’s latest market study, with a 2025 base year and a forecast horizon to 2032, synthesizes five years of historical performance (2020–2025) with scenario-driven forecasting through 2032. The market expanded to roughly USD 2.8 billion in 2025 and is projected to grow at a compound annual growth rate (CAGR) of 11.2%—crossing the USD 3.1 billion threshold in 2026—underscoring the accelerating shift from manual, point-solution approaches to integrated, risk‑centric audit platforms.
Audit Management Software Systems Market
Why this report matters for 2026 decisions
-
Actionable timing: With enforcement milestones (notably the EU AI Act coming into full force in mid-2026) and a wave of vendor product launches and partnerships already reshaping capabilities, 2026 is a pivotal year for procurement cycles, architecture decisions, and compliance roadmaps. The report translates regulatory timelines into procurement and implementation windows—helping buyers avoid costly rework and choose solutions that are enforceable‑ready.
Audit Management Software Systems Market -
Economics and priority-setting: Rising labor costs and shortages in audit talent make automation and evidence orchestration business imperatives. Our analysis quantifies productivity inflection points where automation materially reduces audit cycle time and total cost of ownership—critical input for finance, IT and internal audit leaders preparing 2026 budgets.
Audit Management Software Systems Market -
Vendor and platform strategy: The market is moderately concentrated (top-three and top-five firm concentration metrics demonstrate meaningful but not prohibitive concentration), creating both incumbent advantages and attack vectors for innovative challengers. The report provides layered vendor assessment to inform shortlists and negotiation strategies.
-
Risk‑informed investment: For investors and private equity teams, our forecast scenarios identify segments with accelerated monetization potential linked to SaaS subscription expansion, embedded AI feature monetization, and cross-sell into adjacent GRC modules.
What the PW Consulting report contains — practical, executable content
-
Proprietary market model and forecast engine: A transparent, traceable model spanning 2020–2032 with sensitivity scenarios (base, upside, downside) tied to regulatory shock events, macroeconomic variance, and AI adoption curves.
-
Buyer playbooks: Step‑by‑step templates for RFP design, vendor scorecards, TCO calculators (license, implementation, change management, and ongoing maintenance), and a migration decision tree for legacy on‑premise versus cloud adoption.
-
Implementation blueprints: Minimum viable architecture for integrating audit platforms with ERP, data warehouses and identity systems; phased rollouts designed to deliver measurable audit KPIs in 90‑ and 180‑day milestones.
-
Benchmarked KPIs: Practical metrics and dashboards for measuring audit program maturity, automation uplift, evidence traceability, and compliance remediation velocity.
-
Vendor evaluation matrix: Multi‑dimensional scoring covering product functionality, AI governance readiness, data residency and privacy posture, ecosystem integrations, professional services maturity, and pricing transparency.
-
Case studies and savings models: Real-world adoption scenarios that illustrate ROI pathways for finance-led, risk-led, and compliance-led procurement initiatives.
Competitive landscape: positioning and strategic moves
The competitive map shows established GRC and enterprise software vendors advancing along different vectors—platform breadth, domain specialization, AI‑infused productivity, and ecosystem partnerships. Key strategic observations:
-
Specialist innovators (e.g., modern audit-native platforms) are doubling down on connected risk workflows and AI-driven evidence orchestration. These vendors excel at purpose-built audit processes and fast time‑to‑value for internal audit teams.
-
Integrated GRC incumbents and enterprise suites are leveraging cross‑module synergies—bundling governance, risk, compliance, and audit capabilities into unified platforms. Such breadth supports enterprise consolidation strategies but may require careful evaluation of depth in audit-specific workflows.
-
Pure-play enterprise software providers are focusing on integration within broader financial and ERP ecosystems, offering seamless data flows and strong controls for organizations with large SAP/ERP footprints.
Representative vendor profiles analyzed in the report include market leaders and rapidly growing challengers. PW Consulting examines their strategic positioning—product strengths, roadmap momentum, go‑to‑market motion, AI readiness, and professional services capability—providing decision‑grade intelligence for 2026 shortlists.
Recent ecosystem developments and implications
-
Partnership acceleration: Strategic alliances and partnerships announced late‑2025 and early‑2026 are expanding capabilities around automated data ingestion and audit evidence readiness. Buyers should treat partner depth (integration maturity, shared SLAs) as a procurement gating factor.
-
Vendor product launches: Several vendors rolled out embedded AI suites and data privacy modules in 2025–2026. These features reduce manual triage work, but buyers must validate AI governance controls, explainability, and human-in-the-loop safeguards—especially with imminent AI regulation.
-
Regulatory inflection points: The full enforcement of the EU AI Act in August 2026 and expanding U.S. state privacy laws increase compliance complexity. Platforms that can demonstrate rigorous model documentation, data lineage, and auditable decision trails will be preferred in regulated industries.
-
Market concentration dynamics: Measured concentration indicates leading vendors hold meaningful share without forming a dominant oligopoly—an environment that encourages both consolidation and continued innovation. Procurement teams can extract value through competitive sourcing while planning for multi‑vendor coexistence.
Technology and regulatory dynamics to watch in 2026
-
AI governance will be a procurement filter. Beyond flashy copilots, auditors and compliance officers will prioritize platforms with policy engines, bias mitigation, model monitoring, and documented human oversight workflows.
-
Data privacy and residency constraints will drive architectural choices. Expect hybrid deployment patterns—some workloads remaining on-premise or in constrained cloud enclaves to satisfy local privacy regimes.
-
Interoperability over monoliths: Organizations increasingly favor platforms that provide robust APIs and packaged connectors to ERPs, contract systems, and evidence repositories, enabling composable audit ecosystems.
-
Automation maturity differentiators: Vendors that convert raw data into audit‑ready evidence (structured mapping, linkage to controls, time‑stamped trails) will win engagement and justify premium pricing.
Recommended strategic moves for 2026
-
For enterprise buyers: Run a two‑track procurement—(1) a short‑term tactical procurement to automate immediate high‑volume audit tasks, and (2) a medium‑term architectural program to consolidate audit, risk and compliance data flows across the enterprise. Insist on proof‑of‑concepts that demonstrate measurable cycle time and remediation velocity improvements.
-
For mid-market and SME buyers: Prioritize platforms that offer pre‑built connectors and packaged workflows to minimize implementation lift. Consider SaaS subscriptions with staged rollouts to control cash flow and deliver early wins.
-
For vendors: Differentiate through verifiable AI governance, domain templates, and close partnerships with ERP and data providers. Invest in verticalized content (industry control frameworks, regulatory mappings) to accelerate buyer time‑to‑value.
-
For investors: Look for companies with high gross retention and strong professional services margins, especially those that can demonstrate composable architectures and platform‑driven monetization beyond seat licenses.
How PW Consulting’s analysis reduces execution risk
Our report minimizes implementation risk by combining quantitative forecasting with practical execution artifacts. The market model quantifies demand trajectories and identifies sensitivity to regulatory and macro drivers; the implementation playbooks reduce time‑to‑value; the vendor scorecards cut vendor selection cycles by providing reproducible evaluation criteria. Collectively, these deliverables turn market insight into executable decisions that align procurement cadence with compliance deadlines and ROI thresholds.
Where this leaves decision‑makers
2026 will separate organizations that treat audit modernization as a tactical cost play from those that view it as a strategic capability—integral to risk management, control assurance, and sustainable compliance. With the market already exhibiting mid‑double‑digit growth and vendors accelerating AI and privacy capabilities, the window to secure advantageous pricing, integration priority, and transformation momentum is narrow but actionable.
PW Consulting’s Audit Management Software Systems Market report equips boards, CFOs, CIOs, CAEs, procurement teams, and investors with the context, tools, and vendor intelligence required to make confident 2026 decisions. To preserve the utility of this briefing as a strategic “trailer,” detailed regional and segment-level breakdowns, full vendor scorecards, and granular financial matrices have been reserved for the full report.
Next steps
-
Download the full dossier and supporting spreadsheets for procurement-ready artifacts, scenario models, and vendor profiles (available via PW Consulting’s report portal).
-
Schedule a briefing with our advisory team for a tailored session: alignment to your audit maturity, mapping of integration points, and a 90-day pilot plan.
Contact PW Consulting to convert the market momentum into a defensible, measurable audit modernization program in 2026.
For detailed analysis of this topic, please visit the official page: Audit Management Software Systems Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Patient Record Management Market to Grow at 6.41% CAGR, Topping USD 64,362.93 Million by 2032
By pmarketresearch, 2026-07-07
Patient Record Management Market — Strategic Imperatives for 2026
As health systems, payers, and technology vendors transition from pandemic-driven triage to long-term digital transformation, patient record management has moved from a compliance checkbox to a strategic spine of care delivery. PW Consulting’s latest market study — anchored on a 2025 base year and a 2026–2032 forecast horizon — projects continued expansion at a compound annual growth rate of 6.41%. The market, which surpassed the USD 41 billion mark in 2025 and is projected to exceed USD 44 billion in 2026, is now at an inflection point where architecture choices, ecosystem partnerships, and regulatory alignment will determine winners and laggards.
Patient Record Management Market
Why this report matters for 2026 decision-making
-
Strategic procurement: Health systems planning major EMR/EHR refreshes in 2026 need a differentiated framework to evaluate not just point features, but long-term extensibility (APIs, FHIR compatibility), total cost of ownership, and partner ecosystems. Our study equips buyers with actionable procurement frameworks that prioritize upgrades with the highest strategic upside.
Patient Record Management Market -
M&A and partnership screening: Investors and corporate development teams require forward-looking lenses — beyond historical revenue multiples — to value interoperability capabilities, AI-readiness, and cloud-native roadmaps. The report synthesizes those valuation levers into a repeatable diligence checklist.
Patient Record Management Market -
Implementation risk reduction: Implementation failures remain an outsized source of cost and reputational damage. The study’s playbooks and risk heatmaps enable program leaders to calibrate governance, change management, and vendor SLAs for 2026 rollouts.
-
Regulatory compliance and reimbursement alignment: With evolving guidance on data exchange and continued incentive signals from payers and regulators, our analysis translates policy into actionable compliance and revenue strategies for 2026.
What the PW Consulting report delivers (operational, practitioner-focused content)
-
Decision-grade market sizing and scenario modeling: A transparent methodology and sensitivity models that let executives stress-test investment decisions under alternative adoption, reimbursement, and regulation scenarios for 2026–2032.
-
Buyer personas and procurement templates: Role-based requirements for chief digital officers, CIOs, CMIOs, and procurement teams — including RFP language, evaluation matrices, and vendor scorecards tuned to interoperability, AI, and security objectives.
-
Implementation playbooks: Step-by-step blueprints for migration (greenfield and brownfield), data migration checklists, cutover strategies, and governance models proven to reduce go-live disruption.
-
Financial tools: TCO and ROI calculators that incorporate direct costs, transition costs, revenue cycle impacts, and longer-term value from analytics and patient engagement.
-
Risk and compliance toolkit: Mapped compliance tasks linked to HITECH, ONC Cures-era rules, CMS interoperability incentives, and EU GDPR constraints for cross-border deployments — plus sample contractual clauses and audit-readiness checklists.
-
Vendor playbooks: Comparative capabilities and integration pathways that help technology partners position their products against enterprise buyers’ priorities.
Market dynamics shaping 2026 strategies
-
Interoperability and API economics: The maturation of HL7 FHIR standards has accelerated API-first approaches. Organizations that design integration layers to absorb standard and non-standard data sources will capture disproportionate downstream value from analytics, care coordination, and patient-facing services.
-
Cloud-first architectures: Cloud adoption continues to outpace legacy on-premise renewals for new projects. Cloud-enabled platforms deliver faster feature cycles, elastic analytics, and improved disaster recovery — but also demand rigorous cloud governance and revised procurement clauses.
-
AI augmentation, not replacement: Recent vendor initiatives demonstrate a shift toward AI-assisted workflows (summarization, decision support, coding automation). Buyers should prioritize vendors that expose AI capabilities through governed APIs and explainability mechanisms aligned to clinical workflows.
-
Regulatory convergence and reimbursement levers: U.S. policy (HITECH, ONC’s Cures rules) and reimbursement programs (CMS Promoting Interoperability incentives) continue to shape adoption levers. In parallel, EU privacy regimes require rigorous controls for health data processing. 2026 strategies must reconcile data liquidity goals with jurisdictional privacy constraints.
-
Market concentration and competitive dynamics: The market displays measurable consolidation at the top; three firms capture a meaningful plurality of enterprise deployments, with a larger set of five vendors controlling a majority footprint. This concentration creates scale advantages in integration breadth, but opens pockets of differentiated opportunity for specialized and cloud-native challengers.
Competitive landscape — strategic positioning of core vendors
Our qualitative benchmarking focuses on product architecture, go-to-market models, partnership ecosystems, and innovation velocity rather than absolute share figures. Highlights include:
-
Epic Systems Corporation — A dominant enterprise incumbent known for deep clinical coverage and robust patient portals. Epic’s continued investments in AI-enabled summarization and enhanced interoperability are intended to defend large-system relationships while enabling downstream services for longitudinal care.
-
Oracle Cerner — Positioned as a platform integrator with a growing emphasis on cloud analytics and third-party partnerships. Strategic alliances with hyperscalers are accelerating its capabilities in large-scale patient record analytics and population health insights.
-
Athenahealth — A cloud-first challenger focused on ambulatory and community health markets. Recent certification milestones solidify its compliance posture and support customers pursuing rapid digital-first deployments.
-
Allscripts, NextGen Healthcare, eClinicalWorks — Each occupies differentiated niches (ambulatory, specialty, practice management) and competes on integration depth, pricing flexibility, and telehealth/engagement feature sets. Their agility in specialized workflows presents strategic value to mid-market buyers.
-
GE HealthCare — Strengths in imaging and diagnostic integration create unique value for enterprises seeking to unify clinical imaging with longitudinal patient records and AI diagnostic workflows.
Recent vendor moves underscore these dynamics: Epic’s platform enhancements for AI summarization (Oct 2025), Oracle Cerner’s cloud analytics partnership announcements (Sep 2025), and Athenahealth’s certification achievements (Jun 2025) signal an industry pivot toward API-enabled services, analytics monetization, and regulatory alignment.
Five strategic imperatives for executives in 2026
-
Design for composability: Favor modular, API-first platforms that separate core record services from specialty apps. This reduces vendor lock-in and accelerates the deployment of targeted innovations (AI, telehealth, patient engagement).
-
Prioritize data governance and interoperability playbooks: Implement standardized APIs, canonical data models, and a tiered access control model that satisfy both exchange goals and privacy constraints across jurisdictions.
-
Invest in implementation muscle, not just software: Allocate budget to change management, data quality remediation, and integration engineering to protect against common go-live failures and to accelerate time-to-value.
-
Leverage vendor partnerships for analytics and population health: Seek contractual commitments for API access, co-development arrangements, and data portability clauses to retain strategic optionality.
-
Embed compliance into product roadmaps: Make regulatory certification and explainable AI non-negotiables for vendor selection, especially where reimbursement or cross-border data flows are material to the business case.
How to use this report in 2026
PW Consulting’s Patient Record Management Market study is a decision-ready toolkit designed for boardrooms and program teams. Use it to:
-
Build a 24–36 month investment roadmap that aligns technology choices to strategic clinical and financial objectives.
-
Run comparative diligence on shortlisted vendors using our scorecards and scenario models.
-
Frame M&A targets and partnerships against interoperability and AI-readiness criteria rather than historic revenue alone.
-
Operationalize compliance with templated clause libraries and audit checklists tied to major regulatory regimes (U.S. and EU).
Next step — where to find the full intelligence
This briefing highlights strategic takeaways while intentionally omitting granular segmentation tables, regional and application-level breakouts, and certain line-item financials to preserve the value of the complete dataset. Executive teams and practitioners seeking the full, downloadable report — including detailed segment analyses, interactive scenario tools, and vendor scorecards — should visit our report portal to access the complete intelligence package and accompanying implementation assets.
PW Consulting is prepared to translate the report into tailored workshops, procurement support, and diligence advisory for organizations investing in patient record modernization in 2026. Reach out to our team to schedule a briefing and obtain the datasets that underpin the strategic recommendations outlined above.
For detailed analysis of this topic, please visit the official page: Patient Record Management Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report: Release Paper Market Hits USD 4.85 Billion in 2025
By pmarketresearch, 2026-07-07
Release Paper Market 2026: Strategic Imperatives from PW Consulting’s Release Paper Market Report
Executive Preview
As companies position for the next cycle of packaging, labeling, and specialty-paper demand, PW Consulting’s Release Paper Market Report (base year 2025) provides a timely strategic compass. Our analysis shows the global release paper market reached approximately USD 4.85 billion in 2025 and is projected to expand at a compound annual growth rate (CAGR) of about 5.45% through the 2026–2032 forecast horizon, reaching roughly USD 7.0 billion by 2032. These headline metrics frame a medium-term growth story that is compelling for investors, procurement leaders, and product strategists—but behind the aggregate numbers lie operational and regulatory dynamics that will determine winners and laggards in 2026.
Release Paper Market
Why this report matters for 2026 decision-making
- Actionable foresight for procurement and cost control: The report translates macro momentum into procurement scenarios and stress-tests supplier exposure against several raw-material and regulatory shocks, providing practical levers procurement teams can deploy in 2026.
- Roadmap for sustainable product transitions: With extended producer responsibility (EPR) regimes and growing recyclability requirements tightening across key jurisdictions, the research helps R&D and sustainability leaders prioritize investments that balance circularity and manufacturability.
- Commercial and M&A playbooks: For corporate development teams, our competitive analysis highlights consolidation opportunities and the degree of fragmentation in the supplier base, supporting informed target screening and integration hypotheses.
- Go-to-market and innovation sequencing: Marketing and product teams receive channel- and use-case-focused guidance to sequence product launches aligned with rising demand pockets and evolving regulatory constraints.
What’s inside the Release Paper Market Report (practical summary)
This release is structured to be immediately operational for business leaders evaluating 2026 initiatives. Key deliverables include:
Release Paper Market
- Proprietary market sizing and a scenario-based forecast model covering 2026–2032 with sensitivity to pulp costs, coating chemistries, and regulatory adoption timelines.
- A supplier risk matrix that maps production footprints, technology differentiation (e.g., silicone vs. poly-coatings), and single-source exposures at the SKU level.
- Playbooks for circularity implementation—technical routes, cost-to-implement estimates, and pilot design templates for in-plant liner recovery and beneficiation.
- Commercial heatmaps and channel strategies for labels, tapes, packaging, and hygiene/medical applications (high-level directional opportunity zones only; detailed regional/application tables are reserved for the full report).
- Deal and partnership frameworks for scaling recycled-content programs, joint procurement, and co-investment in local recycling infrastructure.
Market structure and competitive dynamics
The release paper market remains structurally fragmented. Our concentration analysis indicates a modest degree of aggregation at the top—approximately 20% for the top three players and roughly 28% for the top five—leaving ample room for regional champions, specialized niche players, and new entrants pursuing differentiated sustainability or cost innovations.
Release Paper Market
Across the competitive set, several strategic archetypes are evident:
- Global platform players with integrated solutions —firms that combine base paper production, coating capabilities, and labeling materials are positioned to offer turn-key value to large CPG and industrial customers. These players can bend the supply-cost curve through scale and internal feedstock synergies.
- Sustainability-first innovators —manufacturers investing in recyclable, fiber-based liner technologies and circular feedstock loops are capturing premium mandates from retailers and regulated markets. Their technology roadmap and municipal/recycling partnerships matter more than ever under EPR regimes.
- Regional specialists and film-centric suppliers —companies focused on filmic liners or poly-coated substrates retain cost and performance advantages in specific segments, notably where moisture or barrier properties are non-negotiable.
Company-level implications (selected leaders)
- Loparex LLC (USA) — A leader in specialty paper and film release liners, Loparex’s comprehensive coated and poly-coated portfolio makes it a go-to supplier for complex label and graphics applications. For strategic buyers, Loparex represents a supply partner for high-performance specifications and technical collaboration.
- Ahlstrom (Finland) — Ahlstrom’s emphasis on fiber-based release materials and sustainability positions it well for customers in regulated markets pivoting away from plastics. Expect partnership opportunities for pilots that require high recycled content and strong provenance documentation.
- Mondi Group (Austria/UK) — Mondi’s recent capacity developments and circularity collaborations underline a strategy that marries scale with closed-loop initiatives. Companies exploring regional capacity de-risking or collaborative recycling projects should prioritize Mondi as a potential anchor partner.
- UPM Raflatac / UPM (Finland) — Combining labelstock with release liners, UPM delivers integrated solutions attractive to brand owners seeking simplified supplier consolidation and recyclability roadmaps.
- Avery Dennison & 3M (USA) — Both firms bring deep expertise in pressure-sensitive systems and broad sales channels; their scale enables rapid rollouts of enhanced label-systems but may come at a premium.
- European and Asia-focused specialists (e.g., Gascogne, Sappi, LINTEC, Polyplex) — These firms complement the global players with regional agility and technical niches, particularly where local raw material dynamics and customer proximity matter.
Across all supplier types, buyers should evaluate partners not only on unit cost but on roadmap alignment for recyclability, availability of technical support, and ability to co-invest in pilots or shared recycling infrastructure.
Key dynamics shaping 2026 outcomes
- Raw-material and input-cost volatility: Wood pulp and kraft pulp dynamics continue to be a primary cost driver. Our scenario work shows that procurement strategies which blend longer-term contracts, index-linked clauses, and alternative fiber sourcing materially reduce margin shock exposure.
- Regulatory acceleration on recyclability and EPR: EPR systems now operate or are being enforced across multiple major markets, raising the cost of non-recyclable or hard-to-separate liner formats. Companies that implement recyclable or mono-material liner approaches earlier secure both regulatory compliance and brand value.
- Technology and product substitution: The pace of “paperization” for certain packaging formats is increasing, but technical trade-offs persist (e.g., barrier properties, machine runnability). The most successful product teams will sequence substitutions where return-on-investment and supply resilience align.
- Circularity initiatives and localized recycling partnerships: Recent industry collaborations show an appetite for industrial-scale reuse of siliconized and coated paper waste. Players who can convert waste streams into secondary feedstock will unlock raw-material cost advantages and satisfy EPR reporting requirements.
Recent industry movements worth noting
- Mondi’s infrastructure expansion and circularity partnerships indicate strategic emphasis on local capacity and waste-to-resource programs—signaling windows for co-investment with downstream customers.
- Industry exhibitions and supplier showcases in late 2025 highlighted new coating technologies and barrier chemistries intended to accelerate paperization while preserving performance—an R&D area buyers should audit in 2026 pilots.
- Regulatory guidance continues to push recyclability testing and labeling rules into procurement contracts; legal and sustainability teams must be embedded in supplier selection earlier in the buying cycle.
Practical recommendations for 2026
- Embed a dual sourcing strategy: Combine a global-tier supplier for scale-sensitive SKUs with a regional specialist to manage local compliance and logistical agility.
- Deploy staged circularity pilots: Start with high-volume SKUs where separation is practicable, and structure cost-sharing with suppliers for recycling infrastructure.
- Re-scope procurement KPIs: Add recyclability, documented secondary-feedstock sources, and supply-path transparency to TCO models—not just price per roll or sheet.
- Prioritize technical validation: Require machine trials and runnability guarantees for any supplier proposing substantial material substitutions—minimize SKU disruption risk.
- Monitor regulatory levers: Map EPR timelines against product roadmaps and establish contingency plans for jurisdictions where minor packaging components are now within scope.
How PW Consulting can accelerate your 2026 program
Clients engaging PW Consulting gain access to: bespoke supplier stress-tests tailored to their bill-of-materials, hands-on pilot design templates for circularity, and a private briefing that deciphers which segments and geographies in the release paper ecosystem are most actionable in 2026. Our consulting engagements translate the report’s scenario outputs into board-ready strategies and operational roadmaps.
Next steps and where to get the full intelligence
This release is a strategic preview designed to surface the most consequential trends and practical imperatives for 2026. Detailed segment-level splits, regional and application tables, and the full competitor scorecards have been deliberately omitted from this public brief to preserve the value of the primary research and to encourage direct engagement. For complete datasets (including the full forecast model, supplier-level benchmarking, and execution playbooks), please visit the PW Consulting Release Paper Market Report landing page or contact our advisory team to schedule a confidential briefing.
PW Consulting’s Release Paper Market Report provides the evidence base and execution scaffolding that leaders need to convert the 2026 opportunity into durable advantage—whether through cost resilience, sustainability leadership, or targeted M&A. The market’s growth is clear; the differentiator will be how companies operationalize circularity, procurement sophistication, and supplier partnerships in the year ahead.
For detailed analysis of this topic, please visit the official page: Release Paper Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Image Signal Processor and Vision Processor Market to Expand at 9.16% CAGR, Reach USD 10,715.05 Million by 2032
By pmarketresearch, 2026-07-07
Image Signal Processor and Vision Processor Market: Strategic Imperatives for 2026 Decision-Makers
As demand for edge vision intelligence accelerates across automotive, industrial, security and consumer systems, PW Consulting’s new Image Signal Processor (ISP) and Vision Processor Market report (base year 2025, forecast 2026–2032) provides the strategic intelligence leaders need to navigate a rapidly evolving technology and regulatory landscape. With the market expanding at a compound annual growth rate (CAGR) of 9.16%, and total market value moving from approximately USD 3.85 billion in 2020 to roughly USD 5.8 billion in 2025 — and projected to exceed USD 10.7 billion by 2032 — executives must align product, supply-chain and corporate strategies to capture disproportionate share and minimize exposure to systemic risks.
Image Signal Processor And Vision Processor Market
Why this report matters for 2026 planning
-
Actionable forecasting calibrated for near-term volatility: Our forecast captures a distinct inflection through 2026–2028 where the market normalizes after pandemic-era supply disruptions, followed by an acceleration driven by multi‑sensor automotive systems and software-defined imaging innovations. The forecast explicitly models a modest short-term correction before renewed expansion, enabling finance and product leaders to plan CapEx, inventory and cadence of design wins with a more realistic runway.
Image Signal Processor And Vision Processor Market -
Strategic sensitivity to policy and supply risks: Recent U.S. trade and export policy changes — including ad valorem tariffs under Section 232 on certain advanced computing chips and tightened export controls — materially change sourcing calculus. The report translates those policy shifts into supply-risk scenarios and procurement playbooks for sourcing, qualification and nearshoring that are immediately actionable for 2026 decision cycles.
Image Signal Processor And Vision Processor Market -
Technology roadmap alignment for edge AI: The market is bifurcating around two engineering philosophies — higher-integration system-on-chip (SoC) solutions that embed ISPs and AI accelerators, versus modular approaches that combine best-in-class sensors, companion ISPs and dedicated vision processors. Our analysis maps where each approach wins on power, latency, safety certification and unit-cost at scale, guiding architecture choices for next-generation products.
What’s inside (practical, non-generic deliverables)
-
Executive dashboard and GTM prioritization matrix — shortlists high-opportunity segments and timing windows framed to 2026 product cycles without disclosing proprietary segment splits. These prioritize opportunities by addressable market growth, regulatory exposure and design‑in lead times.
-
Supplier risk-heatmap and mitigation playbook — identifies single-source and geo‑concentrated risks, recommended dual‑sourcing strategies, and a three-tier contingency plan for critical components and processed minerals exposed to new trade measures.
-
Procurement and NRE optimization guide — model clauses for wafer and module long‑lead contracts, recommended buffer strategies given current IC lead times (observed industry trends in early 2026 show certain families trending toward 30–42 week lead times), and scenarios for onshore vs. offshore sourcing to balance total landed cost and regulatory compliance.
-
Technical decision framework — comparative scorecards for integrated ISPs, dedicated vision processors, and sensor‑level intelligent solutions, including metrics for power-per-inference, multi-sensor synchronization, and software portability for customers designing into automotive and safety-critical markets.
-
M&A and partnership playbook — valuation sensitivity exercises, target archetypes (IP-rich startups, sensor+ISP integrators, software‑pipeline innovators), and integration risks to watch for in 2026 transactions.
-
Regulatory and standards readiness checklist — a pragmatic set of actions to maintain market access amid export control regimes and process‑specific tariffs affecting advanced computing chips and processed critical minerals.
Competitive landscape — who’s shaping the market and how
The market structure shows meaningful concentration (CR3 ≈ 42.5%; CR5 ≈ 61.8%), indicating that a small group of incumbent semiconductor and vision-system vendors retain substantial influence over technology direction and pricing. Our competitive analysis synthesizes product strategy, go‑to‑market motion, and ecosystem leverage across leading players, with implications for potential entrants and OEM partners.
-
Ambarella Inc. — continues to push high-performance edge SoCs with integrated ISPs and AI accelerators. Its January 2026 CV7 launch on an advanced process node underscores a strategy to capture high-end security, robotics and emerging automotive use-cases where multi-stream 8K processing and on‑device AI matter. For OEMs, Ambarella represents a route to rapid feature differentiation but with premium pricing and integration demands.
-
onsemi (ON Semiconductor) — positions dedicated ISPs as co-processors complementary to leading CMOS sensors and targets automotive and industrial machine vision. Their revenue profile, with substantial exposure to automotive and industrial verticals, signals a conservative, qualification-heavy GTM approach — valuable to customers prioritizing long lifecycle support and qualification rigor.
-
Qualcomm Technologies — leverages mobile SoC heritage to deliver integrated vision intelligence platforms suitable for security cameras, IoT and other edge scenarios where an existing developer ecosystem can accelerate deployment.
-
NXP Semiconductors — brings broad embedded processing platforms (e.g., i.MX families) with dual-ISP architectures and strong automotive-grade ecosystems, appealing to suppliers that need functional safety pathways and longtime partner support.
-
indie Semiconductor — has focused tightly on automotive vision processors that support multi-sensor low-latency processing and high throughput, matching the timing of advanced ADAS and cabin-monitoring deployments.
-
OmniVision, Sony, STMicroelectronics, Texas Instruments and Renesas — each plays distinct roles from sensor/companion ISP pairings and sensor-level intelligence to vision-enabled MCUs/MPUs for industrial and automotive platforms. Their strengths range from sensor/optics co-design to broad distribution and safety-qualified silicon.
-
Chips&Media (with Visionary.ai) — notable as an innovator in software-defined, AI-based ISP pipelines introduced for real-time video enhancement. Such capability points to a future where image quality and scene understanding are increasingly defined by software updates rather than hardware turnover.
Recent product and ecosystem shifts with strategic implications
-
Edge compute performance is moving aggressively: Ambarella’s CV7 and indie’s iND880xx families illustrate a trend toward higher integration and multi-sensor throughput. For OEM planners, this means evaluating whether to invest in single-chip simplification or retain modularity for upgrade flexibility.
-
Software-defined imaging is a differentiator: The industry’s first full AI-based ISP pipeline demonstrates how software and AI models can materially uplift perceived video quality and analytics performance post‑deployment, altering the economics of camera upgrades and licensing.
-
Policy shocks reshape supplier economics: The January 2026 U.S. actions on tariffs and processed critical minerals, combined with export licensing tightening, introduce transactional friction and potential cost uplift for certain high-performance vision processors. Companies that proactively diversify sourcing, qualify alternate silicon, or redesign to less-restricted components will reduce program execution risk.
Practical recommendations for 2026 strategic plans
-
Re-assess architecture trade-offs during Q1–Q2 product planning: Use our decision framework to choose between integrated SoC approaches and modular sensor+ISP flows based on product lifetime, safety requirements and total delivered cost over multiple production runs.
-
Harden supply‑chain playbooks now: Move from vendor selection to vendor qualification for multiple tiers of suppliers. Establish rolling six‑month forecasts, revise long-lead procurement terms, and build contingency contracts for silicon families most exposed to extended lead times.
-
Prioritize software/update monetization models: With software-defined imaging emerging, consider monetizable firmware upgrades and model-delivery subscriptions as part of product roadmaps, enabling revenue capture beyond the initial hardware sale.
-
Prepare M&A and partnership scouting lists: Identify targets that can fill IP gaps (e.g., ISP IP, AI pipelines) or accelerate deployment into regulated markets; our M&A playbook provides valuation sensitivities and integration checkpoints tuned to 2026 market dynamics.
-
Embed regulatory stress-testing in new program gates: For every program slated for 2026–2028 production, include export-control and tariff-scenario checks to avoid late-stage redesigns or certification delays.
Conclusion — how PW Consulting’s report becomes your tactical advantage
For executives preparing budgets, design cycles and strategic partnerships in 2026, the convergence of stronger edge compute, software-oriented imaging, and a shifting policy environment creates both opportunity and risk. PW Consulting’s Image Signal Processor and Vision Processor Market report gives you the integrated market forecast (CAGR 9.16%, detailed year-by-year modeling), supply‑chain and regulatory scenario planning, and a competitive technology playbook to prioritize investments and mitigate execution risk. The report is intentionally prescriptive and operational — designed to be used at the program level by product, procurement, corporate development and legal teams.
To access the full intelligence suite, including proprietary segmentation models, supplier heatmaps, and the complete competitive scorecards that power our recommendations, please consult the full report. Our lenses are calibrated to 2026 decision cadences — pragmatic, prioritized, and ready to influence budgets and roadmaps today.
For detailed analysis of this topic, please visit the official page: Image Signal Processor And Vision Processor Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Ocean Wave Energy Market Poised for Rapid Expansion — Forecasted 16.52% CAGR
By pmarketresearch, 2026-07-07
Ocean Wave Energy Technology Market — Strategic Preview for 2026 Decision-Makers
Executive summary
As governments and utilities accelerate decarbonization pathways, ocean wave energy is transitioning from niche pilots to commercially credible projects. PW Consulting’s new market study — grounded on a 2025 base year and projecting through 2032 — quantifies this transition and provides the operational playbooks that executives, project developers, investors, and policymakers need to make high‑confidence decisions in 2026.
Ocean Wave Energy Technology Market
At the macro level, the global ocean wave energy market has more than doubled in reported revenue since 2020 and is forecast to expand at a compound annual growth rate (CAGR) of approximately 16.5% across the 2026–2032 forecast window. This trajectory reflects a convergence of maturing device designs, targeted public funding, emerging commercial offtake mechanisms, and early evidence of sustainable operations cost profiles. Importantly, while the sector remains fragmented with a moderate degree of concentration among the leading technology providers, the pace of scale‑up in key markets creates clear windows for strategic entrants and incumbents alike.
Ocean Wave Energy Technology Market
Why the report matters for 2026 corporate strategy
- Timing: 2026 is a pivotal year for first commercial array deployments and test‑site commercialization. Decisions made this year on partner selection, site contracting, and supply‑chain commitments will materially influence 2027–2029 cost trajectories and equity returns.
- Capital allocation: The market profile in our study translates technology readiness and operational risk into investable scenarios. That enables CFOs and investment committees to compare probabilistic IRR outcomes across device classes, geographies, and business models.
- Policy leverage: New and scheduled public programs — including sizable competitive grants and infrastructure support — change the economics for early movers. Incorporating these into commercial negotiations and project timelines is now table stakes.
Market trajectory — the numbers that drive boardroom decisions
PW Consulting’s topline time series tracks the market from a modest commercial base in 2020 to accelerated commercial activity by 2025 (base year). The study documents a clear inflection: market revenue more than doubled during the 2020–2025 historical window and continues on an accelerated path into the forecast period. The report models this expansion under multiple scenarios, with a central case CAGR of ~16.52% for the forecast horizon. By tying market size, cost curves, and deployment schedules together, the analysis transforms headline growth rates into actionable timing for procurement, manufacturing scale‑up, and O&M planning.
Ocean Wave Energy Technology Market
What’s in the report — practical, decision‑grade content
- Investment framework: Deal‑ready financial models (sensitivity matrices, return profiles, and de‑risking mechanisms) tailored for equity, project finance, and blended finance structures.
- Technology and performance playbooks: Device‑agnostic acceptance criteria, site‑selection checklists, survivability testing protocols, and commissioning milestones mapped to commercial revenue triggers.
- Operational cost modeling: Benchmarks and drivers for CAPEX, OPEX, lifecycle replacement schedules, and logistics footprints; comparative scenarios for onshore/nearshore vs. offshore deployments.
- Supply chain mapping: Critical node analysis from composite hull manufacturing to PTO (power take‑off) systems and mooring/anchor supply, with supplier risk ratings and localization pathways.
- Policy & market readiness toolkit: Contract templates, PPA negotiation playbooks, regulatory roadmaps, and public funding capture strategies specific to marine energy corridors.
- Commercialization roadmaps: Step‑by‑step pathways to move from pilot to pilot‑plus to commercial array — including partner archetypes, staging timelines, and sample procurement schedules.
- Proprietary datasets and models: Interactive scenario tools that convert macro growth into project‑level demand, supply, and price forecasts — core subsegment data is excluded from this public summary to preserve the report’s subscription value.
Competitive landscape — who matters and why
The sector’s competitive map is characterized by a broad set of specialized device developers, several of whom have achieved meaningful operational milestones in the past 18–24 months. This creates a buyer’s market for offtake partners and a competitive pool for project developers seeking validated technologies.
- Eco Wave Power — With a practical onshore model that leverages existing marine infrastructure and recent U.S. pilot completion, Eco Wave demonstrates the near‑term commercial pathway for land‑connected approaches. Their automation and O&M metrics from recent projects point to tangible reductions in operational uncertainty.
- CorPower Ocean — CorPower’s compact point absorbers and demonstrated survivability at commercial test sites make it a candidate for high‑energy array deployments. Device efficiency and hull composite choices influence overall array productivity and lifecycle costs.
- Carnegie Clean Energy — CETO’s combined wave power and desalination capability represents a differentiated value proposition for co‑located utility and water‑security projects, particularly in water‑stressed coastal regions.
- Ocean Power Technologies , AW‑Energy , Mocean Energy — These established players span key device classes and have moved toward utility‑scale readiness, each offering alternative reliability and deployment profiles attractive to specific market niches.
- U.S. innovators (Oscilla Power, CalWave, ORPC) — Benefiting from domestic test sites and federal support, these companies are advancing drivetrain and multi‑degree‑of‑freedom capture technologies, which could shift cost curves if scaled rapidly.
- Seabased, NoviOcean, Marine Power Systems — Representing seabed, inverted hydropower, and hybrid platform approaches, these firms expand the technology mix available to project developers and system integrators.
Collectively, the top three companies account for a modest share of the market by revenue, and the top five capture under half of market revenues — a structure that favors strategic consolidation, selective partnership, and differentiated niche strategies.
Recent developments that change commercial calculus
- Deployment momentum: Multiple firms completed pilots and commercial‑scale tests in 2025–2026, including the first U.S. onshore project deployments and successful survivability trials in high‑energy environments.
- Offtake and revenue signaling: A landmark power purchase agreement for wave‑generated energy from a U.S. test facility (covering multi‑MW outcomes) establishes precedent for utility procurement terms and credit structures.
- Public funding & infrastructure: Major competitive programs are now resourcing device development and open‑water testing — including a dedicated multi‑year federal funding window that materially lowers early‑stage cost burdens for developers and sponsors.
- Operational cost evidence: Real project O&M results have begun to surface, with at least one onshore project reporting OPEX at a low single‑digit percentage of initial CAPEX in its inaugural full‑year operations, validating lifecycle cost assumptions used in many commercial models.
- Materials and manufacturing trends: Adoption of advanced composites (e.g., filament‑wound GFRP) and modular PTO designs is driving weight‑to‑cost improvements and improving manufacturability for serial production.
Policy and infrastructure outlook
Public programs and test infrastructure are now aligned to accelerate commercialization. The U.S. Department of Energy has launched a targeted funding opportunity over multiple years that allocates over one hundred million dollars to marine energy development, supporting device maturation, open‑water testing, and utility‑scale demonstrations. Complementary test sites are scheduled to host first prototype deployments in the near term, creating focal points for procurement, grid integration trials, and supply‑chain clustering.
Strategic recommendations — actions for 2026
- Prioritize early commercial PPAs and staged offtake: Secure staged offtake tied to commissioning milestones to share technology and grid‑integration risk with developers.
- Adopt a modular procurement strategy: Favor options that allow rapid substitution of PTO and mooring components as suppliers prove serial production metrics.
- Form hybrid consortia: Pair device developers with desalination, offshore energy, or port infrastructure partners to capture co‑value streams and improve IRR profiles.
- Lock in manufacturing partnerships now: Lead times for specialized composite hulls and PTO components will lengthen with scaling; early supplier agreements reduce schedule risk and improve pricing certainty.
- Use public funding as de‑risking capital: Blend grants and concessional capital into first arrays to improve bankability for private lenders.
- Invest in O&M intelligence: Remote monitoring, automation upgrades, and condition‑based maintenance can materially lower lifecycle costs — evidenced by operational pilots that have achieved sub‑4% OPEX-to‑CAPEX ratios in early operation.
Risk & concentration assessment
Market concentration metrics indicate that leadership is distributed among several specialized vendors rather than dominated by a single incumbent. This structure reduces single‑point technology risk for buyers but increases the importance of rigorous due diligence on supply chain capacity, failure modes, and retrieval/repair logistics. The report’s risk matrices convert technology, market, and regulatory risks into investable mitigation steps and reserving strategies.
Conclusion & how to use the full study
Our market study serves as a strategic playbook: it turns macro growth forecasts and public funding levers into operational plans and investment actions for 2026. Senior executives will find the report particularly valuable for timing capital calls, structuring PPAs, designing supply‑chain agreements, and prioritizing R&D pathways.
To preserve the report’s tactical value for subscribers, this public synopsis intentionally omits the granular subsegment breakdowns, regional and application‑level percentage allocations, and device‑level revenue schedules that underpin project‑specific financials. Organizations preparing procurement strategies, investment commitments, or regulatory engagement plans should access the full report for the proprietary datasets, interactive scenario models, and deal‑ready templates that convert sector growth into executable projects.
Contact PW Consulting to obtain the full Ocean Wave Energy Technology Market report and subscriber access to the interactive financial models and procurement playbooks designed specifically for 2026 commercial decision cycles.
For detailed analysis of this topic, please visit the official page: Ocean Wave Energy Technology Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com