

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Lithium Battery Ethylene Carbonate Market to Expand at 13.15% CAGR Through 2032 as Asia‑Pacific EV Demand Accelerates

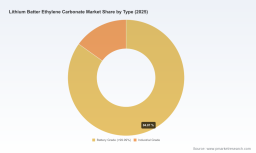
PW Consulting Strategic Brief: Lithium Battery Ethylene Carbonate Market — Actionable Intelligence for 2026 Decision-Making
PW Consulting today publishes an executive-level release accompanying our in-depth market study on ethylene carbonate (EC) used in lithium battery electrolytes. Designed as a strategic tool for leadership teams preparing budgets, supply-chain commitments, and technology roadmaps in 2026, this briefing highlights the macro trajectory, competitive posture, and the operational levers that matter — while reserving the proprietary, company- and segment-level tables for subscribers of the full report.
Lithium Batter Ethylene Carbonate Market
Top-line market context
-
Market scale and momentum: The lithium battery ethylene carbonate market has expanded rapidly over the past five years, rising from the low hundreds of millions in revenue in 2020 to USD 660.42 Million in our base year (2025). Our scenario-weighted forecast projects the market continuing to grow through the 2026–2032 horizon at a compound annual growth rate (CAGR) of 13.15%, reaching approximately USD 1.57 Billion by 2032.
Lithium Batter Ethylene Carbonate Market -
Historic acceleration: The market more than doubled over the 2020–2025 period, reflecting the acceleration of electrification in mobility, the scaling of stationary storage projects, and intensified demand for high-purity, battery-grade solvents.
Lithium Batter Ethylene Carbonate Market -
Concentration dynamics: Market share is meaningfully concentrated among leading global and regional producers; our concentration metrics indicate the top three firms control just under half of the market (CR3 ≈ 48.25%), and the top five account for roughly two-thirds (CR5 ≈ 64.12%). That structure creates both pricing power pockets and clear targets for competition and partnership.
Why this report is essential for 2026 strategic planning
-
Supply-demand alignment: Our demand model integrates battery build programs, electrolyte formulation trends, and a plant-level supply-side inventory to identify timing mismatches that can create short-term price spikes or margin compression. Executives can use these signals to prioritize feedstock hedges, capacity investments, or offtake agreements.
-
Cost exposure and sourcing: Ethylene oxide represents a dominant portion of raw material expense in EC manufacture (roughly 65–75%). Fluctuations in ethylene oxide availability and price translate almost directly into EC margin volatility — an operational reality our cost-pass-through templates quantify for 18-month and 36-month horizons.
-
Regional arbitrage and pricing regimes: Material price dispersion has widened in recent quarters — for example, Q4 2025 spot differentials in North America and China were pronounced — a structural feature that influences near-term trading, tolling economics, and the case for localizing capacity.
-
Regulatory and technology risk: Nearly half of manufacturers have shifted to lower-emission EC synthesis routes that leverage CO2-based feedstocks, reflecting regulatory pressure and ESG-aligned procurement. Simultaneously, academic and industrial R&D into EC-lean or EC-free electrolyte chemistries presents a medium-term demand risk that buyers and producers must monitor closely.
Key thematic takeaways (teaser insights)
-
EV battery buildouts remain the primary demand engine. While consumer electronics and utility-scale storage contribute, the pace and design of EV programs determine the shape of near-term demand surges.
-
Global production scale versus battery capture: Global EC production reached roughly 620 kilotons in 2024, and a significant share flows into lithium-ion battery electrolytes. How that production is allocated — between battery and industrial uses — is a leading indicator of market tightness or slack.
-
Price volatility is a strategic lever. The gap between regional price points creates incentives for trade, tolling, and investment that can be exploited by vertically integrated players or agile traders; it also increases the urgency for secure feedstock arrangements among battery makers.
-
Emission-conscious synthesis is becoming a competitive differentiator. Manufacturers adopting CO2-based routes are reducing regulatory exposure and gaining access to sustainability-linked customers, but these routes also require capital and operational redesign.
Competitive landscape — profiles and strategic postures
Our competitive analysis examines active global and regional suppliers, assessing technology readiness, capacity footprints, vertical integration, and strategic moves. Below we summarize the strategic posture of core players mapped in the market.
-
Mitsubishi Chemical Group Corporation (Japan) — A leading producer of high-purity EC focused on battery electrolytes. Recent investments include a new Southeast Asia production facility and strategic asset transfers of electrolyte manufacturing assets in North America and Europe to optimize a global manufacturing network. These moves indicate a deliberate strategy to secure regional supply while improving scale economics.
-
Huntsman International LLC (United States) — A North American leader that has expanded capacity tailored to EV-grade EC. Huntsman’s strengths are its product customization for high-purity applications and its integration with specialty chemical portfolios that can provide formulation advantages for electrolyte producers.
-
Oriental Union Chemical Corporation (OUCC) (Taiwan) — A focused manufacturer with strong proximity to East Asian battery supply chains; its positioning emphasizes reliability for OEMs sourcing in the region.
-
TOAGOSEI CO., LTD. (Japan) — A producer leveraging joint ventures to secure feedstocks and deliver battery-grade quality, benefiting from Japanese quality perceptions and overseas JV scale.
-
BASF SE (Germany) — A diversified global chemical player that supplies EC as part of broader electrolyte solutions; BASF’s strength lies in global reach and R&D capabilities to co-develop formulations with battery manufacturers.
-
Leading Chinese producers — Several vertically integrated Chinese firms (formerly organized under groups such as Shinghwa and others) combine raw material sourcing, EC manufacture, and proximity to battery cell builders, offering a cost-competitive pathway to scale. Our analysis highlights how their vertical integration changes trade flows and contract structures.
-
Specialty suppliers — Niche firms in Japan and Europe emphasize premium, battery-grade (>99.99%) specifications and tailor services such as quality assurance and small-lot supply for R&D and pilot programs.
Collectively, these players demonstrate differentiated strategies: scale and cost competitiveness, regional supply security, premium high-purity specialization, and vertical integration aimed at capture of downstream margin. Recent disclosed moves — such as Mitsubishi’s Southeast Asia plant and asset optimizations, and new capacity announcements from electrolyte players in China — validate our view that the next 18 months will be a window of strategic consolidation and greenfield responses.
What the PW Consulting report delivers (practical contents)
-
Scenario-driven demand model (2026–2032) with sensitivity levers for EV penetration, pack-level EC intensity, and alternative electrolyte adoption.
-
Supplier scorecard and plant-mapped capacity atlas (includes utilization, ramp timing, and feedstock exposure) to prioritize sourcing partners and contingency plans.
-
Raw-material cost pass-through models and recommended hedging templates to quantify margin risk under multiple ethylene oxide scenarios.
-
Regulatory and sustainability pathway mapping that links low-emission synthesis adoption to permitting timelines, capex needs, and buyer preferences.
-
Commercial playbooks for producers and battery manufacturers — including tolling structures, offtake clause language, and transition strategies for EC-lean electrolytes.
-
M&A and partnership shortlists based on strategic fit, with valuation frameworks and integration risk matrices.
Strategic recommendations for 2026 stakeholders
-
Producers: Prioritize flexible capacity (tolling and modular units) to exploit regional price spreads while investing selectively in low-emission routes to access premium customers and reduce regulatory risk.
-
Battery manufacturers/OEMs: Secure multi-year supply contracts with clause structures that balance price stability and access to battery-grade quality; evaluate co-investment in regional capacity where cell programs are large and concentrated.
-
Investors and private equity: Focus diligence on players with feedstock security, proximity to EV supply chains, and the capability to upgrade to lower-emission synthesis economically; look for consolidation targets in mid-size regional suppliers.
-
Policymakers and procurement leads: Use the transition window to incentivize CO2-based synthesis adoption and to support circularity initiatives that reduce raw-material volatility in the long term.
Methodology and data integrity
The PW Consulting study uses a mixed-methods approach. Base year calibration is 2025, with historical coverage from 2020 to 2025 and a forecast window of 2026–2032. Our forecast integrates primary interviews at plant and C-suite levels, trade and customs flows, input-cost modeling (including the ethylene oxide cost bucket), price-series analysis, and publicly disclosed capacity announcements. All monetary values are reported in USD and revenue units are expressed in millions unless otherwise noted. The full report includes model files and scenario toggles for client use.
Accessing full, granular intelligence
This article is a strategic preview highlighting the report’s value. To preserve the commercial integrity of our modeling and to deliver a high-actionable product for subscribers, we have omitted granular regional and application-level breakdowns and company-level volumes from this brief. Those detailed tables, supply maps, and the interactive forecast model are available exclusively in the full PW Consulting Lithium Battery Ethylene Carbonate Market Report. Visit PW Consulting’s research portal or contact our subscription desk to request the complete deliverable and a licensed model walkthrough.
In an environment where price spreads, feedstock exposure, regulatory shifts, and formulation innovation converge, PW Consulting’s market study provides the decision-grade intelligence leaders need to position portfolios, prioritize investments, and construct resilient supply contracts for 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Lithium Batter Ethylene Carbonate Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com